

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: TFLN Modulator Market Hits $261M in 2025, 35.53% CAGR to $2.2B by 2032

Strategic Intelligence for the Photonics Era: Inside the Worldwide Thin Film Lithium Niobate Modulator Market 2026-2032
The global optical communications landscape is undergoing a structural shift. As data center interconnects, telecommunication networks, and emerging quantum applications demand higher bandwidths, lower power consumption, and tighter integration, Thin Film Lithium Niobate (TFLN) modulators have emerged as a cornerstone technology. For enterprise leaders, investors, and technology strategists operating in 2026, understanding the trajectory of this market is no longer optional. It is a prerequisite for capital allocation, supply chain resilience, and product roadmap planning.
PW Consulting's latest Worldwide Thin Film Lithium Niobate Modulator Market study delivers a comprehensive, data-driven foundation for these decisions. Below, we outline the strategic contours of the market, the competitive forces shaping its evolution, and the operational intelligence embedded in the full report.
The Macro Trajectory: A Sector in Hypergrowth
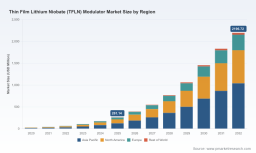
The TFLN modulator market has moved decisively beyond its early adoption phase. Historical data from 2020 through 2025 reveals an acceleration curve that underscores the technology's transition from specialized laboratory demonstrations to production-grade commercial deployment. Beginning at a modest baseline in the early 2020s, the market expanded rapidly as hyperscale data centers, coherent optical networks, and next-generation sensing platforms embraced TFLN's superior electro-optic efficiency, ultra-low half-wave voltage characteristics, and compatibility with scalable photonic integrated circuit architectures.
Looking forward, the forecast period from 2026 to 2032 projects a sustained, high-velocity expansion. The market is expected to grow at a compound annual growth rate of 35.53% over this horizon, reflecting the compounding effect of AI-driven interconnect demand, the rollout of next-generation telecommunication infrastructure, and the nascent but accelerating integration of TFLN devices into quantum and advanced sensing applications. By the close of the forecast window, the total market valuation is projected to reach a level that fundamentally reshapes the competitive landscape for photonic component suppliers and system integrators alike.
This growth trajectory is not merely a function of volume. It reflects a deeper structural realignment: TFLN is becoming the material platform of choice for high-speed, energy-efficient optical modulation across multiple end markets simultaneously. The strategic implication for 2026 decision-makers is clear. Companies that fail to map their product portfolios, supply partnerships, and technology roadmaps against this trajectory risk being left behind as the market compounds.
What the Report Delivers: Actionable Intelligence Beyond Top-Line Numbers
PW Consulting's study is designed for practitioners who require more than aggregate market projections. The report provides a granular, multi-dimensional analysis structured to support strategic planning across several critical dimensions:
Worldwide Thin Film Lithium Niobate (TFLN) Modulator Market
- End-to-end market sizing and forecasting: Detailed revenue projections across the forecast period, anchored in historical performance data from 2020 through the base year of 2025, enable precise demand modeling and investment scenario planning.
- Type-level segmentation analysis: The report dissects the market by modulator architecture, including intensity modulators, phase modulators, and IQ modulators. This breakdown clarifies where performance-differentiated products are capturing value, how application requirements are driving architecture preferences, and where R&D investment is most likely to yield competitive advantage.
- Application-driven demand mapping: Demand is analyzed across data center interconnects, telecommunication networks, aerospace and defense, and quantum and sensing verticals. Understanding the distinct performance thresholds, procurement cycles, and qualification requirements in each segment allows companies to prioritize product development and go-to-market strategies with precision.
- Regional dynamics and competitive positioning: The study maps geographic demand patterns and highlights where manufacturing capacity, design talent, and end-customer concentration are creating localized advantages or bottlenecks. This regional lens is essential for supply chain strategy, partnership evaluation, and market entry timing.
- Competitive landscape profiling: In-depth profiles of leading TFLN modulator developers, photonic foundries, and integrated device manufacturers are included, covering technology roadmaps, product families, foundry capabilities, and recent commercial milestones.
- Industry dynamics and constraint analysis: The report examines standardization progress, manufacturing equipment transitions, wafer supply bottlenecks, and the expanding ecosystem of foundry services, providing a realistic view of where growth may be constrained or accelerated in the near term.
This structure ensures that the report functions as a working document for strategy teams, not merely a reference for market awareness.
Competitive Landscape: Foundries, IDMs, and Technology Differentiation
The TFLN modulator market in 2026 is characterized by a dynamic mix of specialized startups, established photonic foundries, and integrated device manufacturers, many of whom are racing to scale production-grade platforms while locking in design-win pipelines. The competitive field reflects the technology's dual nature: it demands sophisticated materials processing, precision lithography, and packaging expertise, while simultaneously offering differentiation through bandwidth, half-wave voltage, integration density, and wavelength compatibility.
Several organizations have emerged as particularly influential in shaping the market's trajectory:
- HyperLight Corporation (Cambridge, Massachusetts, USA) has rapidly established itself as a leader in production-grade TFLN platforms. The company offers packaged electro-optic modulators spanning amplitude, phase, and IQ configurations, with bandwidth capabilities reaching 145 GHz and ultra-low Vπ specifications. Its TFLN Chiplet™ photonic integrated circuit platform targets IMDD architectures at up to 448 Gbps per lane, as well as DPIQ transmitters for AI and datacom, telecom, and quantum applications. The company supports MPW runs and custom development, and has moved aggressively into high-volume production partnerships.
- Lightium AG (Schlieren, Switzerland) operates a production-grade TFLN photonic foundry delivering 200 mm wafer manufacturing from MPW services through high-volume production. Its platform supports high-speed modulators exceeding 100 GHz with Vπ at or below 1V, and provides PDKs spanning C-band, O-band, and visible wavelengths. This foundry model enables customers to develop next-generation PICs for telecom, datacom, and integrated photonics without owning fab assets.
- Liobate Technologies (Nanjing, China) pursues an IDM approach focused on TFLN photonic devices and high-speed modulators for optical communications. Its portfolio includes TFLN-based chips and sub-assemblies built for mass production of electro-optic modulators and PICs targeting 1.6T and 3.2T applications, aligning closely with the escalating bandwidth requirements of next-generation data center and coherent optical infrastructure.
- Ori-Chip Optoelectronics Technology Co. Ltd. (Ningbo, China) develops and manufactures TFLN MZ modulators and PICs in-house on 4-inch wafers. Its products include folded intensity modulators with ultra-low Vπ below 3.3V and extinction ratios above 20 dB, alongside high-speed chips such as 1.6T DR8 MZ modulators and 4x100G DR4 PICs for high-speed optical communication.
- Quantum Computing Inc. (QCi) (Tempe, Arizona, USA) operates a dedicated TFLN foundry with 150 mm wafer processing for photonic ICs. It fabricates electro-optic modulators and phase modulators with low Vπ-length products tailored to high-baud-rate applications, and provides front-end and back-end capabilities, packaging, and PDK development.
- CCRAFT (CSEM spin-off, Switzerland) has launched what it describes as the world's first production-ready TFLN photonic chip foundry, offering MPW runs, a full PDK, and high-volume manufacturing for electro-optic modulators across telecom, datacom, AI, and quantum applications.
- Additional commercial suppliers including Agiltron Inc., Rofea Optoelectronics, Advanced Fiber Resources, and Neon CQ contribute a broad set of product options across bandwidth classes, modulation types, and application segments, from 20G to 60 GHz intensity and phase modulators, to IQ modulator solutions for OFDM and high-speed systems.
The market concentration among the top players is notable, with the top three firms accounting for approximately 68.5% of market share and the top five reaching 85.2%. This concentration underscores the technology's capital intensity and the advantage that early movers with scalable manufacturing platforms, established PDK ecosystems, and design-win momentum hold. However, it also signals opportunity for well-positioned entrants that can address specific performance niches, wavelength bands, or regional supply chain needs.
Recent Developments Shaping the 2026 Landscape
Recent commercial and ecosystem developments provide a concrete window into how the competitive and manufacturing landscape is evolving in real time:
- In March 2026, HyperLight Corporation introduced 400G-per-lane TFLN PICs on its Chiplet™ platform for AI interconnects, alongside 145 GHz packaged intensity modulators enabling 448 Gbps per lane IMDD and 260 GBaud coherent links. The same month, the company announced a strategic manufacturing partnership with UMC and Wavetek for high-volume production of the TFLN Chiplet platform on 6-inch and 8-inch wafers targeting AI and cloud infrastructure.
- In October 2025, Lightium AG participated in the European-Canadian INGENIOUS consortium, which secured €7.6M to integrate lasers and detectors into next-generation TFLN PICs, signaling the industry's push toward more fully integrated photonic solutions.
- In September 2025, Liobate Technologies showcased its latest TFLN chips and devices, including high-speed modulators, at ECOC 2025, reinforcing its focus on mass-producible solutions for high-throughput optical communications.
- In July 2025, CCRAFt launched a production-ready TFLN photonic chip foundry with MPW runs and a full PDK for scalable electro-optic modulators, expanding the foundry ecosystem and lowering barriers for customers seeking to prototype and scale TFLN-based designs.
These milestones illustrate the convergence of multiple forces: performance breakthroughs, manufacturing partnerships, consortium funding, and the expansion of foundry services. Together, they are compressing the timeline from laboratory demonstration to volume deployment.
Industry Dynamics: Standardization, Manufacturing Shifts, and Supply Constraints
Beyond company-level activity, several macro-level dynamics are influencing how the TFLN modulator market will evolve through the forecast period:
- Standardization toward foundry-compatible platforms: Industry efforts are progressing toward standardized TFLN photonic integrated circuits, including waveguides, modulators, and edge couplers, to support foundry platform compatibility and volume manufacturing. Standardization reduces design risk for customers and strengthens the business case for foundry-based production models, but it also raises the stakes for foundries that must deliver consistent, repeatable performance across multiple customers and designs.
- Manufacturing bottleneck dynamics: Limited commercial manufacturing capacity for high-quality TFLN wafers and specialized cleanroom processes has created supply chain constraints. As of early 2026, only a handful of foundries operate at meaningful scale, which means that even as end-market demand accelerates, the availability of production-grade wafers and processing capacity can become a binding constraint on growth. Companies that secure tightly coupled supply partnerships or invest in captive manufacturing capabilities gain a strategic buffer.
- Lithography transitions enabling yield and performance gains: A shift toward deep-ultraviolet (DUV) stepper lithography on 4-inch TFLN wafers with quartz handles is enabling high-yield volume manufacturing of modulators exceeding 110 GHz with propagation loss below 0.4 dB/cm. This transition is replacing lower-throughput electron-beam lithography for many production applications, reducing per-unit cost and improving consistency. The adoption curve of DUV-based processes will influence which foundries and product lines can scale most efficiently.
- Foundry services ecosystem maturation: Panels and industry discussions at venues such as ECOC 2025 have focused on turnaround times, yield, PDK completeness, and roadmaps to volume production for TFLN foundry services. As these services mature, they lower the barrier to entry for system designers and accelerate the pace of design wins, but they also intensify competition among foundries on quality, support, and scaling capacity.
- Geopolitical and regional capacity developments: In June 2025, China established its first pilot production line for 6-inch TFLN photonic chips at Shanghai Jiao Tong University's CHIPX, supporting domestic ambitions in AI, 6G, and quantum computing. Regional capacity investments of this nature signal a long-term push toward supply chain localization and may reshape competitive dynamics over the forecast period.
For strategists, these dynamics create a dual narrative: the market's growth potential is exceptionally strong, but realizing that potential depends on navigating manufacturing scale-up, supply constraints, standardization timing, and regional capacity investments. The companies that succeed will be those that treat these dynamics not as external noise, but as core inputs to capacity planning, partnership strategy, and technology roadmapping.
Why This Report Matters for 2026 Decision-Making
In a market growing at this pace and shaped by this level of technological and manufacturing complexity, decisions made in 2026 will compound over the entire forecast period. Whether the objective is to evaluate a vendor's scalability, assess a region's supply chain resilience, determine where to prioritize R&D investment, or model demand scenarios for a specific application segment, decision-makers need granular, forward-looking intelligence that goes beyond headline numbers.
PW Consulting's Worldwide Thin Film Lithium Niobate Modulator Market report provides that foundation. It combines rigorous historical analysis with forecast modeling, dissects the market by type, application, and region, maps the competitive landscape molecule by molecule, and embeds the industry dynamics that will determine which players scale and which stall. The report is structured to support board-level strategy discussions, product portfolio reviews, procurement planning, and investment committee evaluations.
Worldwide Phase Electro-optic Modulator Market
The macro trajectory is compelling. The competitive field is actively differentiating. The manufacturing and standardization landscape is evolving quickly. For organizations operating in or adjacent to the TFLN modulator ecosystem, the window for informed strategic positioning is open now.
To access the complete segmentation data, full forecast tables, detailed competitor profiles, and region-specific demand analysis, please visit PW Consulting's official report page. The full study provides the depth required to translate market momentum into actionable strategy.
For detailed analysis of this topic, please visit the official page: Worldwide Thin Film Lithium Niobate (TFLN) Modulator Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com