

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global Optical Networking IC Market to Hit $15.7B by 2032, Growing at 13.5% CAGR

Navigating the Next Wave: Strategic Imperatives in the Global Optical Networking IC Market
The global communications infrastructure is undergoing a structural transformation driven by the convergence of artificial intelligence workloads, cloud hyperscale expansion, and next-generation telecom architectures. At the core of this shift lies the optical networking integrated circuit market, a critical enabler of high-bandwidth, low-latency, and energy-efficient data transmission. PW Consulting's latest Worldwide Optical Networking IC Market research provides decision-makers with a comprehensive, forward-looking intelligence framework designed to navigate the complexities of a rapidly scaling industry. As enterprises, semiconductor firms, and system integrators chart their paths through 2026 and beyond, understanding the macroeconomic trajectory, technological inflection points, and competitive dynamics of this sector is no longer optional—it is a strategic imperative.
The Macro Trajectory: A Market Accelerating Under Convergent Demand
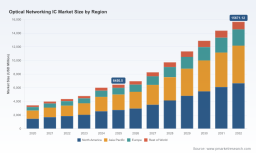
The optical networking IC sector has evolved from a specialized telecommunications component space into a foundational pillar of global digital infrastructure. Historical data reveals a pronounced acceleration in revenue generation, with the market expanding from approximately $3.42 billion in 2020 to $6.45 billion by 2025. This growth trajectory reflects not merely cyclical demand but a fundamental re-architecture of how data moves across networks. The transition to 800G and 1.6T optical modules, the proliferation of co-packaged optics, and the deployment of silicon photonics platforms are fundamentally reshaping component requirements and supply chain priorities.
Looking ahead, the forecast period spanning 2026 through 2032 projects continued robust expansion, supported by a compound annual growth rate of 13.52 percent. The market is expected to surpass the $15.6 billion threshold by the close of the forecast window, underscoring the sustained capital allocation toward optical interconnect technologies. This growth is not uniformly distributed across applications or product categories; rather, it is heavily weighted toward high-performance computing environments, cloud infrastructure buildouts, and advanced coherent transmission systems. Decision-makers must recognize that this trajectory is deeply intertwined with broader infrastructure economics, including the capital intensity of fiber deployment, the energy constraints of large-scale data centers, and the policy-driven expansion of broadband backbones. These intersecting forces create both tailwinds and constraints that will define procurement strategies, manufacturing investments, and product roadmaps throughout the decade.
2026 Decision-Making: Why This Research Matters Now
Entering 2026, the optical networking IC landscape presents a uniquely complex decision environment. Technology nodes are advancing at a pace that outstrips traditional procurement cycles, while energy efficiency mandates and thermal constraints are forcing architects to reconsider pluggable versus co-packaged approaches. Simultaneously, supply chain resilience, geopolitical considerations, and the consolidation of foundry and packaging capabilities are reshaping competitive positioning. In this context, strategic planning cannot rely on historical benchmarks or fragmented vendor narratives. It requires a unified, data-grounded view of market sizing, segmentation behavior, technology adoption curves, and competitive maneuvering.
This research is engineered to serve as a decision-support instrument for executives, product planners, investors, and procurement leaders. Rather than offering static snapshots, it maps the causal links between architectural shifts, component demand, and revenue flows. It clarifies where growth is structurally anchored, which product categories are emerging as critical bottlenecks or enablers, and how regional deployment patterns influence supply chain strategy. By synthesizing historical performance with forward-looking modeling, the report equips organizations to align capital allocation, partnership strategies, and technology roadmaps with the realities of a market that is scaling faster than legacy planning cycles can accommodate.
Inside the Report: What Decision-Makers Will Gain
The research is structured to deliver actionable intelligence across multiple dimensions of the optical networking IC ecosystem. The analytical framework integrates quantitative market modeling with qualitative technology and competitive assessment, ensuring that readers can translate high-level trends into operational strategy. Key components of the study include:
Comprehensive Market Modeling and Forecast Architecture
The report establishes a rigorous baseline using historical data from 2020 through 2025, then extends the analytical scope across the 2026–2032 forecast horizon. Revenue projections are modeled at the aggregate market level, with segmentation frameworks that dissect demand by product type, application vertical, and geographic region. This layered approach allows readers to understand not only where the market is heading, but how different technology categories and end-use environments contribute to overall growth dynamics. The modeling accounts for architectural transitions, module form-factor evolution, and the shifting economics of high-speed interconnect deployment.
Worldwide Optical Networking IC Market
Product Category and Application Deep Dives
Optical networking ICs encompass a diverse set of functional blocks, each with distinct performance requirements, manufacturing considerations, and demand drivers. The report examines the market position and growth trajectory of core product categories, including digital signal processors, laser drivers, transimpedance amplifiers, and clock and data recovery circuits. Each category is evaluated within the context of system-level architecture, highlighting how advancements in signaling rates, power efficiency, and integration complexity influence adoption patterns. Application-level analysis further maps demand to data center environments, telecommunication networks, and enterprise infrastructure, clarifying how workload characteristics and deployment scales shape procurement behavior.
Competitive Positioning and Strategic Movement Analysis
The report delivers a structured assessment of the companies shaping the optical networking IC landscape. Profiles capture corporate positioning, technology portfolios, recent strategic actions, and the implications of those moves for market structure. The analysis tracks product launches, technology acquisitions, interoperability initiatives, and architectural demonstrations that signal shifting competitive priorities. By mapping these activities against broader market trends, the research helps readers identify which players are extending leadership in high-performance DSP and coherent platforms, which are expanding silicon photonics and co-packaged optics capabilities, and how industry consortia and standards bodies are influencing multi-vendor compatibility.
Infrastructure, Energy, and Policy Contextualization
Optical networking IC demand does not exist in isolation. The report embeds component-level analysis within the broader context of infrastructure economics, energy consumption patterns, and policy-driven deployment programs. This contextual layer clarifies how capital intensity in fiber deployment, electricity constraints in large-scale computing facilities, and public investment in broadband expansion influence the pace and geography of optical interconnect adoption. Understanding these external drivers is essential for forecasting demand resilience, evaluating regional opportunity sets, and anticipating regulatory or sustainability-related shifts in procurement criteria.
Competitive Dynamics and the Shape of Market Leadership
The optical networking IC market is characterized by a concentrated yet highly active competitive environment. Incumbent semiconductor and optoelectronic firms are racing to advance process nodes, integrate coherent and PAM4 DSP capabilities, and scale silicon photonics platforms to meet the demands of AI-scale data centers and high-capacity telecom networks. System vendors and vertically integrated players are simultaneously strengthening their control over optical engines, transceiver architectures, and packaging technologies. This dynamic has produced a landscape where leadership is increasingly defined by the ability to deliver low-power, high-density, and interoperable solutions across multiple module form factors and networking architectures.
Recent industry activity illustrates the intensity of this competition. Broadcom has advanced its optical DSP roadmap with the introduction of its 3nm 400G-per-lane PAM-4 DSP, targeting low-power 1.6T pluggable modules for AI-driven networks. Marvell has expanded its technology footprint through the acquisition of plasmonics-based silicon photonics capabilities, positioning itself to scale modulation performance toward 3.2T and beyond. Semtech has demonstrated next-generation 224G-per-lane transimpedance amplifiers and modulator drivers supporting multiple optical architectures for AI data center interconnects. Meanwhile, industry-wide interoperability efforts led by standards organizations have showcased multi-vendor alignment across 800ZR, 400ZR, and emerging 224G/448G electrical and optical interfaces, signaling a concerted push toward energy-efficient, compatible AI cluster networking. These developments, among others, reflect a market where product cadence, technology integration, and ecosystem alignment are becoming decisive competitive differentiators.
The report's competitive analysis goes beyond company profiles to examine how these moves reshape market concentration, influence supply chain dependencies, and alter the balance between integrated solutions and disaggregated component procurement. By mapping strategic actions against market structure, the research helps readers anticipate where consolidation may accelerate, which technology stacks are likely to dominate specific application segments, and how new entrants or acquisitions could shift bargaining dynamics among suppliers and system integrators.
Strategic Takeaways for 2026 and Beyond
As organizations enter 2026, several strategic imperatives emerge from the market's structural evolution. First, technology roadmapping must account for the rapid migration toward higher-per-lane data rates and the parallel push for power reduction through architectural innovation. Decision-makers should evaluate how pluggable, linear pluggable, and co-packaged optics approaches align with their performance, thermal, and cost constraints. Second, supply chain strategy requires a clear view of where advanced DSP, silicon photonics, and high-speed analog integration are concentrating, as well as how packaging and testing capabilities influence time-to-market. Third, investment and partnership decisions should be informed by a nuanced understanding of application-led demand, recognizing that data center buildouts, telecom network upgrades, and enterprise infrastructure modernization are progressing at different speeds and under different economic conditions.
Optical Transceivers Market
The research also underscores the importance of monitoring interoperability and standards alignment. As multi-vendor demonstrations and consortium-driven initiatives gain momentum, compatibility across electrical and optical interfaces will increasingly influence procurement flexibility and deployment risk. Organizations that integrate standards awareness into their technology selection and vendor evaluation processes will be better positioned to manage transition costs and avoid premature lock-in to architectures that may face ecosystem headwinds.
Finally, the market's growth trajectory is intertwined with broader infrastructure and energy realities. Capital intensity in fiber deployment, electricity consumption trends in large-scale computing, and public investment in broadband expansion all shape the demand environment for optical networking ICs. Strategic planners should treat these factors not as peripheral context but as integral inputs to forecasting, capacity planning, and regional opportunity assessment.
Conclusion: Turning Market Intelligence into Strategic Advantage
The Worldwide Optical Networking IC Market is entering a phase of sustained, technology-driven expansion. The convergence of AI workload demands, high-capacity interconnect requirements, and architectural innovation is creating a market environment where insight quality directly correlates with strategic agility. PW Consulting's research is designed to provide the depth, structure, and forward-looking clarity needed to navigate that environment with confidence. By integrating market sizing, segmentation behavior, competitive movement, and infrastructure context into a single analytical framework, the report enables leaders to make informed decisions about product direction, partnership strategy, procurement posture, and investment prioritization.
For organizations seeking to understand where value is being created, which technologies are gaining structural advantage, and how competitive dynamics are evolving across the optical networking IC landscape, this research offers a comprehensive foundation for 2026 planning and beyond. The full analysis, including detailed segmentation breakdowns, regional demand patterns, product-type growth trajectories, application-level revenue distributions, and extended competitive profiling, is available through the complete report. Access the full study to equip your team with the intelligence required to act decisively in a market that is scaling rapidly and redefining the boundaries of high-performance optical networking.
For detailed analysis of this topic, please visit the official page: Worldwide Optical Networking IC Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com