

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecasts Global Furniture Installation & Relocation Market to Hit $2.4B by 2032

Strategic Intelligence for the Worldwide Furniture Installation and Relocation Service Market (2026–2032)
The global furniture installation and relocation service market stands at a critical inflection point as organizations navigate post-pandemic operational realignments, hybrid work mandates, and escalating logistics complexity. PW Consulting’s latest Worldwide Furniture Installation and Relocation Service Market research delivers a comprehensive, data-grounded assessment of this evolving landscape, providing executives, investors, and service operators with the analytical clarity required to make disciplined strategic decisions throughout the forecast horizon. Drawing on rigorous modeling, primary industry validation, and cross-sector demand mapping, this publication is engineered not as a static snapshot but as a forward-looking decision-support instrument for 2026 planning cycles and beyond.
Market Trajectory and Foundational Intelligence
Historical performance across the 2020–2025 observation window demonstrates consistent revenue expansion, culminating in a baseline valuation of 1,650 million USD in the base year of 2025. Macroeconomic stabilization, sustained commercial real estate repositioning, and the continued normalization of corporate relocation programs have collectively reinforced demand resilience. Forward-looking projections spanning 2026 through 2032 indicate a sustained expansion trajectory, anchored by a compound annual growth rate of 5.45 percent. By the terminal forecast year, the market is positioned to cross the 2,400 million USD threshold, reflecting both organic volume growth and structural shifts in how organizations procure, manage, and redeploy physical assets.
These headline figures, while instructive at a macro level, represent only the outermost layer of a deeply segmented operating environment. Growth vectors vary materially across service typologies, end-user verticals, and geographic footprints, each carrying distinct margin profiles, capacity constraints, and competitive intensity. A disciplined approach requires unpacking the underlying demand architecture rather than relying on aggregated revenue totals. PW Consulting’s methodology isolates these dimensions through granular segmentation modeling, scenario testing, and sensitivity analysis, enabling leadership teams to calibrate capacity planning, pricing strategies, and geographic prioritization with precision.
The service ecosystem itself is undergoing measurable recalibration. Installation-driven engagements continue to anchor a substantial share of total contract value, driven by corporate fit-out cycles, retail refresh programs, and healthcare facility expansions. Relocation services maintain strong momentum as organizations execute footprint optimization and employees navigate hybrid living arrangements. Concurrently, asset management and decommissioning workflows are gaining strategic relevance as enterprises prioritize sustainable asset recovery, lifecycle tracking, and compliance-driven disposal protocols. Each segment operates under different operational economics, labor intensity profiles, and client procurement behaviors, necessitating differentiated go-to-market postures.
Structural Shifts Defining the Competitive Landscape
The market remains moderately fragmented, with no single entity exerting decisive pricing or capacity control. Aggregate concentration metrics indicate that the top three operators collectively account for approximately 18.5 percent of total revenue, while the top five expand that share to roughly 24.2 percent. This dispersion signals ample room for targeted scaling, regional consolidation, and service differentiation, but it also underscores the importance of defensible operational advantages. Companies that thrive in this environment typically combine reliable execution quality, transparent pricing frameworks, scalable dispatch infrastructure, and strong client retention mechanics.
A defining feature of the current landscape is the prominent role of platform-enabled and tech-forward service models. TaskRabbit, headquartered in San Francisco, operates a distributed marketplace architecture that connects end users with localized Taskers for furniture assembly, installation, and relocation across select international markets. Handy, based in New York, delivers an on-demand service platform emphasizing professional installation, assembly, and moving capabilities across major metropolitan corridors in the United States, the United Kingdom, and Canada. Thumbtack, also anchored in San Francisco, functions as a curated marketplace for local professionals specializing in furniture installation, disassembly, and relocation, with a strong domestic footprint. Angi, originally recognized as Angie’s List and now operating from Denver, maintains an online directory and booking infrastructure that routes clients to vetted contractors for installation and relocation work throughout the United States.
Beyond the platform layer, traditional and hybrid operators continue to shape market dynamics through scale, brand recognition, and operational specialization. CORT Furniture Rental & Delivery, headquartered in Chantilly, integrates delivery, installation, and relocation into a broader rental ecosystem, serving corporate and transitional housing demand across the United States and select international locations. Two Men and a Truck, based in Atlanta, operates a nationally distributed moving franchise model with more than 400 locations and international extensions, offering dedicated furniture relocation, disassembly, and reassembly capabilities. Bellhop, operating from Nashville, leverages a tech-enabled moving framework to deliver installation and relocation services across more than thirty-five U.S. cities. Collectively, these organizations illustrate the spectrum of business models competing for share—from marketplace aggregation to branded franchise networks to rental-integrated service bundles.
Operational Economics, Regulation, and Labor Dynamics
Strategic planning in this sector requires direct engagement with structural cost and compliance realities. Labor economics remain a central driver of unit economics. Hourly wages for furniture installers and movers averaged 18.50 USD in the United States as of 2024, according to federal labor statistics, establishing a baseline cost structure that directly influences margin thresholds, pricing elasticity, and service-tier design. At the same time, employment projections for furniture movers anticipate growth of approximately 5 percent between 2023 and 2033, a pace that trails broader occupational averages due to automation exposure and efficiency gains in scheduling, routing, and inventory handling. These dual pressures—rising wage floors and measured employment growth— compel operators to pursue labor productivity improvements, standardized process design, and selective technology adoption rather than relying solely on headcount expansion.
Regulatory and safety frameworks further condition operational execution. OSHA standard 1910.176 mandates safe handling and storage of materials, including furniture, to prevent workplace injuries during installation and relocation activities. Compliance with this standard influences training requirements, equipment provisioning, site assessment protocols, and liability management. In parallel, jurisdictional labor classification rules continue to shape platform economics. California’s AB5 framework classifies many gig workers as employees, altering contractor engagement models for marketplace-based service providers and influencing cost structures, scheduling flexibility, and scalability across affected regions. These regulatory dynamics are not static footnotes; they are active variables that inform market entry timing, operating model design, and risk allocation strategies.
Taken together, labor cost trends and regulatory requirements create a narrow window between service affordability and operational profitability. Operators that institutionalize safety-forward workflows, invest in modular training pipelines, and align workforce models with local compliance regimes are better positioned to sustain margins while preserving service quality. For corporate buyers, these same factors elevate the importance of vendor due diligence, ensuring that installation and relocation partners can demonstrate consistent adherence to safety expectations and labor standards across multiple sites and jurisdictions.
Demand Architecture Across End-User Verticals
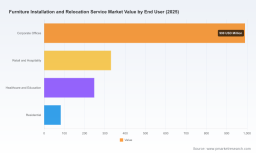
The market’s expansion is not uniform; it is anchored by distinct demand profiles that differ in contract size, procurement cycles, service complexity, and retention behavior. Corporate offices represent a dominant share of total demand, reflecting ongoing workspace reconfiguration, hybrid seating models, and periodic relocation of regional hubs. These engagements tend to prioritize scheduling reliability, minimal operational disruption, and coordinated multi-site execution, making vendor capability and account management critical differentiators.
Retail and hospitality demand forms another substantial pillar, driven by seasonal remodels, flagship refreshes, franchise rollouts, and experiential space redesigns. Service requirements in these verticals frequently emphasize speed, aesthetic precision, and clear post-installation handoff procedures. Healthcare and education segments contribute steady, project-based volume characterized by strict compliance expectations, specialized handling requirements, and coordination with facilities management teams. Residential demand, while smaller in aggregate contract value relative to commercial segments, remains a consistent source of recurring activity, often mediated through platform marketplaces, localized service networks, and hybrid rental-and-relocation offerings.
Each vertical carries its own procurement rhythm and performance expectations. Corporate buyers typically evaluate vendors on execution consistency, safety records, and scalable deployment capacity. Retail and hospitality operators weigh speed, site sensitivity, and brand-aligned presentation. Institutional buyers in healthcare and education prioritize regulatory alignment, documented handling procedures, and coordinated logistics. Residential customers, particularly in platform-mediated transactions, emphasize convenience, transparent pricing, and localized availability. Understanding these divergent requirements is essential for service providers seeking to align sales messaging, operational design, and pricing architecture with the segments most compatible with their capabilities.
What the Full Research Delivers
PW Consulting’s Worldwide Furniture Installation and Relocation Service Market report is structured to translate high-level market intelligence into executable planning inputs. The full publication extends well beyond top-line sizing and trend commentary, offering a layered analytical framework designed for use for corporate strategy, venture and private equity evaluation, capacity planning, and competitive positioning exercises.
Worldwide Furniture Installation and Relocation Service Market
Core components of the research include a detailed segmentation architecture that maps service types, end-user verticals, and regional demand structures without reducing them to isolated percentages, preserving instead the relational context needed for strategic interpretation. The forecast model spans 2026 through 2032 and is supported by scenario analysis that accounts for shifts in commercial real estate utilization, relocation program frequency, labor availability, and regulatory evolution. Competitive profiling examines operating models, geographic reach, service scope, and positioning tactics across leading platform, brokerage, franchise, and rental-integrated participants, providing a reference map for benchmarking and differentiation planning.
The report also integrates operational and regulatory context into the market narrative, ensuring that executives can assess how wage structures, safety mandates, labor classification rules, and automation exposure influence margin potential and scalability. Demand-side analysis connects vertical-specific procurement behaviors to service design implications, clarifying where execution reliability, speed, compliance documentation, or localized availability creates the strongest competitive advantage. Additionally, the research surfaces practical guidance on pricing frameworks, capacity allocation, vendor selection criteria, and risk mitigation practices that can be applied directly to 2026 planning cycles.
For organizations evaluating market entry, geographic expansion, or portfolio adjustment, the publication provides a disciplined basis for comparing opportunity attractiveness across segments and locations. For existing operators, it supports refinement of service mixes, investment prioritization, and competitive response planning. For investors and advisory professionals, it delivers a structured synthesis of market size, growth trajectory, concentration dynamics, and structural risk factors that can inform diligence and valuation discussions.
Strategic Implications for 2026 Decision-Making
As organizations move into 2026 planning, several strategic priorities emerge from the market’s underlying structure. First, service differentiation will increasingly depend on execution quality and process reliability rather than price alone. As demand diversifies across corporate, retail, hospitality, healthcare, education, and residential channels, vendors that can tailor operating procedures, training, and dispatch logic to specific vertical expectations will capture stronger retention and pricing leverage.
Second, labor strategy will remain decisive. With wage floors established and employment growth projected to expand at a measured pace, operators must pursue productivity through standardized workflows, scheduling optimization, and targeted technology integration. Companies that treat labor not as a variable cost to be minimized but as a capability to be engineered will be better equipped to protect margins while meeting service-level expectations.
Third, regulatory and compliance awareness will shape both market access and operating model design. Safety standards, handling requirements, and labor classification frameworks influence training costs, contractor engagement models, and geographic feasibility. Forward-looking strategies should incorporate compliance mapping as a core planning input rather than a reactive operational concern.
Fourth, competitive positioning will increasingly reward clarity of scope and operational fit. The coexistence of platform marketplaces, branded franchise networks, rental-integrated providers, and specialized local operators creates a complex environment in which broad promises are less effective than well-scoped value propositions. Organizations that define where they compete, how they win, and which segments they intentionally serve will be better positioned to allocate capital and attention efficiently.
Final Perspective
The Worldwide Furniture Installation and Relocation Service Market is expanding along a measurable, structurally supported trajectory, but its real strategic value lies beneath the headline figures. Growth is unevenly distributed across service types, end-user segments, and geographies; competitive intensity is shaped by business model diversity; and operating economics are conditioned by labor costs, safety mandates, and regulatory frameworks. PW Consulting’s full market research consolidates these dimensions into a coherent intelligence asset, enabling decision-makers to move beyond surface-level sizing and engage the operational, competitive, and demand-side realities that will shape performance through 2032.
RTA (Ready-to-assemble) Furniture Market
For executives, investors, and service operators preparing for 2026, the complete report offers the segmentation depth, forecast discipline, competitive context, and operational insight required to translate market movement into actionable strategy. The full analysis, including detailed segmentation mapping, scenario frameworks, and competitive profiling, is available through the source publication and serves as a foundational reference for planning, investment evaluation, and market positioning across the forecast period.
For detailed analysis of this topic, please visit the official page: Worldwide Furniture Installation and Relocation Service Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com