

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecasts 4.78% CAGR for Global Coconut Oil Methyl Esters Market to Reach $1.3 Billion by 2032

Global Coconut Oil Methyl Esters Market: Navigating Strategic Growth Through 2032
The worldwide Coconut Oil Methyl Esters Market is undergoing a period of measured expansion driven by shifting regulatory frameworks, evolving end-use demands, and the ongoing transition toward bio-based chemical intermediates. As industries seek to decouple from petrochemical derivatives while maintaining performance standards, methyl esters derived from coconut oil have emerged as a versatile feedstock spanning personal care, industrial cleaning, lubricants, and agro applications. Our latest market intelligence study maps the trajectory from 2020 through the forecast horizon of 2032, delivering a data-backed foundation for capital allocation, supply chain optimization, and competitive positioning.
Palm Methyl Ester Derivatives Market
Strategic decision-makers operating in 2026 face a landscape defined by modest but consistent growth, concentrated supplier dynamics, and heightened sensitivity to raw material pricing. This research briefing outlines the architecture of our analysis and explains how the full report equips corporate teams with the granularity required to navigate volatility, anticipate regulatory shifts, and identify actionable growth corridors within the oleochemical value chain.
Macro Trajectory: From Baseline Recovery to Sustained Expansion
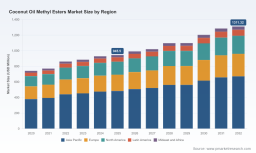
The market has demonstrated steady revenue progression over the historical window. Starting from an estimated 742.15 million USD in 2020, the sector advanced through successive annual increments, reflecting both post-pandemic demand normalization and structural adoption of coconut-derived methyl esters across multiple verticals. By 2023, industry revenue reached approximately 885.02 million USD, and the upward cadence continued into 2024 with 929.19 million USD and 2025 with 945.5 million USD.
The forecast period from 2026 through 2032 indicates a compound annual growth rate of 4.78 percent, translating the sector toward a projected revenue level above 1.3 billion USD by the terminal year. This trajectory is not a simple linear extrapolation; it reflects compounding effects from regulatory mandates in select regions, gradual substitution of conventional solvents and surfactants, and sustained investment in downstream formulation capabilities. The base year of 2025 anchors the model, enabling stakeholders to benchmark current operational performance against forward-looking demand signals and evaluate whether existing capacity pipelines are sized appropriately for the coming cycle.
Importantly, the growth profile is differentiated across product families, application channels, and geographic corridors. While aggregate figures provide a directional compass, the strategic value of this study lies in unpacking the variance beneath the headline numbers—revealing where supply tightness intersects with pricing power, where formulation innovation accelerates adoption, and where policy environments create durable procurement advantages.
Market Segmentation Fundamentals
The worldwide Coconut Oil Methyl Esters Market is structured across three analytical dimensions that collectively determine competitive exposure and commercial opportunity. By product type, the market encompasses distinct methyl ester ranges that serve different solvency, emulsification, and lubricity requirements. The lighter C8-C10 segment and the broader C12-C14 range cater to divergent downstream applications, from high-performance surfactants and cleaning intermediates to emollient carriers and lubricant additives. Understanding the relative weight of these families is essential for assessing margin profiles, feedstock utilization efficiency, and the risk of regulatory or consumer preference shifts.
By application, end-use channels span personal care and cosmetics, detergents and cleaning agents, industrial lubricants and additives, and food alongside agrochemical segments. Each vertical imposes its own specification thresholds, regulatory scrutiny, and procurement cadence. Formulators in personal care, for example, prioritize purity, color, and free fatty acid constraints, while industrial and agro end-users focus on bulk availability, solvency behavior, and compatibility with existing process streams. The interplay between these application demands and the supply side’s fractionation and distillation capabilities shapes both volume distribution and pricing architecture.
Regional distribution further informs procurement strategy, capacity placement, and trade exposure. The study evaluates how local feedstock availability, refining infrastructure, and downstream manufacturing density influence consumption patterns across major economic corridors. For enterprises assessing distribution partnerships, blending facilities, or contract manufacturing arrangements, granular regional insight is indispensable for balancing incremental market access against logistical cost and regulatory compliance overhead.
Competitive Landscape and Strategic Positioning
Concentration within the market remains a defining feature of competitive dynamics. Our analysis indicates a consolidated environment in which a minority of leading participants command a significant share of revenue, while a broader ecosystem of specialized producers and distributors serves niche specification requirements. The reported market concentration metrics underscore the importance of supply relationship durability, technical service capability, and product consistency in securing long-term contracts with formulators and industrial buyers.
Several established players shape the competitive baseline. Wilmar International Limited operates extensive oleochemical production facilities in Southeast Asia and delivers fractionated methyl ester ranges, including stripped coconut methyl ester variants, through transesterification processes. Its portfolio is positioned across surfactants, lubricants, and intermediate applications, supported by integrated regional manufacturing capacity. Tantuco Enterprises, Inc. maintains a vertically integrated model anchored in the Philippines, with a coconut methyl ester operation linked to its oleochemical division and RBD coconut oil and glycerine lines, supported by substantial annual production capacity and direct copra sourcing. Stepan Company provides coconut-derived methyl ester series, including methyl laurate and related solvent and intermediate products, addressing surfactant, cleaner, and agricultural formulation needs.
Oleon NV contributes methyl ester offerings for oleochemical applications such as emollients and surfactants in personal care and industrial segments, reinforcing the European and global supply network for specialized specifications. Covalent Chemical distributes methyl cocoate as a surfactant raw material applicable across skin care, cosmetics, textiles, rubber, plastics, paints, and inks, serving formulators who require consistent quality and technical documentation. Parchem Fine & Specialty Chemicals supplies coconut oil methyl ester globally as an intermediate across agriculture, asphalt, cleaners, coatings, personal care, lubricants, metalworking, and biodiesel adjacencies, with defined specification parameters including free fatty acid limits and color thresholds.
These participants illustrate the spectrum of competitive approaches: large-scale integrated producers, regionally anchored manufacturers, and specification-focused distributors. Our report assesses the relative positioning of each, the implications of their capacity strategies and regional footprints, and the competitive pressure points likely to influence procurement terms, specification availability, and pricing stability over the forecast period.
Regulatory and Raw Material Dynamics Shaping 2026
Decision-making in 2026 must account for an active policy environment and raw material conditions that directly influence feedstock economics. International coconut oil prices, which serve as the primary input for coconut oil methyl ester production, have trended within an elevated band relative to pre-pandemic levels. Annual pricing has generally remained in a range anchored around the low thousands of USD per metric ton, reflecting modest production recovery, persistent demand from food, cosmetic, and bio-based industrial channels, and supply constraints linked to weather impacts. February 2026 pricing signals from key producing regions indicate continued tightness, reinforcing the importance of hedging strategies, contract structuring, and supply diversification for buyers exposed to input cost fluctuation.
On the policy front, regulatory mandates in select markets are actively shaping demand composition. In the Philippines, diesel fuel has maintained a mandatory blend requirement for coconut methyl ester following increases implemented in late 2024, with planned incremental increases to higher blend levels subject to ongoing review due to feedstock cost pressures. This regulatory stance carries broad implications for domestic production viability, copra price support, and the balance between imported alternatives and locally sourced methyl esters.
Recent policy positions underscore this tension. In March 2026, the Philippine Coconut Authority opposed any full suspension of the mandatory biodiesel blend program, advocating instead to preserve the current blend level or revert to a lower threshold rather than allow substitution with imported palm methyl ester. The stated rationale centered on protecting local copra prices, supporting farmers, and safeguarding the viability of domestic CME production facilities. This stance reflects a broader strategic concern: when policy design intersects with feedstock economics, procurement architectures must account not only for cost but also for continuity of supply, domestic content requirements, and potential future blending increments.
For enterprises operating across food, cosmetics, cleaning, lubricants, and agro segments, these dynamics translate into practical considerations. Procurement teams must evaluate the resilience of supply contracts under variable feedstock pricing, assess the likelihood of regulatory adjustments in blend mandates, and determine whether regional sourcing or blended feedstock strategies can mitigate exposure. Our complete study maps these dynamics against end-use demand and competitive capacity, enabling teams to model scenarios rather than react to them.
Actionable Intelligence Inside the Report
This research is designed as a decision-support instrument rather than a static overview. It combines historical tracking, forward modeling, segmentation detail, and competitive assessment into a coherent framework that can be applied across planning functions. The full publication includes:
Worldwide Coconut Oil Methyl Esters Market
- Historical reconstruction and forecast modeling that align baseline performance with projected growth corridors, enabling scenario testing around blend mandates, feedstock pricing, and downstream substitution trends.
- Product-type and application-level analysis that isolates the relative contribution, specification requirements, and procurement characteristics of each segment to inform product portfolio decisions and technical service investments.
- Regional consumption and supply context that connects feedstock availability, refining capacity, and end-user density to procurement footprints and distribution strategies.
- Competitor positioning and capability mapping that evaluates integrated producers, specialty manufacturers, and distributors by production approach, geographic reach, and application coverage, highlighting where differentiation is most durable.
- Regulatory and policy tracking that integrates mandates, blend trajectories, and industry association positions into a practical view of demand risk and supply continuity.
- Strategic recommendations for 2026 and beyond that translate market structure and dynamics into actionable guidance for capacity planning, contracting strategy, specification management, and market entry or expansion decisions.
The report also documents key specification parameters, quality controls, and application compatibility considerations that directly influence supplier selection and formulation adoption. For teams evaluating supplier qualification, contract terms, or technical collaboration, these details reduce uncertainty and accelerate internal decision cycles.
Why This Study Matters for 2026 Strategy
In a market where aggregate growth is steady but underlying conditions are variable, strategic advantage arises from knowing where concentration creates margin resilience, where application demand is expanding fastest, and where policy and feedstock economics may alter procurement economics. The 4.78 percent compound annual growth rate projected across the forecast window signals durability, yet the composition of that growth differs materially by segment and region. Generic market narratives are insufficient for capital planning, vendor selection, or portfolio optimization in this environment.
Our analysis equips leadership teams to answer targeted questions: which product ranges align with high-specification end-use channels and command premium positioning; how regional supply structures influence availability and trade exposure; what capacity strategies are being pursued by leading participants; and how blend mandate trajectories and feedstock pricing may alter the cost base and sourcing options over the next several years. By linking macro direction with segment-level context and competitive intelligence, the study helps organizations prioritize investments where the risk-reward profile is most favorable.
Access the Full Worldwide Coconut Oil Methyl Esters Market Research
The full report extends beyond headline growth figures to deliver detailed segment context, company-level capability assessment, policy tracking, and scenario-ready forecasting that can be integrated into procurement, R&D, and commercial strategy workflows. For organizations preparing for 2026 and the multi-year horizon through 2032, comprehensive intelligence is the difference between reactive positioning and deliberate market strategy.
To obtain the complete dataset, segmentation detail, competitive profiles, and forward-looking strategic guidance, request the full Worldwide Coconut Oil Methyl Esters Market research. The publication is structured to support executive review, operational planning, and supplier evaluation with the specificity required to act confidently in a dynamic oleochemical environment.
For detailed analysis of this topic, please visit the official page: Worldwide Coconut Oil Methyl Esters Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com