

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global Sparkling Water Maker Market to Hit $2.7B by 2032

Global Sparkling Water Maker Market 2026–2032: Strategic Intelligence for Decision Makers
The worldwide sparkling water maker market is entering a phase of disciplined expansion, driven by shifting consumer habits, supply chain recalibration, and intensifying product innovation. At PW Consulting, we recognize that sustainable growth in this category requires more than headline revenue figures. It demands a rigorous understanding of how unit economics, channel dynamics, regional maturity, and competitive positioning intersect across the forecast horizon. Our Worldwide Sparkling Water Maker Market research was built to provide exactly that operational clarity.
Worldwide Sparkling Water Maker Market
Between 2020 and 2025, the category moved from post-pandemic normalization into a structurally stronger demand environment. Revenue progressed from approximately USD 1,020.15 million in 2020 to an estimated USD 1,533.95 million in 2025, reflecting a compound trajectory that underscores both household adoption and sustained commercial interest. The forecast window from 2026 through 2032 extends this momentum, projecting revenues to reach USD 1,732.84 million in 2026 and advance toward USD 2,715.31 million by 2032. This growth path corresponds to a forecast-period CAGR of 8.5 percent, a rate that rewards organizations able to align product portfolios, pricing architectures, and distribution strategies with evolving consumer expectations.
For executives planning 2026 budgets, capacity decisions, and channel investments, these aggregate numbers are only the starting point. The strategic value of our analysis lies in translating macro growth into actionablesegmentation, competitive mapping, and risk-aware scenario planning. The following overview outlines the structure, content, and decision utility of the full report, while intentionally leaving the granular regional, application, and channel data for the complete intelligence package.
Report Architecture: From Market Physics to Execution Roadmaps
What the Full Study Delivers
Our research is structured to support cross-functional planning across product, sales, supply chain, and corporate development teams. The report integrates historical performance tracking with forward-looking scenario modeling, ensuring that strategy teams can test assumptions against both demand-side shifts and input-cost realities.
Commercial Soda Water Dispenser Market
The core analytical modules include:
- Historical market sizing and trajectory analysis covering 2020 through 2025, establishing baseline momentum and post-cycle normalization patterns
- Forecast modeling for 2026–2032 with explicit growth drivers, moderation risks, and sensitivity considerations
- Type-level evaluation distinguishing manual sparkling water makers from electric sparkling water makers, with attention to performance trade-offs, consumer preference gradients, and portfolio implications
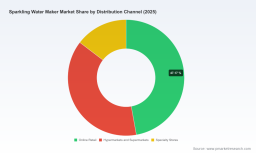
- Distribution channel assessment spanning online retail, hypermarkets and supermarkets, and specialty stores, including channel-mix dynamics and go-to-market leverage points
- Competitive benchmarking across the leading global and regional players, with emphasis on product architecture, brand positioning, and strategic differentiation
- Regulatory and input-cost context, particularly around beverage-grade carbon dioxide supply, purity standards, and cost volatility exposure
- Consumer habit analysis supporting demand forecasting, messaging strategy, and premiumization pathways
Each section is designed to avoid generic market description and instead surface implications for pricing power, channel selection, model mix, and capacity planning. The report also bridges market-level insights with operational reality, allowing teams to assess where growth is concentrated, where competition is intensifying, and where margin protection requires deliberate structuring.
Growth Dynamics and the 2026 DecisionHorizon
Why the Forecast Period Matters Now
The 2026–2032 window is not simply an extension of recent historical performance. It reflects a market where adoption is broadening beyond early innovators, yet competitive intensity is rising in parallel. Organizations entering this period with static product assortments or fixed channel assumptions risk losing share to players who are recalibrating around design, convenience, versatility, and input-cost resilience.
Several structural forces shape the trajectory:
- Demand normalization in developed markets, where carbonated water has become a recurring household staple rather than an occasional purchase
- Continued expansion in higher-growth regions, where urbanization, retail modernization, and aspirational kitchen appliance spending support incremental adoption
- Product-tier divergence, with premium design-led models competing alongside affordable, utility-focused offerings
- Channel evolution as digital retail infrastructure matures and omnichannel purchase journeys become more relevant to durable home appliances
Our forecast frames these dynamics within a disciplined growth path, but the real decision value lies in understanding which levers matter most in each strategic context. For instance, a manufacturer prioritizing volume may focus on accessible price points and mass retail reach, while a design-led brand may emphasize limited colorways, premium materials, and specialty retail credibility. The report helps leaders identify where their strategic posture aligns with market structure and where it may require adjustment.
Competitive Landscape: Strategic Archetypes and Positioning Pressure
Who Shapes the Market and How
The competitive environment is defined by a mix of scale leaders, design-focused specialists, versatile appliance players, and professional-grade tool manufacturers. Rather than treating competition as a static ranking, our analysis maps companies into strategic archetypes that reveal where differentiation is durable and where commoditization risk is rising.
At the center of the category sits a dominant global leader with broad product lines, strong retail distribution, and ecosystem advantages in flavor compatibility and brand recognition. This scale position supports shelf presence, consumer trust, and cross-selling potential, but it also invites targeted challenges from brands that compete on aesthetics, material quality, or functional flexibility.
Alongside the leader, a set of premium specialists competes through Scandinavian and European design language, stainless steel construction, and emphasis on durability and kitchen aesthetics. These players often target consumers willing to pay for appearance, perceived craftsmanship, and long-term product identity. Their relevance grows in markets where kitchen appliances are treated as lifestyle statements as much as utility devices.
A second competitive cluster focuses on versatility and beverage expansion. Some manufacturers position their systems as capable of carbonating more than plain water, including juices, cocktails, and other liquids. This functional breadth can widen use cases and justify higher price points, but it also introduces complexity in consumer education and usage expectations.
Budget-conscious and high-volume segments are served by affordable offerings that emphasize simplicity, quick bottle systems, and water-focused performance. These models compete on accessibility and ease of adoption, often relying on retail visibility and value messaging to capture first-time purchasers.
The landscape also includes iconic design brands that integrate carbonation into premium kitchen styling, appliance conglomerates extending into beverage carbonation within broader small-appliance portfolios, and niche specialists focused on siphons and professional-grade tools for culinary applications. Together, these players illustrate the category’s breadth: sparkling water makers are no longer a single product story but a spectrum of solutions spanning utility, design, versatility, and professional use.
Our corporate profiles examine each major player’s positioning, product architecture, and market relevance, then connect those profiles to broader strategic questions. Where does each brand win? Which consumer segments are most accessible? What product iterations signal future competition? These are the kinds of questions the full report is built to answer.
Demand Shifts, Input-Cost Realities, and Supply-Chain Implications
Beyond Consumer Adoption
Market growth cannot be understood in isolation from input availability and cost behavior. Beverage-grade carbon dioxide is a core enabler of sparkling water makers, and its supply dynamics directly influence production economics and margin planning. Recent analysis indicates that the U.S. beverage-grade carbon dioxide market was estimated at USD 547.0 million in 2025, with projections reaching USD 780.1 million by 2033. This trajectory signals expanding input demand, but also underscores the importance of sourcing stability.
Equally important is volatility. Beverage-grade CO2 has experienced price volatility exceeding 40 percent annually in recent periods, influenced by feedstock costs from ethanol and fertilizer production cycles. For sparkling water maker manufacturers and brand owners, this level of variability can affect cost structures, replenishment timing, and pricing flexibility. Even when final consumer pricing does not move in lockstep with input costs, internal budgeting and supplier negotiation strategies must anticipate fluctuation.
Regulatory expectations add another layer of complexity. Beverage manufacturers and carbonation system providers prioritize high-purity CO2 that meets FDA and food-safety requirements, with traceability for use in both home and commercial systems. This focus on purity and documentation matters not only for compliance but also for brand assurance, especially as consumers become more attentive to ingredient integrity and product safety.
Broader environmental policy trends also shape the operating environment. Global carbon pricing instruments covered around 28 percent of emissions in 2025, creating potential cost implications across CO2 production and beverage carbonation supply chains. While the direct impact will vary by region and supplier footprint, organizations with internationally exposed operations should consider how carbon-related costs may influence total landed cost and long-term competitiveness.
Consumer Behavior: The Demand Floor and the Premium Ceiling
Why Household Habits Translate into Category Resilience
Consumer adoption is the engine behind sustained category performance. Recent sector analysis indicates that more than 62 percent of urban households in developed markets considered carbonated water a weekly staple as of Q4 2025. This habit formation supports a durable demand base for home sparkling water makers, especially where convenience, cost-per-serving considerations, and flavor customization align with everyday usage.
Importantly, habit strength does not automatically translate into uniform purchasing behavior. Some households prefer low-friction manual systems, while others seek electric convenience. Some prioritize simplicity and price, while others choose premium design or multi-beverage capability. This behavioral diversity is precisely why segment-level evaluation matters: the market reward goes to companies that can match product architecture to the right consumer job-to-be-done, rather than relying on a single universal offering.
For 2026 planning, the implication is clear. Growth is supported by habitual usage, but differentiation is determined by how well brands serve distinct preference clusters. Messaging, packaging, accessory ecosystems, and after-sale support all influence whether a first purchase becomes repeat usage or category churn.
Recent Product Developments: Signals of Competitive Acceleration
What Launches Reveal About Direction
New product activity in this category is not merely cosmetic. It reflects shifting priorities in design, performance, and use-case expansion. In September 2025, MySoda Oy introduced the Ruby 2 All Black premium sparkling water maker, designed to compete with established brands through enhanced aesthetics and performance. This launch underscores the continued importance of premium positioning and material-led differentiation, especially where design credibility can support margin resilience.
In September 2024, SodaStream International Ltd. launched the enso and ART GOLD sparkling water makers alongside new SodaStream Crafted cocktail mixers, expanding home carbonation offerings into flavor and mixology adjacent use cases. Moves like these illustrate how category leaders seek to deepen engagement by broadening the functional and experiential appeal of home carbonation, rather than competing solely on the device itself.
These developments are consistent with a broader pattern: brands are refining aesthetics, expanding model ranges, and exploring adjacent consumption occasions. Our report contextualizes such launches within competitive strategy, helping readers interpret whether new products represent incremental line extensions, defensive positioning, or genuine differentiation.
How to Use This Research for 2026 Planning
From Intelligence to Action
The Worldwide Sparkling Water Maker Market report is designed to support concrete decisions rather than abstract market awareness. Depending on organizational role, the analysis can be applied to:
- Portfolio prioritization, including which product types and feature sets deserve investment in the next planning cycle
- Channel strategy, identifying where distribution effort should be concentrated and how channel mix may evolve
- Competitive response planning, especially as premium design players, versatile appliance brands, and value-oriented manufacturers all advance distinct propositions
- Supply chain and sourcing sensitivity, particularly regarding input volatility and the need for resilience in CO2-dependent categories
- Geographic expansion assessment, using regional maturity and demand structure to inform rollout sequencing without overcommitting to underdeveloped or saturated contexts
- Pricing and value architecture, aligning price tiers with consumer willingness to pay for design, convenience, and versatility
Because the market is projected to grow at an 8.5 percent CAGR across the 2026–2032 forecast period, pacing matters. Organizations that move early with well-targeted product and channel decisions may secure advantageous positions before competitive density increases further. At the same time, indiscriminate expansion can erode margins, especially where input costs fluctuate and regional demand structures differ. The full report provides the segmentation depth and strategic context required to make these trade-offs explicit.
Concentration, Risk, and the Case for Detailed Market Intelligence
Why Aggregation Is Not Enough
Market-level revenue and growth rates are essential, but they do not reveal the distribution of opportunity or the concentration of competitive advantage. The sparkling water maker market reflects a moderately concentrated structure, with the top three players accounting for approximately 68.45 percent of market share and the top five reaching about 76.12 percent. This level of concentration suggests that scale, distribution strength, and brand recognition continue to matter, while also implying that targeted differentiation can still create meaningful footholds for specialist and emerging players.
Concentration also shapes competitive behavior. In a market where leading positions are meaningful but not absolute, incumbents must defend shelf space, consumer attention, and product relevance, while challengers must identify niches where design, versatility, or value can break through. Understanding how these forces interact across segments and channels is central to strategic planning.
The report’s detailed segmentation and company-level analysis is intended to make these dynamics legible. By separating regional performance patterns, type-based demand profiles, and channel-specific behavior, the study allows decision makers to assess where concentration is an advantage, where it is a vulnerability, and where it can be disrupted through disciplined positioning.
Conclusion: A Market Ready for Disciplined Strategy
The worldwide sparkling water maker market is moving into a period where growth is supported by habitual demand and broadening product relevance, yet challenged by input volatility, competitive overlap, and the need for targeted differentiation. An 8.5 percent forecast-period CAGR through 2032 signals opportunity, but the real strategic advantage will belong to organizations that can translate that growth into segment-appropriate product strategies, channel choices, and supply-chain resilience.
This article has outlined the strategic architecture of our research and the decision problems it is built to address. To access the complete segmentation detail, competitive profiles, regional and channel-level intelligence, and the full forecast dataset needed for 2026 planning, we invite you to explore the full Worldwide Sparkling Water Maker Market report on the PW Consulting platform.
For detailed analysis of this topic, please visit the official page: Worldwide Sparkling Water Maker Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com