

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Category: market research
PW Consulting: Global Mobile Music Rhythm Games Revenue Hits $1.65B in 2025, Nearing $2.68B by 2032
By pmarketresearch, 2026-09-16
Global Mobile Music Rhythm Games Market 2026: Strategic Outlook and Competitive Landscape
The mobile gaming sector continues to evolve at a rapid pace, with music rhythm games emerging as a resilient and highly engaged niche within the broader ecosystem. As players increasingly seek immersive, interactive experiences that blend audio and visual stimuli, the demand for sophisticated rhythm-based mechanics on smartphones has solidified. This article introduces the Worldwide Mobile Music Rhythm Games Market research, a comprehensive study designed to equip stakeholders with the actionable intelligence needed for strategic decision-making in 2026 and beyond. By analyzing revenue trajectories, competitive positioning, and technological shifts, this report serves as a critical tool for publishers, investors, and developers navigating a complex market environment.
Understanding the nuances of this segment requires more than surface-level metrics. It demands a granular look at how monetization strategies interact with player behavior across different platforms and regions. The following analysis outlines the macro-economic backdrop, details the specific contents of the market study, and examines the key players shaping the industry. The goal is to highlight the strategic value of deep-dive research in an era where data-driven choices determine market leadership.
Market Dynamics and Revenue Trajectory
The economic foundation of the mobile music rhythm games market has shown consistent expansion, driven by a combination of growing smartphone penetration, improved audio processing capabilities, and a vibrant culture of community engagement. Historical data indicates a steady compounding of revenue, with the market valued at approximately USD 1,210.45 Million in 2020. This figure grew to USD 1,272.37 Million in 2021, followed by a significant jump to USD 1,450.7 Million in 2022.
While 2023 saw a slight adjustment to USD 1,440.83 Million, the market regained momentum, reaching USD 1,601.62 Million in 2024 and stabilizing at an estimated USD 1,650.0 Million in 2025. This trajectory sets the stage for the forecast period spanning 2026 to 2032. Current projections suggest that the market will reach USD 1,711.88 Million in 2026, continuing its upward climb to USD 1,837.18 Million in 2027 and USD 2,017.22 Million in 2028. By the end of the forecast horizon in 2032, the market is anticipated to approach USD 2,684.41 Million.
This growth pattern reflects a Compound Annual Growth Rate (CAGR) of 7.2 Percent over the forecast period, signaling a healthy expansion rate that outpaces many broader gaming segments. For stakeholders, this CAGR offers a reliable benchmark for internal budgeting and external investment pitches. The consistency of revenue growth, despite macroeconomic fluctuations, underscores the sticky nature of rhythm game communities. Players frequently return to these titles for daily challenges, event participation, and social competition, ensuring predictable cash flow for operators who maintain high engagement standards.
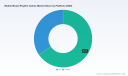
Furthermore, the revenue streams within this market are diversified, though heavily weighted toward specific models. The data indicates a dominant preference for Freemium and In-App Purchases, which constitute the largest share of the revenue pie. Premium and Paid Downloads represent a smaller but stable fraction, while Ad-Supported Services contribute a supplementary layer. This hierarchy suggests that while upfront payment models retain a loyal user base, the long-term scalability of the market relies on continuous content updates, battle passes, and character gacha mechanisms typical of the freemium ecosystem.
Worldwide Mobile Music Rhythm Games Market
Platform distribution also reveals critical strategic insights. iOS and Android remain the primary conduits for revenue generation. The split between these platforms often informs technical development priorities and monetization tuning, as user demographics and spending behaviors can vary significantly between the two ecosystems. Understanding the relative weight of each platform is essential for allocating marketing spend and optimizing user acquisition costs.
Geographically, the market is not uniformly distributed. Certain regions demonstrate higher density of players and spending power, influencing where publishers prioritize localization efforts and server infrastructure. While detailed regional percentages are reserved for the full report, the macro data confirms that a few key territories drive the majority of global volume, making regional strategy a non-negotiable component of success.
Industry Dynamics and Recent Developments
The operational landscape for mobile rhythm games is shaped by a mix of technical standards, regulatory frameworks, and cultural trends. Mobile games, including rhythm titles, operate under app store policies from Apple and Google governing in-app purchases, age ratings, and data privacy compliance such as GDPR and CCPA equivalents in major markets. Compliance with these regulations is not merely a legal requirement but a trust signal that impacts user retention and brand reputation. Publishers must navigate age classification systems carefully, especially when featuring music content that may vary by region, and ensure that data collection practices remain transparent to avoid regulatory penalties.
Recent product launches and platform expansions highlight the innovation occurring within the sector. In January 2026, Cover Corporation unveiled hololive Dreams, a new mobile rhythm game featuring falling notes gameplay. Planned for global release in 2026, the title leverages the popularity of hololive talent songs and covers, illustrating the trend of integrating established IP and virtual talent into rhythm mechanics to drive immediate user interest. This move signals a broader industry shift toward leveraging community-driven fandoms to accelerate market entry.
Earlier in October 2025, Crunchyroll announced the launch of Spin Rhythm XD Mobile, set to launch exclusively on the Crunchyroll Game Vault in Q4 2025. This platform-specific launch demonstrates the strategic value of integrating rhythm games into larger entertainment ecosystems. By bundling rhythm experiences with anime and media content platforms, publishers can access cross-demographic audiences and enhance user lifetime value through ecosystem lock-in. These developments suggest that the boundary between standalone games and broader media platforms is blurring, creating new opportunities for partnership and content synergy.
The industry context also points to a maturation of gameplay mechanics. Developers are increasingly experimenting with laneless formats, falling note challenges, and dimension-blending styles to differentiate their titles in a crowded market. Innovation in user interface and audio synchronization remains a key differentiator, as players demand precision and responsiveness that rivals dedicated console experiences. As hardware capabilities on mobile devices improve, the ceiling for visual fidelity and audio complexity continues to rise, allowing developers to create more immersive experiences without sacrificing portability.
Report Scope and Operational Content
The Worldwide Mobile Music Rhythm Games Market research is structured to provide a 360-degree view of the industry, enabling stakeholders to move from high-level trends to granular execution plans. The report covers the historical period from 2020 to 2025 and extends the forecast through 2032, offering a long-term perspective essential for strategic planning. The analysis is anchored in primary and secondary research methodologies, ensuring that the data reflects actual market conditions rather than theoretical models.
Racing Games Market
Key components of the report include a detailed market size analysis that breaks down revenue by major classification axes while maintaining the confidentiality of sensitive granular data. Readers will find a comprehensive segmentation analysis that dissects the market by region, business model, and platform. While the full report provides the exact split and dollar values for each segment, the executive overview highlights the relative dominance of key regions and the preference for freemium monetization, guiding readers to dive deeper for the precise numbers required for financial modeling.
Beyond size and segmentation, the report delivers an extensive competitive landscape analysis. This section profiles the core companies driving the market, examining their headquarters, business focus, and strategic positioning. The analysis covers a diverse set of players, ranging from major global publishers and tech conglomerates to specialized developers known for specific titles. Companies such as Tencent, with significant presence in the music rhythm genre via distribution and development support, and T3 Entertainment, focused on music and rhythm games for mobile platforms, are examined for their impact on market dynamics.
The report also details the activities of regional specialists and niche innovators. This includes Rayark Inc., developer of the major Cytus and Cytus II series; Colorful Palette, creator of the leading Project SEKAI COLORFUL STAGE! feat. Hatsune Miku; and Lowiro Limited, developer of the prominent new dimension rhythm game Arcaea. Developers like PigeonGames, known for the laneless mobile rhythm game Phigros, and DRIMAGE Co., Ltd., developer of the official HYBE rhythm game Rhythm Hive featuring BTS and other artists, are analyzed for their unique value propositions. Additionally, the landscape includes contributions from entities such as C4Cat, Baidu, 7th Beat Games, Maniacs s.r.o., Tiger Tang, Digixart, and Konami, the latter bringing rhythm game heritage including mobile adaptations.
Competitive metrics such as market concentration are included to assess the level of competition. Data on CR3 and CR5 percentages provides insight into the consolidation of the market, helping stakeholders understand the balance between dominant incumbents and emerging challengers. A highly concentrated market may suggest barriers to entry and the importance of partnership strategies, while a fragmented landscape could indicate opportunities for differentiation and niche capture.
The report further incorporates a section on industry dynamics, addressing the regulatory and operational factors that influence market behavior. This includes a discussion of app store policies, age rating compliance, and data privacy requirements across major markets. Understanding these constraints is vital for risk management and for designing monetization structures that comply with platform rules while maximizing revenue.
Recent developments are tracked to capture the pulse of the market. By analyzing product announcements, platform launches, and partnership news, the report helps readers stay ahead of trends that could disrupt the status quo. For example, the analysis of how virtual talent IPs are being integrated into rhythm games or how media platforms are hosting exclusive rhythm titles provides early signals for where investment and development focus should shift.
Strategic Implications for Decision-Makers
For business leaders and investors, the value of this research lies in its ability to translate data into strategy. The projected growth to USD 2,684.41 Million by 2032 suggests a market with substantial room for expansion, but capturing that growth requires precise execution. The dominance of the freemium model implies that success depends on robust content pipelines, balanced monetization, and community management. Publishers must invest in regular updates, event cycles, and social features that keep players engaged over the long term.
The platform dynamics further inform resource allocation. With iOS and Android sharing the revenue base, developers need to tailor their technical and marketing strategies to the nuances of each ecosystem. This might involve optimizing store presence, adjusting pricing tiers, or leveraging platform-specific advertising tools. Regional insights, though high-level in the preview, point to the necessity of localization. Expanding into high-value territories requires not just translation but cultural adaptation of music selections, events, and marketing messaging.
Competitive analysis offers a roadmap for positioning. By studying the profiles of key companies like Tencent, Konami, and Rayark, as well as specialized developers like PigeonGames and Colorful Palette, stakeholders can identify best practices in game design, IP utilization, and user acquisition. The presence of large tech companies like Baidu alongside dedicated rhythm game studios illustrates the variety of approaches to market entry and growth. New entrants can learn from the strengths of established players while looking for gaps in the market that allow for differentiation, such as innovative gameplay mechanics or unique IP partnerships.
The report's coverage of market concentration metrics helps in assessing the competitive intensity. A market with significant concentration may favor incumbents with established brands and large user bases, making it crucial for new players to secure strong differentiators or strategic partnerships. Conversely, areas of lower concentration may present opportunities for agile developers to gain traction with superior products or targeted marketing. Understanding the CR3 and CR5 dynamics allows for a realistic assessment of the barriers to scale and the potential for market disruption.
Finally, the inclusion of recent developments such as the hololive Dreams announcement and the Crunchyroll Game Vault launch underscores the importance of agility. The ability to capitalize on trends like IP integration and ecosystem partnerships can accelerate growth and reduce customer acquisition costs. Stakeholders who monitor these signals and adapt their strategies accordingly will be better positioned to capture emerging opportunities.
Conclusion and Call to Action
The Worldwide Mobile Music Rhythm Games Market is poised for sustained growth, supported by a dedicated player base, evolving monetization models, and continuous innovation in gameplay and content. The trajectory from USD 1,650.0 Million in 2025 to a projected USD 2,684.41 Million by 2032 reflects a market that is both resilient and expanding. However, realizing the full potential of this growth requires more than general awareness. It demands precise data, competitive intelligence, and a deep understanding of regional and platform-specific dynamics.
This article has provided a strategic overview of the market landscape, highlighting key revenue trends, recent industry developments, and the scope of analysis available. It has touched upon the dominance of freemium models, the distribution across platforms, the concentration of market share, and the diverse array of companies vying for leadership. Yet, the macro view only scratches the surface. The exact segmentation splits, detailed regional revenue figures, precise platform shares, and comprehensive competitive profiles contain the granular insights necessary for accurate forecasting and targeted strategy formulation.
To access the full spectrum of intelligence, including the confidential data cuts, detailed company profiles, and actionable recommendations, stakeholders are encouraged to consult the complete Worldwide Mobile Music Rhythm Games Market report. The full study offers the depth required to make informed decisions, mitigate risks, and capitalize on the opportunities within this dynamic sector. Explore the comprehensive research to transform market knowledge into competitive advantage.
Access the full report at: https://www.globemarketresearch.com/report/mobile-music-rhythm-games-market
Contact Information:
Email: info@globemarketresearch.com
Website: https://www.globemarketresearch.com
For detailed analysis of this topic, please visit the official page: Worldwide Mobile Music Rhythm Games Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Telecom Security Software to Hit $15.5B in 2025, Grow at 13% CAGR Through 2032
By pmarketresearch, 2026-09-16
Global Telecom Security Software Market: Strategic Intelligence for 2026 Decision-Making
The telecommunications industry is currently navigating a transformative period defined by rapid technological shifts and escalating security challenges. As networks evolve toward 5G standalone architectures and beyond, the surface area for potential cyber threats expands proportionally. In this environment, security software is no longer a peripheral utility but a core component of network infrastructure and business strategy. PW Consulting's latest Worldwide Security Software in Telecom Market research provides a comprehensive lens through which enterprises and investors can understand these dynamics. This report is designed to equip decision-makers with the actionable intelligence required to navigate the forecast period from 2026 through 2032.
The market trajectory observed over the past five years indicates a robust growth pattern, driven by the urgent need to secure digital infrastructure against sophisticated attacks. Historical data from 2020 to 2025 shows a consistent upward trend in market valuation, reflecting the increasing prioritization of cybersecurity within telecom operations. Looking forward, the market is projected to continue this momentum, with a compound annual growth rate of approximately 13 percent across the forecast horizon. This growth is not merely a function of inflation or expanded connectivity but represents a fundamental structural shift in how security is integrated into network design, deployment, and management.
Market Scale and Growth Trajectory
Understanding the magnitude of this opportunity is essential for capital allocation and strategic planning. The global revenue for security software in telecom has seen significant expansion, moving from a baseline in the mid-eight thousands millions USD in 2020 to surpassing the fifteen thousands millions USD mark by 2025. This historical performance sets the stage for a forecast period where valuations are expected to climb substantially, reaching over thirty-six thousands millions USD by 2032. Such figures underscore the critical nature of security investments as telecom operators transition into techco models, offering cybersecurity offerings alongside traditional connectivity, cloud, and IoT services.
This growth trajectory is supported by several converging factors. The proliferation of edge computing and network slicing creates new vulnerabilities that require specialized software interventions. Furthermore, the regulatory landscape is tightening globally, with governments implementing cybersecurity regulations, trusted vendor policies, and data localization requirements. These compliance drivers compel operators to invest heavily in compliant security software solutions, thereby fueling market expansion. The report details how these macroeconomic and regulatory forces interact to shape demand curves over the next seven years.
Segmentation and Deployment Dynamics
While the overall market size provides a high-level view, the underlying segmentation reveals where the greatest opportunities and risks lie. The market is divided across various dimensions, including deployment mode and solution type. The shift toward cloud-based security solutions is prominent, reflecting the industry's broader migration to virtualized network functions and cloud-native architectures. This deployment mode accommodates the flexibility required for modern telecom environments, though on-premise solutions remain significant for specific high-security or latency-sensitive use cases.
Solution types vary from network security and endpoint protection to identity and access management and cloud security solutions. Each category addresses distinct threat vectors within the telecom ecosystem. For instance, network security remains a dominant focus area given the criticality of protecting the core infrastructure from intrusion. However, as service providers expand their B2B portfolios, identity management and cloud security are gaining traction. The report provides deep dives into each segment, analyzing adoption rates, technological maturity, and regional preference patterns without exposing sensitive proprietary estimates in this summary.
Geography also plays a crucial role in market dynamics. Different regions exhibit varying levels of maturity, regulatory pressure, and investment capacity. North America, Europe, and Asia Pacific represent significant portions of the market, each driven by unique local factors such as digital sovereignty initiatives or infrastructure modernization plans. Latin America and the Middle East and Africa are also contributing to the growth, albeit at different scales. The full research document breaks down these regional nuances, offering specific insights into local market conditions, key regulatory frameworks like the EU Digital Networks Act, and the impact of legal shifts such as recent court rulings on net neutrality that may influence service provider strategies.
Competitive Landscape and Key Players
The competitive environment in telecom security software is characterized by a mix of specialized security vendors and large telecommunications infrastructure providers. Market concentration indicates that a handful of major players command a significant share of the revenue, yet there is ample room for niche innovators and regional specialists. The top five companies collectively hold a substantial portion of the market, reflecting the importance of scale, brand reputation, and integrated solution portfolios in this sector.
Key companies such as Cisco Systems, Palo Alto Networks, and Fortinet are central to the landscape, offering comprehensive solutions ranging from secure firewalls to AI-driven security platforms tailored for 5G and enterprise networks. These vendors are continuously innovating, with recent developments highlighting a focus on sovereign AI security frameworks and fabric-based AI agents. For example, recent product releases in early 2026 have introduced new innovations for AI and modern networks, emphasizing secure AI controls and simplified SD-WAN for telecom environments. Such movements signal a trend where security vendors are embedding intelligence directly into the network fabric to handle evolving threats autonomously.
Telecom infrastructure giants like Ericsson and Nokia also play a pivotal role, providing 5G core security solutions and cloud packet core security integrated directly into the hardware and software stacks operators rely on. Their approach often focuses on built-in security features for RAN, core, and transport networks, ensuring security is baked into the infrastructure from the outset. Meanwhile, companies like Huawei Technologies and Juniper Networks contribute extensive portfolios covering everything from cloud fabric security to AI-driven routing solutions optimized for service providers.
The landscape also includes specialized players focusing on specific telecom security niches. Check Point Software Technologies offers advanced threat prevention suitable for network perimeters, while Allot specializes in traffic management and DDoS protection for mobile networks. P1 Security stands out with a focus exclusively on telecom security software for 5G, 4G, and OpenRAN attack simulation. Additionally, firms like F5 Networks and Trend Micro provide application security and hybrid cloud security solutions applicable to telecom environments. The report profiles these companies in detail, analyzing their recent partnership expansions, product launches, and strategic positioning. For instance, recent announcements at major industry events have highlighted expanded security ecosystems aimed at protecting AI factories in telecom networks, indicating a strategic pivot toward securing the artificial intelligence infrastructure that powers modern networks.
Telecommunications Market
Industry Dynamics and Regulatory Context
Macro-level dynamics are reshaping the market just as much as technological innovation. The shift toward techco models means telecom operators are increasingly competing with traditional IT security firms, blurring the lines between connectivity and security services. This convergence creates both opportunities for revenue diversification and challenges in maintaining operational focus. Furthermore, the threat landscape remains volatile. Threat intelligence reports from late 2025 warned that telecom threats observed involving new technologies are expected to persist into 2026, necessitating proactive rather than reactive security postures.
Regulatory pressure is a critical driver in this environment. In Europe, advancements in the Digital Networks Act aim to stimulate investment in next-generation networks while addressing digital sovereignty and cybersecurity requirements. Simultaneously, the EU has set targets for the transition to quantum-safe cryptography in telecommunications, pushing vendors and operators to future-proof their encryption standards. Globally, governments are implementing trusted vendor policies and data localization requirements that affect how security software is deployed and sourced. In the United States, legal challenges regarding net neutrality rules have added layers of complexity to network management strategies, indirectly influencing security architecture decisions.
These regulatory and dynamic shifts create a complex operating environment. Companies must navigate compliance hurdles while ensuring their security solutions remain effective against evolving threats. The research report analyzes how these factors influence market growth, vendor selection criteria, and deployment strategies across different regions. It provides a framework for understanding how regulatory compliance can be turned into a competitive advantage rather than viewed solely as a cost center.
Worldwide Security Software in Telecom Market
Strategic Value for 2026 Decision-Makers
For enterprises operating in or investing in the telecom sector, access to granular, forward-looking data is vital. This research offers more than just high-level numbers; it delivers an operational blueprint for the forecast period. Decision-makers can utilize the insights to refine their product development roadmaps, identify partnership opportunities, and assess market entry risks. The detailed segmentation analysis helps in pinpointing high-growth niches, while the competitive profiling allows organizations to benchmark their strategies against leading players.
The inclusion of recent developments, such as partnership expansions and product releases from key vendors, ensures that the intelligence is current and actionable. Understanding the timing and nature of these moves can provide early signals of market shifts. For example, the focus on sovereign AI security frameworks suggests a growing demand for localized, trusted security solutions that protect AI workloads within telecom networks. Recognizing such trends early allows strategies to align with emerging demands before the market becomes saturated.
Furthermore, the report addresses the consolidation trends reflected in market concentration metrics. Knowing the share held by the top three or five players helps investors and competitors understand the barriers to entry and the potential for disruption by smaller, agile firms. The balance between established incumbents and specialized innovators is a key theme explored in the analysis, offering guidance on where collaboration or acquisition might yield the highest returns.
Ultimately, the Worldwide Security Software in Telecom Market research is designed to reduce uncertainty. In a sector defined by rapid change, regulatory flux, and sophisticated threat actors, having a reliable source of comprehensive data is a strategic asset. The report enables stakeholders to move beyond intuition and make evidence-based decisions that align with long-term growth objectives.
Accessing Complete Intelligence
This overview serves as a preview of the depth and breadth contained within the full PW Consulting report. While the macro trends and competitive dynamics outlined here provide a solid foundation for understanding the market, the detailed data required for precise planning is available in the complete document. The full report includes granular segmentation splits, specific regional revenue estimates, detailed company profiles with financial and strategic metrics, and extensive analysis of the regulatory landscape across all covered regions.
Readers are encouraged to access the source webpage to download the complete study. There, you will find the specific data points necessary to validate assumptions, build financial models, and craft targeted go-to-market strategies. In an industry where timing and accuracy are paramount, the complete intelligence offered by this research provides the clarity needed to navigate the complex telecom security landscape from 2026 through 2032. The insights contained within are updated to reflect the latest developments and market conditions, ensuring that your strategic decisions are based on the most current information available.
For detailed analysis of this topic, please visit the official page: Worldwide Security Software in Telecom Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Urethritis Drugs Market Hits $2.15B in 2025, Projected 4.85% CAGR Through 2032
By pmarketresearch, 2026-09-16
Global Urethritis Drugs Market Outlook 2026: Strategic Imperatives in a Shifting Therapeutic Landscape
Executive Overview
The worldwide urethritis drugs market stands at a critical inflection point as it moves through the 2026-2032 forecast period. Driven by evolving treatment guidelines, persistent antimicrobial resistance patterns, and a maturing generic ecosystem, the sector is projected to expand from an estimated 2.15 billion USD in 2025 to approximately 2.99 billion USD by 2032, reflecting a compound annual growth rate of 4.85 percent over the forecast horizon. This trajectory is neither linear nor guaranteed. It is shaped by regulatory recalibrations, formulary decisions, supply chain dynamics, and the strategic positioning of incumbent innovators alongside generic manufacturers. For executives navigating product portfolios, commercial planning, and market entry, the 2026 landscape demands a disciplined reading of where volume is migrating, which therapeutic categories are gaining policy tailwinds, and how distribution channels are being reconfigured by reimbursement realities.
This article previews our comprehensive Worldwide Urethritis Drugs Market research, a decision-grade intelligence asset designed to translate macro momentum into actionable commercial strategy. The full study delivers granular segmentation, competitive profiling, pricing and volume trajectories, channel-level dynamics, and scenario frameworks. What follows is a strategic orientation: the structural forces at work, the competitive contours, the regulatory currents, and the analytical architecture that decision-makers will need in 2026 and beyond.
Market Architecture and Growth Logic
Across the historical window of 2020 through 2025, the market consolidated around a core set of widely prescribed antibiotics and standardized treatment protocols, reaching a baseline that positioned the sector for measured expansion. The forecast period from 2026 through 2032 anticipates a broad-based uplift, underpinned by steady demand for first-line agents, incremental uptake of newer options where clinically indicated, and the continued role of public health programs that embed key therapies into STI management pathways.
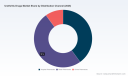
Growth is not uniform across therapeutic categories. The market bifurcates between gonococcal and non-gonococcal indications, each governed by distinct clinical protocols, resistance considerations, and reimbursement exposure. At the same time, distribution channels reflect a pragmatic mix of institutional procurement, community dispensing, and digital fulfillment pathways, with each channel responding differently to formularies, prescription behaviors, and patient access programs. The interplay among these dimensions determines where commercial opportunity concentrates and where margin pressure intensifies.
Beyond the headline trajectory, the research decomposes the market into operationally meaningful layers:
- Therapeutic segmentation that distinguishes treatment pathways by pathogen type and guideline positioning
- Channel-level analysis capturing how hospital, retail, and online pathways differ in volume mix, reimbursement exposure, and growth elasticity
- Geographic framing that isolates high-volume markets and emerging demand centers without overstating localized statistics
- Competitive benchmarking mapped to product positioning, portfolio breadth, and pipeline relevance
This architecture enables teams to move from aggregate growth narratives to channel-level and category-level decision-making, aligning sales coverage, supply planning, pricing strategy, and partnership logic with where value is actually created.
Competitive Landscape: Innovators, Generics, and Positioning Realities
The competitive field blends global innovators with high-volume generic manufacturers, each exercising distinct commercial leverage. A small set of leading firms commands a meaningful share of total market value, while a broader cohort competes on cost, supply reliability, and regional access. Concentration metrics indicate that the top three players account for roughly 28.5 percent of market value, and the top five reach approximately 39.2 percent, signaling a landscape that is neither fully consolidated nor fragmented beyond strategic coherence. For commercial leaders, this structure has direct implications for pricing power, tender dynamics, and partnerships.
Bacterial Vaginosis Drug Market
Pfizer Inc. maintains a recognized presence through azithromycin-based offerings indicated for urethritis and cervicitis, alongside ceftriaxone products relevant to dual-therapy protocols for gonococcal infections. Its positioning is anchored in established brand recognition, clinical heritage, and broad distribution reach, making it a reference point in both institutional and community settings.
GlaxoSmithKline plc has advanced the competitive frontier with newer antibiotic options, including Blujepa for gonococcal infections. The introduction of differentiated therapies in this space is significant because it can shift treatment conversations, influence guideline interpretations, and create premium positioning where resistance management and tolerability matter. GSK’s broader anti-infective portfolio also supports cross-utilization and formularies that span multiple STI indications.
On the generic side, Teva Pharmaceutical Industries Ltd., Sun Pharmaceutical Industries Ltd., Cipla Ltd., and Dr. Reddy's Laboratories Ltd. collectively sustain the supply backbone for widely used agents such as azithromycin and doxycycline. Their commercial relevance lies in affordability, availability, and the ability to serve public health programs and private channels alike. In many markets, these manufacturers determine the practical accessibility of first-line regimens and influence the cost floor for competing products.
AbbVie Inc. and Merck & Co., Inc. contribute through antibiotic and anti-infective portfolios that intersect with broader bacterial infection management. While their direct exposure to urethritis-specific prescriptions varies, their commercial footprint, R&D orientation, and collaboration potential can influence supply resilience, pipeline optionality, and cross-indication utilization patterns.
Recent industry developments reinforce how quickly competitive positioning can shift when clinical evidence and regulatory milestones intersect. The 2025 approval landscape for newer gonorrhea-focused therapies, together with late-stage trial readouts for single-dose oral regimens, signals a market in which innovation may reframe standard-of-care discussions over the forecast period. At the same time, generic competition continues to compress price points in core categories, placing a premium on supply reliability, quality assurance, and channel relationships. The research evaluates each major player’s product relevance, geographic reach, pipeline implications, and likely strategic maneuvers so that clients can benchmark their own positioning and identify whitespace or defensive priorities.
Industry Dynamics Shaping 2026 and Beyond
Market performance in the urethritis drugs space is tightly coupled to clinical guidance, resistance trends, procurement structures, and reimbursement policy. These dynamics do not merely influence demand; they redefine which products are preferred, where volume concentrates, and how durable margin profiles can be.
Clinical practice standards remain foundational. Public health guidance continues to emphasize doxycycline-based regimens as preferred therapy for non-gonococcal urethritis, with azithromycin serving as an alternative in defined scenarios. For gonococcal infections, treatment conversations increasingly account for dual-therapy considerations in response to rising antimicrobial resistance. These protocols shape prescribing behaviors, formulary placement, and the relative pull-through of competing products. As stewardship expectations intensify, the ability to align product positioning with guideline-concordant use becomes a commercial advantage, not just a compliance matter.
Antimicrobial resistance is a persistent structural pressure. Emerging resistance patterns in pathogens associated with non-gonococcal urethritis, including Mycoplasma genitalium and Haemophilus spp., are driving interest in resistance-guided therapy and updated stewardship approaches. This trend has two strategic consequences. First, it increases the clinical value of diagnostic alignment and targeted treatment logic, which can shift demand toward therapies that fit resistance-aware protocols. Second, it creates a backdrop in which new or differentiated options may command greater attention where standard regimens face efficacy or tolerability limitations.
Reimbursement and access frameworks further condition the market. Many standard antibiotics used for urethritis are incorporated into public health formularies and STI treatment programs across multiple regions, which supports stable baseline demand but also reinforces price discipline. In parallel, API supply chains for widely used antibiotics depend on established global manufacturing routes, with generic competition driving cost efficiencies in production. For commercial teams, these realities mean that volume growth can be paired with margin compression unless product strategy accounts for channel economics, tender dynamics, and programmatic procurement.
Supply-side resilience is also increasingly strategic. The market relies on mature production ecosystems, but demand timing, regional availability, and regulatory expectations can create localized constraints or opportunity pockets. In this context, the research evaluates not only what is sold, but how products move through institutional and retail ecosystems, which channels are expanding, and where access models may shift as patient behavior and digital fulfillment continue to evolve.
What the Full Study Delivers: Decision-Oriented Intelligence
Our Worldwide Urethritis Drugs Market research is built for practitioners who need more than top-line forecasts. It is structured to support product strategy, commercial planning, market entry evaluation, and competitive response. The study translates epidemiological and regulatory context into market-level implications, then drills into the segments and channels that matter for operational execution.
Inside the report, readers will find:
- A full market sizing and forecast framework spanning the 2020-2025 historical period and the 2026-2032 outlook, with USD-denominated valuation and growth decomposition
- Segment-level analysis across therapeutic categories and distribution channels, with emphasis on volume pathways, channel economics, and adoption dynamics
- Geographic assessment that identifies where demand is concentrated, where expansion is most plausible, and how regional protocols and programs shape market behavior
- Competitive profiling of leading global and generic manufacturers, covering product relevance, portfolio orientation, and strategic positioning within guideline-driven treatment environments
- Analysis of recent regulatory and clinical developments and their likely influence on treatment standards, formulary decisions, and competitive differentiation
- Scenario-based considerations that help teams evaluate uncertainty around resistance trends, guideline updates, reimbursement shifts, and supply chain conditions
The study is designed to answer 2026-specific questions: Where should sales and market access resources be prioritized? Which categories are most exposed to pricing pressure, and which may support stronger positioning? How should companies interpret evolving STI treatment guidance in commercial terms? Which competitors are likely to defend share through cost leadership, and which are positioned to create differentiation through newer options or portfolio breadth? By connecting market structure with competitive behavior and policy context, the research gives teams a defensible basis for planning across short-term execution and mid-term strategy.
Strategic Implications for 2026 Decision-Making
Entering 2026, successful participation in the urethritis drugs market will depend on three capabilities: reading guideline-driven demand accurately, managing channel and pricing dynamics with discipline, and anticipating where innovation or resistance trends alter the value map. Aggregate growth is supportive, but the real differentiator is how well a company aligns its portfolio, access strategy, and supply posture with the way treatment protocols and reimbursement structures are evolving.
For innovators, the opportunity lies in converting clinical differentiation into durable positioning. Where newer options address resistance concerns, tolerability, or dosing convenience, the strategic task is to demonstrate fit with stewardship expectations and to secure the formulary and procurement relationships that convert clinical relevance into realized demand. For generic manufacturers, the priority is to protect availability, manage cost structures, and navigate programmatic procurement without eroding quality or reliability. For all participants, channel strategy matters: hospital, retail, and online pathways are not interchangeable, and each responds differently to prescription behavior, reimbursement policy, and access programs.
The wider lesson is that market intelligence in this space must be multidimensional. A single growth rate or total market figure is insufficient for planning. Decision-makers need to understand how therapeutic segmentation interacts with channel economics, how resistance trends influence preferred regimens, how guidelines steer volume, and how competitor portfolios shape negotiation dynamics. The full study is built to provide that integrated view.
Access the Full Intelligence
This article has outlined the strategic logic behind the Worldwide Urethritis Drugs Market research and the major forces shaping the 2026-2032 outlook. The detailed segmentation, competitive profiles, channel analysis, and scenario frameworks necessary for concrete commercial decisions are developed in the full report. For executives seeking to translate market momentum into targeted action, the complete study provides the depth required to plan with confidence.
To access the complete worldwide urethritis drugs market research, including full segmentation detail, competitive benchmarking, and forecast breakdowns, visit the PW Consulting report page for this study.
Worldwide Urethritis Drugs Market
For detailed analysis of this topic, please visit the official page: Worldwide Urethritis Drugs Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: TRIS Buffer Market Size Hits $324.47M in 2025, 6.32% CAGR to $498.29M by 2032
By pmarketresearch, 2026-09-16
Strategic Imperatives in the Global TRIS Buffer Market: Navigating Growth, Regulation, and Supply Chain Resilience Through 2032
The worldwide TRIS buffer market stands at a critical inflection point. As life sciences, biopharmaceutical manufacturing, and diagnostic applications continue to scale, the demand for reliable, high-purity buffering solutions has become a foundational requirement for research and commercial production alike. For executive teams, procurement leaders, and R&D directors, understanding the trajectory of this market is no longer optional. It is a strategic necessity. PW Consulting's latest Worldwide TRIS Buffer Market research report delivers the comprehensive intelligence required to make informed decisions in 2026 and beyond.
This article serves as a preview of the depth and rigor embedded in our full analysis. It outlines the macro-level dynamics, competitive forces, regulatory headwinds, and operational considerations that will shape the market through the forecast period ending in 2032. The complete report, however, contains the granular segmentation, regional breakdowns, application-level revenue splits, and actionable scenario models that decision-makers require. Access the full intelligence to equip your organization with the precision data needed for 2026 planning.
Market Trajectory: Sustained Expansion Anchored by Life Sciences Demand
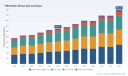
The TRIS buffer market has demonstrated consistent growth over the past half-decade, reflecting the broader expansion of biotechnology, molecular diagnostics, and pharmaceutical development. Our historical analysis captures a market that has moved from a baseline of approximately 238.15 million USD in 2020 to an estimated 324.47 million USD by 2025. This upward trajectory is projected to continue, with the market expected to reach 339.71 million USD in 2026 and accelerate toward 498.29 million USD by 2032.
The compound annual growth rate of 6.32 percent across the 2026 to 2032 forecast window underscores a market that is both mature enough to offer stable returns and dynamic enough to present meaningful opportunities for strategic positioning. Growth is being propelled by several structural drivers: the increasing complexity of nucleic acid analysis workflows, the rising adoption of protein purification in bioprocessing pipelines, and the ongoing expansion of cell culture applications in research and commercial manufacturing.
At the same time, the market is not without its tensions. Capacity constraints, raw material cost volatility, and shifting regulatory frameworks introduce variables that can disrupt pricing stability and supply continuity. Our report dissects these dynamics in detail, providing leaders with the context needed to anticipate disruptions and structure resilient procurement strategies.
Competitive Landscape: A Fractured Ecosystem with Concentrated Influence
The TRIS buffer market is characterized by a diverse array of participants, ranging from global life sciences conglomerates to specialized fine chemical manufacturers and regional producers with significant production capacity. This diversity creates both opportunities and challenges. Buyers benefit from multiple sourcing options, but the lack of uniformity in quality standards, production capabilities, and geographic reach can complicate vendor selection and long-term supply agreements.
Market concentration metrics indicate that the top three players account for a substantial share of total market revenue, while the top five collectively command a majority of the market. This concentration suggests that scale, integrated production, and established distribution networks provide meaningful competitive advantages. Yet, the presence of numerous mid-tier and regional manufacturers ensures that niche applications, custom formulations, and price-sensitive segments remain highly contested.
Several key companies illustrate the breadth of strategies currently shaping the market. Advancion Corporation, operating as the world's only fully integrated manufacturer of TRIS AMINO and TRIS HCl buffers, has built a dual-site production footprint spanning the United States and Germany. Its ISO 9001:2015-certified operations deliver Standard, ACS, and advanced crystal grades tailored for bioprocessing and life sciences. In recent months, Advancion has moved aggressively to strengthen its supply chain position, expanding U.S. manufacturing capabilities at its Sterlington, Louisiana facility with the commercial launch of MOPS buffer production, and broadening its North American distribution agreement for TRIS AMINO buffers and related life science ingredients.
Hopax Fine Chemicals, based in Taiwan, supplies TRIS and TRIS HCl buffers at purity levels of 99 percent or higher, with analytical testing for DNase, RNase, protease, and heavy metals. Its focus on bulk quantities for cell culture media, diagnostic tests, and biochemical applications positions it as a relevant supplier for customers prioritizing tested purity at scale. Suzhou Yacoo Science Co., Ltd. and Jiangsu Tianjiayi Chemical Co., Ltd. represent the significant production capacity emanating from China, with Yacoo specifically emphasizing high-purity grades for life science and research use. Desheng, also based in China, has built a global customer base for TRIS base biological buffers.
On the global supplier side, Merck KGaA (Sigma-Aldrich) offers an extensive range of TRIS base, TRIS HCl, and pre-made buffer solutions for electrophoresis, chromatography, ELISA, and molecular biology. Thermo Fisher Scientific supplies TRIS buffers and solutions, including 1.0M formulations at various pH levels, supporting nucleic acid and protein stabilization in research and bioprocessing. Avantor provides TRIS buffers and solutions through its VWR and J.T.Baker brands, targeting life science, biopharma, and laboratory applications. Bio-Rad Laboratories, Boston BioProducts, Promega Corporation, and FUJIFILM Wako Pure Chemical Corporation each contribute specialized offerings, from cGMP-quality custom buffers to research-grade reagents for electrophoresis and molecular biology workflows.
Understanding the strategic positioning, capability gaps, and recent moves of these players is essential for competitive sourcing, partnership evaluation, and market entry planning. Our full report provides detailed company profiles, capability comparisons, and an analysis of how recent developments are reshaping the competitive hierarchy.
Regulatory and Supply Chain Headwinds: Navigating a Complex Environment
The TRIS buffer market operates within an evolving regulatory and trade environment that demands close attention. In April 2026, Advancion Corporation filed antidumping and countervailing duty petitions on Tris (hydroxymethyl)aminomethane and Tris HCl from China, alleging dumping margins of up to 965.62 percent. The petitions cover all grades, purities, and forms, and the potential tariffs could significantly impact imports into the United States. For buyers with exposure to Chinese-sourced TRIS products, this development introduces a new layer of uncertainty that must be factored into sourcing strategies, inventory planning, and cost modeling.
Beyond trade policy, raw material dynamics are exerting pressure on production and pricing. Industry data indicates that global production capacity for tris(hydroxymethyl)aminomethane reached approximately 25,000 metric tons in 2023, with actual consumption estimated at 22,400 metric tons. Biological-buffer applications account for a substantial portion of total usage, reflecting the centrality of TRIS to life sciences workflows. However, approximately 28.7 percent of producers report that raw material cost fluctuations are a significant factor limiting production and pricing stability. This volatility can cascade through the value chain, affecting lead times, contract pricing, and the feasibility of long-term supply agreements.
Quality standards further complicate the landscape. TRIS and TRIS HCl products are primarily supplied for research use, bioprocessing, diagnostics, and pharmaceutical intermediates, and they are subject to quality standards such as ACS, ISO 9001:2015, and multicompendial cGMP grades depending on the application. Buyers must therefore align supplier capabilities with end-use requirements, ensuring that purity, testing protocols, and documentation meet the demands of their specific workflows. Our report provides a structured framework for evaluating these requirements across applications and regulatory contexts.
Report Contents: Actionable Intelligence for 2026 Decision-Making
The full Worldwide TRIS Buffer Market report is designed to translate macro-level trends into operational guidance. It moves beyond high-level summaries to deliver the specific insights that procurement teams, R&D leaders, and strategy professionals need to act with confidence. Below is an overview of the core components included in the analysis.
Comprehensive Market Sizing and Forecast Modeling
The report provides historical market sizing from 2020 through 2025, establishing a verified baseline for trend analysis, and extends into a detailed forecast through 2032. Revenue projections are presented in USD millions, enabling direct integration into financial models and budgeting processes. The forecast methodology accounts for demand drivers, capacity constraints, and regulatory variables, offering a range of scenarios that help leaders stress-test their assumptions.
Segmentation Analysis Across Demand Drivers
While the full report contains detailed segmentation data, it is structured around the key dimensions that matter most to buyers and strategists. Analysis covers demand patterns by purity grade, distinguishing between biological-grade and industrial-grade applications, and examines how usage varies across major application areas including nucleic acid analysis, protein purification, cell culture, and biopharmaceutical manufacturing. Regional breakdowns are also provided, mapping demand and supply dynamics across North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa. Each segmentation is analyzed not only in terms of current value but also in terms of growth trajectory, competitive intensity, and strategic relevance.
Competitive Intelligence and Company Profiles
The report includes in-depth profiles of the key companies shaping the market. Each profile examines production capabilities, product portfolios, quality certifications, geographic reach, and recent strategic moves. The analysis is supplemented by a review of recent industry developments, including capacity expansions, distribution agreements, and product launches that signal shifting competitive dynamics. This section is intended to help buyers evaluate vendor reliability, compare alternatives, and identify potential partnership or sourcing opportunities.
Regulatory, Trade, and Raw Material Dynamics
Given the potential impact of trade policy and input cost volatility, the report dedicates significant attention to regulatory and supply chain factors. This includes an analysis of the implications of antidumping and countervailing duty petitions, the status of raw material cost fluctuations, and the quality standards that govern product selection across different applications. The report also contextualizes these factors within broader industry trends, helping leaders anticipate how policy changes and input market conditions may affect availability and pricing.
Worldwide TRIS Buffer Market
Bio Pharma Buffer Market
Strategic Recommendations and Scenario Planning
Beyond descriptive analysis, the report offers actionable guidance for navigating the market. This includes recommendations for sourcing strategy, risk mitigation, supplier evaluation, and capacity planning. Scenario-based discussions help leaders consider how different regulatory outcomes, cost environments, and demand shifts could affect their operations, enabling more robust decision-making in an uncertain landscape.
Why the Full Report Matters for 2026 Strategy
The macroeconomic trends and competitive dynamics outlined in this preview illustrate a market that is growing steadily but is also subject to significant variables that can disrupt planning. The antidumping petitions targeting Chinese-origin TRIS products, the reported raw material cost pressures affecting nearly a third of producers, and the capacity expansions underway at key manufacturing sites all signal that the market is in flux. For organizations that rely on TRIS buffers for research, bioprocessing, diagnostics, or manufacturing, these variables carry real consequences for cost, continuity, and compliance.
Partial information is insufficient for making high-stakes decisions. Leaders need detailed segmentation data to understand where growth is concentrated, regional analysis to identify supply risks and opportunities, company-level intelligence to evaluate vendors and track competitive moves, and scenario models to prepare for multiple futures. The full Worldwide TRIS Buffer Market report delivers this depth, providing the intelligence required to structure procurement strategies, evaluate market entry or expansion opportunities, and align R&D and production planning with realistic demand forecasts.
The base year of 2025 and the forecast window extending to 2032 position this research as a timely resource for 2026 planning cycles. Whether your organization is optimizing its supplier base, assessing the impact of trade policy on sourcing costs, or evaluating the growth potential of specific application segments, the complete report offers the structured, data-driven insight needed to move forward with confidence.
To access the full analysis, including detailed segmentation figures, regional breakdowns, competitive profiles, and scenario models, visit the source page for the Worldwide TRIS Buffer Market report. Equip your team with the intelligence required to navigate this evolving market and make strategic decisions that support long-term resilience and growth.
For detailed analysis of this topic, please visit the official page: Worldwide TRIS Buffer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Plastic Bracket Market to Grow at 5.82% CAGR to $369.37M by 2032
By pmarketresearch, 2026-09-16
Strategic Intelligence for 2026: Navigating the Global Motorcycle Headlight Bracket Market
The motorcycle component ecosystem is undergoing a period of structural transformation. As manufacturers and aftermarket suppliers alike recalibrate their product portfolios, the headlight bracket segment has emerged as a critical nexus of engineering precision, regulatory compliance, and consumer customization. Our latest market research offers a comprehensive, data-driven blueprint of the Worldwide Motorcycle Headlight Bracket Market, designed specifically to equip executive teams with the foresight required for 2026 decision-making. This analysis moves beyond surface-level trends to dissect the mechanical, economic, and competitive forces that will shape revenue trajectories through the end of the decade.
Macro Trajectory: A Baseline of Sustained Expansion
The market has demonstrated resilient upward momentum across the historical review window. From a baseline of approximately 185.3 million USD in 2020, revenue progression has accelerated steadily, crossing the 220 million USD threshold by 2023 and reaching an estimated 248.6 million USD by the 2025 base year. Forward projections indicate continued growth, with the market expected to expand to 268.76 million USD in 2026 before ascending toward a peak valuation of roughly 370.41 million USD by 2031. The forecast period through 2032 reflects a compound annual growth rate of 5.82 percent, signaling a mature yet dynamically expanding sector that rewards manufacturers and distributors who align their strategies with underlying demand drivers.
This trajectory is not merely a function of unit sales growth. It reflects deeper structural shifts: the integration of advanced lighting architectures, the proliferation of custom and semi-custom motorcycle builds, and the ongoing migration toward lightweight, corrosion-resistant mounting solutions. For strategic planners, these numbers provide a quantitative anchor. Yet the real strategic value lies in understanding what forces are compressing or expanding margins, how material science is reshaping product specifications, and which distribution channels will capture disproportionate value as the market matures.
Market Architecture: Material, Channel, and Application Dimensions
The competitive landscape is fundamentally shaped by how manufacturers segment their offerings across material specifications, sales channels, and motorcycle classifications. Aluminum alloy has firmly established itself as the dominant structural material for headlight brackets, driven by its favorable strength-to-weight ratio, inherent corrosion resistance, and compatibility with precision machining processes. Steel continues to occupy specific durability-focused applications, while stainless steel and carbon fiber composites serve niche performance and aesthetic segments. The interplay between material cost volatility, particularly in aluminum markets, introduces a critical variable for production cost modeling and pricing architecture.
Worldwide Automotive Bracket Market
Distribution dynamics further complicate the landscape. The OEM channel maintains a substantial footprint, anchored by original equipment suppliers who integrate headlight mounting solutions directly into factory assembly lines. Simultaneously, the aftermarket segment is expanding rapidly, fueled by the rise of custom motorcycle culture, the increasing popularity of electric two-wheelers requiring adapted lighting configurations, and consumer demand for CNC-machined, adjustable mounting platforms. This bifurcation between factory-integrated and post-purchase modification channels creates distinct opportunity zones for suppliers capable of serving both volume-driven production environments and high-mix, low-volume customization workflows.
Application segmentation reveals additional layers of complexity. Standard and commuter motorcycles continue to represent a significant volume base, while cruisers, choppers, sport bikes, and off-road or adventure platforms each impose different geometric, thermal, and load-bearing requirements on bracket designs. Understanding which application segments are expanding fastest, and how mounting geometries are adapting to varying fork diameters and integrated wiring harnesses, is essential for firms developing product roadmaps or evaluating acquisition targets.
Competitive Landscape: A Fragmented Field with Strategic Chokepoints
The market exhibits a moderate degree of concentration, with the top three players collectively commanding a substantial share of total revenue and the top five firms consolidating a broader portion of industry output. This structure indicates a competitive environment where scale, engineering capability, and channel relationships serve as meaningful barriers to entry, even as specialized manufacturers carve out defensible niches through material innovation and regional specialization.
Leading European manufacturers have built reputations around precision engineering and premium material finishes. Italian operations have focused on fork-mounted bracket designs that actively mitigate road-induced vibrations, frequently utilizing brushed aluminum construction to balance aesthetic refinement with functional durability. German suppliers have emphasized individually adjustable premium brackets engineered for common fork diameters, leveraging CNC-machined aluminum to deliver certified quality standards and design-forward configurations. These European capabilities reflect a broader industry emphasis on vibration dampening, aesthetic consistency, and adherence to rigorous quality protocols.
North American manufacturers have pursued a different strategic emphasis, often targeting the custom motorcycle and direct-replacement segments. US-based producers have developed brackets machined from high-grade aluminum alloys specifically for secure fork tube mounting, with design philosophies that minimize installation friction, such as eliminating the need for top clamp removal during retrofitting. Parallel US operations have expanded into LED lighting ecosystems, offering compatible brackets and mounts across major legacy brands while emphasizing durable replacement and conversion solutions for aging fleets.
Asian manufacturing hubs have scaled rapidly by combining precision fabrication with competitive cost structures. Taiwanese operations have introduced standardized and premium CNC aluminum bracket series designed for both auxiliary lighting and primary headlight mounting, emphasizing straightforward installation and long-term durability. Chinese metal fabricators have expanded production of high-strength carbon steel and alternative alloy brackets, while specialized accessory suppliers have broadened their portfolios to capture cross-border distribution channels. These regional capabilities have steadily increased their influence across both OEM supply networks and global aftermarket channels.
Tier-one motorcycle OEMs remain influential anchors within the ecosystem. Major manufacturers supply genuine headlight brackets and relocation kits as original equipment components, establishing baseline specifications that aftermarket innovators must navigate. Premium OEMs continue to release updated mounting hardware across refreshed model cycles, reinforcing the importance of technical alignment between factory designs and aftermarket adaptation kits. The interplay between OEM specification control and aftermarket innovation creates a dynamic tension that rewards firms capable of rapid prototyping, materials engineering, and regulatory-aware design.
Regulatory and Supply Chain Dynamics: Navigating Constraints and Catalysts
Regulatory frameworks have become an increasingly salient factor in bracket design and qualification. In the United States, Federal Motor Vehicle Safety Standard FMVSS 108 specifies requirements for motorcycle headlighting systems, including mounting and performance criteria that indirectly shape bracket geometry, durability expectations, and attachment methodologies. Stringent safety standards across multiple jurisdictions mandate the use of high-quality, durable brackets that satisfy specific mounting integrity and impact-resistance criteria. Compliance is no longer a peripheral concern; it is a core engineering parameter that influences material selection, fastening mechanisms, and testing protocols.
Worldwide Motorcycle Headlight Bracket Market
Supply chain volatility introduces an additional strategic layer. Fluctuations in raw material pricing, particularly within aluminum markets, directly impact production cost structures and short-term margin planning. Firms that maintain diversified sourcing strategies, implement forward-contracting Discipline, or invest in lightweight design optimization are better positioned to absorb commodity volatility without compromising competitive pricing. The intersection of material science, manufacturing efficiency, and regulatory compliance creates a multi-variable optimization challenge that separates reactive operators from strategically agile manufacturers.
What the Full Report Delivers: Operational Intelligence for Executive Teams
This market research publication is structured to translate macro trends into actionable strategic inputs. The report provides a detailed segmentation framework that maps revenue distribution across material categories, sales channels, and motorcycle applications, enabling readers to identify high-growth subsegments without relying on generalized market narratives. Regional performance is assessed through a comparative lens that highlights leading demand centers, supply base maturity, and growth acceleration patterns, offering a geographic roadmap for capacity planning, distribution expansion, and partnership evaluation.
Competitive profiling extends beyond basic company descriptions to examine positioning strategies, material and manufacturing capabilities, product architecture philosophies, and channel orientations. Profiles covering Italian, German, US, Taiwanese, Chinese, and French operations, alongside tier-one OEM participants, provide a panoramic view of how incumbents are competing on quality certification, customization flexibility, installation efficiency, and aftermarket support. This multi-dimensional competitor mapping allows strategy teams to benchmark their own capabilities, identify white-space opportunities, and anticipate competitive responses as the market consolidates around quality and engineering differentiation.
The research also integrates regulatory context and supply chain dynamics into a unified market dynamics assessment. Readers gain clarity on how safety standards shape design requirements, how raw material price movements influence cost structures, and how the expanding aftermarket ecosystem interacts with OEM specification cycles. This synthesis is particularly valuable for product managers evaluating new bracket architectures, procurement teams modeling input cost scenarios, and commercial leaders assessing channel mix strategies across OEM and aftermarket segments.
Importantly, the full report preserves analytical depth while protecting proprietary segmentation figures and region-specific revenue allocations. This deliberate structure ensures that the intelligence remains decision-ready and commercially sensitive, encouraging stakeholders to engage with the complete dataset for precise forecasting, scenario modeling, and investment justification.
Strategic Imperatives for 2026 Decision-Making
As the market advances toward its projected mid-decade expansion, several strategic imperatives become evident. Firms should prioritize engineering investments that reduce dependency on volatile commodity inputs while maintaining structural integrity and aesthetic quality. Expanding compatibility across common fork diameters and streamlining installation procedures will continue to differentiate aftermarket suppliers in an increasingly crowded field. OEM-adjacent players should evaluate how updated factory specifications and LED-integrated lighting architectures may reshape bracket attachment requirements and aftermarket retrofit demand.
Distribution strategy also warrants renewed focus. The coexistence of high-volume OEM supply and customization-driven aftermarket demand creates an opportunity for hybrid commercial models that balance production efficiency with engineering flexibility. Companies that can anticipate regional demand shifts, align material procurement with forecasted growth, and position themselves within both factory supply chains and independent distributor networks will capture disproportionate value as the market matures.
Accessing the Complete Intelligence Framework
This overview establishes the analytical foundation and strategic relevance of the Worldwide Motorcycle Headlight Bracket Market research. The complete report extends far beyond these thematic highlights, providing detailed segmentation data, region-specific growth assessments, competitive capability comparisons, and forward-looking scenario analysis designed for 2026 planning cycles and beyond. For executives, product leaders, and investment teams seeking precise, defensible market intelligence, the full dataset offers the granularity necessary to convert directional insight into executable strategy. We invite stakeholders to access the complete report to unlock the full breadth of segmentation breakdowns, competitive evaluations, and forecast modeling tools that will inform critical decisions in the year ahead.
For detailed analysis of this topic, please visit the official page: Worldwide Motorcycle Headlight Bracket Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Global Enzymes for Biofuels Market Hits $1.89B in 2025, Projected 6.51% CAGR to 2032
By pmarketresearch, 2026-09-16
Navigating the Enzyme-Powered Biofuel Revolution: Strategic Intelligence for 2026 Decision Makers
The global transition toward low-carbon energy systems has placed industrial enzymes at the center of biofuel production economics. For executives, investors, and strategy teams operating in the renewable fuels space, understanding the trajectory of enzyme demand is no longer optional. It is a core input for capital allocation, supply chain design, and technology roadmapping. This article introduces our latest Worldwide Enzymes for Biofuels Market research, a comprehensive analysis engineered to translate macroeconomic trends, competitive shifts, and regulatory developments into actionable intelligence for 2026 and beyond.
Between 2020 and 2025, the market demonstrated steady expansion, reflecting the compounding effects of policy mandates, feedstock flexibility requirements, and process optimization needs across ethanol and biodiesel manufacturing. The historical trajectory shows consistent growth from approximately 1,380 million USD to roughly 1,885 million USD by the 2025 base year. Looking forward, our forecast modeling projects the market to reach nearly 1,949 million USD in 2026, climbing steadily toward 2,932 million USD by 2032. This expansion corresponds to a compound annual growth rate of approximately 6.51 percent over the 2026 to 2032 forecast period. These macro indicators are not abstract statistics. They represent shifting procurement patterns, evolving technology adoption curves, and the strategic positioning of enzyme suppliers and biofuel producers worldwide.
What sets our research apart is the deliberate translation of historical and projected revenue streams into operational guidance. Rather than presenting raw tables, we contextualize each figure within production economics, regional manufacturing footprints, and application-specific demand drivers. The analysis captures how starch-based ethanol continues to anchor total enzyme consumption, while cellulosic ethanol and biodiesel applications grow in strategic importance as regulatory frameworks tighten and feedstock diversification becomes a competitive necessity. By mapping these dynamics, the report equips leadership teams with the clarity needed to evaluate supplier partnerships, assess process upgrade investments, and anticipate demand volatility across the next seven years.
The competitive landscape in industrial enzymes for biofuels is characterized by concentrated market power alongside a diverse set of specialized technology providers. Our research indicates a high degree of market concentration, with the top three players commanding roughly 68.5 percent of total revenue and the top five collectively controlling about 82.3 percent. This structure creates both opportunities and risks for buyers and suppliers alike. Dominant players benefit from scale, established technical service networks, and long-term supply agreements, while also facing margin pressure from feedstock cost exposure and the need to continuously innovate. Smaller and mid-tier enzyme developers, by contrast, often compete through customized formulations, niche feedstock compatibility, or differentiated biocatalyst engineering.
Enzymes For Fuel Ethanol Market
Within this environment, several companies define the strategic contours of the market. Novonesis, based in Bagsværd, Denmark, remains a leading provider of enzymes and yeast solutions tailored to starch-based and fiber-based ethanol production. Its portfolio spans liquefaction, saccharification, and biomass conversion technologies designed to maximize yields while reducing the carbon footprint of biofuel production. DuPont, operating through its Industrial Biosciences and IFF legacy in Wilmington, Delaware, continues to develop enzyme solutions such as Accellerase for lignocellulosic biomass hydrolysis, alongside starch processing enzymes optimized for corn and cellulosic feedstocks. Lallemand Biofuels & Distilled Spirits, headquartered in Montreal, supplies high-performance industrial enzymes for grain processing and ethanol production. Its strategic acquisition of BASF's bioenergy enzymes business in June 2024, including the Spartec product portfolio and related development technologies for fuel ethanol, significantly expanded its capabilities and competitive positioning in bioethanol fuel and co-product yield optimization.
Other key participants shape the market through specialized roles. AB Enzymes GmbH, based in Darmstadt, Germany, specializes in industrial enzymes for starch and biomass conversion in ethanol production. DSM-Firmenich, with operations across the Netherlands and Switzerland, contributes enzymes for both lignocellulosic ethanol and starch-based processes, reflecting a broader biosolutions strategy for bioenergy. Advanced Enzyme Technologies Ltd. in Thane, India, offers carbohydrases and related enzymes used in bioethanol manufacturing from both starch and lignocellulosic sources. Iogen Corporation, located in Ottawa, Canada, develops cellulase and hemicellulase enzymes for cellulosic ethanol and advanced biofuel production from biomass. TransBioDiesel Ltd., based in Israel, focuses on lipase enzymes for enzymatic biodiesel production via transesterification, offering alternatives to conventional chemical catalysts. Enzyme Supplies Limited in the United Kingdom provides customized enzyme formulations for first and second generation biofuel feedstocks, including maize, sugar beet, and lignocellulosic materials. Codexis, Inc., in Redwood City, California, focuses on engineered enzymes for biomass-to-sugars conversion, improving cellulases and other biocatalysts for ethanol production. Amano Enzyme Inc., headquartered in Nagoya, Japan, supplies lipases and other enzymes applicable to biodiesel and bioethanol processes. Agrivida Inc., based in the United States, develops enzyme technologies integrated into feedstocks or processes to enhance ethanol yields from biomass. Together, these companies illustrate a competitive ecosystem where scale, technical specialization, and feedstock adaptability determine long-term relevance.
Beyond company profiles, our report integrates a rigorous examination of market dynamics that directly influence procurement, pricing, and planning. Enzymatic production itself depends heavily on fermentation feedstocks such as glucose derived from corn or other starches. Raw material costs typically account for a substantial portion of total manufacturing expenses, which means that fluctuations in agricultural commodity prices can cascade into enzyme pricing and availability. Competing demand from food and biofuel sectors amplifies this sensitivity, making feedstock cost monitoring an essential input for enzyme procurement strategies. Our analysis contextualizes these cost structures within broader volatility patterns, helping buyers and suppliers anticipate margin shifts and negotiate more effectively.
Regulatory developments further reshape the demand environment. The U.S. Environmental Protection Agency's establishment of Renewable Fuel Standard volume requirements for 2026 and 2027, including adjustments to cellulosic biofuel volumes, supports continued demand for enzymes in advanced biofuel production. At the same time, global policy targets for biofuel blending and decarbonization accelerate the adoption of cellulases and other enzymes for lignocellulosic ethanol, as producers seek to meet renewable energy mandates while managing feedstock flexibility. These regulatory signals are not uniform across regions, but they collectively reinforce the strategic relevance of enzyme-enabled process efficiency, yield optimization, and advanced biofuel pathway development. Our report maps these policy drivers to regional and application-level implications, giving decision makers a clearer view of where sustained demand is likely to emerge and where regulatory uncertainty may create planning challenges.
The practical value of this research lies in its operational depth. The Worldwide Enzymes for Biofuels Market report is structured to support multiple decision-making functions within an organization. It begins with a detailed market sizing and forecasting framework that connects historical performance to forward-looking scenarios, enabling leadership to benchmark internal expectations against external realities. The segmentation analysis examines enzyme types, applications, and regional markets in a way that reveals demand patterns without exposing the sensitive micro-level splits that often shape competitive negotiations. Instead, the report focuses on the strategic logic behind each segment's growth trajectory, including the relative prominence of starch-based bioethanol, the expanding role of cellulosic bioethanol, and the distinct economics of biodiesel enzyme applications.
A dedicated competitive landscape section profiles the major players and recent corporate developments, providing context for supplier evaluation, partnership strategy, and market entry or expansion planning. The analysis of Lallemand's acquisition of BASF's bioenergy enzymes business is one example of how the report translates corporate events into strategic implications, helping readers understand how portfolios, technical capabilities, and regional coverage are evolving in real time. In addition, the report incorporates raw material dynamics, cost structure considerations, and regulatory influences into a unified market narrative. This integrated approach allows executives to assess not just where the market is heading, but why, and what operational levers can be adjusted in response.
For 2026 planning, the report offers particular value in several areas. First, it supports supplier and technology selection by comparing the capabilities and strategic positioning of leading enzyme providers, including those focused on starch conversion, biomass hydrolysis, and enzymatic biodiesel processes. Second, it informs capacity and investment decisions by aligning forecast growth with application-specific demand drivers and regulatory timelines. Third, it strengthens procurement and risk management by highlighting the sensitivity of enzyme manufacturing costs to agricultural feedstock fluctuations and by identifying how policy shifts can alter demand patterns across advanced biofuel pathways. Fourth, it provides a structured view of market concentration and competitive dynamics, helping organizations anticipate supplier power, pricing behavior, and potential consolidation trends.
The research also addresses a critical question for biofuel producers and enzyme manufacturers alike: how to navigate the transition from established starch-based processes toward more advanced, lignocellulosic, and enzymatically driven pathways. By analyzing both the current revenue base and the forward growth trajectory, the report helps stakeholders evaluate whether to invest in incremental process improvements or to position for higher-growth advanced biofuel enzyme applications. It also clarifies how regional market differences shape supplier entry strategies, technical service requirements, and localization priorities. For investors and corporate development teams, the study provides a disciplined basis for assessing value creation opportunities in a market where scale, feedstock economics, and regulatory alignment all matter.
Worldwide Enzymes for Biofuels Market
Ultimately, the Worldwide Enzymes for Biofuels Market study is designed to convert complexity into clarity. The industry's growth is real, but its value is unevenly distributed across enzyme types, applications, regions, and competitive positions. Capturing that value requires more than top-line forecasts. It requires an integrated view of cost structures, technological differentiation, regulatory direction, and corporate strategy. Our report delivers that view, providing executives with the intelligence needed to make informed decisions in 2026 and to build resilient strategies through 2032.
For teams that need the complete dataset, detailed segmentations, and the full competitive intelligence package, the full research is available through our official report page. The published version expands on every dimension discussed here, offering the granular detail required for procurement planning, market entry analysis, supplier benchmarking, and long-range strategic forecasting. If your 2026 decisions depend on understanding where enzyme demand is heading, how competitors are repositioning, and which regulatory and feedstock dynamics will shape profitability, this research provides the foundation for those choices.
Access the Complete Market Intelligence
To obtain the full scope of analysis, including comprehensive market sizing, forecast scenarios, detailed segmentation context, and the complete competitive landscape profiles, please visit the official Worldwide Enzymes for Biofuels Market research page. The complete report is structured for immediate application in strategic planning, supplier evaluation, investment review, and regulatory response planning, enabling your organization to move from insight to action with confidence.
For detailed analysis of this topic, please visit the official page: Worldwide Enzymes for Biofuels Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Embedded Hypervisor Market Hits $565M in 2025, Poised for 7.5% CAGR Growth
By pmarketresearch, 2026-09-16
Strategic Imperatives in the Embedded Hypervisor Landscape: A 2026 Outlook
As embedded systems grow increasingly complex, the demand for robust virtualization solutions has moved from niche experimentation to core architectural necessity. The Worldwide Embedded Hypervisor Software Market stands at a critical inflection point, driven by the convergence of automotive electrification, industrial IoT expansion, and stringent safety regulations across aerospace and defense sectors. For enterprise leaders navigating 2026, understanding the trajectory of this market is not merely an academic exercise but a strategic imperative for supply chain planning, technology investment, and competitive positioning. This analysis draws upon comprehensive market intelligence to outline the structural forces shaping the industry, while highlighting the operational value embedded within our latest Worldwide Embedded Hypervisor Software Market research report.
The market has demonstrated consistent momentum over the past half-decade, evolving from a foundational phase into a growth-driven ecosystem. Historical data from 2020 through 2025 reveals a steady climb in global revenue, reflecting the gradual adoption of virtualization across safety-critical and mission-critical domains. As we project forward into the 2026 to 2032 forecast period, the trajectory indicates sustained expansion, underpinned by architectural shifts toward multi-OS environments, hardware-assisted partitioning, and the increasing requirement to isolate mixed-criticality workloads on shared silicon. The compound annual growth rate observed across the forecast horizon signals a market that is maturing yet still expanding, offering both opportunity and risk for stakeholders who must align their strategies with precise market realities.
Market Evolution and Structural Growth Drivers
The embedded hypervisor software space has transitioned from supporting isolated development boards to becoming integral to production-grade systems where downtime, safety certification, and deterministic real-time performance are non-negotiable. Early adoption was largely confined to research environments and select aerospace programs, but the past several years have seen industrialization of hypervisor platforms that meet rigorous certification standards. This maturation has been enabled by concurrent advancements in silicon architecture, particularly the integration of virtualization extensions within ARM Cortex cores and x86 platforms, which provide the hardware fidelity required for efficient Type 1 partitioning without compromising latency budgets.
Several macroeconomic and sector-specific forces are compressing the timeline for hypervisor adoption. In automotive, the proliferation of domain controllers and zonal architectures demands that multiple operating environments coexist on a single SoC, from real-time control stacks to infotainment and advanced driver-assistance systems. Industrial automation is similarly pushing toward consolidated edge nodes that must run deterministic control loops alongside higher-level analytics and connectivity stacks. Meanwhile, aerospace and defense programs continue to rely on partitioning solutions that enforce strict fault containment and compliance with avionics standards. The combined effect of these trends is a broad-based pull for hypervisor software that can deliver certified isolation, deterministic scheduling, and long-term supplier support.
Desktop Hypervisor Market
Segmentation Dynamics: Types, Applications, and Regional Distribution
The market structure reflects a clear preference for native embedded virtualization architectures. Type 1 hypervisors, which operate directly on hardware to provide deterministic isolation, dominate the revenue landscape, reflecting their alignment with safety-critical and real-time use cases. Type 2 hypervisors, while valuable in development and general-purpose scenarios, face inherent limitations in hard real-time contexts due to host operating system scheduling overhead, making them less suitable for applications where sub-millisecond latency and predictable behavior are mandatory. This architectural divide informs procurement strategies, as engineering teams must evaluate not only feature sets but also certification pedigrees and hardware compatibility when selecting a virtualization layer.
Application demand is distributed across multiple verticals, each with distinct performance, certification, and lifecycle requirements. Automotive represents a substantial share of market activity, fueled by the need to virtualize electronic control units and consolidate mixed-criticality functions. Industrial automation follows closely, driven by the modernization of factory floors and the integration of edge computing into motion control and robotics. Aerospace and defense maintain a strong presence, supported by long program cycles and the requirement for avionics partitioning that meets rigorous certification frameworks. Consumer electronics, healthcare, and medical devices contribute additional demand, particularly where regulatory compliance and data isolation intersect with embedded system design. Regionally, the market is balanced among major economic zones, with North America, Europe, and Asia Pacific forming the core of revenue generation, while Latin America and the Middle East and Africa represent emerging footholds that are gradually expanding as local industrial and automotive programs mature.
Worldwide Embedded Hypervisor Software Market
Competitive Landscape: Incumbents and Strategic Positioning
The competitive environment is characterized by specialized vendors with deep domain expertise in safety certification, real-time performance, and long-term support commitments. Market concentration data indicates that leading participants command a significant share of global revenue, reflecting the high barriers to entry created by certification costs, architectural expertise, and established customer relationships. Incumbents have built their positions on platforms that span multiple industries, while others focus narrowly on specific certification regimes or hardware ecosystems to differentiate their offerings.
Wind River remains a prominent force with its VxWorks 653 hypervisor, which is engineered for safety-critical embedded systems and carries certifications relevant to aerospace, defense, and automotive applications. Its recent expansion to support newer processor architectures underscores the vendor's focus on future-proofing safety-critical deployments. Green Hills Software competes with real-time hypervisors that emphasize ARINC 653 partitioning, serving avionics and industrial programs that require deterministic behavior and robust fault containment. Lynx Software Technologies provides a separation kernel approach designed for defense, aerospace, and automotive environments, with strong alignment to multi-level security partitioning principles. SYSGO’s PikeOS platform is widely recognized for its multi-certification breadth, covering avionics, automotive, and industrial safety standards, and continues to extend its footprint into medical applications where stringent software lifecycle requirements apply.
Real-Time Systems GmbH delivers virtualization solutions optimized for ARM and x86 platforms, targeting automotive and industrial IoT deployments that require real-time partitioning and hardware flexibility. BlackBerry QNX brings its reputation in real-time operating systems to the hypervisor space, offering Type 1 virtualization with safety certifications suited to automotive and medical use cases, and has extended its platform to support advanced edge computing accelerators. Mentor Graphics, now part of Siemens EDA, contributes tooling and virtualization assets that complement embedded development workflows in automotive and aerospace programs. ETAS, within the Bosch Group, addresses automotive electronic control unit consolidation with solutions that support AUTOSAR and functional safety requirements, reflecting the industry's push toward integrated multi-OS ECUs.
Recent product and partnership activity illustrates how vendors are adapting to hardware evolution and certification demands. One major vendor advanced its safety-critical hypervisor to support emerging processor architectures, reinforcing its position in next-generation avionics and automotive programs. Another achieved a notable medical certification milestone, broadening the addressable market for embedded virtualization in regulated healthcare devices. Strategic partnerships with semiconductor suppliers have also accelerated, enabling tighter integration between hypervisor platforms and silicon featuring virtualization extensions, which reduces integration risk for customers building industrial and automotive systems. In parallel, expanded support for high-performance edge accelerators has opened new deployment pathways in automotive edge computing, where inference workloads and real-time control must coexist on consolidated hardware.
Regulatory and Technical Forces Shaping Demand
Regulatory frameworks continue to act as both a gatekeeper and a growth catalyst. In avionics, certification standards mandate rigorous partitioning and verification for commercial aircraft systems, compelling suppliers to invest in compliant hypervisor architectures and long-term support commitments. In automotive, functional safety requirements dictate that electronic control units handling mixed-criticality workloads must demonstrate deterministic isolation and fault containment, which in turn drives adoption of certified hypervisors that can separate safety-related functions from infotainment or connectivity stacks. Standardization efforts further reinforce these expectations by defining time and space partitioning interfaces that enable interoperability and predictable behavior across guest operating environments.
Technical constraints also shape procurement and architecture decisions. Efficient Type 1 partitioning depends on silicon that provides virtualization extensions and predictable interrupt handling, meaning that hardware selection and hypervisor choice are increasingly made in tandem. Development teams must account for scheduling latency, memory isolation, and I/O virtualization performance when evaluating solutions, particularly in applications where hard real-time guarantees are essential. These technical realities reinforce the preference for platforms with proven certification records and robust hardware compatibility matrices, as the cost of late-stage integration issues can far exceed the upfront investment in a well-matched virtualization stack.
Strategic Value of the Research for 2026 Decision-Making
For executives and technical leaders planning 2026 initiatives, the value of detailed market intelligence lies in its ability to convert broad trends into actionable decision support. The Worldwide Embedded Hypervisor Software Market report provides a structured foundation for assessing demand durability, competitive intensity, and technology alignment across verticals and regions. It enables organizations to benchmark their product roadmaps against market momentum, identify segments where certification and hardware compatibility create durable moats, and evaluate partnership or acquisition targets with greater precision. Procurement and supply chain teams can use the research to anticipate vendor concentration risks, assess long-term support viability, and align sourcing strategies with program timelines that span multiple years. Engineering leaders can leverage the analysis to prioritize architecture choices, validate hypervisor selections against certification pathways, and reduce integration risk by understanding which platforms are gaining traction in specific application domains.
Beyond strategic planning, the report offers operational utility through detailed segmentation analysis, competitive profiling, and scenario-based forecasting. Readers gain access to structured evaluations of vendor capabilities, release cadences, certification statuses, and partnership ecosystems, all contextualized within the broader market trajectory. The inclusion of recent developments helps organizations track how incumbents and challengers are responding to hardware transitions and regulatory shifts, while the segmentation and concentration data illuminate where market power is accumulating and where entry opportunities may still exist. This combination of macro-level forecasting and granular competitive intelligence is designed to support decisions ranging from portfolio prioritization to regional expansion and technology adoption timing.
Organizations that integrate this intelligence into their planning cycles are better positioned to navigate the trade-offs between performance, certification, and cost that define embedded virtualization procurement. By understanding how application demand, regional dynamics, and vendor strategies intersect, leaders can construct roadmaps that align with both near-term program requirements and long-term market evolution. The report serves as a decision-grade reference for mapping investment priorities, reducing uncertainty in vendor selection, and anticipating the regulatory and technical hurdles that will shape deployment success in the coming years.
Conclusion: Positioning for the Next Phase of Embedded Virtualization
The Worldwide Embedded Hypervisor Software Market is entering a phase where growth is increasingly tied to certified, deterministic, and hardware-aligned virtualization platforms. Demand is being shaped by the consolidation of automotive systems, the modernization of industrial automation, and the persistent requirements of aerospace and defense programs, while regulatory frameworks and silicon capabilities continue to define what is commercially viable. Market concentration among established vendors reflects the engineering and certification burdens inherent to this space, but also signals the strategic importance of selecting partners with the right pedigree, roadmap, and support commitments.
For decision-makers preparing for 2026 and beyond, the opportunity lies in translating market momentum into disciplined strategy. That means aligning technology choices with certification pathways, validating hardware compatibility early, and monitoring competitive moves that indicate where capabilities are headed. The full research report expands on these themes with detailed segmentation data, competitive profiles, and forward-looking forecasts that provide the depth required for executive planning, procurement strategy, and engineering roadmap development. To access the complete market intelligence and supporting analysis, please visit the source page for the Worldwide Embedded Hypervisor Software Market research.
For detailed analysis of this topic, please visit the official page: Worldwide Embedded Hypervisor Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Semiconductor Magnetic Sensor Market to Hit $5,995.97M by 2032, 9.0% CAGR
By pmarketresearch, 2026-09-16
Navigating the Magnetic North: Strategic Imperatives in the Global Semiconductor Sensor Landscape
The semiconductor industry stands at a critical inflection point, where the convergence of electrification, automation, and advanced sensing technologies is redefining value chains across the globe. For enterprise leaders and strategic planners, understanding the trajectory of semiconductor magnetic sensors is no longer optional—it is a prerequisite for capital allocation, supply chain resilience, and product roadmap justification. Our latest comprehensive study, the Worldwide Semiconductor Magnetic Sensor Market analysis, provides the granular intelligence required to navigate this complex environment through 2032.
This report serves as a definitive guide for stakeholders aiming to capitalize on the projected expansion of this vital sector. As industries increasingly rely on precise magnetic field detection for everything from electric vehicle powertrains to industrial robotics, the demand for robust, high-sensitivity sensor solutions is accelerating. The following insights outline the macro-environmental drivers, competitive dynamics, and regulatory headwinds that will shape decision-making in 2026 and beyond.
Macro Market Trajectory and Growth Vectors
The historical data from 2020 through 2025 sets a robust foundation for future projections. Over this period, the market has demonstrated resilient growth, moving from a base of approximately $2.15 billion in 2020 to an estimated $3.28 billion by 2025. This upward trajectory reflects the deepening integration of magnetic sensing technologies into core industrial and consumer processes. However, the forecast period from 2026 to 2032 suggests an acceleration in value creation that outpaces recent historical trends.
Our analysis projects the market to reach significant milestones by the end of the decade, driven by a compound annual growth rate (CAGR) of 9.0%. This growth rate indicates a healthy expansion environment, though it is not without volatility. The forecast values indicate a steady climb, suggesting that demand drivers are structural rather than cyclical. For strategic planners, this implies that investments made in 2026 will likely yield compounding returns as the market matures toward 2032. The revenue projections, denominated in USD millions, highlight a market capable of sustaining high-volume production while accommodating premium pricing for advanced technologies such as Tunnel Magnetoresistance (TMR) and Giant Magnetoresistance (GMR).
It is crucial for stakeholders to recognize that this growth is not uniform across all vectors. The momentum is concentrated in specific technological and application domains that are undergoing rapid transformation. Understanding where this growth concentrates allows organizations to prioritize R&D spending and capacity expansion in high-yield areas while mitigating exposure to slower-growing segments.
Segmentation Dynamics: Technology and Application Convergence
The market structure is defined by a diverse array of sensor technologies, each serving distinct performance requirements. Hall Effect sensors continue to hold a substantial share of the value proposition, particularly in applications requiring cost-effective and reliable detection. However, the landscape is shifting toward higher-sensitivity technologies. Magnetoresistive solutions, including AMR, GMR, and TMR, are gaining traction in scenarios demanding greater precision and stability under varying environmental conditions.
Worldwide Semiconductor Magnetic Sensor Market
Magnetic Field Sensors Market
From an application perspective, the automotive sector remains the dominant force driving revenue. The ongoing transition toward electric vehicles and the integration of advanced driver-assistance systems (ADAS) are creating sustained demand for position, speed, and current sensing. Industrial automation constitutes another significant pillar, where the push for smart manufacturing and predictive maintenance is increasing the deployment of magnetic sensors in robotics and motor control systems. Consumer electronics and medical healthcare sectors represent growing niches, where miniaturization and low-power consumption are key differentiators.
Strategic decisions in 2026 must account for the interplay between these segments. For instance, a technology chosen for automotive safety-critical applications may not be suitable for consumer goods due to cost constraints, yet the underlying IP might be leveraged across both. Our report details these cross-segment opportunities without exposing the specific revenue splits that constitute proprietary intelligence within the full dataset.
Competitive Landscape and Strategic Positioning
The market is characterized by a consolidated competitive environment where established players leverage deep portfolios and vertical integration. The top three companies command a significant portion of the market revenue, indicating high barriers to entry for new competitors. The top five firms further extend this influence, controlling over two-thirds of the market share. This concentration suggests that partnership, acquisition, or licensing strategies may be more viable for smaller entities than direct competition on scale.
Leading entities such as Allegro MicroSystems, Infineon Technologies, and NXP Semiconductors are central to this ecosystem. Allegro has been aggressive in expanding its portfolio, particularly following strategic acquisitions that broadened its TMR and current sensing capabilities. Infineon continues to leverage its XENSIV brand to cover a wide spectrum of sensing technologies for automotive and industrial use. NXP remains focused on automotive-specific solutions, emphasizing ultra-low power and reliability.
In the Asia-Pacific region, Japanese manufacturers like Asahi Kasei Microdevices (AKM) and TDK Corporation are pivotal. TDK's recent introduction of compact TMR angle sensors highlights the industry's move toward higher performance in safety-critical contexts. Similarly, STMicroelectronics and Melexis are pushing the boundaries with 3D magnetic position sensors and multi-sensor reference designs. American giants like Honeywell and Texas Instruments maintain strong positions in industrial and aerospace applications, while specialized players like ABLIC and Tower Semiconductor offer niche capabilities ranging from ZCL detection to GaN-based foundry services.
Recent product launches underscore the pace of innovation. STMicroelectronics launched a new industrial multi-sensor reference design featuring ultra-low-power 3-axis magnetic sensors in late 2025. TDK followed with the TAS8240, a compact TMR angle sensor for safety-critical applications. Allegro MicroSystems made significant waves with the ACS37100, the first commercial 10 MHz TMR magnetic current sensor designed for high-speed wide-bandgap power electronics. These launches indicate a clear trend toward higher frequency response, lower power consumption, and enhanced integration.
Geopolitical and Supply Chain Risk Factors
While demand drivers are strong, supply chain resilience remains a paramount concern for 2026 planning. The geopolitical landscape has introduced new complexities, particularly regarding raw materials essential for high-performance magnetic systems. China's dominance in the refining of heavy rare earth elements, holding over 85% of global capacity and approximately 90% of processed dysprosium and terbium supply, creates a potential bottleneck. These materials are critical for the magnets and systems associated with advanced sensor technologies.
Regulatory actions have further tightened the environment. In late 2024 and early 2025, restrictions were imposed on the export of gallium, germanium, antimony, and certain heavy rare earth elements to the United States. These measures were followed by a foreign direct product rule-style measure in late 2025, requiring licenses for foreign-produced rare earth magnets or semiconductor materials containing significant Chinese-origin heavy rare earth elements. Such regulations necessitate a thorough review of tier-2 and tier-3 supply chain dependencies.
Furthermore, trade policy shifts in the United States, including tariffs on certain advanced computing chips and semiconductor imports implemented in early 2026, add another layer of cost and compliance complexity. Organizations must evaluate whether their sourcing strategies are robust against these regulatory fluctuations. Conversely, there are mitigating factors; global battery pack prices fell significantly in 2024, driven by declines in critical minerals prices. This volatility in input costs can ripple through the sensor supply chain, affecting margins and pricing strategies.
For decision-makers, the implication is clear: strategic sourcing and diversification are no longer just operational tasks but competitive advantages. Reliance on single-source geographies for critical materials poses a tangible risk to production continuity and cost stability. The full report provides a risk matrix that maps these regulatory and material constraints against specific market segments, enabling leaders to model contingency plans.
Proprietary Intelligence and Decision Support
The value of this market research extends beyond high-level trends. The complete study offers actionable granularity that is essential for nuanced strategy formulation. While this overview highlights the macro landscape, the full document contains detailed segmentation analysis that breaks down revenue potential by specific technology types and application verticals without aggregating them into broad categories.
Stakeholders will find detailed profiles of key competitors, including their headquarters, strategic focus areas, and recent developmental milestones. This information allows for benchmarking against peers and identifying potential partnership opportunities. The report also includes a comprehensive examination of regulatory impacts by region, helping organizations anticipate compliance requirements in key markets across Asia Pacific, North America, Europe, Latin America, and the Middle East and Africa.
By accessing the full intelligence package, enterprises can quantify the market opportunity with precision, validate internal forecasts against independent data, and identify white spaces for innovation. The data is structured to support financial modeling, inventory planning, and long-term capacity strategy.
Conclusion: Strategic Readiness for 2026 and Beyond
The Worldwide Semiconductor Magnetic Sensor Market is poised for substantial growth, driven by technological advancement and expanding application bases. However, the path to capturing this value is fraught with competitive intensity and supply chain complexities. Success in 2026 will depend on the ability to interpret macro trends through the lens of specific operational realities.
This report provides the foundational intelligence required to make those interpretations with confidence. By understanding the concentration of market power, the trajectory of technological adoption, and the impact of geopolitical regulations, leaders can position their organizations to not only withstand volatility but to leverage it. We invite you to explore the complete findings to unlock the detailed data necessary for securing your strategic advantage in this evolving landscape.
For detailed analysis of this topic, please visit the official page: Worldwide Semiconductor Magnetic Sensor Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Automotive ISOFIX Mounts Reach $1.05B in 2025, Expanding to $1.6B by 2032 at 6.25% CAGR
By pmarketresearch, 2026-09-16
Strategic Imperatives in the Global Automotive ISOFIX Mounts Market: Navigating Growth and Compliance Through 2032
The automotive safety ecosystem is undergoing a fundamental transformation, driven by rigorous regulatory frameworks and an increasing consumer demand for child passenger safety. At the heart of this evolution lies the ISOFIX mounting system, a standardized attachment mechanism that has become critical for securing child restraint systems within vehicles. For industry stakeholders, understanding the trajectory of the Automotive ISOFIX Mounts Market is not merely an exercise in data analysis; it is a strategic necessity for capital allocation, product development, and supply chain resilience.
Our latest comprehensive study, the Worldwide Automotive ISOFIX Mounts Market research, offers a granular view of this sector. This article serves as a strategic briefing, highlighting the macro-economic drivers and regulatory currents shaping the landscape from 2026 through 2032. While we outline the broad contours of opportunity here, the full depth of segmentation, competitive intelligence, and quantitative forecasts is reserved for our detailed report, designed to equip decision-makers with actionable intelligence.
Market Trajectory and Financial Outlook
The financial narrative of the ISOFIX mounts market reflects a steady upward trend, underpinned by vehicle production growth and mandatory safety installations. Analyzing historical data from 2020 to 2025 provides a baseline for understanding market maturity. In 2020, the global market revenue stood at approximately 785.4 million USD. Over the subsequent five years, the market experienced consistent expansion, reaching 1050.0 million USD by the base year of 2025.
Looking forward, the forecast period from 2026 to 2032 suggests continued momentum, albeit with varying rates of acceleration across different phases. The market is projected to surpass the 1.6 billion USD mark by 2032. This growth trajectory is supported by a Compound Annual Growth Rate (CAGR) of 6.25 percent during the forecast period. Such figures indicate a mature yet expanding market where volume growth is often tied to regulatory mandates in emerging automotive hubs and the replacement cycle in established markets.
It is crucial for strategic planners to note that while the aggregate numbers paint a picture of health, the distribution of this value is heavily influenced by regional manufacturing capabilities and vehicle type segmentation. The shift from historical stability to future expansion requires companies to align their capacity planning with these projected revenue milestones, ensuring that infrastructure investments match the anticipated demand surge in the latter half of the decade.
Regulatory Landscape as a Growth Catalyst
Regulations are the primary engine driving standardization and, consequently, market demand for ISOFIX components. The industry is currently navigating a complex web of international safety standards that dictate design specifications and installation protocols.
UNECE Standards and i-Size Mandates
In Europe and many other jurisdictions, the United Nations Economic Commission for Europe (UNECE) regulations hold significant sway. Within UNECE R129, commonly known as i-Size, ISOFIX is mandatory for the i-Size category. This regulation aims to ensure universal vehicle compatibility and significantly reduce incorrect installations, which have historically been a major safety risk. The mandate creates a compliance-driven demand where vehicle manufacturers must equip cars with standardized anchor points, and child seat producers must design around these fixed points.
Furthermore, the evolution of these standards is ongoing. During the GRSP-77 session in May 2025, there was discussion on the potential evolution of ISOFIX 3.0. Building on 30 years of the standardized attachment system, these discussions signal that the technology is not static. Companies must remain agile to adapt to potential iteration in mounting mechanisms or strength requirements that could arise from these standardization bodies.
NHTSA and Side-Impact Protection
In the United States, the National Highway Traffic Safety Administration (NHTSA) continues to tighten safety requirements. Ongoing implementation preparations for FMVSS 213a, focusing on side-impact protection standards, are affecting child restraint systems that utilize ISOFIX mounts. This standard requires enhanced side-impact testing for child car seats under 40 pounds. The compliance date has been extended to December 5, 2026, which impacts the design and validation of ISOFIX-compatible restraints.
This regulatory update creates a specific pressure point for manufacturers. It is not enough to simply meet anchorage strength requirements; the interaction between the mount and the restraint system must withstand higher lateral forces. Anchorage strength and positioning must meet specific ECE R44/ECE R129 and FMVSS requirements to prevent anchorage failure or seat damage during use. For component suppliers, this means material science and structural integrity testing are becoming more critical than ever before.
Competitive Landscape and Key Players
The market structure is characterized by a moderate level of concentration, with key players holding significant sway over supply chains and technological standards. Our analysis indicates a CR3 of 42.5 percent and a CR5 of 58.8 percent, suggesting that while there are dominant entities, there is still room for specialized manufacturers and regional players to capture value.
The competitive environment is defined by companies that specialize in the precision engineering of safety components. Leading entities include:
- Holmbergs (Sweden): This company specializes in ISOFIX/LATCH connectors, arms, straps, tethers, and adjusters. They supply global child car seat manufacturers, focusing on the secure vehicle anchoring ecosystem. Their strategic position lies in their integration with child seat producers who require high-reliability connectors.
- Ningbo Welldon Infant and Child Safety Technology Co., Ltd. (China): As a manufacturer of ISOFIX mounting points, anchors, and related child safety seat components, Welldon represents the significant manufacturing capacity located in Asia. Their focus on automotive applications makes them a key supplier for vehicle OEMs and tier-one safety component integrators.
- IMMI (United States): IMMI produces ISOFIX anchorages, LATCH attachments, snap hooks, and child seating components. They are notable for their compliance with global safety standards including FMVSS and ECE. Their location in the US positions them strategically to navigate North American regulatory changes such as FMVSS 213a.
- Quanzhou Kwok Shing Automotive Subassembly Co., Ltd. (China): This firm supplies ISOFIX systems and rigid baby car seat components as automotive subassemblies. Their role highlights the trend towards modular subassemblies that can be integrated directly into vehicle production lines or child seat manufacturing processes.
These companies are not merely competing on price; they are competing on certification, reliability, and the ability to adapt to evolving regulatory standards. The interplay between Swedish design specialization, American regulatory compliance expertise, and Chinese manufacturing scale defines the current competitive dynamics. Strategic partnerships between vehicle manufacturers and these component suppliers are essential to ensure that the final assembly meets the rigorous crash load requirements.
Technical Dynamics and Material Considerations
The engineering behind ISOFIX mounts is driven by the need for structural integrity under crash loads. ISOFIX mounts and anchors are primarily constructed from high-strength steel or alloy steel. This material choice is non-negotiable, as the components must withstand significant force without deformation or failure during an accident.
The technical specifications are tightly linked to the regulatory environment. ISOFIX anchorage strength and positioning must meet specific ECE R44/ECE R129 and FMVSS requirements. Any deviation can lead to anchorage failure or seat damage during use, posing severe liability risks for automakers and component suppliers. As vehicle designs evolve towards lighter materials and different chassis structures, the integration of these steel mounts becomes a challenge in itself. Engineers must ensure that the mounting points do not compromise the structural integrity of the vehicle floor or seat rails while still providing the rigid connection required for child safety.
Moreover, the supply chain for these high-strength materials is subject to global commodity fluctuations. Strategic procurement strategies are required to mitigate cost volatility without compromising the quality standards mandated by safety regulations.
Strategic Focus for OEMs and Aftermarket
The market is broadly divided by sales channel, with distinct implications for different business models. The Original Equipment Manufacturer (OEM) channel represents the larger portion of the market revenue. This segment is driven by vehicle production volumes and the mandatory inclusion of ISOFIX points in new car models. For suppliers targeting this segment, long-term contracts and qualification processes with automotive OEMs are critical. The revenue flow here is stable but subject to the cycles of the automotive industry.
Conversely, the Aftermarket segment serves a different need. While smaller in total revenue compared to OEM, it represents a vital channel for retrofitting older vehicles or replacing damaged components. As the fleet of vehicles equipped with ISOFIX grows, the aftermarket demand evolves from installation assistance to replacement parts for wear and tear or post-accident repair. Companies operating in this space must maintain broad compatibility across various vehicle models and generations.
Understanding the split between these channels is vital for revenue forecasting. While the OEM channel drives volume through new car sales, the aftermarket offers recurrent revenue opportunities and niche customization possibilities. A balanced portfolio strategy often involves servicing both streams to mitigate the risk of production slowdowns in the automotive sector.
Regional Growth Vectors
Geographically, the market exhibits distinct characteristics based on vehicle ownership rates and regulatory adoption. Asia Pacific remains a critical region, driven by high vehicle production volumes and increasing awareness of child safety standards. Europe continues to be a mature market where regulations like i-Size drive consistent demand for compliant mounts. North America presents a specific regulatory environment focused on FMVSS compliance and side-impact enhancements.
Latin America and the Middle East and Africa represent emerging vectors where vehicle fleet modernization and the import of safety-standard-compliant vehicles are gradually increasing the uptake of ISOFIX systems. However, the pace of adoption in these regions is influenced by economic factors and the penetration of standardized child restraint systems. Strategic expansion into these regions requires a nuanced understanding of local regulatory enforcement and consumer behavior regarding child safety.
Conclusion: The Value of Detailed Intelligence
The Automotive ISOFIX Mounts Market is at a intersection of regulatory pressure, technological evolution, and steady market growth. The projected increase to over 1.6 billion USD by 2032 offers significant opportunity, but realizing this value requires navigating complex compliance landscapes and supply chain dynamics. The upcoming changes in FMVSS 213a and potential evolutions in UNECE standards mean that static strategies will fail.
Engine Mounts Market
For executives and strategy teams, the high-level trends are clear, but the path to capturing market share lies in the details. Which specific vehicle segments are driving the highest growth rates? How do supply chain vulnerabilities in specific regions impact lead times? What are the precise design constraints imposed by the new side-impact regulations?
Worldwide Automotive ISOFIX Mounts Market
Our full Worldwide Automotive ISOFIX Mounts Market research report delves into these specifics. It provides the segmented data, the competitive profiles, and the granular forecast models necessary to build a robust strategic plan. We invite you to access the complete study to unlock the full depth of this intelligence and ensure your organization is positioned to lead in the next era of automotive safety.
For detailed analysis of this topic, please visit the official page: Worldwide Automotive ISOFIX Mounts Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Copaiba Oil Market Hits $148.5M in 2025, Projects 7.2% CAGR to $241.6M by 2032
By pmarketresearch, 2026-09-16
Strategic Horizons: Navigating the Global Copaiba Essential Oil Market Through 2032
The global essential oils sector stands at a critical inflection point, where botanical versatility meets escalating demand for clean, sustainable ingredients across wellness, cosmetic, and pharmaceutical verticals. Within this complex landscape, Copaiba essential oil has emerged as a compelling asset class, driven by its unique chemical profile, traditional therapeutic applications, and growing integration into modern consumer products. As industry participants prepare for the next cycle of growth, understanding the macroeconomic trajectory, competitive architecture, and regulatory undercurrents of this niche market is no longer optional—it is a strategic imperative.
Our latest Worldwide Copaiba Essential Oil Market research provides a rigorous, data-driven framework for stakeholders aiming to capitalize on the projected expansion through 2032. This overview outlines the market's historical momentum, near-term catalyst landscape, competitive positioning, and the analytical depth embedded in our full report. The objective is to equip executives, procurement leaders, and product developers with the contextual intelligence required to make informed, forward-looking decisions in an increasingly fragmented and sustainability-centric value chain.
Worldwide Copaiba Essential Oil Market
Historical Trajectory and Forecasted Growth Dynamics
Between 2020 and 2025, the global Copaiba essential oil market established a firm foundation through expanding consumer awareness, innovative extraction methodologies, and the formalization of sustainable sourcing protocols across key origin regions. The base year assessment reflects a market that has matured beyond early-stage experimentation into a structured commercial ecosystem. Steady year-over-year valuation increases during this historical window underscore the product's successful migration from niche herbal applications into mainstream cosmetic formulations, wellness supplements, and specialty fragrance compounds.
Moving into the forecast horizon of 2026 through 2032, the market is projected to sustain a compound annual growth rate of 7.2%. This trajectory signals more than incremental expansion; it indicates structural demand acceleration driven by formulation innovation, cross-industry adoption, and the premiumization of botanical ingredients. The valuation progression from the 2026 baseline through to the terminal forecast year reflects a compounding effect of new market entrants, geographic diversification, and the monetization of clinically backed or sustainably certified product variants. Stakeholders who align their supply chain resilience, brand positioning, and R&D investments with this forecasted cadence are positioned to capture disproportionate share during the growth window.
The underlying demand architecture continues to be shaped by an interplay of end-use breadth and quality differentiation. As manufacturers seek ingredients that simultaneously satisfy sensory expectations, stability requirements, and clean-label mandates, Copaiba's dual utility as both a functional botanical and an aromatic carrier positions it advantageously. The market's evolution will increasingly reward players who can articulate clear value propositions across therapeutic, cosmetic, and industrial gradations while maintaining supply integrity and regulatory compliance.
Value Chain Architecture and Segmentation Intelligence
A nuanced understanding of the Copaiba essential oil market requires dissecting how revenue distributes across geographic territories, quality specifications, and application channels. Our analysis maps these dimensions not as isolated silos, but as interconnected nodes that dictate pricing power, sourcing strategy, and go-to-market execution. The regional landscape reveals a market where established consumer maturity and robust distribution infrastructure coexist alongside emerging demand centers that are actively building local processing capacity and import dependencies.
Demand is not evenly distributed across end-use categories. The application matrix demonstrates how cosmetic and personal care formulations currently anchor the largest share of commercial activity, capitalizing on Copaiba's emollient properties, natural aroma profile, and compatibility with clean beauty trends. Pharmaceutical and nutraceutical applications represent a secondary but rapidly evolving vector, where standardized extracts, softgel formulations, and bioactive research are opening premium pathways. Simultaneously, aromatherapy, wellness blending, and specialty flavor or fragrance uses continue to expand, supported by direct-to-consumer education and influencer-driven discovery cycles.
Cypress Essential Oil Market
Grade differentiation further modulates market behavior. Therapeutic-grade material commands heightened scrutiny around purity, traceability, and clinical or traditional efficacy claims, while food-grade and industrial-grade variants serve distinct regulatory and formulation requirements. The relative weighting of these categories influences procurement strategies, from bulk commodity hedging to specialized small-batch sourcing. Understanding how each grade interacts with regional supply availability and end-market price elasticity is essential for companies optimizing inventory allocation, contract negotiation, and product line extension.
From a supply-side perspective, the origin ecosystem remains anchored by producers operating within the Amazon biome, where oleoresin extraction from Copaifera species underpins the raw material pipeline. The integration of agroextractivist partnerships, cooperative models, and fair-trade frameworks has shifted sourcing from a purely extractive paradigm to one emphasizing sociobiodiversity preservation and community economic security. These practices are increasingly viewed not only as ethical imperatives but also as risk-mitigation instruments that stabilize long-term supply continuity amid environmental and regulatory pressures. Recent corporate disclosures reinforce this shift, highlighting collaborative sourcing journeys and low-impact harvesting protocols designed to maintain product quality while safeguarding collector livelihoods and ecosystem integrity.
Competitive Landscape: Strategic Positioning and Differentiation Vectors
The Copaiba essential oil market features a heterogeneous mix of multinational ingredient groups, regional Latin American producers, and specialized Western distributors, each competing through distinct lenses of scale, authenticity, certification, and application expertise. Competitive advantage in this space rarely stems from price alone; it emerges from the ability to reliably deliver consistent chemotype profiles, validate sustainability claims, and provide technical support tailored to downstream formulation needs.
Leading global wellness and essential oils enterprises have built expansive brand ecosystems that pair direct-to-consumer marketing with rigorous internal research initiatives. One prominent player has emphasized Co-Impact Sourcing networks that connect Brazilian Amazon communities with structured procurement pathways, translating socioenvironmental commitments into branded product lines spanning pure oils and encapsulated softgel formats. Concurrently, this company has advanced its scientific credibility by publishing detailed human clinical investigations examining cellular, molecular, and microbiome-level interactions, reinforcing a positioning rooted in evidence-informed wellness.
On the industrial and ingredients side, integrated chemical and specialty groups have leveraged local sourcing relationships to secure steady access to Amazonian raw materials while embedding sociobiodiversity and fair-trade principles into their operating models. Partnerships with cooperatives illustrate a supply chain philosophy that prioritizes transparent compensation structures and low-impact harvesting, aligning commercial output with biodiversity protection standards. These initiatives are increasingly cited in corporate sustainability communications, signaling to buyers that ethical provenance is becoming a procurement criterion rather than an optional accessory.
Specialty bulk suppliers and fragrance-focused producers occupy another strategic layer, often competing on consistency, origin transparency, certification portfolios, and technical service. Companies with established relationships across multiple origin points can buffer against seasonal or logistical variability, offering downstream formulators greater predictability. Meanwhile, organic-certified distributors and herbal-focused retailers continue to build loyalty through curated quality standards, educational content, and niche application expertise in aromatherapy and personal care. The resulting ecosystem is characterized by overlapping yet distinct value propositions, where scale, traceability, clinical or traditional validation, and format adaptability collectively determine share dynamics.
Recent corporate activity illustrates the breadth of strategic maneuvering shaping the market. High-profile sustainability partnerships have brought Amazon cooperative sourcing into sharper focus, while clinical research publications have sought to substantiate functional benefit narratives at a physiological level. For competitors and new entrants alike, these signals carry strategic weight: they demonstrate that credibility is increasingly constructed through visible supply chain ethics and scientifically grounded communication, not merely through product availability.
Regulatory, Sustainability, and Sourcing Dynamics
Market evolution in Copaiba essential oil is tightly coupled to regulatory expectations and sustainability mandates that are becoming more explicit across buyer organizations and origin jurisdictions. As end-users and brand owners incorporate biodiversity protection, ethical procurement, and traceability into vendor qualification criteria, suppliers who can document compliant harvesting practices, fair economic impact, and low ecological disturbance gain preferential access to premium contracts. This trend is especially pronounced in cosmetic and personal care segments, where clean-label narratives and responsible sourcing claims are subject to heightened consumer scrutiny and internal compliance review.
Forestry and biodiversity regulations governing the Amazon biome further influence how raw materials are harvested, transported, and certified. Producers reliant on conventional vs. cooperative or certified models face different cost structures, administrative burdens, and reputational exposure. As a result, sourcing strategy has evolved into a multidimensional challenge that balances yield stability, quality consistency, audit readiness, and community impact. Companies that invest early in supplier mapping, documentation infrastructure, and partnership transparency are better equipped to navigate volatility and demonstrate resilience to institutional buyers.
What the Full Research Delivers: Analytical Depth for Decision-Makers
Our complete market study extends far beyond high-level growth narratives. It is structured to support operational planning, competitive benchmarking, and investment prioritization across multiple functional teams. The report integrates historical baselines, forecast modeling, and segmentation intelligence into an actionable format that enables readers to assess market entry suitability, channel expansion opportunities, and supply chain optimization pathways.
Inside the full publication, stakeholders will find detailed analysis covering regional demand profiles, grade-specific commercial behaviors, and application-level adoption trends, along with quantitative estimates that clarify revenue distribution without exposing proprietary granular breakdowns in this summary. The competitive section profiles key companies by headquarters, sourcing philosophy, product formats, and strategic focus, supplemented by recent corporate developments that illuminate where incumbents are directing attention. Additional components examine raw material origins, extraction methodologies, certification landscapes, and regulatory considerations that shape procurement risk and formulation compatibility.
The research is designed for multiple use cases. Product developers can align ingredient selection with grade availability and application performance expectations. Procurement leaders can benchmark supplier types and assess sourcing model trade-offs. Commercial strategists can evaluate where differentiation through sustainability claims, clinical narratives, or format innovation is likely to yield stronger positioning. Investors and analysts can use the structural overview to frame portfolio exposure and identify segments where growth is most concentrated.
Strategic Imperatives for 2026 and Beyond
As the forecast period unfolds, several strategic priorities will distinguish adaptable organizations from those caught reacting to market shifts. First, supply chain resilience must be treated as a competitive asset. Diversifying origin relationships, verifying certification integrity, and maintaining contingency pathways can mitigate the impact of environmental, logistical, or regulatory disruptions. Second, communication credibility matters. Claims around sustainability, ethical compensation, and functional benefits increasingly require substantiation through documented sourcing practices, research integration, or certification frameworks. Third, application breadth should be approached with discipline. While cosmetic and personal care channels currently anchor volume, pharmaceutical, aromatherapy, and specialty flavor or fragrance segments offer differentiated margin profiles and require tailored technical alignment.
Companies that treat Copaiba essential oil as a dynamic ingredient platform—rather than a static commodity—will be better positioned to respond to evolving consumer expectations, formulation trends, and procurement standards. The intersection of projected growth, sustainability-driven sourcing, and application expansion creates a period where informed strategic action can yield durable advantage.
To access the complete dataset, segmentation estimates, company profiles, regional demand breakdowns, and forecast modeling that underpin this analysis, we invite decision-makers to explore the full Worldwide Copaiba Essential Oil Market research. The full report delivers the operational precision and contextual depth required to convert market intelligence into executable strategy across the 2026 to 2032 horizon.
For detailed analysis of this topic, please visit the official page: Worldwide Copaiba Essential Oil Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com