

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Embedded Hypervisor Market Hits $565M in 2025, Poised for 7.5% CAGR Growth

Strategic Imperatives in the Embedded Hypervisor Landscape: A 2026 Outlook
As embedded systems grow increasingly complex, the demand for robust virtualization solutions has moved from niche experimentation to core architectural necessity. The Worldwide Embedded Hypervisor Software Market stands at a critical inflection point, driven by the convergence of automotive electrification, industrial IoT expansion, and stringent safety regulations across aerospace and defense sectors. For enterprise leaders navigating 2026, understanding the trajectory of this market is not merely an academic exercise but a strategic imperative for supply chain planning, technology investment, and competitive positioning. This analysis draws upon comprehensive market intelligence to outline the structural forces shaping the industry, while highlighting the operational value embedded within our latest Worldwide Embedded Hypervisor Software Market research report.
The market has demonstrated consistent momentum over the past half-decade, evolving from a foundational phase into a growth-driven ecosystem. Historical data from 2020 through 2025 reveals a steady climb in global revenue, reflecting the gradual adoption of virtualization across safety-critical and mission-critical domains. As we project forward into the 2026 to 2032 forecast period, the trajectory indicates sustained expansion, underpinned by architectural shifts toward multi-OS environments, hardware-assisted partitioning, and the increasing requirement to isolate mixed-criticality workloads on shared silicon. The compound annual growth rate observed across the forecast horizon signals a market that is maturing yet still expanding, offering both opportunity and risk for stakeholders who must align their strategies with precise market realities.
Market Evolution and Structural Growth Drivers
The embedded hypervisor software space has transitioned from supporting isolated development boards to becoming integral to production-grade systems where downtime, safety certification, and deterministic real-time performance are non-negotiable. Early adoption was largely confined to research environments and select aerospace programs, but the past several years have seen industrialization of hypervisor platforms that meet rigorous certification standards. This maturation has been enabled by concurrent advancements in silicon architecture, particularly the integration of virtualization extensions within ARM Cortex cores and x86 platforms, which provide the hardware fidelity required for efficient Type 1 partitioning without compromising latency budgets.
Several macroeconomic and sector-specific forces are compressing the timeline for hypervisor adoption. In automotive, the proliferation of domain controllers and zonal architectures demands that multiple operating environments coexist on a single SoC, from real-time control stacks to infotainment and advanced driver-assistance systems. Industrial automation is similarly pushing toward consolidated edge nodes that must run deterministic control loops alongside higher-level analytics and connectivity stacks. Meanwhile, aerospace and defense programs continue to rely on partitioning solutions that enforce strict fault containment and compliance with avionics standards. The combined effect of these trends is a broad-based pull for hypervisor software that can deliver certified isolation, deterministic scheduling, and long-term supplier support.
Desktop Hypervisor Market
Segmentation Dynamics: Types, Applications, and Regional Distribution
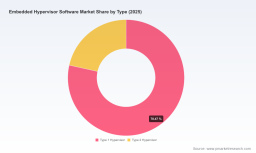
The market structure reflects a clear preference for native embedded virtualization architectures. Type 1 hypervisors, which operate directly on hardware to provide deterministic isolation, dominate the revenue landscape, reflecting their alignment with safety-critical and real-time use cases. Type 2 hypervisors, while valuable in development and general-purpose scenarios, face inherent limitations in hard real-time contexts due to host operating system scheduling overhead, making them less suitable for applications where sub-millisecond latency and predictable behavior are mandatory. This architectural divide informs procurement strategies, as engineering teams must evaluate not only feature sets but also certification pedigrees and hardware compatibility when selecting a virtualization layer.
Application demand is distributed across multiple verticals, each with distinct performance, certification, and lifecycle requirements. Automotive represents a substantial share of market activity, fueled by the need to virtualize electronic control units and consolidate mixed-criticality functions. Industrial automation follows closely, driven by the modernization of factory floors and the integration of edge computing into motion control and robotics. Aerospace and defense maintain a strong presence, supported by long program cycles and the requirement for avionics partitioning that meets rigorous certification frameworks. Consumer electronics, healthcare, and medical devices contribute additional demand, particularly where regulatory compliance and data isolation intersect with embedded system design. Regionally, the market is balanced among major economic zones, with North America, Europe, and Asia Pacific forming the core of revenue generation, while Latin America and the Middle East and Africa represent emerging footholds that are gradually expanding as local industrial and automotive programs mature.
Worldwide Embedded Hypervisor Software Market
Competitive Landscape: Incumbents and Strategic Positioning
The competitive environment is characterized by specialized vendors with deep domain expertise in safety certification, real-time performance, and long-term support commitments. Market concentration data indicates that leading participants command a significant share of global revenue, reflecting the high barriers to entry created by certification costs, architectural expertise, and established customer relationships. Incumbents have built their positions on platforms that span multiple industries, while others focus narrowly on specific certification regimes or hardware ecosystems to differentiate their offerings.
Wind River remains a prominent force with its VxWorks 653 hypervisor, which is engineered for safety-critical embedded systems and carries certifications relevant to aerospace, defense, and automotive applications. Its recent expansion to support newer processor architectures underscores the vendor's focus on future-proofing safety-critical deployments. Green Hills Software competes with real-time hypervisors that emphasize ARINC 653 partitioning, serving avionics and industrial programs that require deterministic behavior and robust fault containment. Lynx Software Technologies provides a separation kernel approach designed for defense, aerospace, and automotive environments, with strong alignment to multi-level security partitioning principles. SYSGO’s PikeOS platform is widely recognized for its multi-certification breadth, covering avionics, automotive, and industrial safety standards, and continues to extend its footprint into medical applications where stringent software lifecycle requirements apply.
Real-Time Systems GmbH delivers virtualization solutions optimized for ARM and x86 platforms, targeting automotive and industrial IoT deployments that require real-time partitioning and hardware flexibility. BlackBerry QNX brings its reputation in real-time operating systems to the hypervisor space, offering Type 1 virtualization with safety certifications suited to automotive and medical use cases, and has extended its platform to support advanced edge computing accelerators. Mentor Graphics, now part of Siemens EDA, contributes tooling and virtualization assets that complement embedded development workflows in automotive and aerospace programs. ETAS, within the Bosch Group, addresses automotive electronic control unit consolidation with solutions that support AUTOSAR and functional safety requirements, reflecting the industry's push toward integrated multi-OS ECUs.
Recent product and partnership activity illustrates how vendors are adapting to hardware evolution and certification demands. One major vendor advanced its safety-critical hypervisor to support emerging processor architectures, reinforcing its position in next-generation avionics and automotive programs. Another achieved a notable medical certification milestone, broadening the addressable market for embedded virtualization in regulated healthcare devices. Strategic partnerships with semiconductor suppliers have also accelerated, enabling tighter integration between hypervisor platforms and silicon featuring virtualization extensions, which reduces integration risk for customers building industrial and automotive systems. In parallel, expanded support for high-performance edge accelerators has opened new deployment pathways in automotive edge computing, where inference workloads and real-time control must coexist on consolidated hardware.
Regulatory and Technical Forces Shaping Demand
Regulatory frameworks continue to act as both a gatekeeper and a growth catalyst. In avionics, certification standards mandate rigorous partitioning and verification for commercial aircraft systems, compelling suppliers to invest in compliant hypervisor architectures and long-term support commitments. In automotive, functional safety requirements dictate that electronic control units handling mixed-criticality workloads must demonstrate deterministic isolation and fault containment, which in turn drives adoption of certified hypervisors that can separate safety-related functions from infotainment or connectivity stacks. Standardization efforts further reinforce these expectations by defining time and space partitioning interfaces that enable interoperability and predictable behavior across guest operating environments.
Technical constraints also shape procurement and architecture decisions. Efficient Type 1 partitioning depends on silicon that provides virtualization extensions and predictable interrupt handling, meaning that hardware selection and hypervisor choice are increasingly made in tandem. Development teams must account for scheduling latency, memory isolation, and I/O virtualization performance when evaluating solutions, particularly in applications where hard real-time guarantees are essential. These technical realities reinforce the preference for platforms with proven certification records and robust hardware compatibility matrices, as the cost of late-stage integration issues can far exceed the upfront investment in a well-matched virtualization stack.
Strategic Value of the Research for 2026 Decision-Making
For executives and technical leaders planning 2026 initiatives, the value of detailed market intelligence lies in its ability to convert broad trends into actionable decision support. The Worldwide Embedded Hypervisor Software Market report provides a structured foundation for assessing demand durability, competitive intensity, and technology alignment across verticals and regions. It enables organizations to benchmark their product roadmaps against market momentum, identify segments where certification and hardware compatibility create durable moats, and evaluate partnership or acquisition targets with greater precision. Procurement and supply chain teams can use the research to anticipate vendor concentration risks, assess long-term support viability, and align sourcing strategies with program timelines that span multiple years. Engineering leaders can leverage the analysis to prioritize architecture choices, validate hypervisor selections against certification pathways, and reduce integration risk by understanding which platforms are gaining traction in specific application domains.
Beyond strategic planning, the report offers operational utility through detailed segmentation analysis, competitive profiling, and scenario-based forecasting. Readers gain access to structured evaluations of vendor capabilities, release cadences, certification statuses, and partnership ecosystems, all contextualized within the broader market trajectory. The inclusion of recent developments helps organizations track how incumbents and challengers are responding to hardware transitions and regulatory shifts, while the segmentation and concentration data illuminate where market power is accumulating and where entry opportunities may still exist. This combination of macro-level forecasting and granular competitive intelligence is designed to support decisions ranging from portfolio prioritization to regional expansion and technology adoption timing.
Organizations that integrate this intelligence into their planning cycles are better positioned to navigate the trade-offs between performance, certification, and cost that define embedded virtualization procurement. By understanding how application demand, regional dynamics, and vendor strategies intersect, leaders can construct roadmaps that align with both near-term program requirements and long-term market evolution. The report serves as a decision-grade reference for mapping investment priorities, reducing uncertainty in vendor selection, and anticipating the regulatory and technical hurdles that will shape deployment success in the coming years.
Conclusion: Positioning for the Next Phase of Embedded Virtualization
The Worldwide Embedded Hypervisor Software Market is entering a phase where growth is increasingly tied to certified, deterministic, and hardware-aligned virtualization platforms. Demand is being shaped by the consolidation of automotive systems, the modernization of industrial automation, and the persistent requirements of aerospace and defense programs, while regulatory frameworks and silicon capabilities continue to define what is commercially viable. Market concentration among established vendors reflects the engineering and certification burdens inherent to this space, but also signals the strategic importance of selecting partners with the right pedigree, roadmap, and support commitments.
For decision-makers preparing for 2026 and beyond, the opportunity lies in translating market momentum into disciplined strategy. That means aligning technology choices with certification pathways, validating hardware compatibility early, and monitoring competitive moves that indicate where capabilities are headed. The full research report expands on these themes with detailed segmentation data, competitive profiles, and forward-looking forecasts that provide the depth required for executive planning, procurement strategy, and engineering roadmap development. To access the complete market intelligence and supporting analysis, please visit the source page for the Worldwide Embedded Hypervisor Software Market research.
For detailed analysis of this topic, please visit the official page: Worldwide Embedded Hypervisor Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com