

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Plastic Bracket Market to Grow at 5.82% CAGR to $369.37M by 2032

Strategic Intelligence for 2026: Navigating the Global Motorcycle Headlight Bracket Market
The motorcycle component ecosystem is undergoing a period of structural transformation. As manufacturers and aftermarket suppliers alike recalibrate their product portfolios, the headlight bracket segment has emerged as a critical nexus of engineering precision, regulatory compliance, and consumer customization. Our latest market research offers a comprehensive, data-driven blueprint of the Worldwide Motorcycle Headlight Bracket Market, designed specifically to equip executive teams with the foresight required for 2026 decision-making. This analysis moves beyond surface-level trends to dissect the mechanical, economic, and competitive forces that will shape revenue trajectories through the end of the decade.
Macro Trajectory: A Baseline of Sustained Expansion
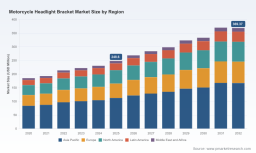
The market has demonstrated resilient upward momentum across the historical review window. From a baseline of approximately 185.3 million USD in 2020, revenue progression has accelerated steadily, crossing the 220 million USD threshold by 2023 and reaching an estimated 248.6 million USD by the 2025 base year. Forward projections indicate continued growth, with the market expected to expand to 268.76 million USD in 2026 before ascending toward a peak valuation of roughly 370.41 million USD by 2031. The forecast period through 2032 reflects a compound annual growth rate of 5.82 percent, signaling a mature yet dynamically expanding sector that rewards manufacturers and distributors who align their strategies with underlying demand drivers.
This trajectory is not merely a function of unit sales growth. It reflects deeper structural shifts: the integration of advanced lighting architectures, the proliferation of custom and semi-custom motorcycle builds, and the ongoing migration toward lightweight, corrosion-resistant mounting solutions. For strategic planners, these numbers provide a quantitative anchor. Yet the real strategic value lies in understanding what forces are compressing or expanding margins, how material science is reshaping product specifications, and which distribution channels will capture disproportionate value as the market matures.
Market Architecture: Material, Channel, and Application Dimensions
The competitive landscape is fundamentally shaped by how manufacturers segment their offerings across material specifications, sales channels, and motorcycle classifications. Aluminum alloy has firmly established itself as the dominant structural material for headlight brackets, driven by its favorable strength-to-weight ratio, inherent corrosion resistance, and compatibility with precision machining processes. Steel continues to occupy specific durability-focused applications, while stainless steel and carbon fiber composites serve niche performance and aesthetic segments. The interplay between material cost volatility, particularly in aluminum markets, introduces a critical variable for production cost modeling and pricing architecture.
Worldwide Automotive Bracket Market
Distribution dynamics further complicate the landscape. The OEM channel maintains a substantial footprint, anchored by original equipment suppliers who integrate headlight mounting solutions directly into factory assembly lines. Simultaneously, the aftermarket segment is expanding rapidly, fueled by the rise of custom motorcycle culture, the increasing popularity of electric two-wheelers requiring adapted lighting configurations, and consumer demand for CNC-machined, adjustable mounting platforms. This bifurcation between factory-integrated and post-purchase modification channels creates distinct opportunity zones for suppliers capable of serving both volume-driven production environments and high-mix, low-volume customization workflows.
Application segmentation reveals additional layers of complexity. Standard and commuter motorcycles continue to represent a significant volume base, while cruisers, choppers, sport bikes, and off-road or adventure platforms each impose different geometric, thermal, and load-bearing requirements on bracket designs. Understanding which application segments are expanding fastest, and how mounting geometries are adapting to varying fork diameters and integrated wiring harnesses, is essential for firms developing product roadmaps or evaluating acquisition targets.
Competitive Landscape: A Fragmented Field with Strategic Chokepoints
The market exhibits a moderate degree of concentration, with the top three players collectively commanding a substantial share of total revenue and the top five firms consolidating a broader portion of industry output. This structure indicates a competitive environment where scale, engineering capability, and channel relationships serve as meaningful barriers to entry, even as specialized manufacturers carve out defensible niches through material innovation and regional specialization.
Leading European manufacturers have built reputations around precision engineering and premium material finishes. Italian operations have focused on fork-mounted bracket designs that actively mitigate road-induced vibrations, frequently utilizing brushed aluminum construction to balance aesthetic refinement with functional durability. German suppliers have emphasized individually adjustable premium brackets engineered for common fork diameters, leveraging CNC-machined aluminum to deliver certified quality standards and design-forward configurations. These European capabilities reflect a broader industry emphasis on vibration dampening, aesthetic consistency, and adherence to rigorous quality protocols.
North American manufacturers have pursued a different strategic emphasis, often targeting the custom motorcycle and direct-replacement segments. US-based producers have developed brackets machined from high-grade aluminum alloys specifically for secure fork tube mounting, with design philosophies that minimize installation friction, such as eliminating the need for top clamp removal during retrofitting. Parallel US operations have expanded into LED lighting ecosystems, offering compatible brackets and mounts across major legacy brands while emphasizing durable replacement and conversion solutions for aging fleets.
Asian manufacturing hubs have scaled rapidly by combining precision fabrication with competitive cost structures. Taiwanese operations have introduced standardized and premium CNC aluminum bracket series designed for both auxiliary lighting and primary headlight mounting, emphasizing straightforward installation and long-term durability. Chinese metal fabricators have expanded production of high-strength carbon steel and alternative alloy brackets, while specialized accessory suppliers have broadened their portfolios to capture cross-border distribution channels. These regional capabilities have steadily increased their influence across both OEM supply networks and global aftermarket channels.
Tier-one motorcycle OEMs remain influential anchors within the ecosystem. Major manufacturers supply genuine headlight brackets and relocation kits as original equipment components, establishing baseline specifications that aftermarket innovators must navigate. Premium OEMs continue to release updated mounting hardware across refreshed model cycles, reinforcing the importance of technical alignment between factory designs and aftermarket adaptation kits. The interplay between OEM specification control and aftermarket innovation creates a dynamic tension that rewards firms capable of rapid prototyping, materials engineering, and regulatory-aware design.
Regulatory and Supply Chain Dynamics: Navigating Constraints and Catalysts
Regulatory frameworks have become an increasingly salient factor in bracket design and qualification. In the United States, Federal Motor Vehicle Safety Standard FMVSS 108 specifies requirements for motorcycle headlighting systems, including mounting and performance criteria that indirectly shape bracket geometry, durability expectations, and attachment methodologies. Stringent safety standards across multiple jurisdictions mandate the use of high-quality, durable brackets that satisfy specific mounting integrity and impact-resistance criteria. Compliance is no longer a peripheral concern; it is a core engineering parameter that influences material selection, fastening mechanisms, and testing protocols.
Worldwide Motorcycle Headlight Bracket Market
Supply chain volatility introduces an additional strategic layer. Fluctuations in raw material pricing, particularly within aluminum markets, directly impact production cost structures and short-term margin planning. Firms that maintain diversified sourcing strategies, implement forward-contracting Discipline, or invest in lightweight design optimization are better positioned to absorb commodity volatility without compromising competitive pricing. The intersection of material science, manufacturing efficiency, and regulatory compliance creates a multi-variable optimization challenge that separates reactive operators from strategically agile manufacturers.
What the Full Report Delivers: Operational Intelligence for Executive Teams
This market research publication is structured to translate macro trends into actionable strategic inputs. The report provides a detailed segmentation framework that maps revenue distribution across material categories, sales channels, and motorcycle applications, enabling readers to identify high-growth subsegments without relying on generalized market narratives. Regional performance is assessed through a comparative lens that highlights leading demand centers, supply base maturity, and growth acceleration patterns, offering a geographic roadmap for capacity planning, distribution expansion, and partnership evaluation.
Competitive profiling extends beyond basic company descriptions to examine positioning strategies, material and manufacturing capabilities, product architecture philosophies, and channel orientations. Profiles covering Italian, German, US, Taiwanese, Chinese, and French operations, alongside tier-one OEM participants, provide a panoramic view of how incumbents are competing on quality certification, customization flexibility, installation efficiency, and aftermarket support. This multi-dimensional competitor mapping allows strategy teams to benchmark their own capabilities, identify white-space opportunities, and anticipate competitive responses as the market consolidates around quality and engineering differentiation.
The research also integrates regulatory context and supply chain dynamics into a unified market dynamics assessment. Readers gain clarity on how safety standards shape design requirements, how raw material price movements influence cost structures, and how the expanding aftermarket ecosystem interacts with OEM specification cycles. This synthesis is particularly valuable for product managers evaluating new bracket architectures, procurement teams modeling input cost scenarios, and commercial leaders assessing channel mix strategies across OEM and aftermarket segments.
Importantly, the full report preserves analytical depth while protecting proprietary segmentation figures and region-specific revenue allocations. This deliberate structure ensures that the intelligence remains decision-ready and commercially sensitive, encouraging stakeholders to engage with the complete dataset for precise forecasting, scenario modeling, and investment justification.
Strategic Imperatives for 2026 Decision-Making
As the market advances toward its projected mid-decade expansion, several strategic imperatives become evident. Firms should prioritize engineering investments that reduce dependency on volatile commodity inputs while maintaining structural integrity and aesthetic quality. Expanding compatibility across common fork diameters and streamlining installation procedures will continue to differentiate aftermarket suppliers in an increasingly crowded field. OEM-adjacent players should evaluate how updated factory specifications and LED-integrated lighting architectures may reshape bracket attachment requirements and aftermarket retrofit demand.
Distribution strategy also warrants renewed focus. The coexistence of high-volume OEM supply and customization-driven aftermarket demand creates an opportunity for hybrid commercial models that balance production efficiency with engineering flexibility. Companies that can anticipate regional demand shifts, align material procurement with forecasted growth, and position themselves within both factory supply chains and independent distributor networks will capture disproportionate value as the market matures.
Accessing the Complete Intelligence Framework
This overview establishes the analytical foundation and strategic relevance of the Worldwide Motorcycle Headlight Bracket Market research. The complete report extends far beyond these thematic highlights, providing detailed segmentation data, region-specific growth assessments, competitive capability comparisons, and forward-looking scenario analysis designed for 2026 planning cycles and beyond. For executives, product leaders, and investment teams seeking precise, defensible market intelligence, the full dataset offers the granularity necessary to convert directional insight into executable strategy. We invite stakeholders to access the complete report to unlock the full breadth of segmentation breakdowns, competitive evaluations, and forecast modeling tools that will inform critical decisions in the year ahead.
For detailed analysis of this topic, please visit the official page: Worldwide Motorcycle Headlight Bracket Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com