

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global Semiconductor Magnetic Sensor Market to Hit $5,995.97M by 2032, 9.0% CAGR

Navigating the Magnetic North: Strategic Imperatives in the Global Semiconductor Sensor Landscape
The semiconductor industry stands at a critical inflection point, where the convergence of electrification, automation, and advanced sensing technologies is redefining value chains across the globe. For enterprise leaders and strategic planners, understanding the trajectory of semiconductor magnetic sensors is no longer optional—it is a prerequisite for capital allocation, supply chain resilience, and product roadmap justification. Our latest comprehensive study, the Worldwide Semiconductor Magnetic Sensor Market analysis, provides the granular intelligence required to navigate this complex environment through 2032.
This report serves as a definitive guide for stakeholders aiming to capitalize on the projected expansion of this vital sector. As industries increasingly rely on precise magnetic field detection for everything from electric vehicle powertrains to industrial robotics, the demand for robust, high-sensitivity sensor solutions is accelerating. The following insights outline the macro-environmental drivers, competitive dynamics, and regulatory headwinds that will shape decision-making in 2026 and beyond.
Macro Market Trajectory and Growth Vectors
The historical data from 2020 through 2025 sets a robust foundation for future projections. Over this period, the market has demonstrated resilient growth, moving from a base of approximately $2.15 billion in 2020 to an estimated $3.28 billion by 2025. This upward trajectory reflects the deepening integration of magnetic sensing technologies into core industrial and consumer processes. However, the forecast period from 2026 to 2032 suggests an acceleration in value creation that outpaces recent historical trends.
Our analysis projects the market to reach significant milestones by the end of the decade, driven by a compound annual growth rate (CAGR) of 9.0%. This growth rate indicates a healthy expansion environment, though it is not without volatility. The forecast values indicate a steady climb, suggesting that demand drivers are structural rather than cyclical. For strategic planners, this implies that investments made in 2026 will likely yield compounding returns as the market matures toward 2032. The revenue projections, denominated in USD millions, highlight a market capable of sustaining high-volume production while accommodating premium pricing for advanced technologies such as Tunnel Magnetoresistance (TMR) and Giant Magnetoresistance (GMR).
It is crucial for stakeholders to recognize that this growth is not uniform across all vectors. The momentum is concentrated in specific technological and application domains that are undergoing rapid transformation. Understanding where this growth concentrates allows organizations to prioritize R&D spending and capacity expansion in high-yield areas while mitigating exposure to slower-growing segments.
Segmentation Dynamics: Technology and Application Convergence
The market structure is defined by a diverse array of sensor technologies, each serving distinct performance requirements. Hall Effect sensors continue to hold a substantial share of the value proposition, particularly in applications requiring cost-effective and reliable detection. However, the landscape is shifting toward higher-sensitivity technologies. Magnetoresistive solutions, including AMR, GMR, and TMR, are gaining traction in scenarios demanding greater precision and stability under varying environmental conditions.
Worldwide Semiconductor Magnetic Sensor Market
Magnetic Field Sensors Market
From an application perspective, the automotive sector remains the dominant force driving revenue. The ongoing transition toward electric vehicles and the integration of advanced driver-assistance systems (ADAS) are creating sustained demand for position, speed, and current sensing. Industrial automation constitutes another significant pillar, where the push for smart manufacturing and predictive maintenance is increasing the deployment of magnetic sensors in robotics and motor control systems. Consumer electronics and medical healthcare sectors represent growing niches, where miniaturization and low-power consumption are key differentiators.
Strategic decisions in 2026 must account for the interplay between these segments. For instance, a technology chosen for automotive safety-critical applications may not be suitable for consumer goods due to cost constraints, yet the underlying IP might be leveraged across both. Our report details these cross-segment opportunities without exposing the specific revenue splits that constitute proprietary intelligence within the full dataset.
Competitive Landscape and Strategic Positioning
The market is characterized by a consolidated competitive environment where established players leverage deep portfolios and vertical integration. The top three companies command a significant portion of the market revenue, indicating high barriers to entry for new competitors. The top five firms further extend this influence, controlling over two-thirds of the market share. This concentration suggests that partnership, acquisition, or licensing strategies may be more viable for smaller entities than direct competition on scale.
Leading entities such as Allegro MicroSystems, Infineon Technologies, and NXP Semiconductors are central to this ecosystem. Allegro has been aggressive in expanding its portfolio, particularly following strategic acquisitions that broadened its TMR and current sensing capabilities. Infineon continues to leverage its XENSIV brand to cover a wide spectrum of sensing technologies for automotive and industrial use. NXP remains focused on automotive-specific solutions, emphasizing ultra-low power and reliability.
In the Asia-Pacific region, Japanese manufacturers like Asahi Kasei Microdevices (AKM) and TDK Corporation are pivotal. TDK's recent introduction of compact TMR angle sensors highlights the industry's move toward higher performance in safety-critical contexts. Similarly, STMicroelectronics and Melexis are pushing the boundaries with 3D magnetic position sensors and multi-sensor reference designs. American giants like Honeywell and Texas Instruments maintain strong positions in industrial and aerospace applications, while specialized players like ABLIC and Tower Semiconductor offer niche capabilities ranging from ZCL detection to GaN-based foundry services.
Recent product launches underscore the pace of innovation. STMicroelectronics launched a new industrial multi-sensor reference design featuring ultra-low-power 3-axis magnetic sensors in late 2025. TDK followed with the TAS8240, a compact TMR angle sensor for safety-critical applications. Allegro MicroSystems made significant waves with the ACS37100, the first commercial 10 MHz TMR magnetic current sensor designed for high-speed wide-bandgap power electronics. These launches indicate a clear trend toward higher frequency response, lower power consumption, and enhanced integration.
Geopolitical and Supply Chain Risk Factors
While demand drivers are strong, supply chain resilience remains a paramount concern for 2026 planning. The geopolitical landscape has introduced new complexities, particularly regarding raw materials essential for high-performance magnetic systems. China's dominance in the refining of heavy rare earth elements, holding over 85% of global capacity and approximately 90% of processed dysprosium and terbium supply, creates a potential bottleneck. These materials are critical for the magnets and systems associated with advanced sensor technologies.
Regulatory actions have further tightened the environment. In late 2024 and early 2025, restrictions were imposed on the export of gallium, germanium, antimony, and certain heavy rare earth elements to the United States. These measures were followed by a foreign direct product rule-style measure in late 2025, requiring licenses for foreign-produced rare earth magnets or semiconductor materials containing significant Chinese-origin heavy rare earth elements. Such regulations necessitate a thorough review of tier-2 and tier-3 supply chain dependencies.
Furthermore, trade policy shifts in the United States, including tariffs on certain advanced computing chips and semiconductor imports implemented in early 2026, add another layer of cost and compliance complexity. Organizations must evaluate whether their sourcing strategies are robust against these regulatory fluctuations. Conversely, there are mitigating factors; global battery pack prices fell significantly in 2024, driven by declines in critical minerals prices. This volatility in input costs can ripple through the sensor supply chain, affecting margins and pricing strategies.
For decision-makers, the implication is clear: strategic sourcing and diversification are no longer just operational tasks but competitive advantages. Reliance on single-source geographies for critical materials poses a tangible risk to production continuity and cost stability. The full report provides a risk matrix that maps these regulatory and material constraints against specific market segments, enabling leaders to model contingency plans.
Proprietary Intelligence and Decision Support
The value of this market research extends beyond high-level trends. The complete study offers actionable granularity that is essential for nuanced strategy formulation. While this overview highlights the macro landscape, the full document contains detailed segmentation analysis that breaks down revenue potential by specific technology types and application verticals without aggregating them into broad categories.
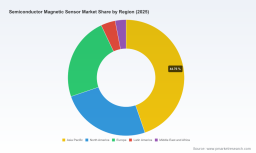
Stakeholders will find detailed profiles of key competitors, including their headquarters, strategic focus areas, and recent developmental milestones. This information allows for benchmarking against peers and identifying potential partnership opportunities. The report also includes a comprehensive examination of regulatory impacts by region, helping organizations anticipate compliance requirements in key markets across Asia Pacific, North America, Europe, Latin America, and the Middle East and Africa.
By accessing the full intelligence package, enterprises can quantify the market opportunity with precision, validate internal forecasts against independent data, and identify white spaces for innovation. The data is structured to support financial modeling, inventory planning, and long-term capacity strategy.
Conclusion: Strategic Readiness for 2026 and Beyond
The Worldwide Semiconductor Magnetic Sensor Market is poised for substantial growth, driven by technological advancement and expanding application bases. However, the path to capturing this value is fraught with competitive intensity and supply chain complexities. Success in 2026 will depend on the ability to interpret macro trends through the lens of specific operational realities.
This report provides the foundational intelligence required to make those interpretations with confidence. By understanding the concentration of market power, the trajectory of technological adoption, and the impact of geopolitical regulations, leaders can position their organizations to not only withstand volatility but to leverage it. We invite you to explore the complete findings to unlock the detailed data necessary for securing your strategic advantage in this evolving landscape.
For detailed analysis of this topic, please visit the official page: Worldwide Semiconductor Magnetic Sensor Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com