

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Urethritis Drugs Market Hits $2.15B in 2025, Projected 4.85% CAGR Through 2032

Global Urethritis Drugs Market Outlook 2026: Strategic Imperatives in a Shifting Therapeutic Landscape
Executive Overview
The worldwide urethritis drugs market stands at a critical inflection point as it moves through the 2026-2032 forecast period. Driven by evolving treatment guidelines, persistent antimicrobial resistance patterns, and a maturing generic ecosystem, the sector is projected to expand from an estimated 2.15 billion USD in 2025 to approximately 2.99 billion USD by 2032, reflecting a compound annual growth rate of 4.85 percent over the forecast horizon. This trajectory is neither linear nor guaranteed. It is shaped by regulatory recalibrations, formulary decisions, supply chain dynamics, and the strategic positioning of incumbent innovators alongside generic manufacturers. For executives navigating product portfolios, commercial planning, and market entry, the 2026 landscape demands a disciplined reading of where volume is migrating, which therapeutic categories are gaining policy tailwinds, and how distribution channels are being reconfigured by reimbursement realities.
This article previews our comprehensive Worldwide Urethritis Drugs Market research, a decision-grade intelligence asset designed to translate macro momentum into actionable commercial strategy. The full study delivers granular segmentation, competitive profiling, pricing and volume trajectories, channel-level dynamics, and scenario frameworks. What follows is a strategic orientation: the structural forces at work, the competitive contours, the regulatory currents, and the analytical architecture that decision-makers will need in 2026 and beyond.
Market Architecture and Growth Logic
Across the historical window of 2020 through 2025, the market consolidated around a core set of widely prescribed antibiotics and standardized treatment protocols, reaching a baseline that positioned the sector for measured expansion. The forecast period from 2026 through 2032 anticipates a broad-based uplift, underpinned by steady demand for first-line agents, incremental uptake of newer options where clinically indicated, and the continued role of public health programs that embed key therapies into STI management pathways.
Growth is not uniform across therapeutic categories. The market bifurcates between gonococcal and non-gonococcal indications, each governed by distinct clinical protocols, resistance considerations, and reimbursement exposure. At the same time, distribution channels reflect a pragmatic mix of institutional procurement, community dispensing, and digital fulfillment pathways, with each channel responding differently to formularies, prescription behaviors, and patient access programs. The interplay among these dimensions determines where commercial opportunity concentrates and where margin pressure intensifies.
Beyond the headline trajectory, the research decomposes the market into operationally meaningful layers:
- Therapeutic segmentation that distinguishes treatment pathways by pathogen type and guideline positioning
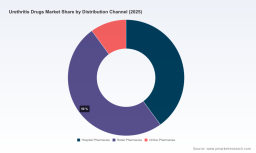
- Channel-level analysis capturing how hospital, retail, and online pathways differ in volume mix, reimbursement exposure, and growth elasticity
- Geographic framing that isolates high-volume markets and emerging demand centers without overstating localized statistics
- Competitive benchmarking mapped to product positioning, portfolio breadth, and pipeline relevance
This architecture enables teams to move from aggregate growth narratives to channel-level and category-level decision-making, aligning sales coverage, supply planning, pricing strategy, and partnership logic with where value is actually created.
Competitive Landscape: Innovators, Generics, and Positioning Realities
The competitive field blends global innovators with high-volume generic manufacturers, each exercising distinct commercial leverage. A small set of leading firms commands a meaningful share of total market value, while a broader cohort competes on cost, supply reliability, and regional access. Concentration metrics indicate that the top three players account for roughly 28.5 percent of market value, and the top five reach approximately 39.2 percent, signaling a landscape that is neither fully consolidated nor fragmented beyond strategic coherence. For commercial leaders, this structure has direct implications for pricing power, tender dynamics, and partnerships.
Bacterial Vaginosis Drug Market
Pfizer Inc. maintains a recognized presence through azithromycin-based offerings indicated for urethritis and cervicitis, alongside ceftriaxone products relevant to dual-therapy protocols for gonococcal infections. Its positioning is anchored in established brand recognition, clinical heritage, and broad distribution reach, making it a reference point in both institutional and community settings.
GlaxoSmithKline plc has advanced the competitive frontier with newer antibiotic options, including Blujepa for gonococcal infections. The introduction of differentiated therapies in this space is significant because it can shift treatment conversations, influence guideline interpretations, and create premium positioning where resistance management and tolerability matter. GSK’s broader anti-infective portfolio also supports cross-utilization and formularies that span multiple STI indications.
On the generic side, Teva Pharmaceutical Industries Ltd., Sun Pharmaceutical Industries Ltd., Cipla Ltd., and Dr. Reddy's Laboratories Ltd. collectively sustain the supply backbone for widely used agents such as azithromycin and doxycycline. Their commercial relevance lies in affordability, availability, and the ability to serve public health programs and private channels alike. In many markets, these manufacturers determine the practical accessibility of first-line regimens and influence the cost floor for competing products.
AbbVie Inc. and Merck & Co., Inc. contribute through antibiotic and anti-infective portfolios that intersect with broader bacterial infection management. While their direct exposure to urethritis-specific prescriptions varies, their commercial footprint, R&D orientation, and collaboration potential can influence supply resilience, pipeline optionality, and cross-indication utilization patterns.
Recent industry developments reinforce how quickly competitive positioning can shift when clinical evidence and regulatory milestones intersect. The 2025 approval landscape for newer gonorrhea-focused therapies, together with late-stage trial readouts for single-dose oral regimens, signals a market in which innovation may reframe standard-of-care discussions over the forecast period. At the same time, generic competition continues to compress price points in core categories, placing a premium on supply reliability, quality assurance, and channel relationships. The research evaluates each major player’s product relevance, geographic reach, pipeline implications, and likely strategic maneuvers so that clients can benchmark their own positioning and identify whitespace or defensive priorities.
Industry Dynamics Shaping 2026 and Beyond
Market performance in the urethritis drugs space is tightly coupled to clinical guidance, resistance trends, procurement structures, and reimbursement policy. These dynamics do not merely influence demand; they redefine which products are preferred, where volume concentrates, and how durable margin profiles can be.
Clinical practice standards remain foundational. Public health guidance continues to emphasize doxycycline-based regimens as preferred therapy for non-gonococcal urethritis, with azithromycin serving as an alternative in defined scenarios. For gonococcal infections, treatment conversations increasingly account for dual-therapy considerations in response to rising antimicrobial resistance. These protocols shape prescribing behaviors, formulary placement, and the relative pull-through of competing products. As stewardship expectations intensify, the ability to align product positioning with guideline-concordant use becomes a commercial advantage, not just a compliance matter.
Antimicrobial resistance is a persistent structural pressure. Emerging resistance patterns in pathogens associated with non-gonococcal urethritis, including Mycoplasma genitalium and Haemophilus spp., are driving interest in resistance-guided therapy and updated stewardship approaches. This trend has two strategic consequences. First, it increases the clinical value of diagnostic alignment and targeted treatment logic, which can shift demand toward therapies that fit resistance-aware protocols. Second, it creates a backdrop in which new or differentiated options may command greater attention where standard regimens face efficacy or tolerability limitations.
Reimbursement and access frameworks further condition the market. Many standard antibiotics used for urethritis are incorporated into public health formularies and STI treatment programs across multiple regions, which supports stable baseline demand but also reinforces price discipline. In parallel, API supply chains for widely used antibiotics depend on established global manufacturing routes, with generic competition driving cost efficiencies in production. For commercial teams, these realities mean that volume growth can be paired with margin compression unless product strategy accounts for channel economics, tender dynamics, and programmatic procurement.
Supply-side resilience is also increasingly strategic. The market relies on mature production ecosystems, but demand timing, regional availability, and regulatory expectations can create localized constraints or opportunity pockets. In this context, the research evaluates not only what is sold, but how products move through institutional and retail ecosystems, which channels are expanding, and where access models may shift as patient behavior and digital fulfillment continue to evolve.
What the Full Study Delivers: Decision-Oriented Intelligence
Our Worldwide Urethritis Drugs Market research is built for practitioners who need more than top-line forecasts. It is structured to support product strategy, commercial planning, market entry evaluation, and competitive response. The study translates epidemiological and regulatory context into market-level implications, then drills into the segments and channels that matter for operational execution.
Inside the report, readers will find:
- A full market sizing and forecast framework spanning the 2020-2025 historical period and the 2026-2032 outlook, with USD-denominated valuation and growth decomposition
- Segment-level analysis across therapeutic categories and distribution channels, with emphasis on volume pathways, channel economics, and adoption dynamics
- Geographic assessment that identifies where demand is concentrated, where expansion is most plausible, and how regional protocols and programs shape market behavior
- Competitive profiling of leading global and generic manufacturers, covering product relevance, portfolio orientation, and strategic positioning within guideline-driven treatment environments
- Analysis of recent regulatory and clinical developments and their likely influence on treatment standards, formulary decisions, and competitive differentiation
- Scenario-based considerations that help teams evaluate uncertainty around resistance trends, guideline updates, reimbursement shifts, and supply chain conditions
The study is designed to answer 2026-specific questions: Where should sales and market access resources be prioritized? Which categories are most exposed to pricing pressure, and which may support stronger positioning? How should companies interpret evolving STI treatment guidance in commercial terms? Which competitors are likely to defend share through cost leadership, and which are positioned to create differentiation through newer options or portfolio breadth? By connecting market structure with competitive behavior and policy context, the research gives teams a defensible basis for planning across short-term execution and mid-term strategy.
Strategic Implications for 2026 Decision-Making
Entering 2026, successful participation in the urethritis drugs market will depend on three capabilities: reading guideline-driven demand accurately, managing channel and pricing dynamics with discipline, and anticipating where innovation or resistance trends alter the value map. Aggregate growth is supportive, but the real differentiator is how well a company aligns its portfolio, access strategy, and supply posture with the way treatment protocols and reimbursement structures are evolving.
For innovators, the opportunity lies in converting clinical differentiation into durable positioning. Where newer options address resistance concerns, tolerability, or dosing convenience, the strategic task is to demonstrate fit with stewardship expectations and to secure the formulary and procurement relationships that convert clinical relevance into realized demand. For generic manufacturers, the priority is to protect availability, manage cost structures, and navigate programmatic procurement without eroding quality or reliability. For all participants, channel strategy matters: hospital, retail, and online pathways are not interchangeable, and each responds differently to prescription behavior, reimbursement policy, and access programs.
The wider lesson is that market intelligence in this space must be multidimensional. A single growth rate or total market figure is insufficient for planning. Decision-makers need to understand how therapeutic segmentation interacts with channel economics, how resistance trends influence preferred regimens, how guidelines steer volume, and how competitor portfolios shape negotiation dynamics. The full study is built to provide that integrated view.
Access the Full Intelligence
This article has outlined the strategic logic behind the Worldwide Urethritis Drugs Market research and the major forces shaping the 2026-2032 outlook. The detailed segmentation, competitive profiles, channel analysis, and scenario frameworks necessary for concrete commercial decisions are developed in the full report. For executives seeking to translate market momentum into targeted action, the complete study provides the depth required to plan with confidence.
To access the complete worldwide urethritis drugs market research, including full segmentation detail, competitive benchmarking, and forecast breakdowns, visit the PW Consulting report page for this study.
Worldwide Urethritis Drugs Market
For detailed analysis of this topic, please visit the official page: Worldwide Urethritis Drugs Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com