

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global Automotive ISOFIX Mounts Reach $1.05B in 2025, Expanding to $1.6B by 2032 at 6.25% CAGR

Strategic Imperatives in the Global Automotive ISOFIX Mounts Market: Navigating Growth and Compliance Through 2032
The automotive safety ecosystem is undergoing a fundamental transformation, driven by rigorous regulatory frameworks and an increasing consumer demand for child passenger safety. At the heart of this evolution lies the ISOFIX mounting system, a standardized attachment mechanism that has become critical for securing child restraint systems within vehicles. For industry stakeholders, understanding the trajectory of the Automotive ISOFIX Mounts Market is not merely an exercise in data analysis; it is a strategic necessity for capital allocation, product development, and supply chain resilience.
Our latest comprehensive study, the Worldwide Automotive ISOFIX Mounts Market research, offers a granular view of this sector. This article serves as a strategic briefing, highlighting the macro-economic drivers and regulatory currents shaping the landscape from 2026 through 2032. While we outline the broad contours of opportunity here, the full depth of segmentation, competitive intelligence, and quantitative forecasts is reserved for our detailed report, designed to equip decision-makers with actionable intelligence.
Market Trajectory and Financial Outlook
The financial narrative of the ISOFIX mounts market reflects a steady upward trend, underpinned by vehicle production growth and mandatory safety installations. Analyzing historical data from 2020 to 2025 provides a baseline for understanding market maturity. In 2020, the global market revenue stood at approximately 785.4 million USD. Over the subsequent five years, the market experienced consistent expansion, reaching 1050.0 million USD by the base year of 2025.
Looking forward, the forecast period from 2026 to 2032 suggests continued momentum, albeit with varying rates of acceleration across different phases. The market is projected to surpass the 1.6 billion USD mark by 2032. This growth trajectory is supported by a Compound Annual Growth Rate (CAGR) of 6.25 percent during the forecast period. Such figures indicate a mature yet expanding market where volume growth is often tied to regulatory mandates in emerging automotive hubs and the replacement cycle in established markets.
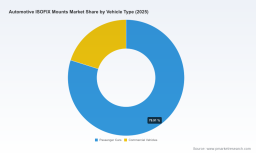
It is crucial for strategic planners to note that while the aggregate numbers paint a picture of health, the distribution of this value is heavily influenced by regional manufacturing capabilities and vehicle type segmentation. The shift from historical stability to future expansion requires companies to align their capacity planning with these projected revenue milestones, ensuring that infrastructure investments match the anticipated demand surge in the latter half of the decade.
Regulatory Landscape as a Growth Catalyst
Regulations are the primary engine driving standardization and, consequently, market demand for ISOFIX components. The industry is currently navigating a complex web of international safety standards that dictate design specifications and installation protocols.
UNECE Standards and i-Size Mandates
In Europe and many other jurisdictions, the United Nations Economic Commission for Europe (UNECE) regulations hold significant sway. Within UNECE R129, commonly known as i-Size, ISOFIX is mandatory for the i-Size category. This regulation aims to ensure universal vehicle compatibility and significantly reduce incorrect installations, which have historically been a major safety risk. The mandate creates a compliance-driven demand where vehicle manufacturers must equip cars with standardized anchor points, and child seat producers must design around these fixed points.
Furthermore, the evolution of these standards is ongoing. During the GRSP-77 session in May 2025, there was discussion on the potential evolution of ISOFIX 3.0. Building on 30 years of the standardized attachment system, these discussions signal that the technology is not static. Companies must remain agile to adapt to potential iteration in mounting mechanisms or strength requirements that could arise from these standardization bodies.
NHTSA and Side-Impact Protection
In the United States, the National Highway Traffic Safety Administration (NHTSA) continues to tighten safety requirements. Ongoing implementation preparations for FMVSS 213a, focusing on side-impact protection standards, are affecting child restraint systems that utilize ISOFIX mounts. This standard requires enhanced side-impact testing for child car seats under 40 pounds. The compliance date has been extended to December 5, 2026, which impacts the design and validation of ISOFIX-compatible restraints.
This regulatory update creates a specific pressure point for manufacturers. It is not enough to simply meet anchorage strength requirements; the interaction between the mount and the restraint system must withstand higher lateral forces. Anchorage strength and positioning must meet specific ECE R44/ECE R129 and FMVSS requirements to prevent anchorage failure or seat damage during use. For component suppliers, this means material science and structural integrity testing are becoming more critical than ever before.
Competitive Landscape and Key Players
The market structure is characterized by a moderate level of concentration, with key players holding significant sway over supply chains and technological standards. Our analysis indicates a CR3 of 42.5 percent and a CR5 of 58.8 percent, suggesting that while there are dominant entities, there is still room for specialized manufacturers and regional players to capture value.
The competitive environment is defined by companies that specialize in the precision engineering of safety components. Leading entities include:
- Holmbergs (Sweden): This company specializes in ISOFIX/LATCH connectors, arms, straps, tethers, and adjusters. They supply global child car seat manufacturers, focusing on the secure vehicle anchoring ecosystem. Their strategic position lies in their integration with child seat producers who require high-reliability connectors.
- Ningbo Welldon Infant and Child Safety Technology Co., Ltd. (China): As a manufacturer of ISOFIX mounting points, anchors, and related child safety seat components, Welldon represents the significant manufacturing capacity located in Asia. Their focus on automotive applications makes them a key supplier for vehicle OEMs and tier-one safety component integrators.
- IMMI (United States): IMMI produces ISOFIX anchorages, LATCH attachments, snap hooks, and child seating components. They are notable for their compliance with global safety standards including FMVSS and ECE. Their location in the US positions them strategically to navigate North American regulatory changes such as FMVSS 213a.
- Quanzhou Kwok Shing Automotive Subassembly Co., Ltd. (China): This firm supplies ISOFIX systems and rigid baby car seat components as automotive subassemblies. Their role highlights the trend towards modular subassemblies that can be integrated directly into vehicle production lines or child seat manufacturing processes.
These companies are not merely competing on price; they are competing on certification, reliability, and the ability to adapt to evolving regulatory standards. The interplay between Swedish design specialization, American regulatory compliance expertise, and Chinese manufacturing scale defines the current competitive dynamics. Strategic partnerships between vehicle manufacturers and these component suppliers are essential to ensure that the final assembly meets the rigorous crash load requirements.
Technical Dynamics and Material Considerations
The engineering behind ISOFIX mounts is driven by the need for structural integrity under crash loads. ISOFIX mounts and anchors are primarily constructed from high-strength steel or alloy steel. This material choice is non-negotiable, as the components must withstand significant force without deformation or failure during an accident.
The technical specifications are tightly linked to the regulatory environment. ISOFIX anchorage strength and positioning must meet specific ECE R44/ECE R129 and FMVSS requirements. Any deviation can lead to anchorage failure or seat damage during use, posing severe liability risks for automakers and component suppliers. As vehicle designs evolve towards lighter materials and different chassis structures, the integration of these steel mounts becomes a challenge in itself. Engineers must ensure that the mounting points do not compromise the structural integrity of the vehicle floor or seat rails while still providing the rigid connection required for child safety.
Moreover, the supply chain for these high-strength materials is subject to global commodity fluctuations. Strategic procurement strategies are required to mitigate cost volatility without compromising the quality standards mandated by safety regulations.
Strategic Focus for OEMs and Aftermarket
The market is broadly divided by sales channel, with distinct implications for different business models. The Original Equipment Manufacturer (OEM) channel represents the larger portion of the market revenue. This segment is driven by vehicle production volumes and the mandatory inclusion of ISOFIX points in new car models. For suppliers targeting this segment, long-term contracts and qualification processes with automotive OEMs are critical. The revenue flow here is stable but subject to the cycles of the automotive industry.
Conversely, the Aftermarket segment serves a different need. While smaller in total revenue compared to OEM, it represents a vital channel for retrofitting older vehicles or replacing damaged components. As the fleet of vehicles equipped with ISOFIX grows, the aftermarket demand evolves from installation assistance to replacement parts for wear and tear or post-accident repair. Companies operating in this space must maintain broad compatibility across various vehicle models and generations.
Understanding the split between these channels is vital for revenue forecasting. While the OEM channel drives volume through new car sales, the aftermarket offers recurrent revenue opportunities and niche customization possibilities. A balanced portfolio strategy often involves servicing both streams to mitigate the risk of production slowdowns in the automotive sector.
Regional Growth Vectors
Geographically, the market exhibits distinct characteristics based on vehicle ownership rates and regulatory adoption. Asia Pacific remains a critical region, driven by high vehicle production volumes and increasing awareness of child safety standards. Europe continues to be a mature market where regulations like i-Size drive consistent demand for compliant mounts. North America presents a specific regulatory environment focused on FMVSS compliance and side-impact enhancements.
Latin America and the Middle East and Africa represent emerging vectors where vehicle fleet modernization and the import of safety-standard-compliant vehicles are gradually increasing the uptake of ISOFIX systems. However, the pace of adoption in these regions is influenced by economic factors and the penetration of standardized child restraint systems. Strategic expansion into these regions requires a nuanced understanding of local regulatory enforcement and consumer behavior regarding child safety.
Conclusion: The Value of Detailed Intelligence
The Automotive ISOFIX Mounts Market is at a intersection of regulatory pressure, technological evolution, and steady market growth. The projected increase to over 1.6 billion USD by 2032 offers significant opportunity, but realizing this value requires navigating complex compliance landscapes and supply chain dynamics. The upcoming changes in FMVSS 213a and potential evolutions in UNECE standards mean that static strategies will fail.
Engine Mounts Market
For executives and strategy teams, the high-level trends are clear, but the path to capturing market share lies in the details. Which specific vehicle segments are driving the highest growth rates? How do supply chain vulnerabilities in specific regions impact lead times? What are the precise design constraints imposed by the new side-impact regulations?
Worldwide Automotive ISOFIX Mounts Market
Our full Worldwide Automotive ISOFIX Mounts Market research report delves into these specifics. It provides the segmented data, the competitive profiles, and the granular forecast models necessary to build a robust strategic plan. We invite you to access the complete study to unlock the full depth of this intelligence and ensure your organization is positioned to lead in the next era of automotive safety.
For detailed analysis of this topic, please visit the official page: Worldwide Automotive ISOFIX Mounts Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com