

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Telecom Security Software to Hit $15.5B in 2025, Grow at 13% CAGR Through 2032

Global Telecom Security Software Market: Strategic Intelligence for 2026 Decision-Making
The telecommunications industry is currently navigating a transformative period defined by rapid technological shifts and escalating security challenges. As networks evolve toward 5G standalone architectures and beyond, the surface area for potential cyber threats expands proportionally. In this environment, security software is no longer a peripheral utility but a core component of network infrastructure and business strategy. PW Consulting's latest Worldwide Security Software in Telecom Market research provides a comprehensive lens through which enterprises and investors can understand these dynamics. This report is designed to equip decision-makers with the actionable intelligence required to navigate the forecast period from 2026 through 2032.
The market trajectory observed over the past five years indicates a robust growth pattern, driven by the urgent need to secure digital infrastructure against sophisticated attacks. Historical data from 2020 to 2025 shows a consistent upward trend in market valuation, reflecting the increasing prioritization of cybersecurity within telecom operations. Looking forward, the market is projected to continue this momentum, with a compound annual growth rate of approximately 13 percent across the forecast horizon. This growth is not merely a function of inflation or expanded connectivity but represents a fundamental structural shift in how security is integrated into network design, deployment, and management.
Market Scale and Growth Trajectory
Understanding the magnitude of this opportunity is essential for capital allocation and strategic planning. The global revenue for security software in telecom has seen significant expansion, moving from a baseline in the mid-eight thousands millions USD in 2020 to surpassing the fifteen thousands millions USD mark by 2025. This historical performance sets the stage for a forecast period where valuations are expected to climb substantially, reaching over thirty-six thousands millions USD by 2032. Such figures underscore the critical nature of security investments as telecom operators transition into techco models, offering cybersecurity offerings alongside traditional connectivity, cloud, and IoT services.
This growth trajectory is supported by several converging factors. The proliferation of edge computing and network slicing creates new vulnerabilities that require specialized software interventions. Furthermore, the regulatory landscape is tightening globally, with governments implementing cybersecurity regulations, trusted vendor policies, and data localization requirements. These compliance drivers compel operators to invest heavily in compliant security software solutions, thereby fueling market expansion. The report details how these macroeconomic and regulatory forces interact to shape demand curves over the next seven years.
Segmentation and Deployment Dynamics
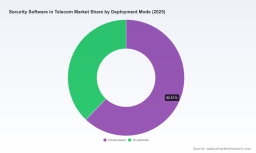
While the overall market size provides a high-level view, the underlying segmentation reveals where the greatest opportunities and risks lie. The market is divided across various dimensions, including deployment mode and solution type. The shift toward cloud-based security solutions is prominent, reflecting the industry's broader migration to virtualized network functions and cloud-native architectures. This deployment mode accommodates the flexibility required for modern telecom environments, though on-premise solutions remain significant for specific high-security or latency-sensitive use cases.
Solution types vary from network security and endpoint protection to identity and access management and cloud security solutions. Each category addresses distinct threat vectors within the telecom ecosystem. For instance, network security remains a dominant focus area given the criticality of protecting the core infrastructure from intrusion. However, as service providers expand their B2B portfolios, identity management and cloud security are gaining traction. The report provides deep dives into each segment, analyzing adoption rates, technological maturity, and regional preference patterns without exposing sensitive proprietary estimates in this summary.
Geography also plays a crucial role in market dynamics. Different regions exhibit varying levels of maturity, regulatory pressure, and investment capacity. North America, Europe, and Asia Pacific represent significant portions of the market, each driven by unique local factors such as digital sovereignty initiatives or infrastructure modernization plans. Latin America and the Middle East and Africa are also contributing to the growth, albeit at different scales. The full research document breaks down these regional nuances, offering specific insights into local market conditions, key regulatory frameworks like the EU Digital Networks Act, and the impact of legal shifts such as recent court rulings on net neutrality that may influence service provider strategies.
Competitive Landscape and Key Players
The competitive environment in telecom security software is characterized by a mix of specialized security vendors and large telecommunications infrastructure providers. Market concentration indicates that a handful of major players command a significant share of the revenue, yet there is ample room for niche innovators and regional specialists. The top five companies collectively hold a substantial portion of the market, reflecting the importance of scale, brand reputation, and integrated solution portfolios in this sector.
Key companies such as Cisco Systems, Palo Alto Networks, and Fortinet are central to the landscape, offering comprehensive solutions ranging from secure firewalls to AI-driven security platforms tailored for 5G and enterprise networks. These vendors are continuously innovating, with recent developments highlighting a focus on sovereign AI security frameworks and fabric-based AI agents. For example, recent product releases in early 2026 have introduced new innovations for AI and modern networks, emphasizing secure AI controls and simplified SD-WAN for telecom environments. Such movements signal a trend where security vendors are embedding intelligence directly into the network fabric to handle evolving threats autonomously.
Telecom infrastructure giants like Ericsson and Nokia also play a pivotal role, providing 5G core security solutions and cloud packet core security integrated directly into the hardware and software stacks operators rely on. Their approach often focuses on built-in security features for RAN, core, and transport networks, ensuring security is baked into the infrastructure from the outset. Meanwhile, companies like Huawei Technologies and Juniper Networks contribute extensive portfolios covering everything from cloud fabric security to AI-driven routing solutions optimized for service providers.
The landscape also includes specialized players focusing on specific telecom security niches. Check Point Software Technologies offers advanced threat prevention suitable for network perimeters, while Allot specializes in traffic management and DDoS protection for mobile networks. P1 Security stands out with a focus exclusively on telecom security software for 5G, 4G, and OpenRAN attack simulation. Additionally, firms like F5 Networks and Trend Micro provide application security and hybrid cloud security solutions applicable to telecom environments. The report profiles these companies in detail, analyzing their recent partnership expansions, product launches, and strategic positioning. For instance, recent announcements at major industry events have highlighted expanded security ecosystems aimed at protecting AI factories in telecom networks, indicating a strategic pivot toward securing the artificial intelligence infrastructure that powers modern networks.
Telecommunications Market
Industry Dynamics and Regulatory Context
Macro-level dynamics are reshaping the market just as much as technological innovation. The shift toward techco models means telecom operators are increasingly competing with traditional IT security firms, blurring the lines between connectivity and security services. This convergence creates both opportunities for revenue diversification and challenges in maintaining operational focus. Furthermore, the threat landscape remains volatile. Threat intelligence reports from late 2025 warned that telecom threats observed involving new technologies are expected to persist into 2026, necessitating proactive rather than reactive security postures.
Regulatory pressure is a critical driver in this environment. In Europe, advancements in the Digital Networks Act aim to stimulate investment in next-generation networks while addressing digital sovereignty and cybersecurity requirements. Simultaneously, the EU has set targets for the transition to quantum-safe cryptography in telecommunications, pushing vendors and operators to future-proof their encryption standards. Globally, governments are implementing trusted vendor policies and data localization requirements that affect how security software is deployed and sourced. In the United States, legal challenges regarding net neutrality rules have added layers of complexity to network management strategies, indirectly influencing security architecture decisions.
These regulatory and dynamic shifts create a complex operating environment. Companies must navigate compliance hurdles while ensuring their security solutions remain effective against evolving threats. The research report analyzes how these factors influence market growth, vendor selection criteria, and deployment strategies across different regions. It provides a framework for understanding how regulatory compliance can be turned into a competitive advantage rather than viewed solely as a cost center.
Worldwide Security Software in Telecom Market
Strategic Value for 2026 Decision-Makers
For enterprises operating in or investing in the telecom sector, access to granular, forward-looking data is vital. This research offers more than just high-level numbers; it delivers an operational blueprint for the forecast period. Decision-makers can utilize the insights to refine their product development roadmaps, identify partnership opportunities, and assess market entry risks. The detailed segmentation analysis helps in pinpointing high-growth niches, while the competitive profiling allows organizations to benchmark their strategies against leading players.
The inclusion of recent developments, such as partnership expansions and product releases from key vendors, ensures that the intelligence is current and actionable. Understanding the timing and nature of these moves can provide early signals of market shifts. For example, the focus on sovereign AI security frameworks suggests a growing demand for localized, trusted security solutions that protect AI workloads within telecom networks. Recognizing such trends early allows strategies to align with emerging demands before the market becomes saturated.
Furthermore, the report addresses the consolidation trends reflected in market concentration metrics. Knowing the share held by the top three or five players helps investors and competitors understand the barriers to entry and the potential for disruption by smaller, agile firms. The balance between established incumbents and specialized innovators is a key theme explored in the analysis, offering guidance on where collaboration or acquisition might yield the highest returns.
Ultimately, the Worldwide Security Software in Telecom Market research is designed to reduce uncertainty. In a sector defined by rapid change, regulatory flux, and sophisticated threat actors, having a reliable source of comprehensive data is a strategic asset. The report enables stakeholders to move beyond intuition and make evidence-based decisions that align with long-term growth objectives.
Accessing Complete Intelligence
This overview serves as a preview of the depth and breadth contained within the full PW Consulting report. While the macro trends and competitive dynamics outlined here provide a solid foundation for understanding the market, the detailed data required for precise planning is available in the complete document. The full report includes granular segmentation splits, specific regional revenue estimates, detailed company profiles with financial and strategic metrics, and extensive analysis of the regulatory landscape across all covered regions.
Readers are encouraged to access the source webpage to download the complete study. There, you will find the specific data points necessary to validate assumptions, build financial models, and craft targeted go-to-market strategies. In an industry where timing and accuracy are paramount, the complete intelligence offered by this research provides the clarity needed to navigate the complex telecom security landscape from 2026 through 2032. The insights contained within are updated to reflect the latest developments and market conditions, ensuring that your strategic decisions are based on the most current information available.
For detailed analysis of this topic, please visit the official page: Worldwide Security Software in Telecom Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com