

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Category: market research
PW Consulting Report: Global Education Computing Devices To Hit $57.9B By 2032 With 14.5% CAGR
By pmarketresearch, 2026-09-16
Strategic Intelligence for the Digital Classroom: Inside the Worldwide Education Computing Devices Market
The global education technology landscape is undergoing a profound transformation. As schools and universities pivot from emergency remote learning to sustained, technology-enabled pedagogical models, the procurement of computing devices has become a cornerstone of institutional strategy. For executives, procurement leaders, and investors, understanding the trajectory of this market is no longer optional. It is a prerequisite for capital allocation, product roadmap planning, and supply chain resilience. Our recently published Worldwide Education Computing Devices Market research study delivers a comprehensive, data-rich blueprint of this evolving sector. This article outlines the strategic value of the report, previews its analytical architecture, and demonstrates how decision-makers can leverage its findings to navigate the 2026–2032 forecast horizon with confidence.
A Market Poised for Sustained Expansion
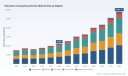
The education computing devices sector has demonstrated remarkable resilience and growth momentum over the past half-decade. Historical revenue data from 2020 through 2025 reveals a sector that recovered swiftly from early-pandemic supply chain disruptions and then accelerated into a phase of structural expansion. In 2020, global market revenue stood at approximately 15.2 billion USD. By 2025, that figure had climbed to 22.45 billion USD, reflecting a compound trajectory driven by renewed institutional budgets, refreshed device fleets, and the normalization of digital-first learning environments.
Looking forward, our forecast model projects that the market will reach roughly 25.25 billion USD in 2026 and continue its upward climb through 2032, when total revenue is expected to surpass 57.9 billion USD. This growth path translates to a forecast-period compound annual growth rate of 14.5 percent. Such a rate places education computing devices among the more dynamic hardware verticals in the broader technology ecosystem. The acceleration is not merely a function of post-pandemic catch-up; it is rooted in durable shifts in curriculum design, administrative digitization, and the integration of artificial intelligence into classroom workflows.
It is important to emphasize that these headline figures represent the aggregated global total. The underlying distribution across geographies, device categories, and end-user segments contains significant variation that can materially impact regional strategy, pricing architecture, and inventory planning. Our full report dissects these layers in granular detail, providing the precision required for localized execution while preserving the macro perspective necessary for board-level strategic planning.
What the Report Delivers: A Framework for Action
A market research publication is only as valuable as its actionable granularity. Our study is engineered to serve as an operational reference rather than a high-level overview. The report is structured around several interlocking analytical modules, each designed to answer specific strategic questions facing education technology stakeholders.
- Historical Reconstruction and Baseline Calibration: We reconstruct revenue performance from 2020 through 2025 across multiple dimensions, establishing a verified baseline that accounts for procurement cycles, policy shifts, and supply-side constraints. This historical lens enables clients to benchmark their own performance against market-wide trends and identify periods of outperformance or underperformance.
- Forward Forecast with Scenario Sensitivity: The 2026–2032 projection framework incorporates multiple growth drivers, including device refresh rates, curriculum modernization mandates, and emerging AI-enabled classroom requirements. The forecast is presented with clear methodological transparency so that readers can test assumptions against their own internal models.
- Device-Type Architecture: The study segments the market across laptops, Chromebooks, tablets, and desktop/hybrid units. Each category is evaluated in terms of adoption momentum, total cost of ownership considerations, and suitability for distinct instructional models. The analysis highlights how procurement preferences are evolving as schools balance performance, manageability, and budget constraints.
- End-User Segmentation: K-12 education and higher education represent distinct buying cultures, funding mechanisms, and deployment scales. Our report maps the demand dynamics within each segment, revealing where volume concentration lies and which institutional profiles are driving incremental growth.
- Competitive Positioning and Mobility Assessment: We profile the major participants shaping the market, examining product strategies, ecosystem leverage, and recent commercial moves. The analysis goes beyond static company descriptions to evaluate how firms are positioning themselves for the next wave of education-focused hardware and software integration.
- Regulatory and Infrastructure Context: Technology procurement does not occur in a vacuum. The report integrates relevant policy developments, connectivity considerations, and infrastructure cost signals that influence device accessibility, total deployment cost, and long-term sustainability for educational institutions.
Competitive Landscape: Who Shapes the Market and How
The education computing devices market is characterized by a concentrated yet dynamic competitive field. Our concentration analysis indicates that the top three firms collectively account for approximately 42.15 percent of total market revenue, while the top five firms represent roughly 64.8 percent. This level of concentration suggests that scale, brand trust, and institutional relationship depth remain powerful differentiators. At the same time, the presence of multiple well-capitalized players competing across overlapping product categories ensures continuous innovation in durability, manageability, and price-to-performance ratios.
Several corporations stand out for their dedicated education-focused portfolios and deployment track records. HP Inc. has built a strong reputation for durable, education-specific Chromebooks and laptops that are widely deployed in K-12 1:1 programs globally. Their education-optimized models emphasize long battery life and centralized manageability, attributes that align closely with the operational realities of large school districts. Dell Technologies Inc. similarly offers Chromebooks and laptops tailored for education, with a pronounced focus on durability, serviceability, and integration for school deployments. Dell's footprint includes substantial institutional contracts, such as its involvement in large-scale public school procurement initiatives.
Lenovo Group Limited supplies education Chromebooks and laptops designed for K-12 durability, affordability, and increasingly AI-enhanced features. Their recent product cadence reflects a deliberate push toward connectivity improvements and classroom-ready form factors. Acer Inc. delivers budget-friendly Chromebooks and education laptops optimized for student use, with long battery life and touchscreen options that appeal to cost-conscious procurement offices. ASUTeK Computer Inc. (ASUS) produces education-focused Chromebooks and Windows laptops that emphasize inclusivity, rugged design for students with special educational needs, and AI features, as evidenced by their recent education portfolio unveilings.
Beyond the traditional hardware manufacturers, platform and ecosystem players exert considerable influence. Apple Inc. provides iPads, MacBooks, and ecosystem tools for education, supported by initiatives that include partnerships for coding and robotics in schools and managed device deployment capabilities. Samsung Electronics Co., Ltd. offers Galaxy Chromebooks, tablets, and interactive displays for classrooms, including premium AMOLED models with AI integration tailored for education. Google LLC, through its ChromeOS and Chromebook ecosystem, provides management tools, AI features, and devices optimized for K-12 education, with a substantial installed base already deployed globally.
Recent commercial activity underscores the pace of evolution. In early 2026, ASUS unveiled an expanded education portfolio at a major industry event, introducing Windows laptops, Chromebook series, detachable models, and AI-enhanced devices focused on durability, accessibility, zero-touch enrollment, and efficient deployment. Around the same period, Lenovo launched new Chromebook series featuring advanced connectivity standards, targeting education durability and performance. Separately, a major municipal procurement initiative announced the distribution of hundreds of thousands of LTE/5G-connected Chromebooks to K-12 public school students across a large network of schools, signaling the continued importance of cellular connectivity in closing digital access gaps. These moves illustrate how product launches, connectivity integration, and large-scale deployment contracts are reshaping the competitive playing field.
Market Dynamics: Policy, Infrastructure, and the Connectivity Imperative
Hardware adoption in education is intimately tied to the policy and infrastructure environment. Several developments in recent months carry direct implications for device procurement strategies and long-term market trajectories.
Worldwide Education Computing Devices Market
First, the regulatory landscape around broadband and internet access continues to evolve. A recent appellate court decision struck down a prior federal net neutrality order, reclassifying broadband as an information service and shifting potential regulatory oversight to state-level bodies or legislative action. For education stakeholders, this development introduces uncertainty around equitable access to digital learning content. However, it also intersects with a broader policy conversation: public interest exceptions to net neutrality rules in various jurisdictions allow zero-rating or prioritized access for educational content to support digital learning initiatives. Institutions and vendors alike must monitor how these exceptions are applied, as they can influence device utility, content delivery costs, and the perceived value of connectivity-enabled hardware.
Second, infrastructure cost dynamics are entering the strategic calculus. Major technology firms have recently committed to covering the costs of new power generation and grid upgrades for data centers to prevent increases in residential electricity prices. While this pledge is primarily directed at data center operations, it signals a broader recognition that the digital infrastructure underpinning cloud-based education tools, device management platforms, and AI features depends on reliable and affordable power. Over time, these infrastructure commitments may help stabilize the operational environment for cloud-reliant education deployments, though regional variability in electricity pricing and grid capacity will remain relevant for large-scale device rollouts.
Third, the connectivity gap remains a persistent strategic concern. The distribution of LTE/5G-connected devices to students in large public school systems reflects a policy-driven effort to ensure that learning can continue regardless of home broadband availability. For vendors and institutional buyers, this trend reinforces the importance of cellular-equipped devices, subscription management models, and partnership structures that bundle hardware with connectivity services. It also highlights the need for procurement frameworks that account for total cost of ownership over multiple years, rather than focusing solely on upfront hardware expenditure.
Strategic Implications for 2026 Decision-Making
The convergence of strong market growth, concentrated competition, and evolving policy and infrastructure conditions creates both opportunity and complexity. Leaders who engage with this market in 2026 must navigate several interrelated strategic questions. How should device portfolios be balanced across categories to match instructional needs and budget realities? Where do regional demand patterns justify localized supply chain or distribution investments? How can procurement teams evaluate competing device and ecosystem offerings without losing sight of long-term manageability and total cost of ownership? And how should organizations position themselves for the integration of AI features, connectivity upgrades, and accessibility requirements into next-generation education hardware?
Our report is designed to equip decision-makers with the evidence base required to answer these questions. By combining macro-level revenue trajectories with category-level insight, competitive profiling, and contextual analysis of regulatory and infrastructure developments, the study provides a multi-layered view of the market. This allows clients to move beyond generic industry narratives and develop strategies that are calibrated to their specific operating context, risk tolerance, and growth ambitions.
Access the Full Intelligence
The Worldwide Education Computing Devices Market research study offers a complete, methodologically rigorous portrait of a sector that is expanding at a compelling pace and being reshaped by technology, policy, and institutional demand. The summary figures and strategic themes outlined here provide a preview of the report's scope and analytical depth, but they are only a starting point. The full study contains detailed segmentation breakdowns, regional demand analysis, category-level revenue trajectories, competitive benchmarking, and forward-looking scenario discussions that are essential for precise planning.
AI Learning Devices for Kids Market
For executives, procurement leaders, investors, and strategy teams seeking to make informed decisions in 2026 and beyond, the complete report delivers the granularity and context needed to translate market intelligence into action. We invite you to access the full study to explore the data, models, and insights that will support your next strategic move in the education computing devices market.
For detailed analysis of this topic, please visit the official page: Worldwide Education Computing Devices Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Automotive Water Separation System Market to Reach $2,059.53M by 2032 at 5.02% CAGR
By pmarketresearch, 2026-09-16
Navigating the Automotive Water Separation System Market: Strategic Imperatives for 2026 and Beyond
As global automotive engineering pivots toward higher efficiency, stricter emissions compliance, and increasingly complex fuel architectures, the water separation system has evolved from a passive maintenance component to a mission-critical engineering subsystem. Water contamination in diesel and heavy-duty fuel streams accelerates injector wear, triggers microbial growth in storage infrastructure, and compromises combustion stability. With regulatory frameworks tightening and powertrain architectures evolving, the strategic importance of reliable water separation has never been more pronounced. This article outlines the macro trajectory of the market, the forces reshaping competitive dynamics, and how PW Consulting’s latest Worldwide Automotive Water Separation System Market study equips leadership teams with the intelligence required to navigate 2026 decision-making with precision.
Market Trajectory: A Decade of Structured Growth and Strategic Inflection
The global automotive water separation system market has demonstrated consistent expansion over the past half-decade, driven by replacement demand, emissions-driven design mandates, and the continuous modernization of commercial fleets. Historical revenue evaluations from 2020 through the base year of 2025 reveal a disciplined upward arc, with valuations moving from the 1,145 million USD range to approximately 1,462 million USD in the most recent assessment period. This progression reflects not only incremental volume growth but also the structural premiumization of filtration architectures as OEMs and aftermarket channels prioritize higher separation efficiency over commoditized cost profiles.
Looking forward, the forecast window spanning 2026 through 2032 projects a sustained compound annual growth rate of roughly 5.02 percent. Under this trajectory, the market is expected to cross the 1,560 million USD threshold in 2026 before advancing toward the 2,060 million USD vicinity by the terminal forecast year. Such a growth cadence signals a mature but still expanding addressable space, where incremental gains will emerge from technology upgrades, regional fleet turnover cycles, and the integration of smarter sensing and monitoring capabilities into traditional mechanical separation assemblies. For strategic planners, this macro arc provides a foundational baseline: growth is real and measurable, but its distribution across vehicle classes, geographic corridors, and component categories demands granular, scenario-based intelligence rather than blanket assumptions.
While the aggregate numbers convey directional confidence, the real strategic value lies beneath the surface. Companies that attempt to allocate capital, capacity, or supplier negotiations based solely on headline valuations risk missing the uneven pacing of regional adoption, the divergent replacement cycles of heavy commercial versus passenger platforms, and the shifting cost structures of specialty media and electronic subcomponents. The full report deconstructs these layers without relying on simplified averages, enabling executives to align procurement, R&D, and go-to-market strategies with the specific demand pockets that will actually drive margin in the coming years.
Competitive Landscape: Ten Navigators Shaping the Filtration Ecosystem
The industry is anchored by a concentrated group of technically rooted manufacturers that have built decades of material science, fluid dynamics expertise, and direct OEM relationships. A handful of global leaders command meaningful share, while a broader field of specialized suppliers competes through niche engineering advantages, regional service networks, and application-specific validation credentials. Understanding who holds leverage where, and why, is essential for anyone evaluating partnership structures, substitution risks, or supply chain exposure.
American-headquartered firms continue to set the pace in heavy-duty and off-road applications. Donaldson Company has reinforced its position with media innovations tailored to low-sulfur diesel environments, most recently advancing its filtration media portfolio to improve separation efficiency under tighter fuel specifications. Parker Hannifin, operating through its Racor division, has expanded its footprint by securing supplier nominations for next-generation truck platforms, embedding its Aquabloc media technology into integrated fuel management architectures. Meanwhile, Cummins Inc., through its Fleetguard division, continues to validate its separation hardware against stringent engine-level cleanliness targets, demonstrating the direct linkage between water management and downstream emissions and performance commitments.
On the European side, engineering heritage and OEM integration depth define the competitive rhythm. Mann+Hummel and Mahle both deliver multifunction filtering architectures that combine water extraction with particulate management, supporting the gradual convergence of fuel preparation and emissions compliance. Hengst SE focuses heavily on heavy-duty diesel platforms, while Sogefi Group leverages its modular system approach to serve global OEM supply chains with standardized yet adaptable separation modules. Separ Sweden AB brings a distinct technical angle through swirl-based separation principles, offering an alternative mechanical pathway for diesel fuel conditioning in demanding applications.
Worldwide Automotive Water Separation System Market
The North American aftermarket and commercial truck ecosystem also remains highly active. Davco Technology, operating under the Eaton umbrella, continues to supply separation and filtration assemblies engineered for medium- and heavy-duty trucks, while Baldwin Filters maintains a strong pedigree in diesel-powered commercial and agricultural platforms through proven housing and bowl configurations. Together, these players illustrate a market where technical differentiation, validation credibility, and tier-one integration relationships matter far more than generic scale alone.
Recent activity underscores that this is not a static field. Product launches, joint development agreements, and validation milestones have accelerated over the past year, signaling that incumbents are actively future-proofing their portfolios against evolving fuel standards and engine cleanliness requirements. Executives evaluating vendor stability, substitution risk, or co-development opportunities need a clear map of who is investing where, which platforms are being targeted, and how recent validation events shift bargaining power in negotiations. The complete competitive assessment in the full study details these strategic alignments and the implied consequences for sourcing, partnership design, and market entry planning.
Forces Reshaping the Market: Regulation, Materials, and Technical Bottlenecks
Market dynamics in this segment are being shaped by a convergence of regulatory mandates, material economics, and technical ceilings. European fuel specifications have progressively tightened allowable water content in diesel streams, compelling OEMs and fleet operators to invest in more effective separation hardware to maintain compliance and protect downstream components. In parallel, nonroad engine standards in key jurisdictions have elevated minimum water removal efficiency expectations, effectively forcing a functional baseline above which only more advanced architectures can reliably perform.
Material-side pressures are equally important. The pricing environment for specialty media inputs, particularly glass microfiber variants used in high-efficiency coalescing elements, has experienced volatility due to supply chain constraints in borosilicate production. Such fluctuations directly affect cost planning for manufacturers and complicate margin forecasting for procurement teams that rely on stable input assumptions. At the same time, certain coalescing polymer membrane approaches are encountering practical limitations when tasked with achieving extremely low residual water thresholds required for emerging compliance frameworks. This technical ceiling is encouraging a broader exploration of hybrid designs, enhanced pre-separation geometries, and sensor-assisted monitoring that can validate performance without relying solely on incremental media upgrades.
Another important nuance is the divergence between fuel types. In gasoline direct injection applications, the inherent solubility characteristics of modern petrol mean that water separation hardware is generally not a focal requirement, which concentrates commercial attention and engineering investment on diesel and heavy-duty domains. This structural difference matters for portfolio strategy: it means growth attention, validation spend, and supplier negotiations should be weighted toward the segments where water management remains a persistent operational and compliance priority.
The interplay of regulation, raw material economics, and technology maturity creates a landscape where static planning is quickly outdated. Companies must continuously assess how new fuel standards alter the minimum viable architecture, how media cost trends influence aftermarket pricing, and whether emerging separation approaches can credibly close the gap toward next-generation cleanliness thresholds. Our report maps these dynamics into actionable scenario considerations, helping leaders distinguish transient fluctuations from durable structural shifts.
From Intelligence to Execution: How the Study Supports 2026 Decisions
For strategy, procurement, product planning, and investor relations teams, the value of a market study lies not in confirming that growth exists, but in exposing the conditions under which growth translates into profitable opportunity. The PW Consulting Worldwide Automotive Water Separation System Market research is structured to support exactly that transition from awareness to execution. Rather than offering a single static snapshot, the analysis integrates historical baseline data, multi-year forward projections, component-level segmentation, vehicle-type differentiation, and regional demand contours into a decision-ready framework.
Oil Water Separator Market
Practically, this means the study is designed to help leadership teams answer questions that generic market narratives typically leave unresolved: which component categories are absorbing the greatest value migration as designs become more integrated; where replacement cycles and fleet turnover create more predictable demand rhythms; how OEM integration priorities differ from aftermarket replacement behavior; and where competitive intensity is likely to compress price expectations versus where technical barriers sustain healthier margins. The report also provides a structured view of concentration dynamics, helping readers gauge how much market leverage is concentrated among leading participants and where opportunities exist for specialized entrants or regional challengers.
Beyond segmentation, the study incorporates an operational lens on supplier behavior, validation activity, and recent portfolio developments. By connecting product announcements, engineering partnerships, and testing milestones to broader demand trends, the analysis helps executives interpret whether a competitor’s movement represents a genuine platform shift or a tactical positioning play. This is particularly valuable when negotiating with tier suppliers, evaluating joint development proposals, or deciding whether to commit internal R&D resources toward a specific separation technology pathway.
The report is also intended to support cross-functional alignment. Finance teams can use the projection architecture to ground revenue scenarios in a defensible macro baseline. Engineering and procurement can benchmark component-level demand against raw material exposure and design migration trends. Commercial teams can identify where regional demand intensity is likely to favor localized service and inventory positioning versus where centralized supply strategies remain appropriate. The overarching objective is to replace directional assumptions with a structured intelligence base that can be directly tied to capital allocation, sourcing strategy, and product roadmap decisions.
What the Full Study Unlocks
While this overview establishes the strategic context, the complete Worldwide Automotive Water Separation System Market report delivers the detailed architecture needed to operationalize these insights. It systematically addresses the structural composition of demand, the pacing of adoption across different platform categories, and the component-level dynamics that influence pricing, sourcing, and engineering priorities. It also lays out the competitive positioning logic that separates sustained market influence from short-term promotional activity, giving readers a clearer lens through which to interpret supplier claims and partnership opportunities.
For decision-makers preparing for 2026 and the subsequent forecast horizon, the difference between a useful market summary and an actionable intelligence product is granularity with purpose. The full study is built to provide exactly that: enough analytical depth to support scenario planning, supplier evaluation, and investment prioritization, while keeping the most decisive segmentation data and strategic readouts within the structured report environment. Readers ready to move from directional confidence to precise execution will find that the detailed breakdown of market structure, competitive behavior, and forward demand logic offers a more reliable basis for committing resources where they will matter most.
The automotive water separation system market is not simply expanding; it is being redefined by compliance pressure, material economics, and design integration. In that environment, the organizations that outperform will be those that can convert market intelligence into disciplined choices about where to supply, what to engineer, whom to partner with, and how to price against a changing technical baseline. The full study is designed to make that conversion faster, clearer, and more defensible.
For detailed analysis of this topic, please visit the official page: Worldwide Automotive Water Separation System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Automotive Engine Oil Additives Market Hits $18.02B in 2025, Forecasts 3.21% CAGR to 2032
By pmarketresearch, 2026-09-16
Navigating the Next Wave: Strategic Imperatives in the Global Automotive Engine Oil Additives Market (2026–2032)
As the automotive industry accelerates toward stricter emissions mandates, advanced powertrain architectures, and evolving performance standards, the engine oil additives sector stands at a critical inflection point. For executives, product developers, and market strategists operating within the lubricants value chain, understanding the trajectory of this market is no longer optional—it is a strategic necessity. Our latest Worldwide Automotive Engine Oil Additives Market research study delivers a comprehensive, forward-looking intelligence framework designed to equip decision-makers with the actionable insights required to navigate the 2026–2032 forecast period with precision.
The global market for automotive engine oil additives has demonstrated remarkable resilience and steady expansion over the past half-decade. Valued at approximately 15.2 billion USD in 2020, the sector has grown consistently to reach an estimated 18.02 billion USD by 2025. This upward trajectory is projected to continue, with the market expected to surpass 19.18 billion USD in 2026 and ultimately approach 22.47 billion USD by 2032. Driven by a compound annual growth rate (CAGR) of 3.21 percent across the forecast horizon, the industry reflects a mature yet innovation-led landscape where incremental gains in formulation efficiency, regulatory compliance, and regional demand shifts will dictate competitive advantage.
However, top-line growth figures only tell part of the story. The real strategic value of our report lies in its granular dissection of market architecture, competitive maneuvering, and the regulatory and macroeconomic forces that will reshape sourcing strategies, pricing architectures, and product development timelines. This article serves as a strategic preview of the full research publication, highlighting the analytical depth, operational frameworks, and competitive intelligence contained within—and explaining why institutional investors, OEM formulation teams, and additive suppliers must treat this study as an essential planning instrument for the next seven years.
Market Architecture and Segmentation Dynamics
The automotive engine oil additives landscape is inherently multi-dimensional, shaped by product chemistry, vehicle application profiles, and geographically dispersed demand centers. Our research systematically maps these intersecting layers to provide a clear view of where volume concentration exists and where emerging opportunities are materializing.
When analyzing the product-type ecosystem, the market reveals a clear hierarchy of functional demand. Dispersants continue to command the largest share of additive consumption, reflecting their critical role in maintaining engine cleanliness, suspending contaminants, and preventing sludge formation across high-mileage passenger and commercial platforms. Detergents follow closely, serving as essential alkaline components that neutralize acidic combustion byproducts and protect metal surfaces. Viscosity index improvers represent another cornerstone category, enabling multi-grade formulations that balance cold-start performance with high-temperature stability. Anti-wear agents, oxidation inhibitors, and corrosion inhibitors round out the essential functional suite, with each chemistry category experiencing distinct growth pressures tied to evolving engine designs and lubricant specification upgrades. Our full report delivers precise volume and revenue mappings across these categories, allowing procurement and R&D leadership to benchmark their portfolio exposure against market-wide demand signals.
Segmentation by vehicle type further illuminates consumption patterns. Passenger cars remain the dominant application channel, driven by global fleet expansion, replacement lubricant demand, and the rapid adoption of low-viscosity, fuel-efficient formulations. Heavy commercial vehicles constitute a substantial secondary demand pillar, particularly in regions where long-haul freight, mining, and construction activities sustain steady consumption of high-performance diesel engine lubricants. Light commercial vehicles occupy a growing mid-tier segment, increasingly influenced by urban delivery logistics, last-mile electrification transition timelines, and localized emissions enforcement. By connecting vehicle-type consumption profiles to regional economic indicators and regulatory calendars, our study enables clients to anticipate category-specific demand shifts rather than react to them.
Geographic Distribution and Regional Growth Vectors
The spatial distribution of additive demand reveals a structurally imbalanced but evolving global map. Asia Pacific continues to represent the largest regional consumption base, underpinned by dense automotive manufacturing networks, expanding middle-class vehicle ownership, and aggressive localization strategies by both multinational suppliers and domestic formulators. North America maintains a robust secondary market, shaped by mature vehicle parc dynamics, stringent OEM performance expectations, and ongoing reformulation activity surrounding latest-generation specifications. Europe occupies a strategically complex position, where decarbonization policies, OEM approvals, and premium lubricant positioning intersect with steady market consolidation.
Fuel Additives Market
Latin America and the Middle East and Africa, while smaller in absolute scale, offer distinctive growth narratives. The Latin American market reflects cyclical economic sensitivities but benefits from sustained commercial fleet activity and incremental modernization of lubricant standards. The Middle East and Africa region presents a dual profile: established demand in Gulf economies with strong automotive import markets, alongside emerging opportunity corridors in parts of Africa where infrastructure investment and vehicle parc growth are gradually lifting baseline lubricant consumption. Our full report contextualizes these regional profiles with historical trend analysis, capacity localization indicators, and supply-demand balance assessments—without relying on superficial aggregate figures—so that market entry, partnership, and sourcing decisions are grounded in structural reality rather than headline numbers.
Competitive Landscape and Strategic Positioning
The engine oil additives sector is characterized by high technical barriers, concentrated intellectual property, and a competitive field that blends global multinationals with regionally focused manufacturers. Market concentration metrics underscore this reality, with the top three players collectively accounting for approximately 62.45 percent of industry revenue and the top five firms extending their combined share to roughly 81.2 percent. This structural concentration signals both the importance of portfolio strength and the persistent pressure on smaller or regionally anchored participants to differentiate through specialty chemistries, cost-efficient manufacturing, or localized customer support.
At the center of the competitive field operate several globally recognized technology providers. The Lubrizol Corporation, headquartered in Wickliffe, Ohio, remains a major global supplier of additive packages for both passenger car and heavy-duty diesel engine oils. Its technology portfolio spans viscosity modifiers, dispersants, and anti-wear components, and its recent product activity illustrates the pace of specification-driven innovation: in mid-2025, Lubrizol introduced the PV1710 passenger car engine oil additive technology to help oil marketers meet ILSAC GF-7 performance requirements effective from March 2025 onward.
Infineum International Limited, based in Abingdon, UK, and structured as a joint venture between ExxonMobil and Shell, specializes in engine oil additive packages that balance fuel efficiency, emissions control, and protection against low-speed pre-ignition (LSPI). Afton Chemical Corporation, operating from Richmond, Virginia, develops and manufactures performance additives for engine oils with a notable emphasis on driveline and fuel additive integration. Chevron Oronite Company LLC, a subsidiary of Chevron and based in San Ramon, California, maintains a strong portfolio of lubricant and fuel additives under its OLOA branded products, with a global focus on OEM approvals and specification compliance.
European chemical giants further deepen the competitive fabric. BASF SE, headquartered in Ludwigshafen, Germany, supplies a broad range of lubricant additives, including antioxidants, dispersants, and viscosity index improvers tailored for automotive formulations. Evonik Industries AG, based in Essen, Germany, leads in viscosity index improvers and offers specialized additive solutions for fuel-efficient and high-performance automotive engine oils. LANXESS AG, from Cologne, Germany, provides antioxidants and extreme-pressure agents for engine oil applications, while Croda International Plc, located in Snaith, UK, contributes specialty additives including friction modifiers and bio-based components for modern automotive lubricants. Vanderbilt Chemicals, LLC, in Norwalk, Connecticut, rounds out the U.S.-based specialty presence with anti-wear, antioxidant, and extreme-pressure additives for engine oil and industrial lubricant formulations.
Worldwide Automotive Engine Oil Additives Market
The competitive picture also extends into Asia, where domestic manufacturing capacity and regional cost structures are reshaping supply dynamics. Jinzhou Kangtai Lubricant Additives Co., Ltd., based in Jinzhou, China, produces detergent and dispersant packages for automotive and industrial applications. Wuxi South Petroleum Additive Co., Ltd., situated in Wuxi, China, focuses on lubricant additives for automotive engine oils, including anti-oxidants and corrosion inhibitors. Tianhe Chemicals Group, also based in Jinzhou, operates as a large-scale producer of lubricant additive components and packages for global automotive engine oil markets. In Europe, BRB International B.V., a subsidiary of PETRONAS based in Ittervoort, Netherlands, supplies viscosity modifiers and engine oil additive packages, while Dorf Ketal Chemicals India Pvt. Ltd., operating from Mumbai, India, delivers specialty additives for fuel and lubricant performance in automotive engine oils. Together, these players illustrate a competitive arena where technology leadership, regional manufacturing footprints, and specification-compliance readiness determine market positioning.
Regulatory Catalysts, Raw Material Pressures, and Macro Trend Alignment
No analysis of the automotive engine oil additives market is complete without addressing the regulatory and macroeconomic forces that directly influence formulation requirements, cost structures, and demand velocity. The introduction of the ILSAC GF-7 specification, first licensed on March 31, 2025, represents one of the most consequential near-term drivers of additive innovation. Emphasizing enhanced fuel efficiency, reduced low-speed pre-ignition risk, and improved piston cleanliness for model year 2026 vehicles, GF-7 is accelerating demand for advanced additive packages capable of meeting stricter performance thresholds without compromising wear protection or oil durability.
Complementary regulatory activity has further shaped the compliance landscape. The American Petroleum Institute introduced the API SQ category in 2025 alongside ILSAC GF-7, addressing ultra-low viscosity grades not covered by GF-7. Both standards remain backward compatible with prior GF-6 and API SP formulations, a design choice that provides formulators with transition flexibility but also requires careful portfolio planning to avoid redundancy and ensure specification coverage across viscosity grades. In addition, API extended the overlap period for ILSAC GF-6 and ILSAC GF-7 engine oil standards to October 1, 2026, granting additional transition time for additive and oil formulations—a development that carries direct implications for inventory strategy, product launch sequencing, and supplier communications.
On the raw material front, the operating environment has grown more volatile. In early 2026, base oil and additive costs rose amid geopolitical tensions in the Middle East and persistent supply chain pressures. Multiple suppliers announced price increases of up to 15–20 percent on finished lubricants and components, underscoring the importance of proactive procurement planning, dual-sourcing strategies, and formulation optimization to protect margins. For additive manufacturers and lubricant marketers alike, cost volatility is not merely an input issue; it is a strategic variable that affects pricing power, competitive positioning, and customer retention.
Broader macro trends reinforce the direction of travel. Stricter global emissions regulations across the United States, the European Union, China, and India continue to mandate lower SAPS (sulphated ash, phosphorus, sulfur) engine oils, accelerating adoption of specialized additives for compliance. This regulatory momentum favors suppliers that can deliver high-performance, low-ash formulations and penalizes those that rely on older additive architectures. At the same time, the industry’s ongoing emphasis on fuel economy, engine durability, and emissions control is aligning additive development priorities with OEM expectations for next-generation powertrains, including turbocharged gasoline direct injection engines and advanced hybrid platforms.
Inside the Report: Operational Content and Decision-Ready Intelligence
Our Worldwide Automotive Engine Oil Additives Market research study is structured to translate market complexity into operational clarity. Rather than presenting data in isolation, the report embeds figures within analytical frameworks that support concrete business decisions. The publication covers historical performance tracking from 2020 through the 2025 base year, providing verified trend lines that contextualize the 2026–2032 forecast period. It then extends forward with demand projections, segmentation mapping, and scenario-aware commentary that help clients test strategic assumptions against plausible market outcomes.
The report systematically examines product-type, vehicle-type, and regional segmentation structures, giving readers a complete view of where demand is concentrated and how it is shifting. Beyond segment sizing, it evaluates the strategic implications of each split, highlighting which categories are most exposed to specification upgrades, which vehicle channels are most sensitive to economic cycles, and which geographies present the strongest mismatch between supply capacity and rising local demand. This layered approach allows clients to move from broad market awareness to targeted portfolio action.
Competitive intelligence forms another central pillar of the study. Company profiles, technology positioning, geographic footprints, and recent activity are synthesized into a comparative landscape that helps clients evaluate partnership opportunities, competitive threats, and benchmarking gaps. Recent developments—including new product launches, exhibition participation, specification updates, and regulatory milestones—are incorporated to ensure that the analysis reflects near-term market momentum rather than stale structural snapshots. For instance, the report captures the ILSAC GF-7 first licensing milestone, the API SQ category introduction, the GF-6/GF-7 overlap extension through October 2026, and key supplier announcements that signal where formulation innovation is heading.
Equally important, the study integrates raw material dynamics, cost pressures, and regulatory timelines into a unified narrative. This ensures that pricing strategy, sourcing decisions, and product roadmap planning are evaluated against the same operational reality. Clients gain a format that supports cross-functional alignment between R&D, procurement, sales, and executive leadership, reducing the friction that often occurs when market data is fragmented across multiple sources.
Strategic Value for 2026 Decision-Making
Portfolio Optimization and Specification Readiness
As ILSAC GF-7 and API SQ gain operational traction, companies must decide how to allocate development resources across viscosity grades, performance tiers, and regional compliance requirements. The report provides the contextual mapping needed to identify which product lines require reformulation urgency, which can be managed through backward-compatible extension strategies, and where transitional overlap periods create timing flexibility. This enables R&D and product management teams to sequence launches with greater confidence and reduce the risk of specification gaps.
Competitive Positioning and Supplier Strategy
Given the high market concentration and the technical sophistication of leading additive suppliers, procurement and strategy teams benefit from a clear view of who controls which technology domains, where regional manufacturers are scaling capacity, and how recent product and exhibition activity signals future competitive moves. Armed with this intelligence, organizations can negotiate from a stronger position, diversify sourcing where appropriate, and align partnership choices with long-term formulation roadmaps rather than short-term price considerations alone.
Cost Management in a Volatile Input Environment
With base oil and additive cost increases persisting into early 2026, margin protection has become a board-level concern. The study’s integrated treatment of cost dynamics, supply chain pressure points, and regional demand resilience supports more disciplined hedging, inventory planning, and formulation efficiency initiatives. Decision-makers can use the report’s frameworks to stress-test pricing strategies, evaluate make-versus-buy considerations, and identify segments where value-added performance can justify premium positioning despite input inflation.
Regional Expansion and Market Entry Planning
For organizations evaluating geographic expansion, the report offers the structural context needed to separate headline opportunity from operationally viable growth. Regional demand profiles, vehicle parc dynamics, regulatory calendars, and competitive density are analyzed together so that market entry, capacity allocation, and distribution partnership decisions are grounded in segment-level realism. This is particularly valuable for companies targeting fast-growing demand centers where local formulation preferences, approval pathways, and pricing norms differ materially from mature Western markets.
Regulatory Foresight and Compliance Alignment
The alignment between additive technology and evolving emissions and performance standards is now a core strategic variable. By mapping the implications of ILSAC GF-7, API SQ, SAPS reduction mandates, and OEM approval requirements, the report helps compliance, technical, and commercial teams synchronize their plans. Organizations that anticipate regulatory shifts early can secure first-mover advantages in specification adoption, reduce reformulation bottlenecks, and position themselves as reliable partners for OEMs and lubricant marketers navigating complex approval processes.
Conclusion: From Market Awareness to Strategic Execution
The Worldwide Automotive Engine Oil Additives Market is entering a phase where growth will increasingly be determined by specification readiness, formulation differentiation, and the ability to manage cost and supply volatility without losing competitive ground. The 3.21 percent CAGR projected through 2032 signals steady expansion, but the real value for 2026 decision-makers lies in understanding where within that growth curve the most defensible opportunities reside. Our full market research study provides the depth, structure, and competitive context required to convert macro trends into actionable strategy. For executives and technical leaders seeking to align product portfolios, sourcing strategies, and regional plans with the realities of a rapidly evolving lubricant ecosystem, this report offers a direct pathway from intelligence to execution. We invite you to access the complete study to explore the full segmentation analysis, detailed company assessments, forecast scenarios, and operational frameworks designed to support high-stakes decisions across the 2026–2032 horizon.
For detailed analysis of this topic, please visit the official page: Worldwide Automotive Engine Oil Additives Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: HEA, HPA, HEMA, HPMA Market to Hit $2.19B by 2032, 5.28% CAGR (2026-2032)
By pmarketresearch, 2026-09-16
Strategic Horizons: Navigating the 2026 Landscape of HEA, HPA, HEMA, and HPMA Markets
Executive Overview
The global chemical landscape for hydroxy-functional acrylate and methacrylate monomers is entering a critical phase of recalibration. As we move through the mid-2020s, the Worldwide HEA, HPA, HEMA, and HPMA Market stands at a pivotal juncture, defined by shifting demand vectors, feedstock volatility, and strategic capacity adjustments among major producers. For executives and strategic planners, understanding the trajectory from 2026 through 2032 is not merely an academic exercise; it is a fundamental requirement for informed capital allocation and supply chain resilience.
This market research provides a comprehensive lens into the sector, capturing the transition from post-pandemic recovery stability to a new era of operational optimization. The narrative is no longer about simple growth but about navigating complexity. With the overall market size reflecting steady expansion over the historical period of 2020 to 2025, stakeholders are now looking toward the forecast period of 2026 to 2032 to capitalize on emerging opportunities while mitigating regulatory and input cost risks.
This introduction serves as a primer to the full study, highlighting the strategic value embedded within the data. It is designed to equip decision-makers with the context needed to understand why this intelligence matters now, without revealing the granular segmentation details that form the core of the proprietary analysis.
Market Trajectory and Macro Indicators
The historical performance of the hydroxy-functional monomers market demonstrates a consistent upward trend, reflecting the enduring utility of these chemicals across diverse industrial applications. From 2020 to 2025, the market experienced measured growth, driven by sustained demand in coatings, adhesives, and specialized medical applications. As we look forward to the forecast period extending to 2032, the momentum is expected to continue, supported by industrial development in key regions and the ongoing modernization of manufacturing processes.
2-Ethylhexyl Methacrylate (2-EHMA) Market
The projected compound annual growth rate over the forecast period indicates a healthy expansion trajectory. For corporate strategists, this implies that the sector remains attractive despite broader economic headwinds. However, growth rates alone do not tell the full story. The timing of revenue realization, the stability of supply chains, and the ability to manage input costs will differentiate the winners from the laggards. Our analysis delves into these temporal dynamics, offering a year-by-year breakdown that allows for precise budgeting and capacity planning.
It is crucial for stakeholders to recognize that these macroeconomic figures are underpinned by complex regional and application-specific drivers. While the top-line numbers suggest stability, the underlying composition varies significantly. Accessing the detailed segmentation within the full report is essential for companies seeking to align their specific product portfolios with the most lucrative growth pockets.
Core Operational Content and Scope
A robust market study must go beyond aggregate statistics to provide actionable intelligence. This report is structured to support detailed strategic planning across multiple dimensions of the business. The analysis covers the four primary chemical types that define this sector, providing a comparative view of their respective market positions and growth potentials. Understanding the nuances between these chemical variants is vital for procurement teams and R&D departments aiming to optimize formulations or identify alternative sourcing opportunities.
Furthermore, the study dissects the application landscape, recognizing that demand is not monolithic. Whether the focus is on industrial coatings, adhesive technologies, medical devices, or water treatment solutions, each vertical presents unique challenges and opportunities. The report details how consumption patterns differ across these sectors, influenced by factors such as regulatory changes, technological advancements, and end-user preferences. For instance, the medical and contact lenses segment requires a different strategic approach compared to the high-volume paints and coatings industry.
Geographic coverage is another cornerstone of this intelligence. The research maps out demand and supply dynamics across major global regions, highlighting where production capacity is concentrated and where consumption is rising fastest. This geographic granularity is essential for multinational corporations managing logistics and local compliance, as well as for investors looking to identify emerging markets before they become mainstream. The full document provides the specific regional valuations and growth rates necessary to build a fully localized strategy.
Competitive Landscape and Player Strategy
The market structure is characterized by a mix of established global chemical giants and specialized regional manufacturers. Analysis of the competitive field reveals a landscape where concentration is moderate, yet strategic consolidations are shaping the future. The industry is not purely commodity-driven; differentiation through purity, specialty grades, and supply reliability plays a significant role in market share retention.
Worldwide HEA, HPA, HEMA, & HPMA Market
Prominent players such as Dow Inc. and BASF SE maintain strong positions through extensive production capabilities and diversified portfolios. Dow, based in Midland, Michigan, remains a major global producer of HEA, HPA, HEMA, and HPMA monomers, leveraging its scale to serve coatings, adhesives, and resin markets. Similarly, BASF SE in Ludwigshafen continues to lead with a broad offering of HEA and HEMA specialty acrylates, recently reporting production expansions to secure supply continuity.
In the Asia Pacific region, Mitsubishi Chemical Group Corporation and Nippon Shokubai Co., Ltd. are key producers. Mitsubishi focuses on high-purity HEMA and HPMA, including grades tailored for electronics and photoresist applications, while Nippon Shokubai emphasizes high-purity and low-skin-sensitization variants for coatings and electronics. Evonik Industries AG and Röhm GmbH from Germany contribute significantly to the methacrylate segment, with Röhm offering HEMA and HPMA under its VISIOMER brand for reactive resins and adhesives.
Recent developments highlight the dynamic nature of this competition. Wanhua Chemical Group Co., Ltd. announced a significant capacity expansion in May 2025, increasing HEMA production capacity to 55,000 tons to meet demand. In contrast, BASF SE announced price increases in mid-2025 to offset rising energy and raw material costs, illustrating the divergent strategic levers companies are pulling. These moves underscore the importance of monitoring competitor actions closely; a capacity expansion in one region can shift global pricing power, while a price increase can accelerate demand for alternatives.
Industry Dynamics: Feedstock and Regulatory Pressures
Operational strategy in 2026 cannot be divorced from the external forces influencing cost structures and compliance requirements. The upstream feedstock environment is a critical variable for margin management. Acrylic acid, the primary upstream feedstock for HEA and HPA, saw US prices reach 1,260 USD per metric ton in August 2025. While this represented a month-over-month increase, it was down year-over-year, reflecting the volatile nature of petrochemical derivatives. Meanwhile, methacrylic acid, key for HEMA and HPMA, experienced a quarter-over-quarter price decline in North America in Q4 2025 due to weaker exports.
These fluctuations are part of a broader trend where global acrylic monomer markets faced downward price pressure in the second half of 2025 from new capacities and weak demand linked to propylene feedstock trends. For procurement leaders, this suggests a potential window for favorable contracting, but also the risk of supply disruptions if capacity adjustments lag behind demand shifts. Our report integrates these feedstock trends with monomer pricing models to help companies forecast their input costs more accurately.
On the regulatory front, the US EPA HON Rule imposes new emissions-control requirements on synthetic organic chemical manufacturing facilities. This introduces compliance costs and potential operational constraints for manufacturers within the region. However, temporary regulatory relief has been granted for certain stationary sources under Clean Air Act section 112(i)(4) for up to two years. Navigating these regulatory nuances is essential for maintaining operational continuity. Additionally, in the medical sector, Poly(2-hydroxyethyl methacrylate) used in devices such as contact lenses and urethral bulking agents remains subject to systematic biocompatibility reviews by the FDA. Literature on host responses and potential adverse effects continues to influence product design and safety standards, requiring manufacturers to stay aligned with evolving compliance expectations.
Strategic Imperatives for 2026 Decision Making
As enterprises plan for the remainder of the decade, several strategic imperatives emerge from the data. First, supply chain diversification is no longer optional. Given the concentration of production capacity in specific regions and the volatility of feedstock markets, relying on a single source or region exposes companies to undue risk. The report provides the visibility needed to identify alternative suppliers and assess their capability to meet quality and volume requirements.
Second, innovation in application technology offers a pathway to margin protection. As commodity pricing faces pressure from new capacities, differentiation through high-performance grades or specialized formulations can justify premium pricing. Companies that invest in R&D aligned with high-growth application segments, such as water treatment or specialized medical devices, will likely outperform those competing solely on volume.
Third, regulatory anticipation must be built into long-term planning. The interplay between emissions controls and temporary exemptions requires agile compliance strategies. Firms that proactively adapt their production processes to meet stricter standards while managing the associated costs will secure a competitive advantage. The full study includes scenario analysis to help leaders model the impact of regulatory changes on their operations.
Concluding Perspective
The Worldwide HEA, HPA, HEMA, and HPMA Market is poised for continued evolution. While the macro indicators suggest steady growth, the true value for decision-makers lies in the details hidden beneath the aggregate numbers. Understanding the specific dynamics of segmentation by type, application, and region is what transforms raw data into actionable strategy. The competitive moves by key players like Wanhua and BASF, combined with the shifting feedstock and regulatory landscape, create a complex environment where information asymmetry determines success.
This report is designed to close that information gap. By providing a detailed roadmap of the market from 2026 to 2032, it enables organizations to move from reactive positioning to proactive strategy. To gain access to the complete segmentation data, precise regional revenue figures, and the full competitive benchmarking analysis required to execute these strategies, stakeholders are encouraged to request the full publication. The insights contained within are critical for navigating the next phase of industry development with confidence.
For detailed analysis of this topic, please visit the official page: Worldwide HEA, HPA, HEMA, & HPMA Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: WNT Signaling Inhibitors Market Reaches $1.45B in 2025; Forecasted to Hit $3.3B by 2032 at 12.5% CAGR
By pmarketresearch, 2026-09-16
Strategic Intelligence for the Next Decade: Inside the Worldwide Wingless and Integrated (WNT) Signaling Pathway Inhibitors Market
The pharmaceutical and biotechnology landscape is constantly reshaped by breakthroughs in molecular understanding. Among the most promising yet complex frontiers lies the Wingless and Integrated (WNT) signaling pathway. Targeting this pathway offers transformative potential for oncology, fibrotic diseases, and regenerative medicine. However, navigating the commercial realities of WNT signaling pathway inhibitors requires more than surface-level data. It demands rigorous, forward-looking analysis grounded in historical performance and predictive modeling. PW Consulting's latest Worldwide Wingless and Integrated (WNT) Signaling Pathway Inhibitors Market report delivers precisely that intelligence.
Worldwide Wingless and Integrated (WNT) Signaling Pathway Inhibitors Market
This comprehensive study examines market evolution from 2020 through 2032, presenting a detailed valuation framework that captures both retrospective growth and forward projections. The market stood at approximately 890.5 million USD in 2020, climbing steadily to 1445.66 million USD by 2025. Looking ahead, the projected trajectory indicates sustained expansion, with the market expected to reach 1725.68 million USD in 2026 and continue its upward march to 3297.12 million USD by 2032. This represents a compound annual growth rate of 12.5 percent, signaling robust demand drivers and deepening investment interest across the value chain.
Such figures are not abstract statistics. They reflect accelerating research activity, expanding preclinical pipelines, and the strategic positioning of key players who are actively shaping the supply ecosystem. Yet behind every headline number lies a nuanced architecture of drug classes, therapeutic applications, and regional dynamics that demand careful dissection. This report goes beyond top-line valuations to unpack the structural forces that will define competitive advantage through 2032.
A Multi-Dimensional Market Architecture
The WNT signaling pathway inhibitors market cannot be understood through a single lens. It is a composite ecosystem where drug modality, disease indication, and geographic reach intersect to create distinct value pools. Our analysis segments the market across three critical dimensions: drug class, therapeutic area, and geographic region. Each segmentation reveals unique growth mechanics and strategic implications for stakeholders operating in this space.
Drug Class Segmentation: The Battle Between Small Molecules and Biologics
Small molecule inhibitors currently command the largest share of the market landscape. Their widespread adoption in academic and preclinical research settings is driven by accessibility, established synthesis pathways, and the breadth of chemical tools available to investigators. Monoclonal antibodies and other biologic modalities represent a growing but more specialized segment. These agents offer distinct pharmacological profiles and are increasingly explored for targeted applications where precision modulation is required. Biologics and other emerging formats complete the triangulation, capturing niche but high-potential demand.
The interplay between these drug classes is far from static. As synthesis techniques mature and manufacturing capabilities scale, cost dynamics shift. Research-grade materials for complex multi-step synthesis pathways, particularly for Porcupine and Tankyrase inhibitors, currently range between 50 and 200 USD per milligram. This pricing structure influences procurement strategies, shapes the inventory decisions of research suppliers, and ultimately affects the pace at which new candidates can advance through discovery pipelines. Understanding these cost structures is essential for anyone evaluating supply chain resilience or forecasting demand elasticity.
Therapeutic Area Distribution: Oncology Leads, Fibrosis and Bone Disorders Follow
Oncology remains the dominant therapeutic anchor for WNT pathway inhibition. The biological rationale is compelling: dysregulated WNT signaling is implicated in tumor initiation, progression, and resistance mechanisms across multiple solid tumor types. Consequently, oncology-directed research and development activities account for the largest portion of market activity. Fibrotic diseases represent the second major cluster, reflecting growing recognition of WNT pathway involvement in tissue remodeling and chronic fibrosis. Bone and joint disorders, along with other indications, round out the therapeutic spectrum, each presenting distinct clinical needs and research priorities.
This therapeutic diversity is both a strength and a challenge. It diversifies revenue potential but also fragments focus. Companies must decide where to concentrate resources, which indications offer the clearest path to clinical validation, and how to align their product portfolios with emerging scientific consensus. Our report provides a structured framework for making these allocation decisions with confidence.
Worldwide Prostaglandins and Related Drugs Market
Regional Dynamics: North America Anchors, Global Markets Expand
Geographically, the market exhibits clear patterns of concentration and opportunity. North America continues to serve as the primary hub for research activity, supply chain infrastructure, and early-stage investment. Europe maintains a strong and stable presence, supported by well-established research institutions and a mature pharmaceutical ecosystem. The Asia Pacific region represents a dynamic growth zone, driven by expanding biotechnology capacity and increasing research expenditure. The Rest of the World segment, while smaller in absolute terms, offers emerging opportunities as global scientific collaboration intensifies.
Competitive Landscape: Research Suppliers and Emerging Clinical Players
The competitive terrain for WNT signaling pathway inhibitors is defined by a dual structure: a robust ecosystem of research-grade suppliers and a smaller but strategically vital cohort of companies advancing clinical-stage candidates. Understanding both layers is critical for anticipating market shifts and identifying partnership or acquisition opportunities.
Research-Grade Suppliers: The Foundation of Discovery
Several established chemical and biological supply companies form the backbone of the research supply chain. MedChemExpress LLC, headquartered in Monmouth Junction, New Jersey, supplies a broad range of research-grade WNT pathway inhibitors, including XAV939, a Tankyrase inhibitor, IWP-2, a Porcupine inhibitor, and ICG-001, a CBP inhibitor. Selleck Chemicals, based in Houston, Texas, offers a complementary portfolio featuring XAV939, IWR-1, KY02111, and Wnt-C59, catering to academic and industrial laboratories alike.
Cayman Chemical, located in Ann Arbor, Michigan, emphasizes high-purity inhibitor offerings such as IWP-L6 and JW55 for laboratory research applications. Tocris Bioscience, operating from Bristol, United Kingdom, markets selective WNT pathway modulators including XAV939 and IWP-2, alongside complementary agents like CHIR99021, which, while an activator, rounds out the research toolkit. Sigma-Aldrich, with its extensive catalog based in St. Louis, Missouri, distributes widely used inhibitors such as IWR-1-endo and IWP-3, leveraging its global distribution network to serve a broad research constituency. TargetMol, based in Boston, Massachusetts, sells a focused collection of WNT signaling inhibitors including ETC-159, a Porcupine inhibitor, RXC004 analogs, and Tankyrase inhibitors specifically curated for preclinical studies.
These suppliers operate in a market where products are labeled for research use only, meaning they are not approved for diagnostic or therapeutic applications. This regulatory reality shapes purchasing behavior, limits commercialization pathways for the suppliers themselves, and reinforces the early-stage nature of the current market. Yet it also creates a stable, recurring demand stream driven by the relentless pace of basic and translational research.
Clinical-Stage Developments: The Horizon of Therapeutic Translation
While no WNT signaling pathway inhibitor has yet received FDA approval for therapeutic use, the clinical pipeline tells a story of accelerating ambition. Over 100 active clinical trials target WNT pathway modulation, with oncology representing the primary focus. This volume of investigative activity signals strong scientific conviction and significant unmet need.
Redx Pharma has emerged as a notable example of clinical ambition in this space. In October 2022, the company announced the first patient dosed in a Phase 1b/2 trial of its Porcupine inhibitor RXC004 in combination with gemcitabine and nab-paclitaxel for advanced pancreatic cancer. Just two months later, in December 2022, Redx Pharma reported another milestone: the first patient dosed in a Phase 1b/2 trial of RXC004 combined with atezolizumab and bevacizumab for advanced solid tumors. These developments illustrate the strategic logic of combination approaches and the broadening exploration of WNT inhibition across difficult-to-treat malignancies.
Such clinical milestones, while early-stage, materially influence market sentiment and investor interest. They validate the biological target, encourage further capital allocation, and stimulate competitive responses from other biotechnology firms considering entry into this pathway. The report tracks these developments in detail, mapping them against broader pipeline trends to provide a realistic view of commercialization timelines and risk factors.
Market Dynamics: Navigating Regulatory and Economic Realities
The WNT signaling pathway inhibitors market operates within a complex set of constraints and opportunities. Regulatory frameworks currently classify WNT pathway inhibitors as research-use-only products, prohibiting their deployment in diagnostic or therapeutic settings. This classification is not merely a legal footnote; it fundamentally shapes market structure, pricing dynamics, and the strategic options available to suppliers and developers alike.
From a reimbursement perspective, the research-use designation means that traditional healthcare reimbursement pathways do not yet apply. Value capture happens through research procurement, institutional budgets, and grant-funded purchasing rather than through payer-driven markets. This dynamic favors suppliers with strong institutional relationships, reliable quality controls, and competitive pricing models. It also means that the transition from research-grade supply to therapeutic commercialization will represent a structural market shift, potentially reshaping competitive hierarchies and value distribution.
On the supply side, the complexity of multi-step synthesis for Porcupine and Tankyrase inhibitors creates inherent cost pressures. Prices ranging from 50 to 200 USD per milligram for research quantities reflect the technical demands of production, purity requirements, and scale limitations. These cost structures influence procurement decisions and serve as a barrier to rapid scaling for some modalities. Companies that can optimize synthesis pathways, secure reliable raw material inputs, or develop more efficient manufacturing processes will gain meaningful competitive advantages.
Despite these constraints, the sheer volume of clinical investigation underscores the market's underlying potential. Over 100 active trials signal sustained scientific interest and a willingness to navigate the regulatory and biochemical challenges associated with WNT pathway modulation. The concentration of market activity further highlights the role of a relatively small group of players. The top three companies account for 42.5 percent of market revenue, while the top five hold 58.8 percent. This concentration indicates that strategic positioning, supply reliability, and product portfolio breadth are significant differentiators in a market where scale and trust matter.
What the Report Delivers: Actionable Intelligence for 2026 and Beyond
This market research report is designed for decision-makers who need more than aggregated numbers. It provides a structured, evidence-based platform for strategic planning across multiple functional domains.
The report opens with a detailed market overview and valuation framework, establishing baseline metrics and growth trajectories that anchor all subsequent analysis. It then proceeds through a comprehensive segmentation analysis, examining drug class performance, therapeutic area adoption patterns, and regional distribution dynamics. Each segment is evaluated for growth drivers, constraints, and prospective shifts through the 2032 forecast horizon.
Competitive landscape assessment forms a central pillar of the report. Detailed company profiles cover research suppliers, their product portfolios, headquarters locations, and strategic positioning. The analysis extends to clinical-stage developments, tracking trial phases, combination strategies, and therapeutic targets that are shaping the future commercial landscape. Recent developments, including Redx Pharma's Phase 1b/2 trial initiations, are contextualized within broader pipeline activity to illustrate the pace and direction of clinical translation.
Market dynamics are explored through multiple lenses: regulatory status and its implications for commercialization pathways, reimbursement realities for research-use products, raw material cost structures and their impact on pricing and supply resilience, and the concentration of market value among leading players. The report also addresses frequently asked questions that arise in executive discussions, providing clear, defensible answers grounded in data and regulatory documentation.
Forecasting methodology is transparent and rigorous. The report covers historical performance from 2020 through 2025 and extends projections through 2032, applying a compound annual growth rate of 12.5 percent within a structured scenario framework. All valuations are expressed in USD million, ensuring consistency and comparability for international audiences. Decision-makers can use these projections to model capacity investments, prioritize research and development allocation, evaluate partnership opportunities, and stress-test strategic assumptions against evolving market conditions.
Why This Analysis Matters for 2026 Decision-Making
The year 2026 represents a pivotal inflection point for the WNT signaling pathway inhibitors market. Historical growth has been steady, but the forward trajectory suggests an acceleration driven by deepening scientific understanding, expanding clinical investigation, and maturing supply chain capabilities. Organizations that act on reliable intelligence today will be better positioned to capture value as the market transitions from a predominantly research-focused ecosystem toward broader therapeutic and commercial applications.
For research suppliers, understanding segment growth rates, regional demand patterns, and cost dynamics is essential for optimizing inventory, pricing, and geographic expansion. For biotechnology and pharmaceutical companies, mapping the competitive landscape and clinical pipeline provides critical input for portfolio strategy, partnership targeting, and risk assessment. For investors and financial analysts, the combination of historical valuations, forward projections, and concentration metrics offers a robust basis for evaluating market attractiveness and identifying high-potential sub-segments.
The strategic value of this report lies in its ability to translate complex, multi-layered market data into actionable insights. It does not merely describe where the market has been; it illuminates the structural forces that will determine where it goes. By integrating historical data, segmentation analysis, competitive profiling, and regulatory context, the report equips stakeholders with the clarity needed to make informed, forward-looking decisions.
Get the Complete Intelligence
This overview provides a foundation, but the full strategic picture requires depth. The complete report delivers exhaustive segmentation data, granular company assessments, detailed forecast models, and comprehensive regulatory and reimbursement analysis. Every figure, trend, and strategic recommendation is sourced and verifiable, ensuring that your decisions rest on solid analytical ground.
Do not navigate the WNT signaling pathway inhibitors market with fragmented data or assumptions. Access the full Worldwide Wingless and Integrated (WNT) Signaling Pathway Inhibitors Market report to unlock the detailed intelligence you need. Explore the complete segmentation breakdowns, examine the competitive landscape in full, and leverage the 2032 forecast to shape your strategy with confidence. The market is moving. Make sure your decisions are informed by the most comprehensive analysis available.
For detailed analysis of this topic, please visit the official page: Worldwide Wingless and Integrated (WNT) Signaling Pathway Inhibitors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Strategic Intelligence for the Pseudomonas Aeruginosa Infection Treatment Market: Navigating a $2.8 Billion Horizon (2026-2032)
The global landscape for treating Pseudomonas aeruginosa infections is undergoing a profound transformation, driven by the relentless pressure of antimicrobial resistance, evolving regulatory frameworks, and a shifting clinical consensus on the management of difficult-to-treat Gram-negative pathogens. Plasmid-mediated resistance mechanisms, carbapenem-sparing strategies, and the emergence of novel beta-lactam/beta-lactamase inhibitor combinations have collectively redefined the therapeutic armamentarium available to hospitalists, infectious disease specialists, and critical care teams. Against this backdrop, PW Consulting is proud to present our comprehensive Worldwide Pseudomonas Aeruginosa Infection Treatment Market research, a strategic intelligence asset designed to equip pharmaceutical executives, investors, and healthcare strategists with the precise, forward-looking insights necessary to make confident decisions in 2026 and beyond.
This report does not merely catalog historical revenue streams. It constructs a multidimensional view of where the market stands at its 2025 baseline of approximately 1,942.4 million USD, how it reached that threshold through a disciplined progression from 1,484.2 million USD in 2020, and how it is projected to breach the 2,000 million USD mark in 2026 before charting a sustained upward arc through 2032. Executives operating in the antibiotic and anti-infective space require more than top-line figures. They need to understand which therapeutic classes are consolidating market share, which clinical indications are absorbing the heaviest treatment volumes, how reimbursement philosophies are recalibrating across major healthcare systems, and which competitive moves will define the next wave of portfolio optimization. Our analysis is built to answer those questions with surgical precision while preserving the confidentiality of the granular data that drives our forecasting engine.
A Data-Rich Foundation for Executive Decision-Making
Any credible market evaluation begins with a disciplined historical lens. Over the 2020 to 2025 assessment window, the global Pseudomonas Aeruginosa Infection Treatment Market expanded from 1,484.2 million USD to 1,942.4 million USD, reflecting a compounding trajectory shaped by rising hospital-acquired infection rates, increased adoption of newer antipseudomonal agents in stewardship-aligned protocols, and persistent demand across both branded and generic channels. The forward-looking narrative extends through 2032, with the market projected to reach approximately 2,825.5 million USD by the close of the forecast horizon. This pathway implies a compound annual growth rate of 5.51 percent, a figure that captures both organic volume expansion and the continuous rotation toward higher-value combination therapies that address resistant phenotypes.
Rather than treating this growth as a monolithic trend, our research decomposes the market into clinically and commercially meaningful dimensions. We analyze how different drug classes are navigating shifting susceptibility patterns, how regional healthcare infrastructures are modulating access and adoption, and how specific infection sites are driving differentiated prescribing behaviors. The report deliberately preserves these structural splits within our proprietary analytical framework, requiring stakeholders to engage directly with the complete dataset to fully map the terrain. This approach ensures that the intelligence you receive is not diluted into generic commentary but delivered as an actionable, decision-grade resource.
What This Report Delivers: Operational Depth for Strategic Planning
The Worldwide Pseudomonas Aeruginosa Infection Treatment Market research is structured to function as a working document for strategy, business development, and competitive intelligence teams. Every section has been engineered to translate epidemiological and pharmacological complexity into commercial clarity. The following components form the backbone of the analysis:
- Macro-market sizing and historical reconstruction spanning 2020 to 2025, with full-year revenue trajectories that anchor the 2025 baseline and set the stage for the 2026 to 2032 forecast window.
- A segmented evaluation of therapeutic classes, mapping the relative commercial weight of each category while highlighting the interplay between legacy antipseudomonal agents and next-generation beta-lactam/beta-lactamase inhibitor platforms.
- An indication-level breakdown that examines how respiratory tract infections, urinary tract infections, bacteremia, skin and soft tissue infections, and other clinical scenarios contribute to overall treatment demand and prescribing conventions.
- A regional analysis that contextualizes market dynamics across North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa, incorporating differences in formulary access, reimbursement structures, and local resistance epidemiology.
- Detailed company profiles that map the operational footprint, pipeline positioning, and recent strategic developments of the leading players shaping the competitive battlefield.
- A forward-looking competitive landscape assessment that integrates market concentration metrics, portfolio overlap analysis, and the strategic implications of recent regulatory and clinical milestones.
Throughout these sections, we maintain a disciplined separation between illustrative market architecture and the core quantitative splits that power our projections. Readers seeking the exact revenue contributions of each therapeutic category, each indication, and each geographic zone will find those figures embedded within the complete research instrument, accessible through our full report portal.
Competitive Landscape: Navigating a Concentrated but Dynamic Field
The Pseudomonas Aeruginosa Infection Treatment Market operates within a highly active competitive environment where a relatively concentrated set of large-cap pharmaceutical organizations coexist alongside specialized anti-infective developers and global generic manufacturers. Our concentration analysis indicates that the top three participants collectively command a meaningful share of total market revenue, while the top five extend their footprint to a dominant aggregate position. This structural reality does not imply a static hierarchy. Instead, it reflects a landscape in which established beta-lactam platforms, combination inhibitor strategies, siderophore cephalosporins, and a steady stream of generic entrants are continuously redefining share dynamics through clinical differentiation, regulatory approvals, and stewardship-aligned positioning.
Several anchor organizations define the strategic contours of this market. Pfizer Inc. maintains a deep-rooted presence in hospital and critical care settings through its antipseudomonal antibiotic portfolio, including its longstanding piperacillin-tazobactam platform, reinforcing its relevance in severe infection management. Merck & Co., Inc. has strengthened its positioning through imipenem-cilastatin-relebactam for complicated urinary tract infections, intra-abdominal infections, and hospital-acquired or ventilator-associated bacterial pneumonia, broadening its appeal in resistant Gram-negative contexts. AbbVie Inc., through its Allergan affiliation, continues to expand its ceftazidime-avibactam footprint while extending its reach with the recent approval of aztreonam-avibactam, an asset designed to address scenarios where treatment options are constrained by multidrug resistance.
Shionogi & Co., Ltd. has emerged as a distinctive force with cefiderocol, a siderophore cephalosporin engineered to target carbapenem-resistant and otherwise difficult-to-treat Pseudomonas aeruginosa. The company has advanced this platform through robust real-world evidence generation, including clinical presentations that underscore the role of cefiderocol in serious infection settings where Pseudomonas aeruginosa represents a substantial proportion of monomicrobial cases. Across 2025 and 2026, Shionogi's data disclosures have reinforced clinical cure rates and in vitro activity profiles that support the agent's positioning in complicated Gram-negative disease management. Teva Pharmaceutical Industries Ltd. and Lupin Pharmaceuticals continue to anchor the generic tier by supplying widely utilized antipseudomonal agents across multiple classes, sustaining access while exerting price and availability pressure on established product lines. AstraZeneca remains active with ceftazidime and broader anti-infective initiatives relevant to Gram-negative resistance, while Bristol Myers Squibb, Johnson & Johnson through Janssen, Novartis AG, Sanofi, and Baxter International Inc. each contribute distinct capabilities ranging from supportive injectable therapies to stewardship-focused programs and established antibiotic portfolios.
The strategic significance of this competitive architecture lies not in static market shares, but in the sequencing of innovation, the pace of generic infiltration, and the extent to which newer combination therapies align with guideline-driven prescribing. Our report unpacks these dynamics in detail, but the core percentage contributions and exact revenue alignments that determine relative competitive weight are reserved for clients accessing the full dataset.
The Regulatory and Clinical Context Shaping 2026 Strategy
No market assessment of this kind can be separated from the regulatory and clinical environment in which treatment decisions are made. Between January and February 2025, the U.S. Food and Drug Administration reinforced its recognition of standardized susceptibility testing frameworks for several antipseudomonal agents, including amikacin, cefepime, and ceftazidime, while reevaluating its position on polymyxin breakpoints in light of limited pharmacokinetic and clinical outcome data. These actions matter because they influence how laboratories report susceptibility, how clinicians interpret MIC values, and how manufacturers position their compounds within diagnostic and therapeutic workflows.
Simultaneously, clinical guidance continues to shape demand patterns. The 2024 IDSA antimicrobial resistance guidance, which remains active through 2025 and 2026, recommends a preferential approach to newer beta-lactam/beta-lactamase inhibitors for difficult-to-treat resistant Pseudomonas aeruginosa. This guidance elevates the strategic relevance of agents such as ceftolozane-tazobactam, ceftazidime-avibactam, imipenem-relebactam, and cefiderocol in treatment algorithms where resistance narrows the therapeutic window. At the same time, the European Commission's earlier authorization of aztreonam-avibactam for infections with limited treatment options illustrates how regulatory pathways in major markets are opening doors for combination therapies designed to address resistant Gram-negative organisms, including Pseudomonas contexts.
On the supply and manufacturing side, antibiotic production for beta-lactams and aminoglycosides continues to rely on globally distributed active pharmaceutical ingredient networks. Generic producers play an essential role in maintaining availability, but they also influence margin structures, tender dynamics, and the speed at which new branded entrants can capture share in hospital formularies. These are precisely the kinds of interdependencies that our report maps in depth, while withholding the specific quantitative allocations that would allow competitors to reverse-engineer our forecasting assumptions.
Why This Research Is Critical for 2026 Decision-Making
As pharmaceutical companies, investors, and healthcare strategists plan their next moves, three structural questions dominate the agenda. First, how will the balance between branded combination therapies and generic antipseudomonal agents evolve as resistance patterns continue to shift and stewardship programs refine prescribing behavior. Second, where will clinical demand concentrate across infection sites, and which therapeutic categories will be best positioned to capture that demand under evolving guideline recommendations. Third, how should organizations interpret the competitive actions of major players who are simultaneously defending legacy franchises, expanding into newer combination platforms, and integrating real-world evidence to support adoption in high-acuity settings.
Our analysis is built to address these questions directly. The 2026 market projection of approximately 2,033.6 million USD serves as a strategic inflection point, marking the beginning of a forecast period in which growth is expected to be driven by sustained clinical reliance on antipseudomonal therapies, continued uptake of newer agents in resistant infection pathways, and the ongoing interplay between premium combination products and cost-sensitive generic alternatives. The trajectory from 2026 through 2032 is not a straight line; it reflects the influence of regulatory decisions, guideline updates, manufacturing realities, and the pace at which clinicians adopt next-generation options in the face of limited-treatment scenarios.
Worldwide Pseudomonas Aeruginosa Infection Treatment Market
Worldwide Buruli Ulcer Treatment Market
Executives who engage with this research will emerge with a clearer understanding of where value is accumulating, where pressure is intensifying, and how to prioritize engagements across geographies, indications, and drug classes. The market concentration environment, the prominence of major hospital-focused portfolios, and the steady rhythm of regulatory and clinical updates all point toward a landscape that rewards organizations with precise, forward-looking intelligence rather than reactive assumptions.
Access the Full Strategic Blueprint
This article is intended as a gateway, not a substitute for the complete research product. The Worldwide Pseudomonas Aeruginosa Infection Treatment Market study contains the granular segmentation data, regional revenue architectures, therapeutic class splits, indication-level demand distributions, and company-specific strategic assessments required to build defensible plans in 2026 and beyond. Those elements are intentionally held within the full report to preserve analytical integrity and deliver actionable exclusivity to our clients.
For leadership teams that need to align R&D priorities, portfolio strategy, market access planning, and competitive positioning with a rigorously constructed view of this market, the complete research instrument offers the depth and precision that high-stakes decisions demand. The forecast window ahead will be shaped by resistance evolution, stewardship policy, regulatory milestones, and the strategic choices of globally active pharmaceutical organizations. PW Consulting's latest market research provides the structured intelligence necessary to navigate that environment with confidence, discipline, and strategic clarity.
For detailed analysis of this topic, please visit the official page: Worldwide Pseudomonas Aeruginosa Infection Treatment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global TPS Cable Market Hits $52.2B in 2025, 6.29% CAGR to 2032
By pmarketresearch, 2026-09-16
Strategic Intelligence for the 2026 Market Landscape: Inside the Worldwide Thermoplastic-Sheathed Cable Market
The worldwide thermoplastic-sheathed cable market stands at a critical juncture as enterprises navigate a decade defined by infrastructure modernization, energy transition mandates, and shifting supply chain architectures. Our latest Worldwide Thermoplastic-sheathed Cable Market study delivers a comprehensive strategic foundation for decision-makers operating across manufacturing, procurement, and capital allocation functions. Designed for immediate deployment in 2026 planning cycles, this research translates multi-year trajectory data, regulatory inflection points, and competitive maneuvers into actionable intelligence. Below, we outline the analytical architecture, contextual drivers, and competitive mapping that position this report as an essential reference for enterprise strategy.
Market Trajectory and Structural Shifts
Over the historical observation window from 2020 through 2025, the sector demonstrated consistent expansion, moving from approximately 38,450 million USD to a baseline of 52,150 million USD by the close of the reference period. This progression reflects sustained deployment across power distribution, building wiring, and industrial control environments, underpinned by steady urbanization and grid modernization programs.
The forward-looking horizon from 2026 through 2032 outlines a continued upward path, advancing toward a projected 79,981 million USD by the terminal forecast year. The compound annual growth rate of 6.29 percent signals a mature but resilient demand environment, where volume expansion is increasingly coupled with specification upgrades, compliance-driven material substitutions, and regional sourcing realignments. For executives mapping capacity investments, inventory strategies, or market entry plans, this trajectory provides a calibrated baseline against which internal forecasts and scenario models can be stress-tested.
Importantly, the market structure reveals meaningful differentiation across product architectures, application channels, and geographic corridors. Flat configurations continue to command substantial share within mainstream wiring deployments, while circular and multi-core variants maintain specialized relevance in power routing, instrumentation, and complex harness assemblies. On the application side, residential construction and commercial building projects represent the dominant consumption corridors, with industrial infrastructure providing a steady, specification-sensitive demand layer that rewards manufacturers capable of delivering compliance-ready, durable solutions. Regionally, Asia Pacific anchors the largest consumption base, followed by North America and Europe, while Middle East and Africa and Latin America present growth corridors shaped by infrastructure spending cycles and import-dependency dynamics. These structural patterns are examined in depth within the full report, where segmentation interplay, demand elasticity, and regional procurement behaviors are mapped without the simplifications typically found in high-level summaries.
Regulatory Forces and Supply Chain Reconfiguration
The competitive and operational environment for thermoplastic-sheathed cables is being reshaped by overlapping regulatory, material, and trade dynamics. International standards such as IEC 60227-5 govern thermoplastic-insulated cables rated up to 450/750V, and the 2024 amendments that enhanced flame retardancy requirements have elevated the compliance burden for manufacturers serving building and infrastructure end markets. In parallel, the AS/NZS 5000.2:2022 specification continues to define performance expectations for thermoplastic-sheathed cables used in Australian electrical installations, reinforcing the importance of region-specific certification strategies for suppliers targeting Oceania and export-aligned markets.
These technical standards intersect with broader policy momentum. The global push for energy-efficient buildings under frameworks such as the EU Green Deal is accelerating demand for low-smoke zero-halogen thermoplastic cables, creating an estimated uplift of 5 to 7 percent annually in relevant demand segments. This shift rewards manufacturers that can align product portfolios with stricter emission, fire-safety, and sustainability expectations while maintaining cost competitiveness.
Material economics further complicate planning. PVC resin prices, which are central to thermoplastic sheathing production, averaged 1,200 USD per metric ton in the fourth quarter of 2025 amid relatively stable supply from Asia. While this provided near-term cost visibility, commodity volatility, logistics constraints, and regional availability differences continue to require active procurement hedging and supplier diversification. At the same time, trade policy has introduced meaningful sourcing realignment. US tariffs on Chinese thermoplastic cables increased to 25 percent under Section 301 in 2025, prompting buyers and distributors to shift sourcing toward Mexico and Vietnam. For manufacturers and channel partners, these developments are not merely cost variables; they are strategic determinants of plant location, inventory positioning, contract structure, and long-term market access.
Worldwide Thermoplastic-sheathed Cable Market
Competitive Architecture and Recent Industry Moves
The market remains moderately fragmented, with the top three firms accounting for approximately 18.45 percent of revenue and the top five reaching roughly 24.8 percent. This concentration profile suggests that while scale players hold meaningful influence, there is substantial room for specialized differentiation, regional execution strength, and specification-driven wins. The competitive field includes globally integrated manufacturers and sector-focused specialists, each pursuing distinct routes to advantage through product engineering, certification breadth, distribution reach, and project-level pipeline development.
Prysmian Group, headquartered in Milan, Italy, operates as a leading global manufacturer of thermoplastic-sheathed cables, including TPS power cables for residential, commercial, and industrial applications compliant with AS/NZS 5000.2 standards. Its recent showcase of new thermoplastic-sheathed low voltage cables for renewable energy at the Wire 2025 exhibition signals continued alignment with electrification and clean-energy infrastructure demand.
Nexans, based in Paris, France, produces thermoplastic insulated and sheathed cables such as NYY and similar TPS types for power distribution, mining, and construction worldwide. Its September 2025 launch of enhanced thermoplastic-sheathed cables with improved fire resistance for building applications underscores a product strategy centered on compliance and safety performance in construction end markets.
Southwire Company, located in Carrollton, USA, is a major US producer of thermoplastic-sheathed cables including THHN/THWN with PVC/thermoplastic sheathing for electrical installations. The June 2025 UL certification update for new thermoplastic-sheathed SIMpull cables reflects an ongoing emphasis on specification approval, channel readiness, and installer-friendly product design in the North American market.
LS Cable & System, headquartered in Seoul, South Korea, supplies thermoplastic-sheathed power and control cables for global energy and infrastructure projects. Its April 2025 contract award for an Australian data center project illustrates how infrastructure-linked demand and international project pipelines can create targeted growth opportunities for capable exporters.
In Japan, Sumitomo Electric Industries manufactures thermoplastic-insulated and sheathed cables for automotive, power, and industrial uses, while Furukawa Electric produces PVC/thermoplastic sheathed cables for power transmission and distribution. Both firms leverage strong engineering heritage and broad application coverage to sustain position across demanding performance environments.
NKT A/S, based in Brøndby, Denmark, offers thermoplastic-sheathed medium and low voltage cables for offshore and onshore applications, aligning its portfolio with energy-sector and harsh-environment requirements. Leoni AG, headquartered in Nuremberg, Germany, specializes in thermoplastic-sheathed cables for automotive and industrial sectors, differentiating through application-specific engineering and mission-critical reliability expectations.
In the Americas and Europe, Belden Inc., based in St. Louis, USA, provides thermoplastic-sheathed data, control, and power cables for harsh environments, while the Lapp Group, headquartered in Stuttgart, Germany, serves as a global supplier of ÖLFLEX thermoplastic-sheathed cables for machinery and automation. These players reinforce the importance of specialization, brand equity in industrial and connectivity segments, and the ability to support complex specification processes.
The competitive picture is not static. Recent launches, certification updates, trade-show positioning, and project awards indicate that leading participants are actively reshaping portfolios around fire performance, renewable-energy compatibility, installer efficiency, and project-scale supply reliability. For companies evaluating partnership, sourcing, or competitive response strategies, tracking these moves in the context of regional compliance requirements and procurement shifts is essential.
Research Architecture and Practical Utility
This study is structured to support both strategic planning and operational decision-making. Beyond aggregate market sizing and forward projections, the report examines the interplay between product types, application verticals, and regional demand patterns, enabling readers to identify where volume concentration, specification premiums, and growth accelerations are most likely to emerge. The segmentation analysis is designed to clarify not only where demand currently resides, but also how structural factors such as building codes, infrastructure spending, and procurement geography influence consumption behavior over the forecast period.
The competitive assessment extends beyond simple vendor listing. It maps corporate positioning, geographic coverage, application focus, and recent strategic developments to help stakeholders interpret who is gaining traction, where certification and product launches may alter specification outcomes, and how supply chain realignments could influence procurement choices. By embedding recent industry events within the broader market context, the report helps readers distinguish transient announcements from durable shifts in competitive dynamics.
Operational planners will also find value in the integration of material, regulatory, and trade considerations. The analysis addresses how PVC resin pricing dynamics, flame-retardancy amendments, low-smoke zero-halogen demand pull, and tariff-driven sourcing migration interact to shape cost structures, product design choices, and channel strategy. This multidisciplinary framing is intended to reduce the gap between market intelligence and executable plans, whether those plans involve capacity allocation, product roadmap decisions, distributor expansion, or risk-managed sourcing.
Implications for 2026 Decision-Making
As enterprises move into 2026 planning, the thermoplastic-sheathed cable market offers a case study in how mature demand growth, regulatory tightening, and trade reconfiguration can combine to create both risk and opportunity. The projected trajectory toward the 2032 horizon suggests that scale alone will not determine success; rather, competitive advantage will increasingly depend on compliance agility, specification alignment, regional sourcing competence, and the ability to respond to evolving building and infrastructure standards.
Thermoplastic Composites Market
For manufacturers, the imperative is to reconcile product development with the dual demands of performance upgrading and cost discipline, particularly as flame retardancy, low-smoke characteristics, and installer efficiency become more decisive in specification wins. For distributors and procurement teams, the challenge is to balance cost stability against geopolitical and tariff-related sourcing shifts, while maintaining access to certified, regionally appropriate product assortments. For investors and strategy teams, the opportunity lies in identifying where demand concentration, project pipeline momentum, and competitive positioning converge to support durable margin profiles and market-share gains.
The full Worldwide Thermoplastic-sheathed Cable Market report expands each of these dimensions with detailed segmentation interpretation, regional demand narratives, competitive benchmarking, and forward scenario context. It is designed to serve as a working reference for teams that need more than headline figures: teams that require a coherent, evidence-based view of how the market is structured, how it is changing, and where strategic leverage can be created in 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Worldwide Thermoplastic-sheathed Cable Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Indoor Lighting Control Market to Hit $25.67B by 2032 at 8.52% CAGR
By pmarketresearch, 2026-09-16
Illuminating the Future: Strategic Imperatives in the Global Indoor Lighting Control Systems Market
Executive Perspective
The transition from conventional illumination to intelligent, connected indoor lighting control systems represents one of the most tangible yet complex operational shifts in modern facility management. As organizations across commercial, industrial, and residential sectors confront rising energy costs, stringent sustainability mandates, and the operational demands of hybrid work environments, the strategic deployment of lighting controls has evolved from a peripheral efficiency upgrade into a core infrastructure investment. This analysis introduces our latest comprehensive study, Worldwide Indoor Lighting Control Systems Market, and outlines why its findings carry direct decision-making value for executive teams, procurement leaders, and technology strategists navigating the 2026 landscape.
Market Trajectory and Macro-Scale Context
Over the past half-decade, the indoor lighting control sector has demonstrated consistent annual expansion, reflecting a structural acceleration rather than a cyclical upturn. The global market, valued at approximately 8,900 million USD in 2020, has steadily climbed through a 2025 base year valuation near 14,500 million USD. The trajectory through the 2026-2032 forecast window projects sustained growth, with total market size expected to reach roughly 25,667 million USD by the close of the decade. This expansion is underpinned by a compound annual growth rate of 8.52 percent, indicating durable demand across geographies and deployment types. Several structural forces explain this momentum. First, the rapid overhaul of commercial interiors to support flexible occupancy patterns has made networked lighting controls a prerequisite for both energy optimization and occupant experience. Second, regulatory frameworks in major industrial economies have shifted lighting controls from optional best practices toward default compliance requirements. Third, the convergence of lighting infrastructure with broader building management ecosystems has expanded the addressable scope of control platforms, transforming them from isolated switching mechanisms into data-generating nodes within integrated smart building architectures. Importantly, the market's growth profile does not suggest a homogeneous environment. Deployment preferences, technology adoption curves, and regional regulatory pacing create distinct prioritization matrices for stakeholders. Our research isolates these vectors without relying on top-line generalizations, enabling readers to map investment and product roadmaps against actionable market realities rather than aggregate industry narratives.
What the Study Delivers: Operational Intelligence for 2026 Decision-Making
The Worldwide Indoor Lighting Control Systems Market report is designed as a working reference rather than a high-level market overview. It provides structured, forward-looking intelligence that aligns with the planning cycles of hardware manufacturers, system integrators, facility operators, and capital allocators. The study's architecture prioritizes clarity in three operational dimensions: technology evolution, deployment contexts, and competitive positioning. At the technology layer, the analysis examines the ongoing interplay between wired and wireless control architectures. While traditional wired frameworks continue to anchor large-scale retrofits and mission-critical commercial environments due to their established reliability and deterministic performance, wireless and hybrid configurations are capturing disproportionate attention in renovation scenarios, modular commercial spaces, and multi-tenant residential properties. The study tracks how protocol standardization, mesh networking capabilities, and low-latency sensor integration are reshaping the practical trade-offs between installation complexity, scalability, and lifecycle cost. The application dimension extends beyond categorical labels to assess how control requirements diverge across environment types. Commercial facilities increasingly demand centralized management, daylight harvesting, and occupancy-responsive scheduling that can interface with broader operational systems. Industrial settings prioritize robustness, fault tolerance, and energy performance across expansive, high-bay environments. Residential deployments, meanwhile, are shaped by user experience expectations, retrofit feasibility, and the growing integration of lighting controls into home automation ecosystems. By mapping these distinctions against market dynamics, the report equips decision-makers with a clearer sense of where product positioning, service models, and pricing strategies will encounter the most friction or opportunity. The regional dimension provides a framework for evaluating demand maturity, regulatory exposure, and competitive intensity across major geographic markets. Rather than presenting isolated figures, the analysis connects regional trajectories to underlying drivers such as construction activity, renovation pipelines, energy policy enforcement, and local vendor ecosystems. This approach allows organizations to calibrate geographic expansion, supply chain planning, and partnership strategies in alignment with real-world market pacing.
Competitive Landscape: Positioning, Innovation, and Ecosystem Control
The competitive landscape in indoor lighting control systems is characterized by a moderate concentration of established players, interspersed with technology specialists and protocol-driven component suppliers. The combined market share of the top three firms sits at approximately 32.5 percent, while the top five collectively account for around 42.8 percent of total industry revenue. This structure signals a market that is neither dominated by a single platform monopoly nor so fragmented that differentiation becomes meaningless. Instead, competition hinges on technology interoperability, ecosystem integration, brand trust in large-scale commercial deployments, and the ability to move quickly into emerging protocol and sensor-driven use cases. Several leading organizations illustrate how competitive advantage is being constructed in this environment. Signify has advanced its Interact IoT-based control portfolio for commercial buildings, combining sensor intelligence, gateway architecture, and cloud management to support scalable indoor deployments. Lutron Electronics continues to emphasize flexible wired and wireless control lines for office and residential automation, with a strong track record in dimming, sensor integration, and system-level automation platforms. Acuity Brands has expanded its nLight platform presence by strengthening compatibility between wired and wireless controls and networked indoor management tools. Schneider Electric has positioned its EcoStruxure Building IoT approach as a convergence point for lighting control, HVAC, and security systems within smart building frameworks, emphasizing operational integration over standalone lighting performance. Legrand contributes through residential and commercial control solutions built around recognized protocols, supporting hotel, multi-family, and indoor commercial applications. ABB's Ability Smart Buildings offering extends the conversation further into energy-efficient indoor management with DALI and KNX integration. Meanwhile, component and control specialists such as ams-OSRAM, Tridonic, and Helvar focus on enabling technologies—smart control modules, DALI-2 and wireless-compatible drivers, and sensor-integrated DALI-based systems—allowing broader system designers to assemble interoperable indoor installations at scale. Additional players including Eaton, Delta Electronics, and Hubbell Lighting reinforce the market's breadth, each contributing distinct control architectures, wireless nodes, and commercial/industrial LED-focused solutions. Recent product and certification activity reinforces the strategic importance of interoperability and intelligent sensing. Signify showcased an updated Interact Office offering with AI-based occupancy sensing for commercial spaces. Lutron introduced a node-based wireless control line targeting indoor commercial environments. Acuity Brands achieved DALI-2 certification for its wireless sensors and controls, while Tridonic expanded thread-compatible wireless control support for indoor mesh networking. These developments are not isolated product announcements; they reflect a broader market transition toward standardized communication, plug-and-play compatibility, and occupancy-aware automation. Organizations evaluating vendor relationships, partnership structures, or internal R&D priorities should treat these shifts as early indicators of where cycle times, integration burdens, and end-user expectations are heading.
Industry Dynamics: Standards, Policy, and Cost Realities
The indoor lighting control market is shaped as much by external conditions as by technological innovation. Regulatory and standardization developments have increasingly functioned as market accelerators by reducing ambiguity around performance expectations and interoperability requirements. The EU Ecodesign Directive establishes performance expectations for lighting controls in non-residential buildings, reinforcing the financial and compliance case for control deployment. In parallel, the DALI-2 standard has become a critical reference point for indoor lighting control interoperability, introducing improved error handling and predictable device communication across multi-vendor environments. The KNX protocol continues to provide a widely certified foundation for multi-vendor indoor compatibility, supporting product breadth across thousands of certified implementations. At the regional level, policy frameworks such as the US Energy Policy Act have codified automatic shutoff control expectations for large buildings, embedding lighting controls into baseline operational compliance. Cost dynamics also play a central role in procurement and deployment decisions. Sensor hardware, particularly occupancy-sensing components used in commercial installations, has settled into a recognizable cost band that strongly influences total system economics during retrofits and new construction. While sensor pricing alone does not determine project viability, it interacts with labor intensity, commissioning complexity, and long-term energy savings to shape the adoption curve for different control architectures. The report uses these operational realities to help readers assess where system-level savings are most achievable and where installation friction may offset anticipated efficiency gains.
Why the 2026 Outlook Matters Now
The 2026-2032 forecast window is particularly consequential because it captures the intersection of several simultaneous transitions. Markets are moving beyond early adoption arguments and toward scale execution. Building operators are asking not whether to install controls, but how to standardize across portfolios, manage vendor diversity, and integrate lighting data into broader energy and space-utilization strategies. Technology providers, meanwhile, must navigate protocol evolution, sensor intelligence, cloud-based management, and the commercial realities of wired-versus-wireless deployment trade-offs. For executives, the strategic question is no longer centered on overall market size alone. The more valuable inquiries concern growth composition, competitive pressure points, technology substitution risk, and regional readiness. Where are wireless and hybrid models accelerating fastest? Which application segments are most exposed to standard-driven adoption? How are leading vendors differentiating around integration, service, and protocol support? And how should organizations interpret the balance between established incumbents and specialists competing in niche architectural or protocol-driven segments? The report provides the analytical scaffolding to answer these questions with greater confidence. By examining market structure, competitive moves, regulatory tailwinds, and deployment considerations together, it supports more disciplined planning for product strategy, procurement timing, partnership development, and market entry or expansion decisions.
Conclusion: Turning Market Intelligence into Actionable Advantage
Indoor lighting control systems have matured into an essential infrastructure category that sits at the crossroads of energy management, occupant experience, and smart building integration. The growth trajectory through 2032 reflects sustained structural demand, but the strategic opportunities within that trajectory are uneven and highly dependent on technology readiness, regulatory context, and application-specific requirements. Our Worldwide Indoor Lighting Control Systems Market study is designed to give organizations the depth they need to act, not just the summary they need to brief. It translates broad market momentum into operational insight, helping leadership teams evaluate where to invest, where to standardize, and where to differentiate. For readers seeking a fuller examination of segmentation behavior, vendor positioning, protocol adoption, regional pacing, and forward-looking scenario analysis, the complete report provides the comprehensive intelligence required to align strategy with the realities of the 2026 market.
Worldwide Indoor Lighting Control Systems Market
Worldwide Emergency Lighting Controller Market
For detailed analysis of this topic, please visit the official page: Worldwide Indoor Lighting Control Systems Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Wood Gas Generator Market Hits $696.8M in 2025, 6.54% CAGR to $1,085.8M by 2032
By pmarketresearch, 2026-09-16
Strategic Intelligence: Navigating the Wood Gas Generator Market Landscape in 2026
As the global energy paradigm shifts toward decentralized renewable solutions, the wood gas generator sector stands at a critical inflection point. For strategic leaders and industry stakeholders, understanding the trajectory of this market is not merely an academic exercise but a operational imperative. This article serves as an executive briefing on the findings contained within our latest Worldwide Wood Gas Generator Market research, outlining the macroeconomic forces, competitive dynamics, and technological trends that will define investment and operational decisions throughout the forecast period ending in 2032.
The urgency for this analysis stems from the accelerating convergence of regulatory support, raw material availability, and the economic necessity of energy independence. Our research provides a granular look at how these factors intersect, offering a roadmap for navigating the complexities of biomass gasification technology deployment.
Macro Market Trajectory and Growth Drivers
The historical performance of the wood gas generator market demonstrates a consistent upward trend, reflecting the global commitment to reducing carbon footprints while maintaining energy security. Our analysis tracks revenue performance from 2020 through the base year of 2025, revealing a sector that has resiliently navigated supply chain fluctuations and varying policy landscapes. In 2020, the market valuation stood at approximately 512.45 million USD. By 2025, this figure had grown to 696.84 million USD, indicating a robust rate of adoption across key industrial and residential sectors.
Worldwide Wood Gas Generator Market
Looking forward, the forecast period from 2026 to 2032 projects sustained expansion. The market is expected to initiate this phase at roughly 700.53 million USD in 2026, climbing steadily to reach an estimated 1085.75 million USD by 2032. This trajectory suggests a Compound Annual Growth Rate (CAGR) of 6.54 percent over the forecast window. Such growth is underpinned by several critical drivers, including the increasing demand for decentralized heat and power generation solutions that reduce reliance on centralized grids and fossil fuel imports.
Stakeholders must interpret these figures not just as historical records but as indicators of momentum. The transition from the mid-600 million USD range in 2024 to nearly 700 million USD in 2025 highlights a sector gaining traction. The subsequent years show an acceleration in value accumulation, suggesting that economies of scale and technological maturation are beginning to yield tangible financial results for manufacturers and operators alike.
Technological Segmentation and Regional Distribution
The market is not monolithic; it is defined by distinct technological approaches and geographic concentrations that dictate strategy. Our research delves deeply into the types of gasifiers driving this revenue, analyzing the performance and deployment trends of Downdraft, Updraft, Cross-draft, and Fluidized Bed gasifiers. Each technology offers specific advantages regarding feedstock flexibility, tar content in the producer gas, and operational scale. The comprehensive data within the full report breaks down how these technologies are prioritized across different use cases, allowing engineering and procurement teams to align hardware selection with specific project requirements.
Geographically, the market exhibits a clear hierarchy of maturity and demand. Europe remains a dominant force in terms of market contribution, driven by stringent EU emissions targets and strong incentives for decentralized biomass Combined Heat and Power (CHP) systems. Asia Pacific follows as a significant region, reflecting rapid industrialization and growing energy needs in emerging economies. North America also represents a substantial portion of the market, supported by both commercial applications and rural development initiatives. Latin America and the Middle East and Africa contribute to the global total, often focusing on specific industrial thermal applications or off-grid power solutions where diesel displacement is economically critical.
Micro Gas Generator Market
Understanding the spatial distribution of demand is vital for logistics, supply chain planning, and local partnership development. Our report details the regional nuances that influence market penetration rates, including local regulatory frameworks and the availability of woody biomass feedstocks such as pellets and chips.
Application Verticals and Operational Efficiency
The utility of wood gas generators spans a diverse range of application verticals, each with unique economic drivers. The largest share of market activity is concentrated in Electric Power Generation, where the ability to convert woody biomass into electricity supports everything from micro-grids to larger industrial power needs. Industrial Thermal Energy represents another major pillar, utilizing the heat output from gasification processes for manufacturing and processing applications. Residential Heating markets also show significant activity, particularly in regions where households seek alternatives to traditional heating oils or electric heating systems.
Additionally, the Bio-Chemical Production sector is emerging as a niche but growing area, where syngas produced from wood gasification serves as a feedstock for chemical processes. The full study provides detailed insights into the revenue contributions and growth rates of each application segment, helping investors identify high-yield verticals.
Economic efficiency remains a primary motivator for adoption. Sector analysis indicates that on-site biomass gasification from wood waste can reduce electricity costs significantly compared to diesel generation. Reported examples in the industry highlight drops in energy costs from approximately 0.38 USD per kWh to as low as 0.07 USD per kWh, with project payback periods ranging from 3 to 6 years. These economic metrics are crucial for feasibility studies and investment committee approvals.
Competitive Dynamics and Key Players
The competitive landscape is characterized by a mix of established European manufacturers, innovative North American developers, and expanding players in Asia. The market concentration remains relatively fragmented yet competitive, with the top three companies holding a combined market share of approximately 18.45 percent and the top five holding 28.12 percent. This structure suggests room for consolidation but also indicates a healthy level of competition that drives innovation.
Key companies analyzed in depth within our report include Burkhardt GmbH, based in Mühlhausen, Germany, which manufactures wood gasifier V3.90 and V4.50 series CHP plants using wood pellets or chips for decentralized heat and power generation. Their focus on modular solutions and ongoing process optimization positions them strongly in the European market. Similarly, Spanner Re² GmbH, also headquartered in Germany, provides wood gasification systems and decentralized biomass CHP plants producing CO2-neutral energy from wood waste and biomass. Their installations worldwide include cascades for businesses and heating networks, reflecting a scalable approach to deployment.
In North America, ALL Power Labs, located in Berkeley, California, develops small-scale biomass gasification systems including Power Pallet and GEK Gasifier kits for converting woody biomass into electricity and heat, with a focus on modular, automated solutions. This focus on accessibility and automation appeals to a different segment of the market compared to large-scale industrial plants.
On the industrial scale, Powermax Renewable Energy (Wuxi Powermax), based in Wuxi, Jiangsu, China, offers biomass gasification power plants and wood gas generator systems with over 30 years of experience and over 100 global projects. They specialize in converting wood waste, chips, and residues into electricity, often offering industrial-scale solutions from 50 kW upwards. Other notable entities include Ankur Scientific Energy Technologies in India, known as a commercial producer of wood gasifier systems for stationary power generation applications, and GASEK in Finland, which manufactures commercially available wood gasifier systems primarily for electricity production.
The competitive landscape also includes Holzenergie Wegscheid GmbH and Volter in Finland, both providing specialized biomass gasification-based CHP solutions using wood. Vulcan Gasifier LLC in the USA and Community Power Corporation also remain active in biomass gasification and wood gas generator systems, contributing to the diverse ecosystem of providers.
Strategic Implications of Recent Developments
Market dynamics are heavily influenced by recent financial and regulatory developments. In March 2026, the USDA Rural Business-Cooperative Service approved a 25 million USD loan guarantee for a 3 MW biomass gasification plant converting forestry biomass waste into synthetic natural gas. This event underscores the role of public financing in de-risking large-scale projects and supporting rural renewable energy infrastructure. Such interventions signal to the private sector that government backing is available for projects that align with national forestry and energy goals.
Furthermore, regulatory environments in Europe and national incentives for decentralized biomass CHP continue to contribute to the deployment of wood gasifiers as part of CO2-neutral energy strategies. These incentives reduce the capital expenditure burden and improve the internal rate of return for projects. Companies like Powermax Renewable Energy continue to promote and availability of wood waste gasification power plants and biomass gas generator sets, ensuring that industrial-scale offerings remain accessible to a broad range of clients.
Fuel consistency remains a technical challenge that industry leaders are addressing. Wood pellets and wood chips serve as primary fuels for commercial wood gasifiers in CHP plants, with systems optimized for consistent feedstock quality to maintain gasification efficiency. Operators must consider supply chain stability for these raw materials when planning long-term projects.
Report Scope and Decision Support
Our Worldwide Wood Gas Generator Market research is designed to function as a comprehensive decision-support tool. The full report extends beyond the high-level trends summarized here to provide detailed historical data tables, precise segmentation splits across region, type, and application, and exclusive competitor profiling. We examine the market concentration metrics, supply chain vulnerabilities, and the specific impact of regulatory changes on profitability across different jurisdictions.
For corporate strategy teams, the report offers a benchmark against which internal projections can be validated. For investors, it provides the due diligence necessary to assess the risk-reward profile of entry into this sector. The inclusion of recent developments, such as specific loan guarantees and product updates from key players, ensures that the data remains current and actionable.
The analysis covers the historical period from 2020 to 2025 and provides forecasts through 2032, allowing for long-term strategic planning. By integrating data on market size, growth rates, and competitive positioning, the study enables stakeholders to identify whitespace opportunities and potential threats. Whether evaluating a partnership with a manufacturer like Burkhardt or Spanner Re², or assessing the viability of a local project supported by USDA financing, the intelligence contained herein is structured to reduce uncertainty.
Conclusion: The Path Forward
The wood gas generator market is poised for continued expansion, driven by the dual imperatives of decarbonization and energy security. The growth from roughly 512 million USD in 2020 to a projected 1085 million USD by 2032 reflects a sector that is maturing and integrating deeply into the global energy mix. However, success in this environment requires more than general awareness; it demands precise data on segmentation, competitor capabilities, and regulatory tailwinds.
Stakeholders who leverage detailed market intelligence will be better positioned to capture value in this evolving landscape. We invite you to access the full Worldwide Wood Gas Generator Market research report to unlock the complete dataset and strategic recommendations necessary to navigate the opportunities of 2026 and beyond. The detailed breakdowns of regional performance, specific technology adoption rates, and granular competitor analysis are available exclusively through the full study, providing the depth required for high-stakes decision-making.
For detailed analysis of this topic, please visit the official page: Worldwide Wood Gas Generator Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Polycarbonate Glazing Market Hits $1,832M in 2025, Projected 5.19% CAGR Through 2032
By pmarketresearch, 2026-09-16
Strategic Horizons: Navigating the Worldwide Polycarbonate Glazing Market Through 2032
The global market for polycarbonate glazing stands at a pivotal inflection point. As industries from automotive to construction demand materials that balance transparency, impact resistance, and sustainability, polycarbonate has cemented its role as a foundational material for modern light transmission and protective applications. Our latest Worldwide Polycarbonate Glazing Market research delivers a comprehensive, data-grounded roadmap for executives, investors, and supply chain strategists who must navigate this evolving landscape with precision.
Set against a five-year historical baseline spanning 2020 to 2025 and a forward-looking forecast window from 2026 through 2032, this study is engineered to inform capital allocation, product roadmap decisions, and competitive positioning in the year ahead and beyond.
The Market Trajectory: Growth, Consolidation, and Strategic Timing
The polycarbonate glazing market has demonstrated resilient expansion over the past half-decade, recovering from mid-cycle adjustments to reach a base-year valuation of 1,832.03 million USD in 2025. Looking forward, the trajectory points to sustained momentum with a compound annual growth rate of 5.19 percent across the forecast horizon. By 2032, the market is projected to approach 2,612.42 million USD, reflecting steady demand pull from high-volume structural and specialized transparency applications.
This growth is not uniform across time or geography. Early forecast years show measured expansion, with the market moving from 1,946.39 million USD in 2026 to 2,066.15 million USD in 2027, before a sharper acceleration toward the decade's end as capacity comes online and end-use adoption broadens. Understanding these inflection points is critical for timing capacity investments, inventory planning, and regional expansion strategies.
Polycarbonate Sheet Market
Concentration patterns further illuminate the competitive reality. The top three players account for 38.4 percent of market revenue, while the top five capture 52.15 percent. This concentrated structure means that scale advantages, feedstock partnerships, and technological differentiation carry outsized weight. For challengers and new entrants, the path to meaningful share lies in targeted application niches, regional specialization, or sustainability credentials that resonate with procurement mandates.
Segment-Level Dynamics: Type, Application, and the Shape of Demand
Polycarbonate glazing demand is shaped by a clear hierarchy of product types and end-use sectors, each with distinct performance requirements and cost sensitivities. Solid polycarbonate leads the type segmentation, reflecting its broad applicability in architectural facades, security glazing, and transportation transparencies where baseline clarity and impact resistance are paramount. Multiwall polycarbonate follows, driven by its insulating properties and growing use in construction and agricultural enclosures. Corrugated polycarbonate rounds out the type mix, serving cost-sensitive and high-durability applications where structural profile matters as much as optical performance.
On the application side, automotive remains the dominant demand engine, fueled by lightweighting imperatives, electrification-related redesigns, and the need for high-clarity, UV-stabilized glazing in passenger and commercial vehicles. Construction ranks closely, supported by building energy codes, retrofits, and the substitution of heavier or less durable materials in roofing, skylights, and transparent wall systems. Security and protection applications represent a specialized but high-value segment, while agriculture and other end-use categories provide additional growth nodes where durability and cost efficiency intersect.
Importantly, the interplay between type and application is not static. Buyers increasingly evaluate multiwall versus solid formats through the lens of thermal performance, fabrication complexity, and total installed cost. Procurement teams in construction and transportation are also weighing recycled-content and mass-balance resins as part of broader ESG procurement policies. These cross-cutting considerations make segment-level analysis essential for product managers and sales strategists who must align material grades with purchasing criteria.
Regional Realities: Where Growth Is Concentrated and Why
Regional demand patterns reveal a market where Asia Pacific anchors volume, Europe drives specification-led and regulation-conscious adoption, and North America combines large-scale construction and industrial demand with a mature distribution ecosystem. Latin America and the Middle East and Africa contribute meaningful but smaller shares, often expanding through infrastructure projects, agricultural modernization, and import-dependent supply chains.
These regional profiles are not merely size differences; they reflect divergent procurement behaviors, regulatory environments, and logistics realities. In Europe, compliance with evolving substance restrictions and energy-performance expectations shapes grade selection and supplier qualification. In Asia Pacific, rapid industrial capacity additions and localized fabrication networks influence price dynamics and lead-time expectations. In North America, large project pipelines and a preference for domestically sourced or regionally distributed materials affect fulfillment strategies. Understanding these regional fingerprints allows companies to prioritize go-to-market investments, distribution partnerships, and compliance readiness where they will yield the greatest return.
Competitive Landscape: Incumbents, Specialists, and the Ecosystem of Scale
The competitive field blends global resin and sheet producers with regional formulators and specialized glazing manufacturers. Covestro AG continues to anchor its position through Makrolon-branded polycarbonate resins and sheets tailored for architectural glazing, automotive glazing, and high-impact transparent applications, with an emphasis on UV stabilization and impact resistance. Its January 2025 announcement of a major capacity expansion at its Hebron, Ohio facility signals a deliberate push to serve custom grades across automotive, electronics, and specialty film and glazing demand.
SABIC complements this landscape with LEXAN polycarbonate sheets and resins spanning solid, multiwall, and architectural systems, with a clear focus on durability, clarity, and energy efficiency. The recent integration activity involving POLYVANTIS, including the launch of a new LEXAN sheet series with enhanced lightweight properties and mechanical performance for rail and glazing applications, illustrates how product innovation is being directed at demanding mobility and transparency use cases.
Alongside these global players, a robust set of specialists and regional manufacturers competes on application focus, fabrication capability, and regional service. Palram Industries Ltd. specializes in polycarbonate glazing products including flat solid sheets, multiwall sheets, and corrugated panels for construction, agricultural, and transportation uses. Trinseo supplies polycarbonate resins and sheets with a growing emphasis on sustainable and recycled-content solutions for building and industrial applications. Teijin Limited manufactures high-performance polycarbonate materials, including optical and impact-resistant grades for architectural and specialty applications, while Mitsubishi Gas Chemical Company, Inc. has advanced its sustainability positioning through ISCC PLUS certification for polycarbonate resin at its Kashima plant, using a mass-balance approach for sustainable raw materials applicable to glazing sheet production.
The North American and European markets also feature strong regional contributors. Plaskolite, Inc. offers polycarbonate sheets with emphasis on impact resistance and fabrication for North American construction and industrial markets. EXOLON GROUP, derived from former Covestro European sheet operations, supplies high-quality polycarbonate and thermoplastic sheets targeting construction and industrial sectors. 3A Composites GmbH provides polycarbonate sheets under established brand names for transportation, construction, and renewable energy glazing applications, while Arlaplast focuses on European glazing markets with sustainable processing capabilities. In Asia, LG Chem produces polycarbonate resins suitable for conversion into high-performance glazing sheets for automotive and architectural uses, and LOTTE Chemical CORPORATION supplies polycarbonate materials for sheet extrusion and glazing applications addressing global construction and electronics-related transparency needs.
Finally, Deepak Advanced Materials Limited's March 2025 opening of a new manufacturing facility in Gujarat, India, focused on polycarbonate and engineering polymer compounds for construction and industrial applications including glazing, underscores the expanding manufacturing footprint in the region and the intensifying competition for regional share.
Industry Dynamics: Feedstock Volatility, Regulation, and Trade Realities
Strategic decision-making in this market cannot be separated from the operational and regulatory forces shaping supply and demand. The primary feedstock for polycarbonate, Bisphenol A, experienced mixed price trajectories in Asia Pacific during the second quarter of 2025, with April increases linked to plant maintenance and restocking. These fluctuations ripple through resin pricing, margin planning, and procurement timing, making feedstock visibility a core input for commercial strategy.
Regulatory developments add another layer of complexity. EU regulation banning Bisphenol A and its salts in food contact materials entered into force on 20 January 2025, impacting certain polycarbonate applications while maintaining specific migration limits for non-infant uses. Complementary EU regulations impose stricter Bisphenol A migration limits in food contact plastics effective in 2025, requiring compliance statements for polycarbonate materials. While these restrictions primarily target food-contact applications such as infant feeding bottles and certain containers, they are also driving development of alternative or low-migration grades for broader uses, including non-food glazing, and reshaping supplier qualification processes.
Trade policy introduces further uncertainty. U.S. reciprocal tariffs in 2025, including potential impacts on imports from South Korea, the European Union, and Thailand, affect polycarbonate supply chains with baseline duties applied amid ongoing negotiations. For manufacturers and distributors, these dynamics influence landed-cost calculations, sourcing diversification, and inventory positioning. Companies that map tariff exposure and evaluate alternate supply paths will be better positioned to protect margins and maintain service levels.
Inside the Study: What Decision-Makers Will Find
This market research is built for execution, not just observation. It translates macro trends into an actionable framework covering market sizing and forecast logic, segmentation analysis by type and application, regional demand profiles, and competitive intelligence on the companies shaping pricing, innovation, and capacity. The study details recent developments that matter for near-term planning, including capacity expansions, new facility openings, product launches, and sustainability certifications that signal where supply and differentiation are heading.
Worldwide Polycarbonate Glazing Market
Beyond the numbers, the report connects market structure to commercial implications. It examines how concentration influences pricing power and partnership strategy, how regulatory and feedstock dynamics affect cost structures and qualifying criteria, and how regional demand fingerprints should inform sales coverage and distribution design. The analysis also addresses the practical questions procurement and product teams face: which material grades align with performance and compliance requirements, where multiwall and solid formats create value tradeoffs, and how sustainability credentials are increasingly integrated into purchasing decisions.
The report's structure allows users to move from high-level strategic context to targeted insights without losing rigor. Whether the objective is to evaluate entry opportunities, refine capacity planning, benchmark competitor moves, or build a sourcing and compliance roadmap, the study provides a consistent evidence base and clear analytical pathways.
Why This Research Matters for 2026 Decisions
In a market projected to grow steadily yet unevenly, with concentrated incumbents, evolving regulation, and feedstock and trade volatility, decisions made in 2026 will shape competitive standing through the end of the decade. Companies that align product portfolios with application-led demand, anticipate regional procurement behavior, and prepare for regulatory and cost fluctuations will capture disproportionate value. Those that treat polycarbonate glazing as a commodity category risk missing the specificity that now drives specification, qualification, and repeat purchasing.
This Worldwide Polycarbonate Glazing Market research is designed to reduce ambiguity and accelerate better decisions. It provides the market context, segment logic, competitive mapping, and dynamic intelligence needed to prioritize investments, sharpen go-to-market execution, and build resilience into supply and sourcing strategies.
To access the full dataset, detailed segmentation breakdowns, complete company profiles, regional demand estimates, and the full set of recent developments informing this analysis, visit the source page for the complete report. The comprehensive intelligence is available to support strategic planning, investment review, and operational decision-making across the 2026 to 2032 horizon.
For detailed analysis of this topic, please visit the official page: Worldwide Polycarbonate Glazing Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com