

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global Automotive Engine Oil Additives Market Hits $18.02B in 2025, Forecasts 3.21% CAGR to 2032

Navigating the Next Wave: Strategic Imperatives in the Global Automotive Engine Oil Additives Market (2026–2032)
As the automotive industry accelerates toward stricter emissions mandates, advanced powertrain architectures, and evolving performance standards, the engine oil additives sector stands at a critical inflection point. For executives, product developers, and market strategists operating within the lubricants value chain, understanding the trajectory of this market is no longer optional—it is a strategic necessity. Our latest Worldwide Automotive Engine Oil Additives Market research study delivers a comprehensive, forward-looking intelligence framework designed to equip decision-makers with the actionable insights required to navigate the 2026–2032 forecast period with precision.
The global market for automotive engine oil additives has demonstrated remarkable resilience and steady expansion over the past half-decade. Valued at approximately 15.2 billion USD in 2020, the sector has grown consistently to reach an estimated 18.02 billion USD by 2025. This upward trajectory is projected to continue, with the market expected to surpass 19.18 billion USD in 2026 and ultimately approach 22.47 billion USD by 2032. Driven by a compound annual growth rate (CAGR) of 3.21 percent across the forecast horizon, the industry reflects a mature yet innovation-led landscape where incremental gains in formulation efficiency, regulatory compliance, and regional demand shifts will dictate competitive advantage.
However, top-line growth figures only tell part of the story. The real strategic value of our report lies in its granular dissection of market architecture, competitive maneuvering, and the regulatory and macroeconomic forces that will reshape sourcing strategies, pricing architectures, and product development timelines. This article serves as a strategic preview of the full research publication, highlighting the analytical depth, operational frameworks, and competitive intelligence contained within—and explaining why institutional investors, OEM formulation teams, and additive suppliers must treat this study as an essential planning instrument for the next seven years.
Market Architecture and Segmentation Dynamics
The automotive engine oil additives landscape is inherently multi-dimensional, shaped by product chemistry, vehicle application profiles, and geographically dispersed demand centers. Our research systematically maps these intersecting layers to provide a clear view of where volume concentration exists and where emerging opportunities are materializing.
When analyzing the product-type ecosystem, the market reveals a clear hierarchy of functional demand. Dispersants continue to command the largest share of additive consumption, reflecting their critical role in maintaining engine cleanliness, suspending contaminants, and preventing sludge formation across high-mileage passenger and commercial platforms. Detergents follow closely, serving as essential alkaline components that neutralize acidic combustion byproducts and protect metal surfaces. Viscosity index improvers represent another cornerstone category, enabling multi-grade formulations that balance cold-start performance with high-temperature stability. Anti-wear agents, oxidation inhibitors, and corrosion inhibitors round out the essential functional suite, with each chemistry category experiencing distinct growth pressures tied to evolving engine designs and lubricant specification upgrades. Our full report delivers precise volume and revenue mappings across these categories, allowing procurement and R&D leadership to benchmark their portfolio exposure against market-wide demand signals.
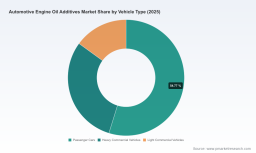
Segmentation by vehicle type further illuminates consumption patterns. Passenger cars remain the dominant application channel, driven by global fleet expansion, replacement lubricant demand, and the rapid adoption of low-viscosity, fuel-efficient formulations. Heavy commercial vehicles constitute a substantial secondary demand pillar, particularly in regions where long-haul freight, mining, and construction activities sustain steady consumption of high-performance diesel engine lubricants. Light commercial vehicles occupy a growing mid-tier segment, increasingly influenced by urban delivery logistics, last-mile electrification transition timelines, and localized emissions enforcement. By connecting vehicle-type consumption profiles to regional economic indicators and regulatory calendars, our study enables clients to anticipate category-specific demand shifts rather than react to them.
Geographic Distribution and Regional Growth Vectors
The spatial distribution of additive demand reveals a structurally imbalanced but evolving global map. Asia Pacific continues to represent the largest regional consumption base, underpinned by dense automotive manufacturing networks, expanding middle-class vehicle ownership, and aggressive localization strategies by both multinational suppliers and domestic formulators. North America maintains a robust secondary market, shaped by mature vehicle parc dynamics, stringent OEM performance expectations, and ongoing reformulation activity surrounding latest-generation specifications. Europe occupies a strategically complex position, where decarbonization policies, OEM approvals, and premium lubricant positioning intersect with steady market consolidation.
Fuel Additives Market
Latin America and the Middle East and Africa, while smaller in absolute scale, offer distinctive growth narratives. The Latin American market reflects cyclical economic sensitivities but benefits from sustained commercial fleet activity and incremental modernization of lubricant standards. The Middle East and Africa region presents a dual profile: established demand in Gulf economies with strong automotive import markets, alongside emerging opportunity corridors in parts of Africa where infrastructure investment and vehicle parc growth are gradually lifting baseline lubricant consumption. Our full report contextualizes these regional profiles with historical trend analysis, capacity localization indicators, and supply-demand balance assessments—without relying on superficial aggregate figures—so that market entry, partnership, and sourcing decisions are grounded in structural reality rather than headline numbers.
Competitive Landscape and Strategic Positioning
The engine oil additives sector is characterized by high technical barriers, concentrated intellectual property, and a competitive field that blends global multinationals with regionally focused manufacturers. Market concentration metrics underscore this reality, with the top three players collectively accounting for approximately 62.45 percent of industry revenue and the top five firms extending their combined share to roughly 81.2 percent. This structural concentration signals both the importance of portfolio strength and the persistent pressure on smaller or regionally anchored participants to differentiate through specialty chemistries, cost-efficient manufacturing, or localized customer support.
At the center of the competitive field operate several globally recognized technology providers. The Lubrizol Corporation, headquartered in Wickliffe, Ohio, remains a major global supplier of additive packages for both passenger car and heavy-duty diesel engine oils. Its technology portfolio spans viscosity modifiers, dispersants, and anti-wear components, and its recent product activity illustrates the pace of specification-driven innovation: in mid-2025, Lubrizol introduced the PV1710 passenger car engine oil additive technology to help oil marketers meet ILSAC GF-7 performance requirements effective from March 2025 onward.
Infineum International Limited, based in Abingdon, UK, and structured as a joint venture between ExxonMobil and Shell, specializes in engine oil additive packages that balance fuel efficiency, emissions control, and protection against low-speed pre-ignition (LSPI). Afton Chemical Corporation, operating from Richmond, Virginia, develops and manufactures performance additives for engine oils with a notable emphasis on driveline and fuel additive integration. Chevron Oronite Company LLC, a subsidiary of Chevron and based in San Ramon, California, maintains a strong portfolio of lubricant and fuel additives under its OLOA branded products, with a global focus on OEM approvals and specification compliance.
European chemical giants further deepen the competitive fabric. BASF SE, headquartered in Ludwigshafen, Germany, supplies a broad range of lubricant additives, including antioxidants, dispersants, and viscosity index improvers tailored for automotive formulations. Evonik Industries AG, based in Essen, Germany, leads in viscosity index improvers and offers specialized additive solutions for fuel-efficient and high-performance automotive engine oils. LANXESS AG, from Cologne, Germany, provides antioxidants and extreme-pressure agents for engine oil applications, while Croda International Plc, located in Snaith, UK, contributes specialty additives including friction modifiers and bio-based components for modern automotive lubricants. Vanderbilt Chemicals, LLC, in Norwalk, Connecticut, rounds out the U.S.-based specialty presence with anti-wear, antioxidant, and extreme-pressure additives for engine oil and industrial lubricant formulations.
Worldwide Automotive Engine Oil Additives Market
The competitive picture also extends into Asia, where domestic manufacturing capacity and regional cost structures are reshaping supply dynamics. Jinzhou Kangtai Lubricant Additives Co., Ltd., based in Jinzhou, China, produces detergent and dispersant packages for automotive and industrial applications. Wuxi South Petroleum Additive Co., Ltd., situated in Wuxi, China, focuses on lubricant additives for automotive engine oils, including anti-oxidants and corrosion inhibitors. Tianhe Chemicals Group, also based in Jinzhou, operates as a large-scale producer of lubricant additive components and packages for global automotive engine oil markets. In Europe, BRB International B.V., a subsidiary of PETRONAS based in Ittervoort, Netherlands, supplies viscosity modifiers and engine oil additive packages, while Dorf Ketal Chemicals India Pvt. Ltd., operating from Mumbai, India, delivers specialty additives for fuel and lubricant performance in automotive engine oils. Together, these players illustrate a competitive arena where technology leadership, regional manufacturing footprints, and specification-compliance readiness determine market positioning.
Regulatory Catalysts, Raw Material Pressures, and Macro Trend Alignment
No analysis of the automotive engine oil additives market is complete without addressing the regulatory and macroeconomic forces that directly influence formulation requirements, cost structures, and demand velocity. The introduction of the ILSAC GF-7 specification, first licensed on March 31, 2025, represents one of the most consequential near-term drivers of additive innovation. Emphasizing enhanced fuel efficiency, reduced low-speed pre-ignition risk, and improved piston cleanliness for model year 2026 vehicles, GF-7 is accelerating demand for advanced additive packages capable of meeting stricter performance thresholds without compromising wear protection or oil durability.
Complementary regulatory activity has further shaped the compliance landscape. The American Petroleum Institute introduced the API SQ category in 2025 alongside ILSAC GF-7, addressing ultra-low viscosity grades not covered by GF-7. Both standards remain backward compatible with prior GF-6 and API SP formulations, a design choice that provides formulators with transition flexibility but also requires careful portfolio planning to avoid redundancy and ensure specification coverage across viscosity grades. In addition, API extended the overlap period for ILSAC GF-6 and ILSAC GF-7 engine oil standards to October 1, 2026, granting additional transition time for additive and oil formulations—a development that carries direct implications for inventory strategy, product launch sequencing, and supplier communications.
On the raw material front, the operating environment has grown more volatile. In early 2026, base oil and additive costs rose amid geopolitical tensions in the Middle East and persistent supply chain pressures. Multiple suppliers announced price increases of up to 15–20 percent on finished lubricants and components, underscoring the importance of proactive procurement planning, dual-sourcing strategies, and formulation optimization to protect margins. For additive manufacturers and lubricant marketers alike, cost volatility is not merely an input issue; it is a strategic variable that affects pricing power, competitive positioning, and customer retention.
Broader macro trends reinforce the direction of travel. Stricter global emissions regulations across the United States, the European Union, China, and India continue to mandate lower SAPS (sulphated ash, phosphorus, sulfur) engine oils, accelerating adoption of specialized additives for compliance. This regulatory momentum favors suppliers that can deliver high-performance, low-ash formulations and penalizes those that rely on older additive architectures. At the same time, the industry’s ongoing emphasis on fuel economy, engine durability, and emissions control is aligning additive development priorities with OEM expectations for next-generation powertrains, including turbocharged gasoline direct injection engines and advanced hybrid platforms.
Inside the Report: Operational Content and Decision-Ready Intelligence
Our Worldwide Automotive Engine Oil Additives Market research study is structured to translate market complexity into operational clarity. Rather than presenting data in isolation, the report embeds figures within analytical frameworks that support concrete business decisions. The publication covers historical performance tracking from 2020 through the 2025 base year, providing verified trend lines that contextualize the 2026–2032 forecast period. It then extends forward with demand projections, segmentation mapping, and scenario-aware commentary that help clients test strategic assumptions against plausible market outcomes.
The report systematically examines product-type, vehicle-type, and regional segmentation structures, giving readers a complete view of where demand is concentrated and how it is shifting. Beyond segment sizing, it evaluates the strategic implications of each split, highlighting which categories are most exposed to specification upgrades, which vehicle channels are most sensitive to economic cycles, and which geographies present the strongest mismatch between supply capacity and rising local demand. This layered approach allows clients to move from broad market awareness to targeted portfolio action.
Competitive intelligence forms another central pillar of the study. Company profiles, technology positioning, geographic footprints, and recent activity are synthesized into a comparative landscape that helps clients evaluate partnership opportunities, competitive threats, and benchmarking gaps. Recent developments—including new product launches, exhibition participation, specification updates, and regulatory milestones—are incorporated to ensure that the analysis reflects near-term market momentum rather than stale structural snapshots. For instance, the report captures the ILSAC GF-7 first licensing milestone, the API SQ category introduction, the GF-6/GF-7 overlap extension through October 2026, and key supplier announcements that signal where formulation innovation is heading.
Equally important, the study integrates raw material dynamics, cost pressures, and regulatory timelines into a unified narrative. This ensures that pricing strategy, sourcing decisions, and product roadmap planning are evaluated against the same operational reality. Clients gain a format that supports cross-functional alignment between R&D, procurement, sales, and executive leadership, reducing the friction that often occurs when market data is fragmented across multiple sources.
Strategic Value for 2026 Decision-Making
Portfolio Optimization and Specification Readiness
As ILSAC GF-7 and API SQ gain operational traction, companies must decide how to allocate development resources across viscosity grades, performance tiers, and regional compliance requirements. The report provides the contextual mapping needed to identify which product lines require reformulation urgency, which can be managed through backward-compatible extension strategies, and where transitional overlap periods create timing flexibility. This enables R&D and product management teams to sequence launches with greater confidence and reduce the risk of specification gaps.
Competitive Positioning and Supplier Strategy
Given the high market concentration and the technical sophistication of leading additive suppliers, procurement and strategy teams benefit from a clear view of who controls which technology domains, where regional manufacturers are scaling capacity, and how recent product and exhibition activity signals future competitive moves. Armed with this intelligence, organizations can negotiate from a stronger position, diversify sourcing where appropriate, and align partnership choices with long-term formulation roadmaps rather than short-term price considerations alone.
Cost Management in a Volatile Input Environment
With base oil and additive cost increases persisting into early 2026, margin protection has become a board-level concern. The study’s integrated treatment of cost dynamics, supply chain pressure points, and regional demand resilience supports more disciplined hedging, inventory planning, and formulation efficiency initiatives. Decision-makers can use the report’s frameworks to stress-test pricing strategies, evaluate make-versus-buy considerations, and identify segments where value-added performance can justify premium positioning despite input inflation.
Regional Expansion and Market Entry Planning
For organizations evaluating geographic expansion, the report offers the structural context needed to separate headline opportunity from operationally viable growth. Regional demand profiles, vehicle parc dynamics, regulatory calendars, and competitive density are analyzed together so that market entry, capacity allocation, and distribution partnership decisions are grounded in segment-level realism. This is particularly valuable for companies targeting fast-growing demand centers where local formulation preferences, approval pathways, and pricing norms differ materially from mature Western markets.
Regulatory Foresight and Compliance Alignment
The alignment between additive technology and evolving emissions and performance standards is now a core strategic variable. By mapping the implications of ILSAC GF-7, API SQ, SAPS reduction mandates, and OEM approval requirements, the report helps compliance, technical, and commercial teams synchronize their plans. Organizations that anticipate regulatory shifts early can secure first-mover advantages in specification adoption, reduce reformulation bottlenecks, and position themselves as reliable partners for OEMs and lubricant marketers navigating complex approval processes.
Conclusion: From Market Awareness to Strategic Execution
The Worldwide Automotive Engine Oil Additives Market is entering a phase where growth will increasingly be determined by specification readiness, formulation differentiation, and the ability to manage cost and supply volatility without losing competitive ground. The 3.21 percent CAGR projected through 2032 signals steady expansion, but the real value for 2026 decision-makers lies in understanding where within that growth curve the most defensible opportunities reside. Our full market research study provides the depth, structure, and competitive context required to convert macro trends into actionable strategy. For executives and technical leaders seeking to align product portfolios, sourcing strategies, and regional plans with the realities of a rapidly evolving lubricant ecosystem, this report offers a direct pathway from intelligence to execution. We invite you to access the complete study to explore the full segmentation analysis, detailed company assessments, forecast scenarios, and operational frameworks designed to support high-stakes decisions across the 2026–2032 horizon.
For detailed analysis of this topic, please visit the official page: Worldwide Automotive Engine Oil Additives Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com