

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Polycarbonate Glazing Market Hits $1,832M in 2025, Projected 5.19% CAGR Through 2032

Strategic Horizons: Navigating the Worldwide Polycarbonate Glazing Market Through 2032
The global market for polycarbonate glazing stands at a pivotal inflection point. As industries from automotive to construction demand materials that balance transparency, impact resistance, and sustainability, polycarbonate has cemented its role as a foundational material for modern light transmission and protective applications. Our latest Worldwide Polycarbonate Glazing Market research delivers a comprehensive, data-grounded roadmap for executives, investors, and supply chain strategists who must navigate this evolving landscape with precision.
Set against a five-year historical baseline spanning 2020 to 2025 and a forward-looking forecast window from 2026 through 2032, this study is engineered to inform capital allocation, product roadmap decisions, and competitive positioning in the year ahead and beyond.
The Market Trajectory: Growth, Consolidation, and Strategic Timing
The polycarbonate glazing market has demonstrated resilient expansion over the past half-decade, recovering from mid-cycle adjustments to reach a base-year valuation of 1,832.03 million USD in 2025. Looking forward, the trajectory points to sustained momentum with a compound annual growth rate of 5.19 percent across the forecast horizon. By 2032, the market is projected to approach 2,612.42 million USD, reflecting steady demand pull from high-volume structural and specialized transparency applications.
This growth is not uniform across time or geography. Early forecast years show measured expansion, with the market moving from 1,946.39 million USD in 2026 to 2,066.15 million USD in 2027, before a sharper acceleration toward the decade's end as capacity comes online and end-use adoption broadens. Understanding these inflection points is critical for timing capacity investments, inventory planning, and regional expansion strategies.
Polycarbonate Sheet Market
Concentration patterns further illuminate the competitive reality. The top three players account for 38.4 percent of market revenue, while the top five capture 52.15 percent. This concentrated structure means that scale advantages, feedstock partnerships, and technological differentiation carry outsized weight. For challengers and new entrants, the path to meaningful share lies in targeted application niches, regional specialization, or sustainability credentials that resonate with procurement mandates.
Segment-Level Dynamics: Type, Application, and the Shape of Demand
Polycarbonate glazing demand is shaped by a clear hierarchy of product types and end-use sectors, each with distinct performance requirements and cost sensitivities. Solid polycarbonate leads the type segmentation, reflecting its broad applicability in architectural facades, security glazing, and transportation transparencies where baseline clarity and impact resistance are paramount. Multiwall polycarbonate follows, driven by its insulating properties and growing use in construction and agricultural enclosures. Corrugated polycarbonate rounds out the type mix, serving cost-sensitive and high-durability applications where structural profile matters as much as optical performance.
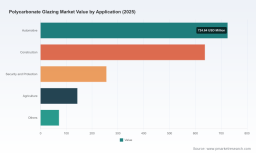
On the application side, automotive remains the dominant demand engine, fueled by lightweighting imperatives, electrification-related redesigns, and the need for high-clarity, UV-stabilized glazing in passenger and commercial vehicles. Construction ranks closely, supported by building energy codes, retrofits, and the substitution of heavier or less durable materials in roofing, skylights, and transparent wall systems. Security and protection applications represent a specialized but high-value segment, while agriculture and other end-use categories provide additional growth nodes where durability and cost efficiency intersect.
Importantly, the interplay between type and application is not static. Buyers increasingly evaluate multiwall versus solid formats through the lens of thermal performance, fabrication complexity, and total installed cost. Procurement teams in construction and transportation are also weighing recycled-content and mass-balance resins as part of broader ESG procurement policies. These cross-cutting considerations make segment-level analysis essential for product managers and sales strategists who must align material grades with purchasing criteria.
Regional Realities: Where Growth Is Concentrated and Why
Regional demand patterns reveal a market where Asia Pacific anchors volume, Europe drives specification-led and regulation-conscious adoption, and North America combines large-scale construction and industrial demand with a mature distribution ecosystem. Latin America and the Middle East and Africa contribute meaningful but smaller shares, often expanding through infrastructure projects, agricultural modernization, and import-dependent supply chains.
These regional profiles are not merely size differences; they reflect divergent procurement behaviors, regulatory environments, and logistics realities. In Europe, compliance with evolving substance restrictions and energy-performance expectations shapes grade selection and supplier qualification. In Asia Pacific, rapid industrial capacity additions and localized fabrication networks influence price dynamics and lead-time expectations. In North America, large project pipelines and a preference for domestically sourced or regionally distributed materials affect fulfillment strategies. Understanding these regional fingerprints allows companies to prioritize go-to-market investments, distribution partnerships, and compliance readiness where they will yield the greatest return.
Competitive Landscape: Incumbents, Specialists, and the Ecosystem of Scale
The competitive field blends global resin and sheet producers with regional formulators and specialized glazing manufacturers. Covestro AG continues to anchor its position through Makrolon-branded polycarbonate resins and sheets tailored for architectural glazing, automotive glazing, and high-impact transparent applications, with an emphasis on UV stabilization and impact resistance. Its January 2025 announcement of a major capacity expansion at its Hebron, Ohio facility signals a deliberate push to serve custom grades across automotive, electronics, and specialty film and glazing demand.
SABIC complements this landscape with LEXAN polycarbonate sheets and resins spanning solid, multiwall, and architectural systems, with a clear focus on durability, clarity, and energy efficiency. The recent integration activity involving POLYVANTIS, including the launch of a new LEXAN sheet series with enhanced lightweight properties and mechanical performance for rail and glazing applications, illustrates how product innovation is being directed at demanding mobility and transparency use cases.
Alongside these global players, a robust set of specialists and regional manufacturers competes on application focus, fabrication capability, and regional service. Palram Industries Ltd. specializes in polycarbonate glazing products including flat solid sheets, multiwall sheets, and corrugated panels for construction, agricultural, and transportation uses. Trinseo supplies polycarbonate resins and sheets with a growing emphasis on sustainable and recycled-content solutions for building and industrial applications. Teijin Limited manufactures high-performance polycarbonate materials, including optical and impact-resistant grades for architectural and specialty applications, while Mitsubishi Gas Chemical Company, Inc. has advanced its sustainability positioning through ISCC PLUS certification for polycarbonate resin at its Kashima plant, using a mass-balance approach for sustainable raw materials applicable to glazing sheet production.
The North American and European markets also feature strong regional contributors. Plaskolite, Inc. offers polycarbonate sheets with emphasis on impact resistance and fabrication for North American construction and industrial markets. EXOLON GROUP, derived from former Covestro European sheet operations, supplies high-quality polycarbonate and thermoplastic sheets targeting construction and industrial sectors. 3A Composites GmbH provides polycarbonate sheets under established brand names for transportation, construction, and renewable energy glazing applications, while Arlaplast focuses on European glazing markets with sustainable processing capabilities. In Asia, LG Chem produces polycarbonate resins suitable for conversion into high-performance glazing sheets for automotive and architectural uses, and LOTTE Chemical CORPORATION supplies polycarbonate materials for sheet extrusion and glazing applications addressing global construction and electronics-related transparency needs.
Finally, Deepak Advanced Materials Limited's March 2025 opening of a new manufacturing facility in Gujarat, India, focused on polycarbonate and engineering polymer compounds for construction and industrial applications including glazing, underscores the expanding manufacturing footprint in the region and the intensifying competition for regional share.
Industry Dynamics: Feedstock Volatility, Regulation, and Trade Realities
Strategic decision-making in this market cannot be separated from the operational and regulatory forces shaping supply and demand. The primary feedstock for polycarbonate, Bisphenol A, experienced mixed price trajectories in Asia Pacific during the second quarter of 2025, with April increases linked to plant maintenance and restocking. These fluctuations ripple through resin pricing, margin planning, and procurement timing, making feedstock visibility a core input for commercial strategy.
Regulatory developments add another layer of complexity. EU regulation banning Bisphenol A and its salts in food contact materials entered into force on 20 January 2025, impacting certain polycarbonate applications while maintaining specific migration limits for non-infant uses. Complementary EU regulations impose stricter Bisphenol A migration limits in food contact plastics effective in 2025, requiring compliance statements for polycarbonate materials. While these restrictions primarily target food-contact applications such as infant feeding bottles and certain containers, they are also driving development of alternative or low-migration grades for broader uses, including non-food glazing, and reshaping supplier qualification processes.
Trade policy introduces further uncertainty. U.S. reciprocal tariffs in 2025, including potential impacts on imports from South Korea, the European Union, and Thailand, affect polycarbonate supply chains with baseline duties applied amid ongoing negotiations. For manufacturers and distributors, these dynamics influence landed-cost calculations, sourcing diversification, and inventory positioning. Companies that map tariff exposure and evaluate alternate supply paths will be better positioned to protect margins and maintain service levels.
Inside the Study: What Decision-Makers Will Find
This market research is built for execution, not just observation. It translates macro trends into an actionable framework covering market sizing and forecast logic, segmentation analysis by type and application, regional demand profiles, and competitive intelligence on the companies shaping pricing, innovation, and capacity. The study details recent developments that matter for near-term planning, including capacity expansions, new facility openings, product launches, and sustainability certifications that signal where supply and differentiation are heading.
Worldwide Polycarbonate Glazing Market
Beyond the numbers, the report connects market structure to commercial implications. It examines how concentration influences pricing power and partnership strategy, how regulatory and feedstock dynamics affect cost structures and qualifying criteria, and how regional demand fingerprints should inform sales coverage and distribution design. The analysis also addresses the practical questions procurement and product teams face: which material grades align with performance and compliance requirements, where multiwall and solid formats create value tradeoffs, and how sustainability credentials are increasingly integrated into purchasing decisions.
The report's structure allows users to move from high-level strategic context to targeted insights without losing rigor. Whether the objective is to evaluate entry opportunities, refine capacity planning, benchmark competitor moves, or build a sourcing and compliance roadmap, the study provides a consistent evidence base and clear analytical pathways.
Why This Research Matters for 2026 Decisions
In a market projected to grow steadily yet unevenly, with concentrated incumbents, evolving regulation, and feedstock and trade volatility, decisions made in 2026 will shape competitive standing through the end of the decade. Companies that align product portfolios with application-led demand, anticipate regional procurement behavior, and prepare for regulatory and cost fluctuations will capture disproportionate value. Those that treat polycarbonate glazing as a commodity category risk missing the specificity that now drives specification, qualification, and repeat purchasing.
This Worldwide Polycarbonate Glazing Market research is designed to reduce ambiguity and accelerate better decisions. It provides the market context, segment logic, competitive mapping, and dynamic intelligence needed to prioritize investments, sharpen go-to-market execution, and build resilience into supply and sourcing strategies.
To access the full dataset, detailed segmentation breakdowns, complete company profiles, regional demand estimates, and the full set of recent developments informing this analysis, visit the source page for the complete report. The comprehensive intelligence is available to support strategic planning, investment review, and operational decision-making across the 2026 to 2032 horizon.
For detailed analysis of this topic, please visit the official page: Worldwide Polycarbonate Glazing Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com