

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global Indoor Lighting Control Market to Hit $25.67B by 2032 at 8.52% CAGR

Illuminating the Future: Strategic Imperatives in the Global Indoor Lighting Control Systems Market
Executive Perspective
The transition from conventional illumination to intelligent, connected indoor lighting control systems represents one of the most tangible yet complex operational shifts in modern facility management. As organizations across commercial, industrial, and residential sectors confront rising energy costs, stringent sustainability mandates, and the operational demands of hybrid work environments, the strategic deployment of lighting controls has evolved from a peripheral efficiency upgrade into a core infrastructure investment. This analysis introduces our latest comprehensive study, Worldwide Indoor Lighting Control Systems Market, and outlines why its findings carry direct decision-making value for executive teams, procurement leaders, and technology strategists navigating the 2026 landscape.
Market Trajectory and Macro-Scale Context
Over the past half-decade, the indoor lighting control sector has demonstrated consistent annual expansion, reflecting a structural acceleration rather than a cyclical upturn. The global market, valued at approximately 8,900 million USD in 2020, has steadily climbed through a 2025 base year valuation near 14,500 million USD. The trajectory through the 2026-2032 forecast window projects sustained growth, with total market size expected to reach roughly 25,667 million USD by the close of the decade. This expansion is underpinned by a compound annual growth rate of 8.52 percent, indicating durable demand across geographies and deployment types. Several structural forces explain this momentum. First, the rapid overhaul of commercial interiors to support flexible occupancy patterns has made networked lighting controls a prerequisite for both energy optimization and occupant experience. Second, regulatory frameworks in major industrial economies have shifted lighting controls from optional best practices toward default compliance requirements. Third, the convergence of lighting infrastructure with broader building management ecosystems has expanded the addressable scope of control platforms, transforming them from isolated switching mechanisms into data-generating nodes within integrated smart building architectures. Importantly, the market's growth profile does not suggest a homogeneous environment. Deployment preferences, technology adoption curves, and regional regulatory pacing create distinct prioritization matrices for stakeholders. Our research isolates these vectors without relying on top-line generalizations, enabling readers to map investment and product roadmaps against actionable market realities rather than aggregate industry narratives.
What the Study Delivers: Operational Intelligence for 2026 Decision-Making
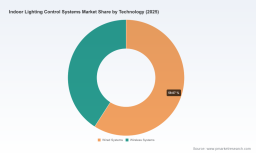
The Worldwide Indoor Lighting Control Systems Market report is designed as a working reference rather than a high-level market overview. It provides structured, forward-looking intelligence that aligns with the planning cycles of hardware manufacturers, system integrators, facility operators, and capital allocators. The study's architecture prioritizes clarity in three operational dimensions: technology evolution, deployment contexts, and competitive positioning. At the technology layer, the analysis examines the ongoing interplay between wired and wireless control architectures. While traditional wired frameworks continue to anchor large-scale retrofits and mission-critical commercial environments due to their established reliability and deterministic performance, wireless and hybrid configurations are capturing disproportionate attention in renovation scenarios, modular commercial spaces, and multi-tenant residential properties. The study tracks how protocol standardization, mesh networking capabilities, and low-latency sensor integration are reshaping the practical trade-offs between installation complexity, scalability, and lifecycle cost. The application dimension extends beyond categorical labels to assess how control requirements diverge across environment types. Commercial facilities increasingly demand centralized management, daylight harvesting, and occupancy-responsive scheduling that can interface with broader operational systems. Industrial settings prioritize robustness, fault tolerance, and energy performance across expansive, high-bay environments. Residential deployments, meanwhile, are shaped by user experience expectations, retrofit feasibility, and the growing integration of lighting controls into home automation ecosystems. By mapping these distinctions against market dynamics, the report equips decision-makers with a clearer sense of where product positioning, service models, and pricing strategies will encounter the most friction or opportunity. The regional dimension provides a framework for evaluating demand maturity, regulatory exposure, and competitive intensity across major geographic markets. Rather than presenting isolated figures, the analysis connects regional trajectories to underlying drivers such as construction activity, renovation pipelines, energy policy enforcement, and local vendor ecosystems. This approach allows organizations to calibrate geographic expansion, supply chain planning, and partnership strategies in alignment with real-world market pacing.
Competitive Landscape: Positioning, Innovation, and Ecosystem Control
The competitive landscape in indoor lighting control systems is characterized by a moderate concentration of established players, interspersed with technology specialists and protocol-driven component suppliers. The combined market share of the top three firms sits at approximately 32.5 percent, while the top five collectively account for around 42.8 percent of total industry revenue. This structure signals a market that is neither dominated by a single platform monopoly nor so fragmented that differentiation becomes meaningless. Instead, competition hinges on technology interoperability, ecosystem integration, brand trust in large-scale commercial deployments, and the ability to move quickly into emerging protocol and sensor-driven use cases. Several leading organizations illustrate how competitive advantage is being constructed in this environment. Signify has advanced its Interact IoT-based control portfolio for commercial buildings, combining sensor intelligence, gateway architecture, and cloud management to support scalable indoor deployments. Lutron Electronics continues to emphasize flexible wired and wireless control lines for office and residential automation, with a strong track record in dimming, sensor integration, and system-level automation platforms. Acuity Brands has expanded its nLight platform presence by strengthening compatibility between wired and wireless controls and networked indoor management tools. Schneider Electric has positioned its EcoStruxure Building IoT approach as a convergence point for lighting control, HVAC, and security systems within smart building frameworks, emphasizing operational integration over standalone lighting performance. Legrand contributes through residential and commercial control solutions built around recognized protocols, supporting hotel, multi-family, and indoor commercial applications. ABB's Ability Smart Buildings offering extends the conversation further into energy-efficient indoor management with DALI and KNX integration. Meanwhile, component and control specialists such as ams-OSRAM, Tridonic, and Helvar focus on enabling technologies—smart control modules, DALI-2 and wireless-compatible drivers, and sensor-integrated DALI-based systems—allowing broader system designers to assemble interoperable indoor installations at scale. Additional players including Eaton, Delta Electronics, and Hubbell Lighting reinforce the market's breadth, each contributing distinct control architectures, wireless nodes, and commercial/industrial LED-focused solutions. Recent product and certification activity reinforces the strategic importance of interoperability and intelligent sensing. Signify showcased an updated Interact Office offering with AI-based occupancy sensing for commercial spaces. Lutron introduced a node-based wireless control line targeting indoor commercial environments. Acuity Brands achieved DALI-2 certification for its wireless sensors and controls, while Tridonic expanded thread-compatible wireless control support for indoor mesh networking. These developments are not isolated product announcements; they reflect a broader market transition toward standardized communication, plug-and-play compatibility, and occupancy-aware automation. Organizations evaluating vendor relationships, partnership structures, or internal R&D priorities should treat these shifts as early indicators of where cycle times, integration burdens, and end-user expectations are heading.
Industry Dynamics: Standards, Policy, and Cost Realities
The indoor lighting control market is shaped as much by external conditions as by technological innovation. Regulatory and standardization developments have increasingly functioned as market accelerators by reducing ambiguity around performance expectations and interoperability requirements. The EU Ecodesign Directive establishes performance expectations for lighting controls in non-residential buildings, reinforcing the financial and compliance case for control deployment. In parallel, the DALI-2 standard has become a critical reference point for indoor lighting control interoperability, introducing improved error handling and predictable device communication across multi-vendor environments. The KNX protocol continues to provide a widely certified foundation for multi-vendor indoor compatibility, supporting product breadth across thousands of certified implementations. At the regional level, policy frameworks such as the US Energy Policy Act have codified automatic shutoff control expectations for large buildings, embedding lighting controls into baseline operational compliance. Cost dynamics also play a central role in procurement and deployment decisions. Sensor hardware, particularly occupancy-sensing components used in commercial installations, has settled into a recognizable cost band that strongly influences total system economics during retrofits and new construction. While sensor pricing alone does not determine project viability, it interacts with labor intensity, commissioning complexity, and long-term energy savings to shape the adoption curve for different control architectures. The report uses these operational realities to help readers assess where system-level savings are most achievable and where installation friction may offset anticipated efficiency gains.
Why the 2026 Outlook Matters Now
The 2026-2032 forecast window is particularly consequential because it captures the intersection of several simultaneous transitions. Markets are moving beyond early adoption arguments and toward scale execution. Building operators are asking not whether to install controls, but how to standardize across portfolios, manage vendor diversity, and integrate lighting data into broader energy and space-utilization strategies. Technology providers, meanwhile, must navigate protocol evolution, sensor intelligence, cloud-based management, and the commercial realities of wired-versus-wireless deployment trade-offs. For executives, the strategic question is no longer centered on overall market size alone. The more valuable inquiries concern growth composition, competitive pressure points, technology substitution risk, and regional readiness. Where are wireless and hybrid models accelerating fastest? Which application segments are most exposed to standard-driven adoption? How are leading vendors differentiating around integration, service, and protocol support? And how should organizations interpret the balance between established incumbents and specialists competing in niche architectural or protocol-driven segments? The report provides the analytical scaffolding to answer these questions with greater confidence. By examining market structure, competitive moves, regulatory tailwinds, and deployment considerations together, it supports more disciplined planning for product strategy, procurement timing, partnership development, and market entry or expansion decisions.
Conclusion: Turning Market Intelligence into Actionable Advantage
Indoor lighting control systems have matured into an essential infrastructure category that sits at the crossroads of energy management, occupant experience, and smart building integration. The growth trajectory through 2032 reflects sustained structural demand, but the strategic opportunities within that trajectory are uneven and highly dependent on technology readiness, regulatory context, and application-specific requirements. Our Worldwide Indoor Lighting Control Systems Market study is designed to give organizations the depth they need to act, not just the summary they need to brief. It translates broad market momentum into operational insight, helping leadership teams evaluate where to invest, where to standardize, and where to differentiate. For readers seeking a fuller examination of segmentation behavior, vendor positioning, protocol adoption, regional pacing, and forward-looking scenario analysis, the complete report provides the comprehensive intelligence required to align strategy with the realities of the 2026 market.
Worldwide Indoor Lighting Control Systems Market
Worldwide Emergency Lighting Controller Market
For detailed analysis of this topic, please visit the official page: Worldwide Indoor Lighting Control Systems Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com