

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global TPS Cable Market Hits $52.2B in 2025, 6.29% CAGR to 2032

Strategic Intelligence for the 2026 Market Landscape: Inside the Worldwide Thermoplastic-Sheathed Cable Market
The worldwide thermoplastic-sheathed cable market stands at a critical juncture as enterprises navigate a decade defined by infrastructure modernization, energy transition mandates, and shifting supply chain architectures. Our latest Worldwide Thermoplastic-sheathed Cable Market study delivers a comprehensive strategic foundation for decision-makers operating across manufacturing, procurement, and capital allocation functions. Designed for immediate deployment in 2026 planning cycles, this research translates multi-year trajectory data, regulatory inflection points, and competitive maneuvers into actionable intelligence. Below, we outline the analytical architecture, contextual drivers, and competitive mapping that position this report as an essential reference for enterprise strategy.
Market Trajectory and Structural Shifts
Over the historical observation window from 2020 through 2025, the sector demonstrated consistent expansion, moving from approximately 38,450 million USD to a baseline of 52,150 million USD by the close of the reference period. This progression reflects sustained deployment across power distribution, building wiring, and industrial control environments, underpinned by steady urbanization and grid modernization programs.
The forward-looking horizon from 2026 through 2032 outlines a continued upward path, advancing toward a projected 79,981 million USD by the terminal forecast year. The compound annual growth rate of 6.29 percent signals a mature but resilient demand environment, where volume expansion is increasingly coupled with specification upgrades, compliance-driven material substitutions, and regional sourcing realignments. For executives mapping capacity investments, inventory strategies, or market entry plans, this trajectory provides a calibrated baseline against which internal forecasts and scenario models can be stress-tested.
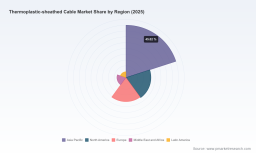
Importantly, the market structure reveals meaningful differentiation across product architectures, application channels, and geographic corridors. Flat configurations continue to command substantial share within mainstream wiring deployments, while circular and multi-core variants maintain specialized relevance in power routing, instrumentation, and complex harness assemblies. On the application side, residential construction and commercial building projects represent the dominant consumption corridors, with industrial infrastructure providing a steady, specification-sensitive demand layer that rewards manufacturers capable of delivering compliance-ready, durable solutions. Regionally, Asia Pacific anchors the largest consumption base, followed by North America and Europe, while Middle East and Africa and Latin America present growth corridors shaped by infrastructure spending cycles and import-dependency dynamics. These structural patterns are examined in depth within the full report, where segmentation interplay, demand elasticity, and regional procurement behaviors are mapped without the simplifications typically found in high-level summaries.
Regulatory Forces and Supply Chain Reconfiguration
The competitive and operational environment for thermoplastic-sheathed cables is being reshaped by overlapping regulatory, material, and trade dynamics. International standards such as IEC 60227-5 govern thermoplastic-insulated cables rated up to 450/750V, and the 2024 amendments that enhanced flame retardancy requirements have elevated the compliance burden for manufacturers serving building and infrastructure end markets. In parallel, the AS/NZS 5000.2:2022 specification continues to define performance expectations for thermoplastic-sheathed cables used in Australian electrical installations, reinforcing the importance of region-specific certification strategies for suppliers targeting Oceania and export-aligned markets.
These technical standards intersect with broader policy momentum. The global push for energy-efficient buildings under frameworks such as the EU Green Deal is accelerating demand for low-smoke zero-halogen thermoplastic cables, creating an estimated uplift of 5 to 7 percent annually in relevant demand segments. This shift rewards manufacturers that can align product portfolios with stricter emission, fire-safety, and sustainability expectations while maintaining cost competitiveness.
Material economics further complicate planning. PVC resin prices, which are central to thermoplastic sheathing production, averaged 1,200 USD per metric ton in the fourth quarter of 2025 amid relatively stable supply from Asia. While this provided near-term cost visibility, commodity volatility, logistics constraints, and regional availability differences continue to require active procurement hedging and supplier diversification. At the same time, trade policy has introduced meaningful sourcing realignment. US tariffs on Chinese thermoplastic cables increased to 25 percent under Section 301 in 2025, prompting buyers and distributors to shift sourcing toward Mexico and Vietnam. For manufacturers and channel partners, these developments are not merely cost variables; they are strategic determinants of plant location, inventory positioning, contract structure, and long-term market access.
Worldwide Thermoplastic-sheathed Cable Market
Competitive Architecture and Recent Industry Moves
The market remains moderately fragmented, with the top three firms accounting for approximately 18.45 percent of revenue and the top five reaching roughly 24.8 percent. This concentration profile suggests that while scale players hold meaningful influence, there is substantial room for specialized differentiation, regional execution strength, and specification-driven wins. The competitive field includes globally integrated manufacturers and sector-focused specialists, each pursuing distinct routes to advantage through product engineering, certification breadth, distribution reach, and project-level pipeline development.
Prysmian Group, headquartered in Milan, Italy, operates as a leading global manufacturer of thermoplastic-sheathed cables, including TPS power cables for residential, commercial, and industrial applications compliant with AS/NZS 5000.2 standards. Its recent showcase of new thermoplastic-sheathed low voltage cables for renewable energy at the Wire 2025 exhibition signals continued alignment with electrification and clean-energy infrastructure demand.
Nexans, based in Paris, France, produces thermoplastic insulated and sheathed cables such as NYY and similar TPS types for power distribution, mining, and construction worldwide. Its September 2025 launch of enhanced thermoplastic-sheathed cables with improved fire resistance for building applications underscores a product strategy centered on compliance and safety performance in construction end markets.
Southwire Company, located in Carrollton, USA, is a major US producer of thermoplastic-sheathed cables including THHN/THWN with PVC/thermoplastic sheathing for electrical installations. The June 2025 UL certification update for new thermoplastic-sheathed SIMpull cables reflects an ongoing emphasis on specification approval, channel readiness, and installer-friendly product design in the North American market.
LS Cable & System, headquartered in Seoul, South Korea, supplies thermoplastic-sheathed power and control cables for global energy and infrastructure projects. Its April 2025 contract award for an Australian data center project illustrates how infrastructure-linked demand and international project pipelines can create targeted growth opportunities for capable exporters.
In Japan, Sumitomo Electric Industries manufactures thermoplastic-insulated and sheathed cables for automotive, power, and industrial uses, while Furukawa Electric produces PVC/thermoplastic sheathed cables for power transmission and distribution. Both firms leverage strong engineering heritage and broad application coverage to sustain position across demanding performance environments.
NKT A/S, based in Brøndby, Denmark, offers thermoplastic-sheathed medium and low voltage cables for offshore and onshore applications, aligning its portfolio with energy-sector and harsh-environment requirements. Leoni AG, headquartered in Nuremberg, Germany, specializes in thermoplastic-sheathed cables for automotive and industrial sectors, differentiating through application-specific engineering and mission-critical reliability expectations.
In the Americas and Europe, Belden Inc., based in St. Louis, USA, provides thermoplastic-sheathed data, control, and power cables for harsh environments, while the Lapp Group, headquartered in Stuttgart, Germany, serves as a global supplier of ÖLFLEX thermoplastic-sheathed cables for machinery and automation. These players reinforce the importance of specialization, brand equity in industrial and connectivity segments, and the ability to support complex specification processes.
The competitive picture is not static. Recent launches, certification updates, trade-show positioning, and project awards indicate that leading participants are actively reshaping portfolios around fire performance, renewable-energy compatibility, installer efficiency, and project-scale supply reliability. For companies evaluating partnership, sourcing, or competitive response strategies, tracking these moves in the context of regional compliance requirements and procurement shifts is essential.
Research Architecture and Practical Utility
This study is structured to support both strategic planning and operational decision-making. Beyond aggregate market sizing and forward projections, the report examines the interplay between product types, application verticals, and regional demand patterns, enabling readers to identify where volume concentration, specification premiums, and growth accelerations are most likely to emerge. The segmentation analysis is designed to clarify not only where demand currently resides, but also how structural factors such as building codes, infrastructure spending, and procurement geography influence consumption behavior over the forecast period.
The competitive assessment extends beyond simple vendor listing. It maps corporate positioning, geographic coverage, application focus, and recent strategic developments to help stakeholders interpret who is gaining traction, where certification and product launches may alter specification outcomes, and how supply chain realignments could influence procurement choices. By embedding recent industry events within the broader market context, the report helps readers distinguish transient announcements from durable shifts in competitive dynamics.
Operational planners will also find value in the integration of material, regulatory, and trade considerations. The analysis addresses how PVC resin pricing dynamics, flame-retardancy amendments, low-smoke zero-halogen demand pull, and tariff-driven sourcing migration interact to shape cost structures, product design choices, and channel strategy. This multidisciplinary framing is intended to reduce the gap between market intelligence and executable plans, whether those plans involve capacity allocation, product roadmap decisions, distributor expansion, or risk-managed sourcing.
Implications for 2026 Decision-Making
As enterprises move into 2026 planning, the thermoplastic-sheathed cable market offers a case study in how mature demand growth, regulatory tightening, and trade reconfiguration can combine to create both risk and opportunity. The projected trajectory toward the 2032 horizon suggests that scale alone will not determine success; rather, competitive advantage will increasingly depend on compliance agility, specification alignment, regional sourcing competence, and the ability to respond to evolving building and infrastructure standards.
Thermoplastic Composites Market
For manufacturers, the imperative is to reconcile product development with the dual demands of performance upgrading and cost discipline, particularly as flame retardancy, low-smoke characteristics, and installer efficiency become more decisive in specification wins. For distributors and procurement teams, the challenge is to balance cost stability against geopolitical and tariff-related sourcing shifts, while maintaining access to certified, regionally appropriate product assortments. For investors and strategy teams, the opportunity lies in identifying where demand concentration, project pipeline momentum, and competitive positioning converge to support durable margin profiles and market-share gains.
The full Worldwide Thermoplastic-sheathed Cable Market report expands each of these dimensions with detailed segmentation interpretation, regional demand narratives, competitive benchmarking, and forward scenario context. It is designed to serve as a working reference for teams that need more than headline figures: teams that require a coherent, evidence-based view of how the market is structured, how it is changing, and where strategic leverage can be created in 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Worldwide Thermoplastic-sheathed Cable Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com