

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting:绿脓杆菌治疗市场2025年达19.42亿美元,预计2032年将增长至28.26亿美元

Strategic Intelligence for the Pseudomonas Aeruginosa Infection Treatment Market: Navigating a $2.8 Billion Horizon (2026-2032)
The global landscape for treating Pseudomonas aeruginosa infections is undergoing a profound transformation, driven by the relentless pressure of antimicrobial resistance, evolving regulatory frameworks, and a shifting clinical consensus on the management of difficult-to-treat Gram-negative pathogens. Plasmid-mediated resistance mechanisms, carbapenem-sparing strategies, and the emergence of novel beta-lactam/beta-lactamase inhibitor combinations have collectively redefined the therapeutic armamentarium available to hospitalists, infectious disease specialists, and critical care teams. Against this backdrop, PW Consulting is proud to present our comprehensive Worldwide Pseudomonas Aeruginosa Infection Treatment Market research, a strategic intelligence asset designed to equip pharmaceutical executives, investors, and healthcare strategists with the precise, forward-looking insights necessary to make confident decisions in 2026 and beyond.
This report does not merely catalog historical revenue streams. It constructs a multidimensional view of where the market stands at its 2025 baseline of approximately 1,942.4 million USD, how it reached that threshold through a disciplined progression from 1,484.2 million USD in 2020, and how it is projected to breach the 2,000 million USD mark in 2026 before charting a sustained upward arc through 2032. Executives operating in the antibiotic and anti-infective space require more than top-line figures. They need to understand which therapeutic classes are consolidating market share, which clinical indications are absorbing the heaviest treatment volumes, how reimbursement philosophies are recalibrating across major healthcare systems, and which competitive moves will define the next wave of portfolio optimization. Our analysis is built to answer those questions with surgical precision while preserving the confidentiality of the granular data that drives our forecasting engine.
A Data-Rich Foundation for Executive Decision-Making
Any credible market evaluation begins with a disciplined historical lens. Over the 2020 to 2025 assessment window, the global Pseudomonas Aeruginosa Infection Treatment Market expanded from 1,484.2 million USD to 1,942.4 million USD, reflecting a compounding trajectory shaped by rising hospital-acquired infection rates, increased adoption of newer antipseudomonal agents in stewardship-aligned protocols, and persistent demand across both branded and generic channels. The forward-looking narrative extends through 2032, with the market projected to reach approximately 2,825.5 million USD by the close of the forecast horizon. This pathway implies a compound annual growth rate of 5.51 percent, a figure that captures both organic volume expansion and the continuous rotation toward higher-value combination therapies that address resistant phenotypes.
Rather than treating this growth as a monolithic trend, our research decomposes the market into clinically and commercially meaningful dimensions. We analyze how different drug classes are navigating shifting susceptibility patterns, how regional healthcare infrastructures are modulating access and adoption, and how specific infection sites are driving differentiated prescribing behaviors. The report deliberately preserves these structural splits within our proprietary analytical framework, requiring stakeholders to engage directly with the complete dataset to fully map the terrain. This approach ensures that the intelligence you receive is not diluted into generic commentary but delivered as an actionable, decision-grade resource.
What This Report Delivers: Operational Depth for Strategic Planning
The Worldwide Pseudomonas Aeruginosa Infection Treatment Market research is structured to function as a working document for strategy, business development, and competitive intelligence teams. Every section has been engineered to translate epidemiological and pharmacological complexity into commercial clarity. The following components form the backbone of the analysis:
- Macro-market sizing and historical reconstruction spanning 2020 to 2025, with full-year revenue trajectories that anchor the 2025 baseline and set the stage for the 2026 to 2032 forecast window.
- A segmented evaluation of therapeutic classes, mapping the relative commercial weight of each category while highlighting the interplay between legacy antipseudomonal agents and next-generation beta-lactam/beta-lactamase inhibitor platforms.
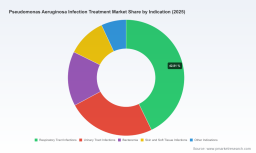
- An indication-level breakdown that examines how respiratory tract infections, urinary tract infections, bacteremia, skin and soft tissue infections, and other clinical scenarios contribute to overall treatment demand and prescribing conventions.
- A regional analysis that contextualizes market dynamics across North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa, incorporating differences in formulary access, reimbursement structures, and local resistance epidemiology.
- Detailed company profiles that map the operational footprint, pipeline positioning, and recent strategic developments of the leading players shaping the competitive battlefield.
- A forward-looking competitive landscape assessment that integrates market concentration metrics, portfolio overlap analysis, and the strategic implications of recent regulatory and clinical milestones.
Throughout these sections, we maintain a disciplined separation between illustrative market architecture and the core quantitative splits that power our projections. Readers seeking the exact revenue contributions of each therapeutic category, each indication, and each geographic zone will find those figures embedded within the complete research instrument, accessible through our full report portal.
Competitive Landscape: Navigating a Concentrated but Dynamic Field
The Pseudomonas Aeruginosa Infection Treatment Market operates within a highly active competitive environment where a relatively concentrated set of large-cap pharmaceutical organizations coexist alongside specialized anti-infective developers and global generic manufacturers. Our concentration analysis indicates that the top three participants collectively command a meaningful share of total market revenue, while the top five extend their footprint to a dominant aggregate position. This structural reality does not imply a static hierarchy. Instead, it reflects a landscape in which established beta-lactam platforms, combination inhibitor strategies, siderophore cephalosporins, and a steady stream of generic entrants are continuously redefining share dynamics through clinical differentiation, regulatory approvals, and stewardship-aligned positioning.
Several anchor organizations define the strategic contours of this market. Pfizer Inc. maintains a deep-rooted presence in hospital and critical care settings through its antipseudomonal antibiotic portfolio, including its longstanding piperacillin-tazobactam platform, reinforcing its relevance in severe infection management. Merck & Co., Inc. has strengthened its positioning through imipenem-cilastatin-relebactam for complicated urinary tract infections, intra-abdominal infections, and hospital-acquired or ventilator-associated bacterial pneumonia, broadening its appeal in resistant Gram-negative contexts. AbbVie Inc., through its Allergan affiliation, continues to expand its ceftazidime-avibactam footprint while extending its reach with the recent approval of aztreonam-avibactam, an asset designed to address scenarios where treatment options are constrained by multidrug resistance.
Shionogi & Co., Ltd. has emerged as a distinctive force with cefiderocol, a siderophore cephalosporin engineered to target carbapenem-resistant and otherwise difficult-to-treat Pseudomonas aeruginosa. The company has advanced this platform through robust real-world evidence generation, including clinical presentations that underscore the role of cefiderocol in serious infection settings where Pseudomonas aeruginosa represents a substantial proportion of monomicrobial cases. Across 2025 and 2026, Shionogi's data disclosures have reinforced clinical cure rates and in vitro activity profiles that support the agent's positioning in complicated Gram-negative disease management. Teva Pharmaceutical Industries Ltd. and Lupin Pharmaceuticals continue to anchor the generic tier by supplying widely utilized antipseudomonal agents across multiple classes, sustaining access while exerting price and availability pressure on established product lines. AstraZeneca remains active with ceftazidime and broader anti-infective initiatives relevant to Gram-negative resistance, while Bristol Myers Squibb, Johnson & Johnson through Janssen, Novartis AG, Sanofi, and Baxter International Inc. each contribute distinct capabilities ranging from supportive injectable therapies to stewardship-focused programs and established antibiotic portfolios.
The strategic significance of this competitive architecture lies not in static market shares, but in the sequencing of innovation, the pace of generic infiltration, and the extent to which newer combination therapies align with guideline-driven prescribing. Our report unpacks these dynamics in detail, but the core percentage contributions and exact revenue alignments that determine relative competitive weight are reserved for clients accessing the full dataset.
The Regulatory and Clinical Context Shaping 2026 Strategy
No market assessment of this kind can be separated from the regulatory and clinical environment in which treatment decisions are made. Between January and February 2025, the U.S. Food and Drug Administration reinforced its recognition of standardized susceptibility testing frameworks for several antipseudomonal agents, including amikacin, cefepime, and ceftazidime, while reevaluating its position on polymyxin breakpoints in light of limited pharmacokinetic and clinical outcome data. These actions matter because they influence how laboratories report susceptibility, how clinicians interpret MIC values, and how manufacturers position their compounds within diagnostic and therapeutic workflows.
Simultaneously, clinical guidance continues to shape demand patterns. The 2024 IDSA antimicrobial resistance guidance, which remains active through 2025 and 2026, recommends a preferential approach to newer beta-lactam/beta-lactamase inhibitors for difficult-to-treat resistant Pseudomonas aeruginosa. This guidance elevates the strategic relevance of agents such as ceftolozane-tazobactam, ceftazidime-avibactam, imipenem-relebactam, and cefiderocol in treatment algorithms where resistance narrows the therapeutic window. At the same time, the European Commission's earlier authorization of aztreonam-avibactam for infections with limited treatment options illustrates how regulatory pathways in major markets are opening doors for combination therapies designed to address resistant Gram-negative organisms, including Pseudomonas contexts.
On the supply and manufacturing side, antibiotic production for beta-lactams and aminoglycosides continues to rely on globally distributed active pharmaceutical ingredient networks. Generic producers play an essential role in maintaining availability, but they also influence margin structures, tender dynamics, and the speed at which new branded entrants can capture share in hospital formularies. These are precisely the kinds of interdependencies that our report maps in depth, while withholding the specific quantitative allocations that would allow competitors to reverse-engineer our forecasting assumptions.
Why This Research Is Critical for 2026 Decision-Making
As pharmaceutical companies, investors, and healthcare strategists plan their next moves, three structural questions dominate the agenda. First, how will the balance between branded combination therapies and generic antipseudomonal agents evolve as resistance patterns continue to shift and stewardship programs refine prescribing behavior. Second, where will clinical demand concentrate across infection sites, and which therapeutic categories will be best positioned to capture that demand under evolving guideline recommendations. Third, how should organizations interpret the competitive actions of major players who are simultaneously defending legacy franchises, expanding into newer combination platforms, and integrating real-world evidence to support adoption in high-acuity settings.
Our analysis is built to address these questions directly. The 2026 market projection of approximately 2,033.6 million USD serves as a strategic inflection point, marking the beginning of a forecast period in which growth is expected to be driven by sustained clinical reliance on antipseudomonal therapies, continued uptake of newer agents in resistant infection pathways, and the ongoing interplay between premium combination products and cost-sensitive generic alternatives. The trajectory from 2026 through 2032 is not a straight line; it reflects the influence of regulatory decisions, guideline updates, manufacturing realities, and the pace at which clinicians adopt next-generation options in the face of limited-treatment scenarios.
Worldwide Pseudomonas Aeruginosa Infection Treatment Market
Worldwide Buruli Ulcer Treatment Market
Executives who engage with this research will emerge with a clearer understanding of where value is accumulating, where pressure is intensifying, and how to prioritize engagements across geographies, indications, and drug classes. The market concentration environment, the prominence of major hospital-focused portfolios, and the steady rhythm of regulatory and clinical updates all point toward a landscape that rewards organizations with precise, forward-looking intelligence rather than reactive assumptions.
Access the Full Strategic Blueprint
This article is intended as a gateway, not a substitute for the complete research product. The Worldwide Pseudomonas Aeruginosa Infection Treatment Market study contains the granular segmentation data, regional revenue architectures, therapeutic class splits, indication-level demand distributions, and company-specific strategic assessments required to build defensible plans in 2026 and beyond. Those elements are intentionally held within the full report to preserve analytical integrity and deliver actionable exclusivity to our clients.
For leadership teams that need to align R&D priorities, portfolio strategy, market access planning, and competitive positioning with a rigorously constructed view of this market, the complete research instrument offers the depth and precision that high-stakes decisions demand. The forecast window ahead will be shaped by resistance evolution, stewardship policy, regulatory milestones, and the strategic choices of globally active pharmaceutical organizations. PW Consulting's latest market research provides the structured intelligence necessary to navigate that environment with confidence, discipline, and strategic clarity.
For detailed analysis of this topic, please visit the official page: Worldwide Pseudomonas Aeruginosa Infection Treatment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com