

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Report: Global Education Computing Devices To Hit $57.9B By 2032 With 14.5% CAGR

Strategic Intelligence for the Digital Classroom: Inside the Worldwide Education Computing Devices Market
The global education technology landscape is undergoing a profound transformation. As schools and universities pivot from emergency remote learning to sustained, technology-enabled pedagogical models, the procurement of computing devices has become a cornerstone of institutional strategy. For executives, procurement leaders, and investors, understanding the trajectory of this market is no longer optional. It is a prerequisite for capital allocation, product roadmap planning, and supply chain resilience. Our recently published Worldwide Education Computing Devices Market research study delivers a comprehensive, data-rich blueprint of this evolving sector. This article outlines the strategic value of the report, previews its analytical architecture, and demonstrates how decision-makers can leverage its findings to navigate the 2026–2032 forecast horizon with confidence.
A Market Poised for Sustained Expansion
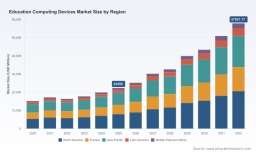
The education computing devices sector has demonstrated remarkable resilience and growth momentum over the past half-decade. Historical revenue data from 2020 through 2025 reveals a sector that recovered swiftly from early-pandemic supply chain disruptions and then accelerated into a phase of structural expansion. In 2020, global market revenue stood at approximately 15.2 billion USD. By 2025, that figure had climbed to 22.45 billion USD, reflecting a compound trajectory driven by renewed institutional budgets, refreshed device fleets, and the normalization of digital-first learning environments.
Looking forward, our forecast model projects that the market will reach roughly 25.25 billion USD in 2026 and continue its upward climb through 2032, when total revenue is expected to surpass 57.9 billion USD. This growth path translates to a forecast-period compound annual growth rate of 14.5 percent. Such a rate places education computing devices among the more dynamic hardware verticals in the broader technology ecosystem. The acceleration is not merely a function of post-pandemic catch-up; it is rooted in durable shifts in curriculum design, administrative digitization, and the integration of artificial intelligence into classroom workflows.
It is important to emphasize that these headline figures represent the aggregated global total. The underlying distribution across geographies, device categories, and end-user segments contains significant variation that can materially impact regional strategy, pricing architecture, and inventory planning. Our full report dissects these layers in granular detail, providing the precision required for localized execution while preserving the macro perspective necessary for board-level strategic planning.
What the Report Delivers: A Framework for Action
A market research publication is only as valuable as its actionable granularity. Our study is engineered to serve as an operational reference rather than a high-level overview. The report is structured around several interlocking analytical modules, each designed to answer specific strategic questions facing education technology stakeholders.
- Historical Reconstruction and Baseline Calibration: We reconstruct revenue performance from 2020 through 2025 across multiple dimensions, establishing a verified baseline that accounts for procurement cycles, policy shifts, and supply-side constraints. This historical lens enables clients to benchmark their own performance against market-wide trends and identify periods of outperformance or underperformance.
- Forward Forecast with Scenario Sensitivity: The 2026–2032 projection framework incorporates multiple growth drivers, including device refresh rates, curriculum modernization mandates, and emerging AI-enabled classroom requirements. The forecast is presented with clear methodological transparency so that readers can test assumptions against their own internal models.
- Device-Type Architecture: The study segments the market across laptops, Chromebooks, tablets, and desktop/hybrid units. Each category is evaluated in terms of adoption momentum, total cost of ownership considerations, and suitability for distinct instructional models. The analysis highlights how procurement preferences are evolving as schools balance performance, manageability, and budget constraints.
- End-User Segmentation: K-12 education and higher education represent distinct buying cultures, funding mechanisms, and deployment scales. Our report maps the demand dynamics within each segment, revealing where volume concentration lies and which institutional profiles are driving incremental growth.
- Competitive Positioning and Mobility Assessment: We profile the major participants shaping the market, examining product strategies, ecosystem leverage, and recent commercial moves. The analysis goes beyond static company descriptions to evaluate how firms are positioning themselves for the next wave of education-focused hardware and software integration.
- Regulatory and Infrastructure Context: Technology procurement does not occur in a vacuum. The report integrates relevant policy developments, connectivity considerations, and infrastructure cost signals that influence device accessibility, total deployment cost, and long-term sustainability for educational institutions.
Competitive Landscape: Who Shapes the Market and How
The education computing devices market is characterized by a concentrated yet dynamic competitive field. Our concentration analysis indicates that the top three firms collectively account for approximately 42.15 percent of total market revenue, while the top five firms represent roughly 64.8 percent. This level of concentration suggests that scale, brand trust, and institutional relationship depth remain powerful differentiators. At the same time, the presence of multiple well-capitalized players competing across overlapping product categories ensures continuous innovation in durability, manageability, and price-to-performance ratios.
Several corporations stand out for their dedicated education-focused portfolios and deployment track records. HP Inc. has built a strong reputation for durable, education-specific Chromebooks and laptops that are widely deployed in K-12 1:1 programs globally. Their education-optimized models emphasize long battery life and centralized manageability, attributes that align closely with the operational realities of large school districts. Dell Technologies Inc. similarly offers Chromebooks and laptops tailored for education, with a pronounced focus on durability, serviceability, and integration for school deployments. Dell's footprint includes substantial institutional contracts, such as its involvement in large-scale public school procurement initiatives.
Lenovo Group Limited supplies education Chromebooks and laptops designed for K-12 durability, affordability, and increasingly AI-enhanced features. Their recent product cadence reflects a deliberate push toward connectivity improvements and classroom-ready form factors. Acer Inc. delivers budget-friendly Chromebooks and education laptops optimized for student use, with long battery life and touchscreen options that appeal to cost-conscious procurement offices. ASUTeK Computer Inc. (ASUS) produces education-focused Chromebooks and Windows laptops that emphasize inclusivity, rugged design for students with special educational needs, and AI features, as evidenced by their recent education portfolio unveilings.
Beyond the traditional hardware manufacturers, platform and ecosystem players exert considerable influence. Apple Inc. provides iPads, MacBooks, and ecosystem tools for education, supported by initiatives that include partnerships for coding and robotics in schools and managed device deployment capabilities. Samsung Electronics Co., Ltd. offers Galaxy Chromebooks, tablets, and interactive displays for classrooms, including premium AMOLED models with AI integration tailored for education. Google LLC, through its ChromeOS and Chromebook ecosystem, provides management tools, AI features, and devices optimized for K-12 education, with a substantial installed base already deployed globally.
Recent commercial activity underscores the pace of evolution. In early 2026, ASUS unveiled an expanded education portfolio at a major industry event, introducing Windows laptops, Chromebook series, detachable models, and AI-enhanced devices focused on durability, accessibility, zero-touch enrollment, and efficient deployment. Around the same period, Lenovo launched new Chromebook series featuring advanced connectivity standards, targeting education durability and performance. Separately, a major municipal procurement initiative announced the distribution of hundreds of thousands of LTE/5G-connected Chromebooks to K-12 public school students across a large network of schools, signaling the continued importance of cellular connectivity in closing digital access gaps. These moves illustrate how product launches, connectivity integration, and large-scale deployment contracts are reshaping the competitive playing field.
Market Dynamics: Policy, Infrastructure, and the Connectivity Imperative
Hardware adoption in education is intimately tied to the policy and infrastructure environment. Several developments in recent months carry direct implications for device procurement strategies and long-term market trajectories.
Worldwide Education Computing Devices Market
First, the regulatory landscape around broadband and internet access continues to evolve. A recent appellate court decision struck down a prior federal net neutrality order, reclassifying broadband as an information service and shifting potential regulatory oversight to state-level bodies or legislative action. For education stakeholders, this development introduces uncertainty around equitable access to digital learning content. However, it also intersects with a broader policy conversation: public interest exceptions to net neutrality rules in various jurisdictions allow zero-rating or prioritized access for educational content to support digital learning initiatives. Institutions and vendors alike must monitor how these exceptions are applied, as they can influence device utility, content delivery costs, and the perceived value of connectivity-enabled hardware.
Second, infrastructure cost dynamics are entering the strategic calculus. Major technology firms have recently committed to covering the costs of new power generation and grid upgrades for data centers to prevent increases in residential electricity prices. While this pledge is primarily directed at data center operations, it signals a broader recognition that the digital infrastructure underpinning cloud-based education tools, device management platforms, and AI features depends on reliable and affordable power. Over time, these infrastructure commitments may help stabilize the operational environment for cloud-reliant education deployments, though regional variability in electricity pricing and grid capacity will remain relevant for large-scale device rollouts.
Third, the connectivity gap remains a persistent strategic concern. The distribution of LTE/5G-connected devices to students in large public school systems reflects a policy-driven effort to ensure that learning can continue regardless of home broadband availability. For vendors and institutional buyers, this trend reinforces the importance of cellular-equipped devices, subscription management models, and partnership structures that bundle hardware with connectivity services. It also highlights the need for procurement frameworks that account for total cost of ownership over multiple years, rather than focusing solely on upfront hardware expenditure.
Strategic Implications for 2026 Decision-Making
The convergence of strong market growth, concentrated competition, and evolving policy and infrastructure conditions creates both opportunity and complexity. Leaders who engage with this market in 2026 must navigate several interrelated strategic questions. How should device portfolios be balanced across categories to match instructional needs and budget realities? Where do regional demand patterns justify localized supply chain or distribution investments? How can procurement teams evaluate competing device and ecosystem offerings without losing sight of long-term manageability and total cost of ownership? And how should organizations position themselves for the integration of AI features, connectivity upgrades, and accessibility requirements into next-generation education hardware?
Our report is designed to equip decision-makers with the evidence base required to answer these questions. By combining macro-level revenue trajectories with category-level insight, competitive profiling, and contextual analysis of regulatory and infrastructure developments, the study provides a multi-layered view of the market. This allows clients to move beyond generic industry narratives and develop strategies that are calibrated to their specific operating context, risk tolerance, and growth ambitions.
Access the Full Intelligence
The Worldwide Education Computing Devices Market research study offers a complete, methodologically rigorous portrait of a sector that is expanding at a compelling pace and being reshaped by technology, policy, and institutional demand. The summary figures and strategic themes outlined here provide a preview of the report's scope and analytical depth, but they are only a starting point. The full study contains detailed segmentation breakdowns, regional demand analysis, category-level revenue trajectories, competitive benchmarking, and forward-looking scenario discussions that are essential for precise planning.
AI Learning Devices for Kids Market
For executives, procurement leaders, investors, and strategy teams seeking to make informed decisions in 2026 and beyond, the complete report delivers the granularity and context needed to translate market intelligence into action. We invite you to access the full study to explore the data, models, and insights that will support your next strategic move in the education computing devices market.
For detailed analysis of this topic, please visit the official page: Worldwide Education Computing Devices Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com