

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Category: market research
PW Consulting: 2025 Insulinoma Market Hits $166.8M, Projected 5.75% CAGR Through 2032
By pmarketresearch, 2026-09-16
Navigating the Global Insulinoma Market: Strategic Imperatives for 2026 and Beyond
Market Trajectory and Core Structural Shifts
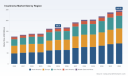
The global insulinoma landscape is entering a decisive phase of structural recalibration, driven by converging forces in clinical innovation, regulatory alignment, and shifting treatment paradigms. Over the historical window of 2020 through 2025, the worldwide insulinoma market expanded from approximately 126.12 million USD to 166.8 million USD, reflecting a compound trajectory shaped by growing diagnostic precision, refined surgical protocols, and incremental pharmacological adoption. Looking ahead to the forecast period spanning 2026 through 2032, the market is projected to continue its measured expansion, anchored by a compound annual growth rate of 5.75 percent and culminating in a total valuation of roughly 246.68 million USD by 2032. These macro-level indicators frame a sector that is simultaneously niche and clinically critical, offering strategic decision-makers a clear window into capital allocation, pipeline prioritization, and go-to-market execution during a period of accelerating therapeutic innovation.
The quantitative progression from 134.11 million USD in 2021 to 162.18 million USD in 2024 underscores an inflection point where clinical research activity, specialized care infrastructure, and targeted investment began converging at practical levels. That momentum carried forward into 2025 and is expected to sustain through 2026, with the market settling around 168.35 million USD before accelerating into the 191.62 million USD range by 2027. For healthcare strategists, pharmaceutical planners, and medical technology executives, this pattern is not merely a financial artifact. It represents a structural narrative: insulinoma management is transitioning from a predominantly surgical and symptomatic intervention model toward an ecosystem where biologic therapies, precision diagnostics, and specialized care pathways increasingly intersect.
Segmentation Dynamics and Operational Realities
Behind the aggregate market figures lies a highly stratified operational environment that demands rigorous segmentation awareness for any enterprise operating within endocrinology, oncology support, or advanced medical devices. The worldwide insulinoma market is organized across multiple interdependent dimensions, each carrying distinct commercial implications, adoption velocities, and operational constraints. Treatment type architectures continue to reflect established clinical hierarchies while simultaneously absorbing emerging modalities, and end-user configurations reveal how care delivery is being reorganized around specialized centers, hospital networks, and diagnostic and research institutions. Regional distributions similarly illustrate how infrastructure maturity, reimbursement frameworks, and clinical trial accessibility influence market penetration patterns.
What makes this segmentation landscape particularly consequential for strategic planning is the uneven pace of innovation across categories. Surgical procedures remain the foundational intervention for localized disease, but the growing recognition of refractory and metastatic subtypes is reshaping how clinicians, investors, and manufacturers position complementary modalities. Pharmacological management, peptide-based approaches, and targeted biologic candidates are steadily expanding the therapeutic arsenal, particularly for patients who cannot undergo resection or who experience persistent hypoglycemia despite conventional management. End-user dynamics further reflect a shift toward institutional specialization, where hospitals continue to function as central treatment nodes, specialty clinics manage complex follow-up pathways, and diagnostic and research centers play an increasingly vital role in case identification, trial recruitment, and biomarker validation.
For corporate strategists, the critical insight is that segmentation performance cannot be interpreted in isolation. Market share, pricing architecture, reimbursement positioning, and clinical adoption are tightly coupled, and misjudging any one dimension can compromise product launch sequencing, partnership selection, and regional prioritization. This is why advanced market intelligence must move beyond headline valuations and examine the structural mechanics that govern how demand materializes across care settings, how value is distributed among treatment modalities, and how regional ecosystems influence time-to-adoption for novel interventions.
Competitive Landscape and the Emerging Therapeutic Frontier
The current competitive environment in the worldwide insulinoma market is characterized by a high degree of clinical concentration, enabling a relatively small cohort of organizations to shape downstream innovation, reimbursement discourse, and physician adoption pathways. Market concentration metrics indicate that a core subset of participants accounts for a disproportionately large share of commercial activity, while broader ecosystem players are increasingly focused on modality-specific innovation, partnership-led development, and precision medicine positioning. This concentration has important strategic implications. It means that competitive intelligence must account not only for revenue footprint but also for intellectual property cadence, clinical trial design, regulatory engagement, and the ability to align with unmet clinical needs in refractory disease populations.
Rezolute, Inc., headquartered in Redwood City, California, exemplifies the type of focused biopharmaceutical entrant that is actively reshaping therapeutic expectations within the rare endocrine oncology space. The company is advancing ersodetug (RZ358), an anti-insulin monoclonal antibody designed for tumor-mediated hyperinsulinism, including malignant insulinoma and refractory hypoglycemia. Its development trajectory has become a central reference point for stakeholders evaluating how biologic interventions might complement or extend beyond current surgical and pharmacological standards.
Recent regulatory developments have elevated the strategic significance of this pipeline. In September 2025, the company announced FDA alignment on a streamlined single-arm, open-label Phase 3 upLIFT trial design for ersodetug in approximately 16 patients with tumor hyperinsulinism. Topline data are expected in the second half of 2026, positioning the trial timeline directly within the early window of this forecast period and making it a closely watched catalyst for both clinical practice and commercial planning. Importantly, regulatory alignment also confirms that positive results from the pivotal sunRIZE Phase 3 trial in congenital hyperinsulinism can serve as supportive or confirmatory evidence for the tumor hyperinsulinism indication. This cross-indication evidentiary strategy could materially influence how development risk, regulatory pathway feasibility, and clinical adoption scenarios are modeled by investors and R&D teams.
From a competitive strategy perspective, these developments illustrate a broader pattern: insulinoma-related innovation is increasingly leveraging rare-disease development efficiency, regulatory consultation, and indication expansion logic. Companies operating in adjacent endocrinology, hypoglycemia management, or oncology-support arenas must therefore monitor not only direct competitors but also clinical trial milestones, regulatory design nuances, and evidence-generation strategies that could redefine treatment standards. The ability to anticipate such shifts is especially valuable in a market where patient populations are limited, clinical adoption depends heavily on specialized expertise, and commercial success is closely tied to reimbursement narratives and physician confidence in novel mechanisms of action.
Epidemiology, Patient Access, and Strategic Positioning
Any credible strategic assessment of the worldwide insulinoma market must account for the epidemiological and clinical constraints that define the addressable opportunity. Insulinomas are estimated to occur at an incidence of roughly one to four cases per million persons per year, with approximately ten to fifteen percent classified as aggressive or metastatic. These figures reinforce the reality that the market is small in absolute patient volume yet highly significant in clinical intensity, economic burden, and therapeutic complexity. The relatively limited incidence means that diagnostic precision, referral pathways, and specialist engagement become decisive factors in both patient outcomes and commercial execution.
The treatment standard similarly shapes strategic assumptions. Surgical resection remains the primary curative option for localized insulinoma, and for inoperable or malignant cases, medical management typically begins with diazoxide as first-line therapy, followed by somatostatin analogs or other interventions for refractory hypoglycemia. Yet a meaningful portion of the patient population does not achieve adequate disease control through existing protocols. Approximately four in ten patients are considered refractory to surgery and medical management including diazoxide, and an estimated 1,500 initially addressable malignant insulinoma patients exist in the United States alone. These numbers are central to planning, because they highlight both the urgency of expanding therapeutic options and the commercial reality that any successful innovation must navigate narrow patient subsets, specialized clinical workflows, and highly scrutinized value propositions.
Strategic positioning in this environment requires disciplined segmentation, realistic forecasting, and an understanding of how clinical evidence translates into adoption. Decision-makers must evaluate how new therapies will integrate into existing care pathways, whether they will reshape referral patterns, and how payers, providers, and research centers will interpret efficacy, safety, and cost-effectiveness. The presence of refractory subpopulations, combined with the rarity of the disease, also means that clinical development strategies and market access plans must be tightly synchronized. Delays, misalignments, or ambiguous evidence packages can materially affect timelines, pricing expectations, and the overall commercial trajectory of an intervention.
Infrastructure, End-User Architecture, and First-Mover Advantages
The delivery of insulinoma-related care is not uniformly distributed across healthcare systems. Instead, it is organized through a layered infrastructure of hospitals, specialty clinics, and diagnostic and research centers, each playing distinct roles in diagnosis, treatment, longitudinal management, and evidence generation. Hospitals continue to anchor procedural capabilities and acute management, while specialty clinics increasingly support complex case coordination and long-term monitoring. Diagnostic and research centers are becoming critical nodes for patient identification, biomarker exploration, trial enrollment, and multidisciplinary consultation.
This end-user architecture matters for strategic planning because it influences how products and services reach the market, how adoption is reinforced, and where commercial value is concentrated. Organizations seeking to enter or expand within this market must determine which care settings offer the most credible pathways to early uptake, which institutional partners can accelerate clinical education, and how reimbursement and procurement dynamics vary across settings. In rare disease markets, the speed and credibility of early clinical endorsement often determine downstream scale. First-mover advantages are therefore not simply about being early; they are about establishing durable relationships with the institutions that define standards of care, support physician decision-making, and validate new therapeutic approaches through real-world use and research activity.
The interplay between clinical concentration, infrastructure distribution, and evidence generation also shapes partnership strategy. Companies may need to align with specialty networks for trial recruitment, collaborate with diagnostic centers for patient identification, or engage hospital-based programs for procedural and translational research. In each case, the objective is to embed commercial initiatives within the operational logic of the care ecosystem rather than treating the market as a uniform endpoint. This approach improves forecasting reliability, reduces adoption friction, and strengthens the credibility of launch planning.
Worldwide Insulinoma Market
Why the 2026 Decision Cycle Demands Precision Intelligence
The 2026 business environment places exceptional pressure on strategic teams to make informed capital, pipeline, and market-entry decisions with limited room for error. In a specialized market like insulinoma, where growth is steady rather than explosive, differentiation depends on understanding structural drivers, anticipating clinical catalysts, and identifying where value is likely to accrue across treatment types, end-user settings, and regional ecosystems. Broad market summaries are insufficient for this task because they do not reveal how demand is distributed, how competitive concentration influences pricing and access, or how regulatory milestones may alter adoption timelines.
This is precisely the type of intelligence gap that our Worldwide Insulinoma Market research is designed to address. The study offers a granular, decision-oriented assessment of the market's historical baseline, forward trajectory, and operational architecture, while deliberately maintaining confidentiality around detailed segment-level figures and proprietary analytics. In practice, this means that executives can rely on the report as a framework for benchmarking assumptions, testing strategic scenarios, and aligning internal planning with market realities, while still being compelled to obtain the complete dataset and analytical models for precise execution.
The strategic value of this approach lies in precision without dilution. For R&D leaders, the report supports assessment of therapeutic positioning, development timelines, and clinical adoption risks. For commercial teams, it informs segmentation planning, channel prioritization, and launch sequencing. For corporate development and investment functions, it clarifies concentration dynamics, competitive exposure, and the likely shape of value creation across the forecast horizon. Rather than offering generic market commentary, the analysis connects epidemiological constraints, treatment standards, regulatory alignment, and infrastructure distribution into a coherent strategic map.
What the Report Delivers and How to Use It
The Worldwide Insulinoma Market report has been structured to function as a working intelligence asset rather than a static overview. It integrates historical performance context, forward-looking market projections, segmentation dynamics, competitive profiles, and industry catalyst tracking into a single decision-support framework. Readers will find detailed coverage of market size evolution from 2020 through the forecast window extending to 2032, alongside analysis of how treatment typologies, end-user configurations, and regional distributions influence commercial behavior and adoption patterns. The report also includes competitive profiling that goes beyond corporate descriptions, examining how developer strategy, trial design, regulatory alignment, and indication expansion shape competitive positioning within a concentrated market.
Importantly, the study emphasizes operational interpretation over raw enumeration. It examines how surgical, pharmacological, targeted, and peptide-based modalities interact within the current care paradigm, how specialized institutions influence early adoption and evidence accumulation, and how rare-disease dynamics shape pricing, reimbursement, and market access logic. This orientation enables users to translate macro-level trends into actionable planning assumptions, such as where to prioritize clinical engagement, how to sequence partnership activity, and which indicators should be monitored to anticipate shifts in competitive intensity or treatment standards.
Because the report is built for strategic application, it also supports scenario planning. Decision-makers can use the analysis to evaluate how changes in regulatory outcomes, trial readouts, or reimbursement environments may affect commercial timelines, market concentration, and relative positioning among incumbents and emerging entrants. In a market where key catalysts are unfolding within the 2026 to 2032 horizon, the ability to model alternative outcomes is a practical necessity rather than an academic exercise.
Conclusion: Strategic Certainty in a Specialized Market
The worldwide insulinoma market is not defined by scale alone, but by the precision with which organizations can interpret clinical need, regulatory evolution, competitive concentration, and infrastructure dynamics. The historical growth observed between 2020 and 2025, combined with the projected trajectory through 2032, confirms that this is a market where disciplined insight can create meaningful strategic advantage. For companies operating in endocrinology, oncology support, medical technology, or specialized care delivery, the ability to read segmentation behavior, anticipate catalyst impacts, and navigate concentrated competitive structures will increasingly differentiate successful strategies from reactive ones.
Our Worldwide Insulinoma Market research is designed to provide that advantage. It offers the analytical rigor, structural clarity, and market-specific intelligence required to make high-stakes decisions with greater confidence, while preserving the detailed quantitative and proprietary elements that underscore its value. For executives who need a complete, decision-ready intelligence foundation, we invite you to access the full report and obtain the comprehensive data, segmentation detail, and competitive analysis necessary to translate strategic vision into executable planning for 2026 and the years ahead.
Lumpectomy Market
For detailed analysis of this topic, please visit the official page: Worldwide Insulinoma Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: NBR Latex Market to Grow at 8.01% CAGR to $4,476M by 2032
By pmarketresearch, 2026-09-16
Navigating the Next Wave: Strategic Outlook for the Global NBR Latex Market (2026-2032)
The global Nitrile Butadiene Rubber (NBR) latex market is entering a decisive phase where demand resilience meets supply chain recalibration. As industries ranging from healthcare to advanced manufacturing continue to depend on nitrile-based solutions for their chemical resistance, durability, and safety profiles, the market has demonstrated a clear upward trajectory. Our latest Worldwide NBR Latex Market study maps this evolution across a base year of 2025 and projects forward through 2032, offering a decision-ready framework for executives, procurement leaders, and investors who must align capacity planning, sourcing strategies, and innovation roadmaps with structural market realities.
The historical record from 2020 through 2025 reveals a market that has absorbed significant volatility while maintaining a strong long-term growth impulse. Total industry revenue, measured in millions of USD, moved from approximately 2,410.5 in 2020 to 2,610.0 in 2025, with annual fluctuations reflecting the interplay of pandemic-era demand spikes, subsequent normalization, feedstock cost dynamics, and shifting end-user procurement patterns. Looking ahead, the forecast window from 2026 to 2032 indicates sustained expansion, with projected revenue climbing toward 2,885.0 in 2026 and reaching roughly 4,476.0 by 2032. This progression corresponds to a compound annual growth rate of 8.01 percent, a figure that underscores both the underlying strength of end-use consumption and the market's capacity to compound value across multiple cycles. For strategic planners, this growth path is not merely a headline statistic. It is a signal that the NBR latex landscape will reward organizations capable of anticipating regional supply shifts, grade-specific demand migration, and the accelerating push toward more sustainable production architectures.
Why This Study Matters for 2026 Decision-Making
Market intelligence is only as valuable as its capacity to reduce uncertainty in real operational contexts. The 2026 planning cycle presents a distinctive set of challenges: feedstock input costs remain sensitive to crude oil fluctuations and geopolitical conditions; regulatory frameworks in key jurisdictions are reshaping formulation priorities; and logistics disruptions have periodically tested the reliability of cross-border supply. In this environment, a robust market assessment must do more than track top-line growth. It must connect macro trends to actionable decisions about capacity allocation, grade portfolio optimization, supplier diversification, and sustainability positioning.
Our analysis is structured to help leadership teams answer the questions that directly affect margin performance and competitive posture. Which application segments are reinforcing steady demand, and where is growth being amplified by regulatory or substitution dynamics? How are grade distinctions between medical-grade and industrial-grade pathways shaping procurement requirements and pricing power? Where are the concentration patterns among leading manufacturers creating both partnership opportunities and supply vulnerability? By integrating historical performance with forward-looking indicators, the report equips stakeholders to stress-test assumptions, prioritize investments, and identify white spaces that align with their operational capabilities.
Scope and Structure of the Analysis
This study is designed as a practical navigation tool rather than a static data table. It brings together market sizing, segmentation logic, competitive profiling, and industry context into a coherent narrative that can be used across functions, from strategy and business development to supply chain and R&D. The analytical framework is organized around the dimensions that most directly influence commercial outcomes.
Segmentation Perspectives
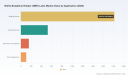
- Regional distribution of market activity and the relative significance of major geographic zones, including Asia Pacific, North America, Europe, Latin America, and the Middle East and Africa
- Application-oriented demand patterns across principal end-use categories such as medical gloves, industrial gloves, adhesives and sealants, and other applications
- Grade-level differentiation between medical-grade and industrial-grade NBR latex, including the implications for specification requirements, compliance, and end-customer expectations
Competitive Landscape and Producer Profiles
The report profiles a broad set of globally active producers and regional specialists whose strategies shape pricing, availability, and product development directions. These include major integrated and specialty players such as LG Chem, Zeon Corporation, ARLANXEO, Kumho Petrochemical, Synthomer, LANXESS, Apcotex Industries Limited, SIBUR, China Petroleum & Chemical Corporation (Sinopec), Nantex Industry Co., Ltd., JSR Corporation, Bangkok Synthetics Co., Ltd., and Nitriflex S.A. Rather than presenting a simple roster, the analysis examines how each organization's geographic footprint, capacity posture, grade focus, and innovation emphasis influences its role within the wider supply network.
Recent Developments Shaping Market Direction
Recent industry activity highlights a clear trend toward diversification of supply and the introduction of more sustainable product options. Synthomer has pursued bio-based NBR latex initiatives, including partnerships aimed at lowering carbon emissions for glove production and the launch of certified sustainable latex lines with reduced carbon footprints. In parallel, capacity expansion efforts continue to reshape regional supply balances, with new plant commissions adding volume in key Asian manufacturing hubs. These moves reflect a broader industry posture in which producers are investing not only in scale, but also in product differentiation and environmental performance.
Market Concentration and Strategic Implications
The competitive structure of the market remains moderately concentrated, with a meaningful share of activity held by leading producers. This concentration matters because it affects negotiating leverage, supply reliability, and the speed at which new grades or process improvements can propagate through the value chain. For buyers, it informs supplier qualification strategies and contingency planning. For manufacturers, it highlights the importance of brand positioning, application-specific technical support, and regional service capabilities as differentiators in a market where scale alone does not guarantee preference.
Industry Dynamics Shaping the 2026-2032 Outlook
No market analysis is complete without attention to the forces that can accelerate, delay, or redirect growth. In the NBR latex sector, several overlapping dynamics are particularly relevant for near-term planning and longer-range scenario building.
Worldwide Nitrile Butadiene Rubber (NBR) Latex Market
Feedstock Cost and Supply Sensitivity
Butadiene and acrylonitrile are core inputs in NBR latex production, and their cost behavior has a direct bearing on manufacturing economics. During 2025 and into 2026, feedstock conditions have been influenced by crude oil-linked pricing and periods of supply tightness tied to broader geopolitical factors. For producers, this translates into cost volatility that must be managed through formulation efficiency, procurement timing, and, where possible, grade mix adjustments. For downstream users, it reinforces the importance of forward contracting, multi-source sourcing, and specification flexibility where performance requirements permit.
Regulatory Pressure and Formulation Evolution
Regulatory expectations continue to shape product development priorities, particularly in Europe, where REACH-related considerations are encouraging demand for lower-VOC and more sustainable NBR latex grades. At the same time, medical and industrial end-users are increasingly attentive to documented compliance, traceability, and environmental attributes. These pressures are not simply constraints; they are becoming selection criteria that can differentiate suppliers with robust technical and sustainability portfolios from those relying solely on price competition.
Logistics, Trade Policy, and Regional Availability
Physical availability remains a critical operational theme. Shipping route disruptions and regional supply concerns have at times affected the reliability of NBR latex deliveries, with repercussions for glove manufacturers and industrial converters dependent on timely input flows. In parallel, trade policy developments, including tariff adjustments affecting certain imports, have introduced additional complexity into cross-border procurement. These factors increase the value of visibility into route-level risk, inventory buffering strategies, and the geographic alignment of supply with demand centers.
Strategic Takeaways for Stakeholders
Taken together, the 2026-2032 outlook points to a market where growth is real but conditional on operational agility. Organizations that can read the intersection of demand structure, feedstock exposure, regulatory direction, and competitive concentration will be best positioned to convert market expansion into durable advantage. Several strategic themes emerge as particularly important.
Nitrile Rubber (NBR) Market
For Producers and Material Suppliers
- Grade specialization and application-specific technical support are likely to become stronger differentiators as buyers seek reliability and performance assurance alongside cost efficiency
- Sustainable and lower-carbon product options are moving from optional innovation to a competitive expectation in selected segments, making portfolio breadth increasingly relevant
- Capacity decisions should be evaluated not only against volume forecasts, but also against regional demand shifts, feedstock access, and logistics resilience
For Convertors, Glove Manufacturers, and Industrial Users
- Supplier qualification strategies should account for concentration risk, geographic exposure, and the ability to maintain continuity during transport or policy disruptions
- Specification management offers an important lever: where performance requirements allow, grade and source flexibility can reduce exposure to cost and availability shocks
- Sustainability attributes and compliance documentation are increasingly part of purchasing decisions, especially in regulated and customer-facing applications
For Investors and Strategic Partners
- Growth visibility is strongest where end-use demand is supported by medical, industrial, and specialty adhesive and sealant consumption patterns, but realization depends on supply-side execution
- Competitive positioning will increasingly favor players that can combine scale with differentiated grades, regional service depth, and credible sustainability narratives
- M&A, partnerships, and capacity collaboration may be especially relevant where feedstock integration, bio-based development, or regional supply balancing can create durable cost or availability advantages
How to Use This Study
This report is intended to support concrete decision-making processes rather than abstract market observation. It can serve as a reference for annual planning cycles, sourcing reviews, capacity expansion evaluations, and competitive benchmarking exercises. By linking historical performance to forward indicators and embedding both producer-level and industry-level context, the study provides a common analytical language for cross-functional teams. The goal is to help decision-makers distinguish between temporary fluctuations and structural shifts, and to prioritize actions that are robust across multiple plausible scenarios.
The global NBR latex market is on a measurable growth path, but the value of that trajectory will be captured by organizations that treat market intelligence as an operational input. With sustained demand across medical and industrial segments, ongoing feedstock and logistics complexity, and a competitive field that rewards both scale and specialization, 2026 represents a pivotal year for setting strategy. Our full Worldwide NBR Late latex Market report extends this foundation with detailed segmentation analysis, comprehensive company profiles, development timelines, and scenario-relevant context, enabling teams to move from insight to execution with greater confidence.
For detailed analysis of this topic, please visit the official page: Worldwide Nitrile Butadiene Rubber (NBR) Latex Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Worldwide Digital Dermatoscope Market Hits $1.16B in 2025, Projects 9.2% CAGR to 2032
By pmarketresearch, 2026-09-16
Unlocking Market Intelligence: Strategic Insights into the Worldwide Digital Dermatoscope Market
The global healthcare technology landscape is undergoing a profound transformation, driven by an aging population, rising prevalence of skin cancer, and the rapid integration of artificial intelligence into diagnostic workflows. Within this ecosystem, digital dermatoscopy stands out as a critical frontier, bridging the gap between traditional clinical examination and advanced digital health solutions. As we move deeper into the mid-2020s, understanding the trajectory of this market is no longer optional for stakeholders; it is a strategic imperative.
This article serves as a strategic preview to our latest comprehensive study, the Worldwide Digital Dermatoscope Market Research. Our objective is to outline the macroeconomic forces shaping the industry, highlight the competitive dynamics at play, and demonstrate why access to granular, data-backed intelligence is essential for informed decision-making in 2026 and beyond. True mastery of this landscape requires a compass grounded in precise data, which our full report provides in detail.
Market Trajectory and Growth Dynamics
The digital dermatoscope sector has demonstrated remarkable resilience and expansion over the past half-decade. Our historical analysis from 2020 through 2025 reveals a consistent upward trend in market valuation, reflecting the accelerated adoption of digital imaging tools in clinical settings. Building on this momentum, the forecast period from 2026 to 2032 projects sustained growth, with the market expected to reach new valuation milestones by the end of the decade.
Worldwide Digital Dermatoscope Market
Central to our forecast is a robust Compound Annual Growth Rate (CAGR), indicating that the industry will continue to expand at a pace well above many mature medical device categories. This growth is underpinned by several structural drivers: the increasing demand for non-invasive diagnostic procedures, the rollout of telemedicine infrastructure that relies on high-quality digital imaging, and the growing homogenization of healthcare standards across emerging markets. However, growth is not uniform across all vectors, and understanding where value is being created requires a nuanced view of product types, end-user segments, and geographic penetration.
Our full analysis dissects these trends, offering stakeholders a clear view of the total addressable market. The data indicates that while the overall market size is expanding significantly, the distribution of revenue across different segments varies considerably based on regulatory environments, reimbursement policies, and technological maturity. For investors and product leaders, identifying the high-growth pockets within this broader expansion is key to capitalizing on the opportunity.
Dermatoscope Market
Segmentation and Value Chains
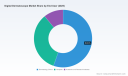
To navigate this market effectively, one must look beyond aggregate numbers. The Worldwide Digital Dermatoscope Market is segmented across multiple dimensions, each presenting distinct strategic considerations. On the product front, the ecosystem is divided between portable handheld devices and integrated imaging systems. Each category serves different clinical needs, price points, and workflow requirements. Handheld units often appeal to practitioners seeking flexibility and ease of deployment, while integrated systems are favored by large-scale clinics and hospitals requiring comprehensive data management and total body mapping capabilities.
End-user segmentation further illuminates where demand is concentrated. Dermatology clinics represent a primary hub for adoption, driven by the need for efficient lesion tracking and patient monitoring. Hospitals and academic research institutes also form significant pillars of demand, often driven by complex case management and the integration of dermoscopy into broader diagnostic protocols. Understanding the specific revenue contributions and growth rates within these segments allows companies to tailor their go-to-market strategies with precision.
Regionally, the market presents a diverse landscape. North America and Europe have historically commanded the largest shares of revenue, supported by well-established healthcare reimbursement frameworks and high awareness of skin cancer screening. Meanwhile, the Asia Pacific region is emerging as a critical growth engine, fueled by expanding healthcare access and increasing investment in medical technology infrastructure. Latin America and the Middle East and Africa, while currently smaller in absolute terms, offer untapped potential as digital health initiatives gain traction. Our report provides a detailed breakdown of these regional dynamics, enabling stakeholders to prioritize markets that align with their risk appetite and strategic goals.
Competitive Landscape and Innovation Waves
The competitive environment in the digital dermatoscope market is characterized by a mix of established medical device manufacturers and specialized technology firms. Market concentration is notable, with a core group of players holding a significant portion of industry revenue. Understanding the positioning, technological differentiators, and strategic moves of these key players is vital for benchmarking and identifying partnership or acquisition opportunities.
Leading manufacturers such as Heine Optotechnik and DermLite continue to drive product innovation, focusing on enhanced imaging quality, user ergonomics, and connectivity features. Heine Optotechnik's DELTA series, for instance, has been widely recognized for its precision and AI integration capabilities aimed at melanoma detection. Similarly, DermLite has maintained a strong presence with its DL series, leveraging polarized and non-polarized light modes alongside robust connectivity solutions that support teledermatology workflows.
Complementing these device manufacturers are companies offering sophisticated software and integrated platforms. FotoFinder Systems has carved a significant niche with its Moleanalyzer and Medicam offerings, emphasizing AI-based lesion analysis and total body mapping. Recent developments, such as the launch of enhanced AI algorithms, underscore the industry's shift toward data-driven diagnostics. Canfield Scientific also contributes to this landscape with its DermaGraph and IntelliStudio systems, integrated with vision software for comprehensive dermatological imaging and tracking. Smaller yet agile players like Dinolite and AnMo Electronics Corporation provide portable and wireless solutions, often targeting cost-sensitive segments or specific clinical use cases with features like high-megapixel sensors and adjustable magnification.
The pace of innovation is rapid, and recent activity illustrates the intensity of competition. Product launches, certification updates, and strategic appearances at major medical conferences are frequent signals of market evolution. These events often signal shifts in regulatory compliance, feature sets, or market entry strategies. Our full report catalogs these developments, providing a timeline of key milestones that stakeholders can use to anticipate competitive moves and align their own roadmaps.
Regulatory, Reimbursement, and Operational Dynamics
Beyond technology and competition, the market is heavily influenced by regulatory frameworks and reimbursement policies. Compliance with medical electrical equipment safety standards, such as IEC 60601-1, is a non-negotiable requirement for manufacturers seeking to operate in major healthcare markets. Adherence to these standards not only ensures patient protection but also serves as a barrier to entry for less established players, consolidating the position of incumbents.
Reimbursement dynamics further shape market accessibility. In the United States, for example, specific CPT codes cover dermoscopy procedures using digital devices in outpatient settings. The availability and clarity of such codes directly impact the adoption rate of digital dermoscopes, as they influence the economic viability for healthcare providers. Changes in reimbursement landscapes can accelerate or decelerate demand, making it essential for stakeholders to monitor policy updates closely.
On the operational side, manufacturing costs remain a critical consideration. Medical-grade optics and LED components constitute a substantial portion of production expenses. Fluctuations in the availability or pricing of these components can affect margins and pricing strategies. Companies with strong supply chain management and vertical integration capabilities are better positioned to navigate these cost pressures while maintaining competitive pricing.
Strategic Imperatives for 2026
As we look toward 2026, several strategic imperatives emerge for participants in the digital dermatoscope market. First, differentiation through technology remains paramount. The integration of AI algorithms for lesion analysis, enhanced connectivity for telehealth, and ergonomic improvements are no longer optional features; they are baseline expectations. Companies that can innovate faster and more effectively will capture greater market share.
Second, market expansion requires a targeted approach. Given the varying maturity levels across regions and segments, a one-size-fits-all strategy is unlikely to succeed. Stakeholders must assess local regulatory requirements, reimbursement environments, and clinical workflows to tailor their offerings. In emerging markets, affordability and ease of use may take precedence, while in established markets, advanced features and integration with existing health IT systems may drive purchasing decisions.
Third, partnerships and ecosystem building are increasingly important. Collaboration with academic institutions, dermatology associations, and technology providers can accelerate R&D, validate clinical efficacy, and expand distribution networks. Additionally, as data becomes central to dermatological care, companies must address data privacy, security, and interoperability concerns to build trust with healthcare providers and patients.
Conclusion
The Worldwide Digital Dermatoscope Market represents a dynamic and growing opportunity at the intersection of healthcare, technology, and patient care. The trajectory from 2020 through 2032 points to sustained expansion, driven by technological innovation, demographic shifts, and evolving clinical standards. However, capturing value in this market requires more than a surface-level understanding. It demands deep, data-driven insights into segmentation, competition, regulatory frameworks, and regional nuances.
Our comprehensive research study provides exactly that depth. From granular revenue splits across product types, end users, and regions to detailed competitor profiles and recent industry developments, the report offers a complete intelligence package for strategic planning. It enables stakeholders to benchmark performance, identify high-growth opportunities, assess competitive threats, and formulate robust market entry or expansion strategies.
For investors, manufacturers, and healthcare providers aiming to make informed decisions in 2026 and beyond, the full report is an indispensable resource. It transforms complex market data into actionable intelligence, empowering you to navigate the digital dermatoscope landscape with confidence. We invite you to explore the complete analysis and unlock the full strategic value of this evolving market.
For detailed analysis of this topic, please visit the official page: Worldwide Digital Dermatoscope Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts Global Phenolic Molding Compound Market to Hit $3,128.18M by 2032, CAGR 4.85%
By pmarketresearch, 2026-09-16
Navigating the Future of the Global Phenolic Molding Compound Market: Strategic Insights for 2026 and Beyond
The phenolic molding compound (PMC) industry stands at a critical inflection point. As global manufacturing ecosystems oscillate between post-pandemic normalization, supply chain restructuring, and accelerating electrification, decision-makers across automotive, electrical, and industrial sectors require more than surface-level trend summaries. They need granular, forward-looking intelligence calibrated for execution. Our newly released Worldwide Phenolic Molding Compound Market study delivers exactly that: a rigorous, data-driven blueprint for navigating the 2026-2032 horizon.
This article outlines the strategic architecture of the report, interprets the macro trajectory shaping the industry, and demonstrates how procurement leaders, product developers, and competitive intelligence teams can leverage the findings to secure operational advantage in the coming years.
Market Trajectory: Decoding the 2026-2032 Growth Arc
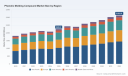
The global PMC market has demonstrated remarkable resilience through a volatile five-year cycle. Tracking historical performance from 2020 through the 2025 base year reveals a compound revenue stream that weathered raw material shocks, geopolitical trade friction, and shifting end-use demand. The overall market expanded from approximately 1,810.45 million USD in 2020 to a 2025 valuation of 2,245.5 million USD. While 2024 registered a temporary contraction to 2,082.15 million USD—a reflection of inventory corrections and regional demand recalibration—the subsequent rebound underscores the sector's structural durability and the latent pull from high-growth downstream applications.
Looking ahead, our forecast model projects the market to reach 2,430.68 million USD in 2026, accelerating through the end of the decade to touch 3,128.18 million USD by 2032. This trajectory translates to a forecasted CAGR of 4.85 percent across the 2026-2032 period. For strategic planners, this growth rate is not merely a headline figure; it signals a maturing but still expanding addressable space where incremental gains will be captured by firms that align product portfolios with regional price dynamics, regulatory shifts, and application-specific performance requirements.
Phenolic Resins Market
Crucially, the forecast accounts for divergent regional fundamentals. Raw material pricing volatility, exemplified by phenol markets in Q1 2026, illustrates why a uniform global strategy is insufficient. In Northeast Asia, phenol prices climbed to 1.01 USD/KG in March 2026, reflecting an 8.6 percent upward move from December driven by firm demand from phenolic resin manufacturing and rising cumene feedstock costs. Europe presents a contrasting picture: prices settled at 1.00 USD/KG, dipping 3.8 percent amid softening resin-sector demand and competitive Asian imports. North America registered 1.18 USD/KG, with a modest 0.8 percent decline against a backdrop of adequate local production and slightly weak resin demand. These price divergences directly influence margin structures, sourcing strategies, and regional capacity allocation—variables our report dissects in depth.
Report Architecture: What Decision-Makers Will Find Inside
The Worldwide Phenolic Molding Compound Market study is engineered for execution. Rather than offering static snapshots, the report maps the value chain from raw material inputs through compounding, molding processes, and end-use deployment. Every section is designed to answer the questions that keep strategy and operations leaders awake at night: where will volume concentrate, which product architectures will command pricing power, and how should organizations position against intensifying regional competition.
Granular Segmentation Analysis
The report deconstructs the market across multiple dimensions, enabling readers to isolate the sub-segments that align with their strategic mandates. A thorough type-level evaluation contrasts Novolac and Resol phenolic resin architectures, examining how their distinct curing behaviors, thermal profiles, and cost structures position them across compression, transfer, and injection molding workflows. Application-level analysis traces demand drivers across automotive, electrical and electronics, industrial components, aerospace and defense, and other emerging verticals. Each application segment is examined through the lens of performance thresholds, certification requirements, and substitution risk, providing a clear view of where growth will materialize and why.
Worldwide Phenolic Molding Compound Market
Regional Supply-Demand Equilibrium
Regional dynamics receive dedicated treatment, recognizing that PMC consumption is fundamentally shaped by local manufacturing footprints, logistics constraints, and raw material accessibility. The analysis maps production capacity distribution, evaluates regional pricing pressure points, and identifies how trade flows and localized resin demand are reshaping competitive positioning. Readers will gain a clear understanding of which regions function as volume engines, which are transitioning toward higher-value formulations, and where supply gaps may create tactical opportunities.
Competitive Landscape: Who Holds the Field and How the Board Is Shifting
Market concentration in the global PMC sector remains moderate, with the top three players collectively commanding approximately 24.15 percent of revenue and the top five holding 38.6 percent. This fragmented-but-consolidating structure creates both defensive moats and offensive openings. The report profiles the firms defining the competitive terrain, analyzing their geographic reach, technical differentiators, and strategic maneuvers.
- Sumitomo Bakelite Co., Ltd. (Tokyo, Japan) maintains a globally integrated footprint spanning production sites in Shizuoka, Nantong, North America, Belgium, and Singapore. Its portfolio emphasizes glass-fiber-reinforced and filler-modified phenolic compounds engineered for weight reduction, cost efficiency, and design flexibility. In March 2026, the company launched a new series of high-adhesion phenolic resins designed for diverse material interfaces, broadening its formulation capabilities for advanced molding applications. This followed a 2024 capacity expansion in Nantong, China, which added significant volume to its regional supply base.
- PLENCO (Plastics Engineering Company), headquartered in Sheboygan, Wisconsin, USA, delivers both novolac and resol phenolic resins alongside tailored molding compounds. Its value proposition centers on dimensional stability, electrical insulation, and heat resistance, serving industrial customers across compression, transfer, and injection molding processes.
- Bakelite Synthetics (Bakelite), with multiple US sites and global reach, emphasizes high-quality thermoset solutions for consumer goods, electrical, and industrial sectors. Its strategy hinges on consistent quality assurance and broad application coverage across mature and growing verticals.
- Chang Chun Plastics Co., Ltd. (Taiwan) manufactures the LONGLITE brand of heat-hardening phenolic molding compounds, formulated to meet customer-specific requirements in electrical, automotive, and industrial applications. Its regional strength in Asia positions it to capture demand tied to localized supply chain development.
- Resinoid Engineering Corporation (USA) specializes in phenolic compound raw goods and custom compounding, with a particular emphasis on high-temperature materials rated for continuous use above 400°F. Its aftermarket automotive focus makes it a notable player in performance-critical niche applications.
- Shengquan Group (China) ranks among the largest phenolic resin manufacturers globally, supplying resins for molding compounds to both domestic and international enterprises. Its scale and integrated supply chain provide a cost-advantaged base for regional and export markets.
- Kaihua Ruida Plastic-Tech Co., Ltd. (Zhejiang, China) produces UL-approved phenolic molding compounds and Bakelite powders, including the PF2D1-9600J series, engineered for heat resistance and dimensional stability across appliance, construction, and automotive sectors.
The report does not stop at profiles. It evaluates how recent capacity investments, product launches, and regional pricing pressures are reshaping share dynamics. Readers will understand which players are expanding into high-performance formulations, which are leveraging cost leadership in core segments, and where consolidation or partnerships may alter the competitive hierarchy over the forecast period.
Industry Dynamics: Raw Material Pressure, Regulatory Anchors, and Demand Realignment
No strategic assessment of the PMC market is complete without addressing the forces that constrain or enable growth. Raw material economics remain the most immediate variable. As noted, phenol pricing divergence across Northeast Asia, Europe, and North America in early 2026 illustrates how regional feedstock costs and import competition directly influence compounding margins. The report integrates these pricing signals into forward-looking cost scenarios, helping procurement teams anticipate squeeze points and evaluate hedging, dual-sourcing, or formulation-adaptation strategies.
Regulatory and certification frameworks further shape market access, particularly in electrical and electronics applications. UL certification remains active for a wide array of phenolic molding compounds supplied as pellets, covering critical performance metrics such as flame class, hot wire ignition (HWI), high current arc ignition (HAI), and relative thermal index (RTI). Compliance with these standards is not optional; it is a gating requirement for market entry in safety-sensitive segments. Our analysis maps how certification requirements influence product development timelines, testing costs, and competitive positioning, enabling firms to align R&D investment with the compliance pathways that matter most to their target customers.
Beyond inputs and regulation, demand-side realignment is accelerating. Automotive electrification, lightweighting mandates, and the continued migration toward higher-efficiency electrical components are shifting the composition of PMC consumption. At the same time, industrial and aerospace applications continue to prize the thermal stability, arc resistance, and mechanical integrity that phenolic architectures deliver. The report examines how these demand vectors interact with regional supply capacity, helping readers anticipate which application segments will see tightening supply, which will benefit from formulation innovation, and where substitution risk warrants proactive portfolio planning.
Strategic Value for 2026 Decision-Making
The 2026-2032 window is not a period for passive observation. It is a window in which capacity commitments, formulation roadmaps, and sourcing architectures will determine which organizations capture margin and which concede share. Our study is built to convert market complexity into actionable clarity.
- For procurement and supply chain leaders, the report provides the regional price context and supply-concentration data needed to negotiate from an informed position, evaluate supplier risk, and structure resilient sourcing networks amid divergent raw material trends.
- For product development and engineering teams, the segmentation analysis highlights where novolac versus resol architectures, reinforcement strategies, and certification pathways create differentiation opportunities—and where performance thresholds are becoming table stakes.
- For competitive intelligence and corporate strategy functions, the firm-level profiles and concentration metrics reveal who is expanding, who is innovating, and where acquisition, partnership, or capacity investment may shift the balance of power.
- For executive planning, the macro trajectory—anchored in rigorous historical data and a transparent 2026-2032 forecast—offers a defensible baseline for capital allocation, market-entry evaluation, and long-range revenue modeling.
Importantly, the report is structured to support scenario planning rather than rigid forecasting. Market conditions will evolve as feedstock costs fluctuate, regulatory standards tighten, and end-use demand shifts with macroeconomic cycles. By grounding strategy in a detailed, evidence-based view of the market's architecture, organizations can adjust with confidence rather than react under pressure.
Accessing the Full Intelligence Package
The Worldwide Phenolic Molding Compound Market study goes far beyond the macro trajectory and competitive overview outlined here. It delivers detailed segmentation assessments, regional supply-demand equilibria, firm-level strategic evaluations, raw material cost scenarios, and certification-impact analysis—all calibrated to support decisive action in 2026 and throughout the 2032 horizon. Core quantitative breakdowns, sub-segment growth rates, and granular regional revenue splits are integrated into the complete report, enabling readers to model outcomes specific to their portfolios and geographies.
Organizations that treat this market as a single homogeneous block will miss the nuanced opportunities hidden in type-specific demand, regional pricing divergence, and application-level performance requirements. The firms that thrive will be those that combine technical precision with strategic foresight. This report is designed to supply both.
To access the full dataset, segmentation matrices, competitive deep dives, and forward-looking scenario analysis, request the complete Worldwide Phenolic Molding Compound Market research. The full intelligence package is available through our research portal, where you can review the complete forecast model, examine detailed firm profiles, and align the findings directly with your 2026 planning cycle.
For detailed analysis of this topic, please visit the official page: Worldwide Phenolic Molding Compound Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Liquid Cooling Fast Connection Market Hits $1.24B in 2025, Forecast 18.25% CAGR to $4.01B by 2032
By pmarketresearch, 2026-09-16
Powering the Liquid Cooling Revolution: Strategic Intelligence for the Fast Connection Solutions Market
The thermal management landscape is undergoing a structural transformation. As artificial intelligence workloads intensify and data center power densities surge, the industry's reliance on air cooling has reached its physical and economic limits. Direct liquid cooling (DLC) and immersion cooling have transitioned from niche alternatives to essential infrastructure, driving unprecedented demand for reliable, high-performance fluid transfer components. At the heart of this shift lies the fast connection solutions ecosystem, a critical enabler of leak-free, high-flow, and rapid deployment cooling architectures.
PW Consulting's latest worldwide market research on Fast Connection Solutions for Liquid Cooling Systems offers a comprehensive, data-driven lens into this rapidly expanding sector. This article outlines the strategic imperatives shaping the 2026 decision-making environment, contextualizes the macroeconomic trajectory of the market, and previews the analytical depth available in the full report. For executives, engineers, and investors navigating the thermal infrastructure value chain, understanding the connective tissue of liquid cooling is no longer optional—it is a competitive necessity.
The Macro Trajectory: A Market in Hypergrowth
The financial signals from the past half-decade tell a clear story of acceleration. Valued at approximately 585.3 million USD in 2020, the global fast connection solutions market for liquid cooling systems has expanded consistently, closing 2025 at an estimated 1,241.18 million USD. The forward-looking projection is equally compelling: revenues are expected to surpass the 1,498 million USD threshold in 2026 and climb steadily toward 4,012.79 million USD by 2032. This translates to a compound annual growth rate of 18.25 percent throughout the 2026–2032 forecast horizon, placing the sector among the fastest-growing subsegments within the broader thermal management and fluid handling industries.
Worldwide Liquid Cooling Couplings Market
Such sustained expansion is not merely cyclical. It is fundamentally anchored in the architectural redesign of computing and energy infrastructure. As hyperscale operators, colocation providers, and industrial facilities migrate toward high-density thermal solutions, the requirement for quick disconnects, blind-mate connectors, and push-to-connect fittings has evolved from a maintenance convenience to a core design specification. The market's trajectory reflects a structural reordering of priorities: downtime minimization, pressure-drop optimization, coolant purity, and interoperability now dictate component selection as much as upfront cost.
Technology Architectures and Segment Dynamics
The market's growth is distributed across three primary connection architectures, each addressing distinct operational requirements. Non-spill quick disconnects dominate the volume landscape, engineered to maintain fluid integrity during mating and unmating cycles—a non-negotiable feature in live data center environments where coolant leaks can trigger immediate operational shutdowns. Blind-mate connectors address the need for automated, alignment-tolerant connections in high-density rack deployments, while push-to-connect fittings serve applications prioritizing rapid manual installation and serviceability.
Material science continues to shape segment performance. Metallic solutions, particularly those fabricated from stainless steel, aluminum, and brass, maintain a dominant position due to their structural strength, thermal resilience, and compatibility with high-pressure cooling loops. Simultaneously, polymer-based valve and piping architectures—leveraging materials such as PVDF, PP-H, and PE100—are gaining traction for their ability to reduce weight, optimize flow characteristics, and deliver leak-tight performance in precision cooling circuits. This dual-material evolution reflects a broader industry trend: component selection is increasingly driven by application-specific thermal loads, coolant chemistry, and facility layout constraints rather than one-size-fits-all specifications.
Geographic Distribution and Application Diversification
Demand is not evenly distributed across the globe, nor is it concentrated in a single end-use vertical. The market exhibits a clear geographic weighting that mirrors regional data center build-out, semiconductor fab expansion, and electric vehicle infrastructure deployment. Supply chains, manufacturing footprints, and local compliance environments further differentiate regional demand patterns, creating both localized opportunities and cross-border procurement considerations for multinational operators.
On the application side, data centers and high-performance computing environments represent the most substantial demand driver, reflecting the direct correlation between AI accelerator density and liquid cooling adoption. Electric vehicle charging and energy storage infrastructure contributes a meaningful secondary demand stream, particularly where rapid coolant routing and field-serviceability are prioritized. Semiconductor manufacturing and medical/industrial equipment round out the application portfolio, each introducing specialized requirements around cleanliness, thermal stability, and connection reliability. The interplay between these verticals creates a diversified demand base that insulates the market from single-sector volatility while simultaneously raising the bar for component standardization.
Porter's Five Forces and Competitive Intensity
The competitive structure of the fast connection solutions market reflects a moderately concentrated landscape with room for both established incumbents and specialized challengers. Top-tier players collectively account for a substantial share of revenue, underscoring the importance of engineering reputation, certification portfolios, and long-term supply agreements in securing anchor contracts. At the same time, the fifth and sixth forces—substitute threats and new entrant potential—remain active. Standardization initiatives, modular cooling designs, and cross-vendor interoperability programs are gradually lowering switching costs, pressuring suppliers to compete on total cost of ownership, flow efficiency, and integration support rather than brand loyalty alone.
Bargaining power varies across the value chain. Large data center operators and hyperscale buyers wield considerable leverage in specifying connection standards and demanding compliance with open frameworks, while mid-tier integrators and facility contractors often rely on supplier-led engineering guidance to navigate fluid dynamics, pressure ratings, and material compatibility. Supplier power is moderated by a healthy pipeline of qualified manufacturers across North America, Europe, and Asia Pacific, though lead-time reliability, quality assurance, and post-installation support remain critical differentiators. The threat of substitutes is muted by the physical specificity of liquid cooling loops, yet the rise of polymer-based valve assemblies and hybrid metal-polymer designs keeps the innovation frontier active.
Competitive Landscape: Leaders and Strategic Moves
The market features a cohort of well-established industrial coupling manufacturers and thermal management specialists, each carving distinct positioning within the liquid cooling ecosystem. CPC (Colder Products Company) continues to advance its Everis series quick disconnect couplings, including blind-mate and high-flow variants engineered for electronics and data center thermal management, backed by rigorous reliability testing protocols. Parker Hannifin's Quick Coupling Division emphasizes dripless, non-spill performance under pressure, targeting server and rack cooling applications where thermal loads and uptime expectations are exceptionally high.
CEJN has strengthened its footprint in data center CDU applications by supplying high-flow, low-pressure-drop quick connect couplings, including OCP-compliant series developed alongside industry leaders to enable blind-mate and interchangeable deployment scenarios. Danfoss, through its Hansen thermal management line, focuses on optimized flow paths that reduce pressure drop while maintaining robust thermal control for electronics and liquid-cooled infrastructure. Stäubli brings clean-break, quick and dry disconnect solutions to both industrial and data center environments, with recent product introductions targeting compact liquid-cooled optical architectures where space constraints and high-temperature performance intersect.
Amphenol Industrial Operations supports a broad portfolio of liquid cooling quick disconnect connectors spanning blind-mate, quick-connect, and high-flow architectures, serving data centers, EV infrastructure, and energy storage systems. Gates Corporation advances full-flow quick disconnect couplings tailored for direct-to-chip liquid cooling, prioritizing secure and simple connections compatible with existing facility infrastructure. Specialty Manufacturing Co. contributes custom and standard thermal management quick disconnects, including the Universal Quick Disconnect series, with an emphasis on reliability in electronics cooling contexts. TITAN Fluid has emerged as a notable player offering stainless steel quick disconnect couplings that align with OCP and NVIDIA specifications, targeting zero-downtime connection requirements in high-performance data centers. Motivair, operating under Schneider Electric, supplies Everis quick connects and Dynamic Cold Plates designed for seamless water transfer in direct-to-chip cooling architectures.
Recent product and partnership activity underscores how actively this competitive field is evolving. In early 2026, GF and Rittal announced a full-scope polymer cooling infrastructure solution, featuring a patented dual-ball valve in PVDF designed for direct-to-chip liquid cooling with optimized flow paths and leak-tight operation. Around the same period, Stäubli unveiled a compact quick disconnect variant aimed at liquid-cooled optical modules during a major industry keynote, highlighting the push toward miniaturization in high-density photonic cooling. Earlier initiatives included trade show showcases and technical publications addressing leakage-free connections for battery energy storage systems, low-pressure-loss coupling demonstrations for semiconductor and data center cooling, and engineering guidance on reducing pressure drops to improve thermal management energy efficiency. These moves illustrate a market where product differentiation, standards alignment, and application-specific validation are accelerating simultaneously.
Regulatory and Standards-Driven Demand Catalysts
External mandates and industry guidelines are acting as powerful adoption accelerants. Updated thermal guidelines for data processing environments and dedicated liquid cooling recommendations have codified the viability of higher supply temperatures and energy-efficient loop designs, reinforcing the case for liquid cooling in high-density server environments. Complementary standards defining data center efficiency metrics place cooling system performance under continuous scrutiny, while regional energy efficiency mandates increasingly favor infrastructure choices that support lower power usage effectiveness targets. In parallel, the broader shift toward direct liquid cooling and immersion cooling is being driven by AI and HPC power density increases, with documented energy savings potential relative to traditional air cooling and the ability to support ultra-low facility efficiency ratios. These dynamics do not merely influence procurement preferences; they reshape engineering specifications, architectural planning, and capital allocation timelines across the digital infrastructure sector.
Worldwide Fast Connection Solutions for Liquid Cooling System Market
What the Full Report Delivers
The PW Consulting Worldwide Fast Connection Solutions for Liquid Cooling System Market study is designed to convert this complex landscape into actionable intelligence. Beyond the headline growth trajectory, the report deconstructs historical performance, forecast pathways, and the operational variables that will determine market outcomes through 2032. It provides a structured assessment of connection architecture demand, end-use application priorities, and regional demand weighting, while mapping the strategic behavior of leading manufacturers and emerging participants.
Practitioners will find detailed analysis of product development directions, materials and flow-optimization trends, and the regulatory and standards environment shaping specification requirements. The research also evaluates competitive positioning, partnership activity, and the practical implications of interoperability frameworks for supply chain planning and product selection. For organizations evaluating market entry, capacity expansion, component standardization, or supplier negotiation strategy, the report offers a decision-ready framework that connects market-level signals with segment-level execution considerations.
Strategic Takeaways for 2026 Decision-Makers
As liquid cooling transitions from specialized deployment to mainstream infrastructure, fast connection solutions have become a defining component of thermal reliability, serviceability, and system efficiency. The market's growth path reflects more than rising compute demand; it signals a fundamental rethinking of how facilities are designed, maintained, and scaled. Decision-makers who align their product roadmaps, procurement standards, and partnership strategies with this evolving reality will be better positioned to capture value in a market where performance, compliance, and interoperability increasingly determine competitive outcomes.
To obtain the full dataset, granular segmentation analysis, forecast breakdowns, and complete competitive profiles, we invite you to explore the complete PW Consulting market report. The detailed intelligence contained within provides the precision required to translate macro trends into executable strategy across engineering, commercial, and investment functions.
For detailed analysis of this topic, please visit the official page: Worldwide Fast Connection Solutions for Liquid Cooling System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Worldwide High Temp Thermocouples Market Hits $582.45 Million in 2025 to Reach $829.45 Million by 2032
By pmarketresearch, 2026-09-16
Navigating the Heat: Strategic Intelligence for the Worldwide High Temperature Thermocouples Market (2026-2032)
In the complex landscape of industrial instrumentation, precision is not merely a technical specification; it is a critical determinant of operational safety, efficiency, and profitability. As global industries push the boundaries of thermal processing, the demand for reliable temperature sensing solutions has never been more paramount. PW Consulting is proud to unveil our latest comprehensive study: the Worldwide High Temperature Thermocouples Market analysis. This report is designed not just as a collection of numbers, but as a strategic compass for stakeholders navigating the thermal instrumentation sector through 2032.
For executives, investors, and strategic planners, understanding the trajectory of this market is essential. The ability to measure extreme temperatures accurately underpins everything from semiconductor fabrication to aerospace propulsion. Our latest research provides a granular yet holistic view of where the market has been, where it stands today, and where it is headed. This article serves as an executive overview, highlighting the strategic value embedded within our full dataset and analysis, while outlining the broader industrial context shaping the competitive landscape.
Macro Growth Trajectory and Market Valuation
The economic narrative for high temperature thermocouples is one of steady, resilient expansion. Our analysis tracks historical performance from 2020 through the base year of 2025, projecting forward into the forecast period ending in 2032. After demonstrating robust recovery and growth in the early 2020s, the market stabilized around a valuation of approximately 582.45 Million USD in 2025. Looking ahead, the market is poised for consistent valuation growth, with projections indicating a rise to 647.47 Million USD in 2026 and climbing steadily toward 829.45 Million USD by the end of the forecast window in 2032.
Worldwide High Temperature Thermocouples Market
This growth trajectory is underpinned by a Compound Annual Growth Rate (CAGR) of 5.17 Percent. While this figure indicates stability rather than explosive volatility, it reflects the specialized nature of the industry. High temperature thermocouples are critical components, not discretionary spend. Consequently, growth is tied closely to foundational industrial output and technological upgrades in extreme environments. For decision-makers, this suggests a market characterized by predictable demand cycles, where strategic investment should focus on long-term capacity planning and R&D rather than short-term market timing. The currency valuation remains standardized in USD, facilitating global comparison across regions and segments for international stakeholders.
Segmentation Landscape Overview
The market is diversified across three primary dimensions, each offering distinct opportunities and challenges for players in the value chain. Understanding the interplay between type, application, and geography is crucial for targeted strategy development.
Mineral Insulated Thermocouple Cables Market
- The market is divided by type into three key categories: Noble Metal Thermocouples, Refractory Metal Thermocouples, and High-Temp Base Metal Thermocouples. Noble metals typically dominate high-end precision applications, while refractory metals serve extreme thermal environments.
- Application segmentation reveals heavy reliance on core industrial sectors. Key verticals include Iron and Steel Manufacturing, Aerospace and Defense, Glass and Ceramics, Semiconductor Processing, and Power Generation. Each sector imposes unique durability and accuracy requirements on sensor assemblies.
- Regional analysis covers major global theaters, including Asia Pacific, North America, Europe, Latin America, and the Mideast and Africa. While specific regional shares fluctuate based on manufacturing shifts and infrastructure investment, the global footprint remains widespread, with industrial hubs driving localized demand.
It is important to note that the specific revenue breakdowns and percentage splits within these segments are detailed exclusively in the full report. These granular figures are critical for identifying niche growth pockets and assessing relative market penetration potential, but they require the depth of our full proprietary modeling to interpret correctly.
Competitive Dynamics and Industry Leaders
The competitive landscape is moderately concentrated, with a competitive environment that rewards technical specialization and supply chain reliability. Our data indicates a CR3 of approximately 38.45 Percent and a CR5 of 52.12 Percent. This structure suggests that while market leaders hold significant sway, there is ample room for specialized players to carve out niches through innovation and customization.
Several key companies define the current operational standard. Omega Engineering, a subsidiary of Spectris plc, offers an extensive range of high temperature options including exotic metal and Super OMEGACLAD probes designed for demanding industrial and laboratory applications. Similarly, WIKA Alexander Wiegand SE & Co. KG in Germany manufactures high-temperature thermometers and thermocouples such as the TC82 and TC80 series, targeting extreme high temperature measurement in industrial processes. Watlow, based in St. Louis, provides high-heat thermocouples including surface mount and multipoint assemblies for demanding thermal applications in industrial heating systems.
Other significant contributors include Pyromation, which specializes in thermocouples, RTDs, and thermowells for industrial process control, and Thermo Electric Company, Inc., which has been manufacturing temperature measurement solutions optimized for high temperature environments since 1941. Nanmac stands out as a world leader in high temperature thermocouples and RTDs with a focus on extreme environment performance. Conax Technologies offers high temperature thermocouples with various termination styles and sealing solutions for harsh industrial conditions. International players like Okazaki Manufacturing Company produce sheathed thermocouples specifically engineered for high temperature applications, while Tempsens Instruments manufactures high temperature variants for industries such as cement, glass, petrochemical, and steel.
Further down the specialized chain, Marlin Manufacturing produces high-quality industrial thermocouples and custom assemblies, particularly for semiconductor applications. ARi Industries, Inc. produces standard and custom high temperature and ultra high temperature thermocouples including mineral insulated types. Eustis/Pyrocom manufactures industrial thermocouples for high temperature requirements in metal, glass, oil and gas, and power generation sectors.
Recent developments highlight the active nature of this competitive field. In January 2025, Pyromation participated in the International Production and Processing Expo, showcasing temperature sensors including thermocouples. Around the same time, Ashcroft announced in March 2025 that additional models of RTDs and thermocouples are now FM approved for use in hazardous locations, a critical certification for safety-sensitive markets. Looking toward mid-2026, Temprel is scheduled to exhibit temperature measurement solutions including high temperature capabilities at Space Tech Expo 2026, signaling continued innovation in the aerospace sector.
Regulatory and Technical Frameworks
Any strategic assessment of this market must account for the regulatory and technical standards that govern product specification and acceptance. Compliance is not optional; it is a barrier to entry and a baseline for trust. ASTM E839-23 provides standard test methods for sheathed thermocouples and sheathed thermocouple cable used in high temperature applications. This standard is vital for quality assurance in procurement. Additionally, IEC 60584-1 and ASTM E230/E230M define accuracy classes and EMF-temperature relationships for standardized thermocouples including high temperature types. These regulations ensure interoperability and precision across different manufacturers and systems.
On the materials front, the industry relies heavily on advanced metallurgy. High temperature thermocouples, particularly Types R, S, and B, rely on platinum-rhodium alloys as the primary core component for operation above 1000 Degrees Celsius. The precious metal aspect introduces cost volatility linked to raw material markets. Analysts Insights noted in October 2025 that the Precious Metal Thermocouple market, encompassing platinum-rhodium types, was valued at USD 264 Million in 2024 and is projected to reach USD 363 Million by 2032. This sub-segment dynamic is a crucial input for cost modeling and pricing strategies in the broader high temperature market.
Market Drivers and Strategic Opportunities
Demand for high temperature thermocouples is driven by requirements for precise temperature control in semiconductor fabrication and high-temperature industrial processes. As semiconductor nodes shrink and processing temperatures increase, the tolerance for error diminishes. Similarly, the resurgence in heavy industry and the push for advanced materials in aerospace and defense create sustained pressure on the supply chain to deliver sensors that can withstand harsher conditions for longer durations.
Strategic opportunities exist at the intersection of these demands. Companies that can offer not just the sensor, but the integration expertise and certification compliance, will capture greater value. The shift toward automation in power generation and the constant upgrades in glass and ceramics manufacturing provide additional avenues for growth. However, success depends on accurate forecasting of capacity needs and raw material sourcing, specifically regarding platinum and rhodium.
Value of the Full Study
While this overview outlines the structural pillars of the market, the complete PW Consulting report offers the actionable intelligence required to execute strategy. The full document provides detailed revenue breakdowns by region and type, allowing for precise market sizing for specific business units. It includes comprehensive competitor profiles, analyzing market share stability and strategic moves. Furthermore, the forecast models incorporate sensitivity analysis regarding raw material costs and regulatory changes, giving stakeholders a range of scenarios rather than a single point estimate.
For procurement specialists, the report identifies supply chain concentration risks. For investors, it highlights growth segments beyond the headline CAGR. For product developers, it maps the regulatory landscape to prevent costly compliance errors. The data regarding segment splits and specific regional valuations is curated to support these specific use cases, providing a layer of detail that general market summaries cannot match.
To access the complete dataset, including the specific regional revenue figures, type-specific growth rates, and detailed competitor benchmarking, we invite you to explore the full Worldwide High Temperature Thermocouples Market research on our website. Understanding the heat map of this industry requires more than just surface temperature readings; it requires deep thermal imaging. Let PW Consulting provide the clarity you need to make informed decisions in this critical sector.
For detailed analysis of this topic, please visit the official page: Worldwide High Temperature Thermocouples Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Mobile UC&C Hits $27.78B in 2025, Forecast to $85.99B by 2032 at 17.52% CAGR
By pmarketresearch, 2026-09-16
Navigating the Mobile Unified Communications and Collaboration Landscape: Strategic Imperatives for 2026 and Beyond
The enterprise communication paradigm has undergone a fundamental transformation. What began as a response to remote work requirements has matured into a permanent architectural shift in how organizations connect, collaborate, and serve customers. Mobile unified communications and collaboration (UCC) is no longer a peripheral capability—it is the backbone of modern enterprise operations. As we enter 2026, leadership teams face a market characterized by accelerating consolidation, AI-driven feature expansion, and intensifying regulatory scrutiny. Understanding the trajectory of this market is not merely an exercise in forecasting; it is a strategic necessity for technology procurement, competitive positioning, and long-term organizational resilience.
Our latest Worldwide Mobile Unified Communications and Collaboration Market study delivers the comprehensive intelligence that executives, investors, and technology strategists require to navigate this complex environment. Drawing on extensive primary research, supplier interviews, and granular demand-side analysis, this report maps the market from its historical foundations through a detailed forecast period extending to the end of the decade. What follows is an overview of the strategic insights contained within, designed to demonstrate the report's value as a decision-support instrument.
The Macro Trajectory: A Market Defined by Sustained Acceleration
The numbers tell a story of relentless growth. From a baseline in the mid-2020s, the global mobile UCC market has expanded at a pace that has consistently outpaced traditional enterprise software categories. Historical data from the early 2020s through the present reveals a compound annual growth rate that underscores the structural demand underpinning mobile collaboration tools. The market has surpassed significant thresholds, with total revenue climbing from approximately $11.8 billion in 2020 to over $27.7 billion by 2025.
Worldwide Mobile Unified Communications and Collaboration Market
Looking forward, the trajectory remains steep. The study projects that market expansion will continue at a compound annual growth rate of 17.52 percent across the forecast horizon, with revenues projected to approach $33.4 billion in 2026 and steadily climb toward the $86 billion mark by 2032. This sustained growth reflects more than cyclical recovery; it signals the deep integration of mobile UCC capabilities into enterprise workflows, customer engagement models, and regulatory compliance frameworks. Decision-makers must understand that this growth is not diffuse—it is concentrated around specific solution categories and vertical applications that our report dissects in detail.
Such magnitude of expansion carries profound implications. Infrastructure investment, vendor partnerships, licensing strategies, and workforce training must all be calibrated against a market that is growing nearly twice as fast as many adjacent technology segments. Organizations that fail to align their communication architectures with this growth trajectory risk falling behind competitors who are leveraging mobile collaboration as a productivity and innovation multiplier.
Strategic Segmentation: Where Growth Is Concentrated
The headline figures, while compelling, only tell part of the story. The true strategic value of our analysis lies in its breakdown of the market across multiple dimensions—solution types, end-user verticals, and geographic regions—each revealing distinct demand drivers, competitive intensity, and adoption barriers.
Solution-Level Dynamics
Within the solution landscape, mobile video conferencing and unified messaging represent the largest revenue pools, reflecting the enduring demand for rich, synchronous collaboration and the continued migration of legacy messaging systems to cloud-native platforms. Presence and mobility solutions, while smaller in absolute terms, serve as critical enablers for workforce agility, allowing organizations to maintain context-aware collaboration regardless of device or location. Contact center as a service (CCaaS) and audio conferencing round out the solution mix, with the former experiencing particular momentum as enterprises rebuild customer engagement infrastructures around digital-first, mobile-optimized experiences.
The report does not merely list these categories; it evaluates them. Our analysis examines the pricing dynamics, feature differentiation, integration requirements, and adoption curves that define each solution segment. For procurement leaders, this means being able to identify which capabilities warrant premium investment and which can be sourced from commoditized providers. For product strategists, it means understanding where feature gaps are likely to emerge and where consolidation pressure will intensify.
Vertical-Specific Demand Patterns
No enterprise communication strategy exists in a vacuum. Different industries face different regulatory environments, workforce structures, and customer engagement models, all of which shape their mobile UCC requirements. The IT and telecommunications sector remains the largest consumer of mobile UCC capabilities, driven by internal collaboration needs and the requirement to support customer-facing communication infrastructure. The BFSI sector follows closely, with compliance mandates, secure communication requirements, and the need for seamless omnichannel customer interactions driving significant investment.
Healthcare organizations are increasingly adopting mobile UCC platforms to support telemedicine workflows, clinician collaboration, and patient engagement—all while navigating stringent data protection regulations. Government and public sector entities face their own unique pressures, including the need for sovereign infrastructure, disaster recovery capabilities, and secure inter-agency communication. Retail and manufacturing organizations are leveraging mobile UCC to connect distributed workforces, streamline supply chain coordination, and enhance customer service operations. Educational institutions round out the vertical landscape, with hybrid learning models driving sustained demand for mobile video and messaging capabilities.
Our report provides a detailed examination of each vertical, analyzing not just current spend levels but the underlying drivers, barriers, and growth catalysts that will shape adoption over the forecast period. This vertical lens is essential for organizations seeking to benchmark their own communication strategies against industry peers and for vendors aiming to refine their go-to-market motions.
Geographic Dispersion and Infrastructure Realities
The global nature of this market means that regional dynamics play an outsized role in shaping both demand and competitive intensity. Our analysis segments the market across North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa, revealing how infrastructure maturity, regulatory environments, and enterprise digitization rates influence adoption patterns.
North America and Europe represent mature, high-spend markets where competition is fierce and differentiation increasingly hinges on AI capabilities, ecosystem integration, and regulatory compliance. Asia Pacific presents a high-growth opportunity shaped by rapid enterprise digitization, expanding mobile broadband coverage, and the emergence of local champions alongside global vendors. Latin America and the Middle East and Africa reflect markets in earlier stages of adoption, where infrastructure development—particularly around broadband capacity and mobile network evolution—will determine the pace of UCC deployment.
Decision-makers must be careful not to treat these regions as monolithic. Our report provides the granularity needed to understand the specific demand drivers, competitive dynamics, and infrastructural prerequisites that define each regional market. Organizations operating across multiple geographies will find this analysis invaluable for tailoring their communication strategies to local realities while maintaining global operational coherence.
Competitive Dynamics: Navigating a Consolidating Field
The competitive landscape for mobile UCC is characterized by a mix of established platform giants, specialized UCaaS providers, and infrastructure players seeking to extend their relevance into the collaboration layer. The report includes detailed profiles of the key companies shaping this market, examining their product portfolios, partnership strategies, and recent strategic moves.
Microsoft Corporation continues to leverage its Microsoft 365 ecosystem to embed Teams as a comprehensive mobile UCC platform, with recent feature releases— including the bundling of intelligent recaps and sentiment analysis for premium subscribers—demonstrating the company's commitment to differentiating through AI. Cisco Systems, Inc. maintains a strong position through Webex and Unified Communications Manager, with strategic acquisitions such as Lightico expanding its contact center capabilities into e-signature and document collection workflows. Zoom Video Communications, Inc. remains a formidable force in mobile video and collaboration, with its Zoom Workplace and Zoom Phone offerings continuing to attract enterprises seeking streamlined, high-quality video experiences.
RingCentral, Inc. has positioned its cloud-based RingCentral MVP platform as a comprehensive UCaaS solution, while its recent unveiling of the AIR Pro agentic voice AI platform signals a strategic push into AI-driven customer engagement. 8x8, Inc. offers its XCaaS platform as a unified cloud delivery model spanning communications, contact center, and collaboration, optimized for mobile access. Avaya Inc. and Mitel Networks Corporation continue to serve enterprise and hybrid environments with their respective experience platforms and hybrid UC solutions, each emphasizing continuity and control for organizations navigating mixed deployment models.
Alcatel-Lucent Enterprise, Verizon Communications Inc., Google LLC, NEC Corporation, and Nextiva round out the competitive field, each bringing distinct positioning—from enterprise networking integration and mobile connectivity bundling to workspace collaboration suites and all-in-one UCaaS platforms. The report provides a comparative analysis of these players, evaluating their market share positions, strategic differentiation, and the implications of their recent developments for enterprise buyers.
A critical insight from our competitive analysis is the high level of market concentration. The data indicates that a relatively small number of players command a significant share of total market revenue, with the top three firms accounting for over 44 percent of the market and the top five collectively capturing nearly 60 percent. This concentration has important implications for procurement leverage, vendor risk management, and the pace of innovation. Enterprise buyers must understand how concentration affects pricing dynamics, integration ecosystems, and the likelihood of future consolidation.
Regulatory and Infrastructure Currents Shaping the Market
No analysis of the mobile UCC market would be complete without addressing the regulatory and infrastructural forces that are reshaping the operating environment. In 2024, regulatory reclassification efforts by the FCC regarding broadband Internet access services introduced new complexities, though subsequent legal challenges have created uncertainty about the ultimate regulatory framework. Simultaneously, the transformation of the Disaster Information Reporting System from voluntary to mandatory compliance in 2025 has raised the bar for provider resilience and reporting obligations, with direct implications for UCaaS and mobile communication providers.
On the infrastructure front, network capacity expansions are enabling the multi-gigabit speeds that mobile UCC applications increasingly require. Spectrum expansions, high-split architectures, Distributed Access Architecture deployments, and DOCSIS 4.0 rollouts are all contributing to the broadband foundation that supports seamless mobile collaboration. At the same time, European telecom operators are investing in sovereign infrastructure pathways, including evolution paths for SIP applications, unified communications, and IP Multimedia Subsystem components, in response to data sovereignty and security concerns. These developments are not peripheral—they directly influence the performance, compliance posture, and total cost of ownership of mobile UCC deployments.
The FCC's ongoing efforts to identify and make available mid-band spectrum for mobile broadband and advanced wireless services further underscore the infrastructural dependencies that underpin mobile UCC performance. Our report contextualizes these regulatory and infrastructure developments within the broader market dynamics, helping decision-makers anticipate compliance requirements, assess infrastructure readiness, and evaluate vendor claims about network performance and security.
What the Full Study Delivers: A Roadmap for Informed Decision-Making
The Worldwide Mobile Unified Communications and Collaboration Market study is designed to serve as a comprehensive decision-support instrument for a wide range of stakeholder groups. Technology procurement leaders will find the detailed segmentation analysis essential for aligning license investments with actual usage patterns and vertical-specific requirements. Competitive intelligence teams will benefit from the granular profiling of key players, recent developments tracking, and market concentration metrics that reveal the structural dynamics of the competitive field. Investor and financial analysts will find the historical-to-forecast revenue trajectory, CAGR analysis, and regional breakdowns critical for modeling growth scenarios and assessing market opportunity.
Push-To-Talk Market
Beyond these core analytical components, the report includes actionable strategic recommendations, demand-side survey insights, and scenario-based forecasting that account for varying assumptions about macroeconomic conditions, regulatory outcomes, and technology adoption rates. The study also examines the impact of agentic AI platforms, hybrid deployment models, and sovereign infrastructure requirements on the competitive positioning of major vendors—topics that are rapidly becoming central to enterprise UCC strategy discussions.
Every section of the report is built on primary research, validated supplier data, and rigorous demand modeling. The result is a resource that goes beyond descriptive market sizing to provide the analytical depth required for strategic planning, budget allocation, and competitive positioning.
Why 2026 Demands Deeper Intelligence
As we move deeper into 2026, the window for passive observation of the mobile UCC market has closed. Organizations are making procurement decisions that will shape their communication architecture for years to come. Vendors are executing product roadmaps and acquisition strategies that will determine competitive positioning for the remainder of the decade. Regulatory frameworks are evolving in ways that will affect compliance costs, data handling requirements, and network performance expectations.
In this environment, surface-level market awareness is insufficient. Decision-makers need access to detailed segmentation data, competitive benchmarking, vertical-specific adoption analysis, and forward-looking scenario modeling. They need to understand not just where the market is headed, but why it is headed there, what the key variables are, and how different strategic choices will play out across varying conditions.
Our full study provides this depth. It delivers the granular data, the competitive intelligence, and the strategic framing that executives need to make informed, confident decisions. The summary insights presented here offer a glimpse of the analysis contained within, but the complete picture—complete with detailed segmentation breakdowns, supplier profiles, regional dynamics, and forecast scenarios—awaits those who engage with the full report.
To access the complete Worldwide Mobile Unified Communications and Collaboration Market study, including all segmentation data, competitor profiles, regional analyses, and strategic recommendations, visit our research portal. The full intelligence is available now, and the strategic advantage it provides begins with a single decision to dig deeper.
For detailed analysis of this topic, please visit the official page: Worldwide Mobile Unified Communications and Collaboration Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global AI Infrastructure Market to Hit $1.68T by 2032, 27.14% CAGR
By pmarketresearch, 2026-09-16
Navigating the 2026 AI Infrastructure Supercycle: Strategic Intelligence for Enterprise Decision-Makers
The global artificial intelligence infrastructure market has entered a phase of unprecedented expansion, fundamentally reshaping how enterprises approach technology investment, capital allocation, and competitive positioning. As organizations worldwide race to deploy generative AI workloads, build sovereign cloud capabilities, and optimize inference economics, the need for rigorous, forward-looking market intelligence has never been more critical. Our latest Worldwide Modern AI Infrastructure Market research offers a comprehensive analytical framework designed specifically to guide executive decision-making through the 2026-2032 forecast period.
Worldwide AI GPU Market
The market has demonstrated remarkable momentum over the past five years, with total revenue climbing from $142.8 billion in 2023 to $312.6 billion in 2025. This trajectory reflects not merely cyclical demand but a structural transformation in how computational resources are procured, deployed, and monetized. Looking ahead, the forecast period projects continued acceleration, with market valuation expected to surpass $1 trillion by the end of the decade. The compound annual growth rate of 27.14 percent underscores the intensity of this expansion, yet raw figures alone tell only part of the story. The real strategic challenge lies in understanding the underlying composition of growth, the competitive forces shaping supply dynamics, and the operational constraints that will determine which organizations capture value and which face costly delays.
This research brief serves as an introduction to our full market study. It outlines the analytical architecture of the report, highlights the competitive and regulatory forces currently reshaping the landscape, and demonstrates how executives can translate granular intelligence into actionable capital and procurement strategies. As you review the insights that follow, consider how systematic exposure to these dynamics will influence your organization's infrastructure roadmap, vendor selection criteria, and risk mitigation frameworks.
Market Architecture: Component, Deployment, and Regional Dynamics
A rigorous understanding of the modern AI infrastructure market requires disaggregating revenue flows across three fundamental dimensions: component categories, deployment models, and geographic distribution. Each dimension reveals distinct growth drivers, pricing pressures, and procurement considerations that collectively determine the shape of enterprise investment portfolios.
Within the component landscape, compute hardware dominates the revenue composition, reflecting the relentless demand for accelerator chips, high-performance networking equipment, and specialized data storage systems. Organizations building training clusters or scaling inference endpoints must navigate a complex procurement environment where silicon availability, interconnect bandwidth, and storage throughput intersect with total cost of ownership calculations. High-performance networking has emerged as a critical enabler, as the latency and throughput requirements of distributed AI workloads place unprecedented strain on cluster interconnects. Data storage systems, while representing a smaller share of overall revenue, are experiencing structural growth as enterprises architecting retrieval-augmented generation pipelines and vector databases require low-latency, high-capacity storage layers that can sustain continuous inference operations.
The deployment dimension further clarifies where capital is flowing and where innovation is concentrated. Hyperscale and public cloud environments command the largest share of infrastructure spending, driven by the scale economics of major cloud providers and the flexibility they offer enterprises migrating AI workloads without upfront capital expenditure. Enterprise data centers represent a significant and growing segment, as organizations with sensitive data requirements, regulatory constraints, or existing on-premises investments pursue hybrid architectures that balance performance with data sovereignty. Edge AI infrastructure, while currently the smallest deployment category by revenue, is attracting strategic attention from organizations seeking to reduce inference latency, mitigate cloud egress costs, and deploy AI capabilities in environments where continuous connectivity cannot be guaranteed.
Geographic distribution reveals the uneven pace of infrastructure buildout across global markets. North America continues to anchor a substantial portion of worldwide revenue, supported by concentrated hyperscaler investment, mature semiconductor supply chains, and a dense ecosystem of AI-native startups. Asia Pacific represents the second-largest regional revenue pool, fueled by sovereign AI initiatives, rapidly expanding cloud capacity, and the manufacturing ecosystem that underpins global chip production. Europe, the Middle East and Africa, and Latin America each present distinct adoption profiles shaped by local regulatory frameworks, energy availability, and the maturity of domestic cloud and colocation markets. Our full report maps these regional dynamics in detail, providing the granular context necessary to calibrate market entry strategies, partnership decisions, and localized procurement plans.
Competitive Intensity and Vertical Specialization
The competitive landscape of the modern AI infrastructure market is defined by a small number of dominant players commanding significant market concentration, alongside a growing cohort of specialized firms advancing adjacent layers of the stack. Understanding this structure is essential for executives evaluating supplier risk, negotiating long-term contracts, and anticipating shifts in pricing and availability.
At the foundation of the compute layer, NVIDIA Corporation maintains a commanding position through its integrated portfolio of graphics processing units, networking technologies, and software ecosystems that have become de facto standards for large-scale AI training and inference. The company's product roadmap, including successive generations of accelerator architectures and high-speed interconnect solutions, continues to set performance benchmarks that shape enterprise procurement cycles. Advanced Micro Devices Corporation has carved out a meaningful competitive position through its MI-series accelerators and high-performance computing solutions, offering alternative silicon paths for organizations seeking to diversify their supplier base or optimize workload-specific performance. Intel Corporation continues to advance its AI infrastructure capabilities through accelerator architectures, central processing unit platforms, and specialized inference technologies designed for data center environments.
Networking and interconnect technologies represent another critical competitive frontier. Broadcom Inc. supplies high-speed networking chips, application-specific integrated circuits, and custom silicon that are indispensable for interconnecting GPU clusters at hyperscale. Arista Networks provides high-speed Ethernet switching platforms engineered for ultra-low latency AI cluster interconnects, addressing the stringent networking requirements of distributed training workloads. These suppliers operate at the intersection of performance and reliability, where incremental improvements in throughput or latency can translate into material differences in training time and inference responsiveness.
On the cloud and infrastructure services side, hyperscale providers dominate the deployment landscape. Amazon Web Services delivers AI infrastructure through elastic compute instances, custom accelerator chips, and managed services that streamline model training and deployment. Microsoft Corporation's Azure platform provides extensive GPU capacity, custom silicon investments, and integrated cloud services tailored to enterprise and hyperscale AI workloads. Alphabet Inc.'s Google Cloud Platform leverages custom tensor processing unit accelerators and infrastructure optimized for large-scale training and inference. Oracle Corporation has expanded its cloud infrastructure capacity through significant financing commitments, targeting major AI customers with bare-metal GPU clusters and dedicated cloud services. These hyperscalers collectively represent a defining force in infrastructure economics, influencing pricing, availability, and the pace at which new capabilities reach enterprise customers.
Specialized providers are also reshaping the market. TSMC, as the leading semiconductor foundry, manufactures advanced AI chips and accelerators for multiple industry participants, making it a critical node in the global supply chain. CoreWeave operates as a specialized GPU cloud provider, offering high-density infrastructure clusters optimized for training and inference workloads. Vertiv Holdings Co. delivers power management, thermal management, and liquid cooling solutions that address the intensifying energy and cooling demands of high-density AI data centers. Equinix enables private and hybrid AI infrastructure deployments through global colocation and interconnection services. Cerebras Systems develops wafer-scale accelerators designed for large-scale model training, while Groq focuses on inference-optimized language processing units engineered for high-speed deployment scenarios.
Recent developments underscore the velocity of competitive and strategic activity. In early 2026, four major hyperscalers signaled combined capital expenditure guidance approaching $650-690 billion for the year, concentrated heavily on AI infrastructure and data center expansion. NVIDIA advanced significant investments and GPU supply agreements with leading AI models developers as part of major infrastructure buildouts. Oracle announced plans to raise substantial debt and equity financing in 2026 to expand cloud infrastructure capacity serving prominent AI customers. These capital commitments signal a multi-year construction and procurement cycle that will influence equipment availability, pricing dynamics, and the strategic positioning of infrastructure providers for years to come.
Market Dynamics: Power, Regulation, and Efficiency Imperative
Beyond component architecture and competitive positioning, the modern AI infrastructure market is being reshaped by structural constraints and regulatory developments that carry direct implications for deployment timelines, cost structures, and strategic risk. Executives who internalize these dynamics early will be better positioned to navigate procurement delays, negotiate favorable terms, and align infrastructure plans with evolving compliance requirements.
Power availability has emerged as the most consequential bottleneck for AI data center deployment. Electrical infrastructure constraints, including large power transformers with multi-year lead times and grid interconnection queues that now exceed 2,100 gigawatts, have created a capacity shortfall that threatens to delay a significant portion of planned 2026 capacity into 2028. This reality forces organizations to confront the fact that AI infrastructure planning can no longer be divorced from energy strategy. Executives must evaluate site selection criteria, power procurement contracts, and the potential role of on-site generation or advanced cooling technologies as integral components of infrastructure roadmaps rather than peripheral considerations.
Material intensity further compounds deployment complexity. Each megawatt of AI data center capacity requires approximately 27 tons of copper for wiring and cooling systems, placing additional strain on global supply chains already navigating constraints in power infrastructure components. These material requirements interact with lead times, logistics costs, and geopolitical supply chain risks, creating a procurement environment where early contracting and diversified sourcing strategies can yield meaningful competitive advantage.
Regulatory frameworks are simultaneously reshaping the market landscape. The U.S. Bureau of Industry and Security maintains export controls on advanced computing integrated circuits and, for the first time, on frontier AI model weights exceeding 10 to the 26th power of operations. These controls require licenses for transfers involving potential military-intelligence end uses in designated country groups, introducing compliance complexity for organizations engaged in cross-border collaboration, model sharing, or hardware deployment. Updated export control measures also address advanced computing items and AI model weights with case-by-case licensing provisions for certain shipments, creating a regulatory environment that demands ongoing monitoring and adaptive procurement strategies.
Standardization efforts provide additional context for infrastructure evaluation. The ISO/IEC 30134 series defines key performance indicators for data center resource efficiency, including power usage effectiveness, water usage effectiveness, and carbon usage effectiveness. These metrics are increasingly used to benchmark the energy consumption of AI-driven facilities, influencing procurement criteria, investor expectations, and regulatory scrutiny. Organizations that embed efficiency metrics into their infrastructure planning and vendor evaluation processes will be better positioned to demonstrate operational responsibility and manage long-term operational costs.
Worldwide Modern AI Infrastructure Market
On the innovation frontier, modular and specialized approaches are gaining traction. Recent patent allowances covering canopy-based distributed edge AI data centers with modular GPU cartridges, liquid cooling, and advanced power management illustrate the industry's exploration of alternative deployment architectures capable of scaling to massive GPU counts. These developments signal a broadening of design thinking around how AI infrastructure can be architected for density, efficiency, and flexibility, themes that our full report examines in depth.
What the Full Report Delivers: From Macro Trends to Operational Strategy
The Worldwide Modern AI Infrastructure Market research is structured to translate high-level market intelligence into decision-grade insights. Rather than offering static snapshots, the report integrates historical performance data, forward-looking forecasts, segmentation analysis, and competitive assessment into a cohesive framework that executives can apply directly to capital planning, vendor negotiations, and risk management.
The report begins with a robust market sizing and forecast methodology, anchoring historical revenue data from 2020 through 2025 and extending projections through 2032. This temporal span enables readers to evaluate growth trajectories against multiple scenarios, assess the durability of demand drivers, and calibrate internal forecasts against externally validated market estimates. Revenue projections are presented in a format that supports scenario planning, allowing organizations to model capital allocation under varying assumptions about deployment pace, pricing dynamics, and supply availability.
Segmentation analysis provides the granularity necessary to understand where growth is concentrated and where pricing or availability pressures are most acute. Readers gain visibility into component-level revenue composition, deployment model trends, and regional distribution patterns, enabling targeted evaluation of procurement categories, partnership opportunities, and geographic expansion considerations. The segmentation framework is designed to support cross-functional decision-making, bridging the perspectives of engineering, procurement, finance, and strategy teams.
The competitive analysis section profiles the core companies shaping the market, examining their product portfolios, strategic positioning, recent developments, and implications for enterprise customers. By evaluating supplier capabilities, capital commitments, and competitive dynamics, the report equips readers to assess supplier risk, identify alternative sourcing paths, and anticipate shifts in the supply landscape that may affect procurement timelines or pricing.
Regulatory and operational dynamics are integrated throughout the analysis, ensuring that market projections are contextualized within the constraints that actually govern deployment. Discussions of power availability, grid interconnection queues, material intensity, export controls, and efficiency standards are woven into the market narrative rather than appended as afterthoughts, reflecting the reality that these factors are inseparable from infrastructure strategy.
Strategic Imperatives for 2026 Executive Decision-Making
As organizations navigate the current phase of AI infrastructure expansion, several strategic imperatives emerge from the market evidence. First, capital allocation must be grounded in a clear-eyed assessment of deployment bottlenecks, particularly power availability and grid interconnection timelines, rather than assuming that equipment procurement alone determines project velocity. Early engagement with power providers, proactive site evaluation, and realistic scheduling buffers are essential to avoiding costly delays.
Second, supply chain resilience requires deliberate diversification and long-term contracting where feasible. Given the concentration of market revenue among a small number of dominant suppliers and the intensity of capital expenditure across hyperscale and enterprise buyers, equipment availability and pricing will remain volatile. Organizations that establish clear supplier evaluation criteria, maintain alternative sourcing options, and align procurement timing with realistic deployment schedules will be better insulated against disruptions.
Third, regulatory compliance and efficiency considerations must be embedded into infrastructure planning from the outset. Export control frameworks, model weight restrictions, and efficiency benchmarking standards are evolving rapidly, and organizations that treat these factors as peripheral compliance tasks risk encountering delays, cost overruns, or reputational exposure. Integrating regulatory monitoring and efficiency metrics into infrastructure evaluation processes strengthens both operational resilience and strategic positioning.
Fourth, competitive intelligence should inform partnership and vendor selection decisions. The market is characterized by intense investment activity, product roadmap acceleration, and strategic partnerships that reshape supply dynamics. Organizations that maintain awareness of supplier financing plans, capacity commitments, and technology investments will be better positioned to negotiate favorable terms and align infrastructure choices with long-term strategic objectives.
Conclusion: Turning Market Intelligence into Strategic Advantage
The Worldwide Modern AI Infrastructure Market research is designed to provide the analytical depth, segmentation clarity, and competitive context that executives need to make informed decisions in a rapidly evolving market. The macro trajectory is clear: total market revenue has expanded dramatically over the past two years and is projected to continue its ascent through 2032, driven by sustained demand for compute hardware, high-performance networking, data storage, and diverse deployment models across global regions. Yet the strategic value of this research lies not in confirming that the market is growing, but in illuminating the structural forces, competitive dynamics, and operational constraints that will determine how individual organizations capture value within that growth.
Market concentration among leading suppliers, the intensity of hyperscaler capital expenditure, the persistence of power and grid interconnection bottlenecks, and the evolution of regulatory frameworks collectively create a landscape where disciplined intelligence translates directly into competitive advantage. Organizations that approach infrastructure planning with a clear understanding of these dynamics will be better equipped to sequence investments, negotiate effectively, manage risk, and align technology deployment with broader business objectives.
The full report provides the comprehensive data, segmentation detail, competitive profiles, and forward-looking analysis necessary to support these decisions. We invite you to explore the complete research on our website, where you will find the full forecast tables, regional breakdowns, supplier assessments, and dynamic scenario analysis that underpin the insights summarized here. In a market moving at this pace, timely and rigorous intelligence is not merely an informational asset; it is a strategic necessity.
For detailed analysis of this topic, please visit the official page: Worldwide Modern AI Infrastructure Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Automotive Clamp Market to Hit $5.92B by 2032, 4.6% CAGR
By pmarketresearch, 2026-09-16
Unlocking the Next Wave: Strategic Intelligence for the Global Automotive Clamp Market (2026–2032)
The automotive industry is undergoing one of the most profound structural transformations in its history, driven by electrification, stringent emission standards, and relentless pursuit of lightweight efficiency. Within this complex ecosystem, a seemingly peripheral component—the automotive clamp—plays a critical role in ensuring the integrity, safety, and performance of fluid, airflow, and exhaust systems. As original equipment manufacturers (OEMs) and tier suppliers navigate supply chain recalibrations and material cost volatilities, access to precise, forward-looking market intelligence is no longer optional; it is a strategic imperative.
Our latest comprehensive research report, Worldwide Automotive Clamp Market, equips industry leaders with the analytical depth required to make informed decisions in 2026 and beyond. This article provides a strategic preview of the market trajectory, competitive dynamics, and operational forces shaping the sector, demonstrating why a granular understanding of this market is essential for capital allocation, product development, and regional expansion planning.
The Macro Trajectory: Sustained Growth Anchored by Engineering Evolution
The global automotive clamp market has demonstrated remarkable resilience and steady expansion over the past half-decade. Historical revenue data from 2020 through 2025 reveals consistent upward momentum, with the sector crossing the four-billion-dollar threshold and establishing a robust baseline for future growth. Looking ahead, the forecast period spanning 2026 to 2032 projects a compound annual growth rate of 4.6 percent, reflecting sustained demand across internal combustion, hybrid, and next-generation electric vehicle platforms.
While headline revenue figures provide a useful compass, the true value of our research lies in the underlying structural drivers. Market expansion is not merely a function of vehicle production volumes; it is increasingly dictated by engineering pivots. As automakers transition toward higher-voltage thermal management architectures and adopt advanced exhaust gas recirculation strategies, the specifications demanded of clamping solutions are evolving. Growth is thus bifurcated: traditional volume-driven demand from established platforms continues to anchor baseline revenues, while specialized, high-performance clamping technologies are capturing premium margins in emerging applications. Understanding how these two streams interact—and where capital should be deployed to capture the higher-yield segment—is a central focus of our analysis.
Decoding the Product and Application Landscape
Automotive clamps are far from commoditized fasteners. The market is segmented across multiple product architectures, each engineered to address distinct operational environments. Worm gear clamps remain a cornerstone for general-purpose fluid and cooling line connections, valued for their adjustable torque characteristics and broad OEM acceptance. Spring and constant-tension clamps have gained significant traction in charge-air, turbocharging, and high-vibration environments where maintaining sealing integrity under thermal cycling is paramount. T-bolt and V-band configurations dominate heavy-duty exhaust and high-temperature manifold applications, while ear clamps serve precision fluid routing needs in compact engine bays and electrified thermal loops.
The application matrix further illustrates how clamping requirements are diverging. Engine and powertrain systems continue to represent the largest demand pool, but the rapid proliferation of battery thermal management, inverter cooling circuits, and cabin HVAC integration is reshaping consumption patterns. Exhaust systems remain heavily dependent on high-temperature profile and V-band solutions, particularly as emissions regulations push back-pressure and catalyst efficiency thresholds higher. Even steering, suspension, and braking subsystems—historically niche consumers of clamping hardware—are seeing incremental demand as vehicle architectures integrate more hydraulic and electronic control lines.
Worldwide Automotive Clamp Market
Our report dissects these segments with granular revenue tracking, volume-to-value conversion analysis, and cross-segment substitution trends. Readers will gain clarity on which product families are experiencing margin compression due to standardization, and which specialized geometries are commanding price premiums as OEMs prioritize reliability over lowest-bit cost. We deliberately refrain from publishing exact regional or application-level breakdowns in this preview; those granular matrices are reserved for clients who require precise portfolio alignment and go-to-market targeting.
Competitive Dynamics: A Consolidated Field of Specialized Leaders
The automotive clamp sector is characterized by a moderately concentrated competitive landscape, where scale, engineering heritage, and certification compliance act as formidable barriers to entry. A handful of established manufacturers command roughly half of total industry revenue, leveraging long-standing OEM relationships, globally distributed production footprints, and continuous process automation. Yet the market is far from static. Mid-tier specialists and regional producers continue to carve out defensible niches by focusing on custom torque profiles, rapid prototyping, or high-volume standardized lines for cost-sensitive platforms.
European firms have historically set the benchmark for engineered joining technologies, particularly in worm-drive, constant-tension, and high-temperature profile clamps designed for demanding European powertrain and exhaust architectures. Swiss manufacturers have built reputations around precision pinch and spring band clamps that prioritize vibration resistance and rapid assembly on automated line systems. North American players contribute deep domain expertise across worm gear, T-bolt, and constant-torque solutions, often serving both passenger vehicle and heavy-duty truck segments with modular product families that can be rapidly adapted to fluid, fuel, and exhaust requirements.
In Asia-Pacific and emerging manufacturing hubs, production capabilities have matured significantly. Several Indian and Taiwanese suppliers now export globally, offering standardized worm-drive, T-bolt, and spring-loaded configurations that align with price-sensitive OEM programs without sacrificing baseline durability. Meanwhile, American-owned manufacturing operations in China and specialized stainless-steel coupling producers in the United States are bridging the gap between performance-grade materials and cost-efficient scale.
Recent corporate developments underscore the strategic agility required to compete. One major European manufacturer expanded automated clamp production lines in early 2025, boosting manufacturing capacity by nearly twenty percent to absorb surging demand from updated cooling and exhaust platforms. A prominent North American supplier subsequently widened its global distribution networks, increasing international supply coverage by more than thirty percent and positioning itself to capture cross-border program wins. Simultaneously, a lightweighting-focused product launch in mid-2025 introduced clamps that reduce component weight by approximately fifteen percent, directly addressing OEM targets for mass reduction and improved overall vehicle efficiency.
Our competitive analysis maps these moves against pricing strategies, capacity utilization rates, and regional program win rates, providing a clear picture of who is gaining share, where margin erosion is most acute, and which suppliers are best positioned to benefit from electrification-driven redesign cycles.
Forces Reshaping the Value Chain: Materials, Regulations, and Performance Demands
Three interlocking forces are redefining competitive advantage in the automotive clamp sector. First, raw material economics exert continuous pressure on cost structures. Steel and stainless steel constitute nearly seventy percent of production inputs for automotive clamps, and price volatility in these commodities can inflate manufacturing costs by fifteen to twenty percent in any given cycle. Suppliers that fail to hedge material exposure, optimize scrap rates, or transition efficiently to alternative alloys risk margin erosion, particularly when OEMs push back on price increases during program renegotiations.
Second, regulatory and quality compliance frameworks are becoming increasingly stringent. Automotive clamps must satisfy IATF 16949 quality management standards and, for worm-drive types, meet SAE J1508 specifications to guarantee reliable performance under vibration, pressure fluctuations, and extreme temperature ranges. Non-compliance is not merely a technical risk; it results in program disqualification, warranty exposure, and reputational damage. Suppliers with robust certification portfolios and documented process controls hold a distinct advantage when qualifying for next-generation vehicle platforms.
Third, engineering performance requirements are escalating. Constant-tension and spring-loaded designs are increasingly specified to accommodate thermal expansion and contraction in cooling and charge-air systems, ensuring long-term sealing integrity without overtightening or relaxation. High-temperature profile clamps engineered to withstand component temperatures approaching nine hundred degrees Celsius are becoming essential for modern exhaust and turbocharger architectures. Meanwhile, lightweighting trends are accelerating the adoption of advanced materials and thinner-gauge constructions, enabling overall vehicle weight reduction that directly improves fuel economy in internal combustion platforms and extends driving range in electric vehicles.
These forces do not operate in isolation. A supplier that masters material cost mitigation, maintains rigorous certification compliance, and delivers thermally optimized, lightweight clamping solutions simultaneously will capture disproportionate value in the coming years. Our report quantifies these capability gaps and maps which competitors are best positioned to navigate the intersection of cost, compliance, and performance.
What the Report Delivers: Actionable Intelligence for 2026 Decision-Making
The Worldwide Automotive Clamp Market report is structured to serve as a practical decision-support tool rather than a static data repository. Key deliverables include:
Hose Clamps Market
- Baseline and forecast revenue tracking from 2020 through 2032, with clear delineation of historical performance versus projected trajectories under multiple adoption scenarios.
- Detailed segmentation analysis across product types and end-use applications, highlighting volume-to-value ratios, substitution patterns, and margin characteristics for each category.
- Regional market structure evaluation, identifying where production localization, import dependency, and OEM consolidation are reshaping supply-demand balances.
- Competitive benchmarking of leading manufacturers, including capacity expansion timelines, distribution network growth, product launch cadence, and program-win positioning.
- Value chain mapping that tracks raw material exposure, manufacturing process automation trends, and logistics bottlenecks affecting lead times and cost-to-serve.
- Regulatory and technical compliance checklists, ensuring that strategic planning accounts for IATF 16949, SAE J1508, and evolving thermal and pressure testing requirements.
- Scenario-based strategic recommendations for suppliers, OEMs, and tier-one partners seeking to optimize sourcing strategies, portfolio mix, and regional footprint.
Each section is designed to translate market data into executable strategy. Whether the objective is to evaluate a potential acquisition target, calibrate production capacity for a new clamp geometry, or identify underserved application niches in electrified thermal management, the report provides the evidentiary foundation required to move with confidence.
Why This Intelligence Matters Now
2026 represents a pivotal inflection point. Vehicle architectures are being finalized for production cycles that will extend well into the next decade, and clamping specifications locked in today will dictate cost structures, assembly line efficiency, and long-term reliability outcomes. Organizations that delay strategic planning until program launches are already behind; those that integrate market intelligence into portfolio planning, sourcing negotiations, and R&D prioritization will secure a compounding advantage.
Material volatility, regulatory complexity, and performance escalation are not temporary headwinds; they are structural features of the modern automotive supply chain. The ability to anticipate how these forces will redistribute value across product segments, geographic markets, and competitor portfolios is precisely what separates reactive suppliers from proactive market leaders.
Navigate the Outlook with Precision
The Worldwide Automotive Clamp Market report offers a complete, data-rich map of a sector in transition. From historical baselines and multi-year forecasts to competitive positioning, material economics, and technical compliance requirements, every insight is calibrated for executive decision-making. We have outlined the macro trajectory, the competitive architecture, and the operational forces reshaping the industry; the full report goes further, delivering the precise segment-level revenue matrices, regional growth differentials, and company-specific capability assessments that inform capital allocation and strategic prioritization.
To access the complete dataset, detailed segmentation breakdowns, and proprietary competitive benchmarking, visit the official research page for Worldwide Automotive Clamp Market. Equip your team with the intelligence required to turn market complexity into strategic clarity.
For detailed analysis of this topic, please visit the official page: Worldwide Automotive Clamp Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Reformer Unit Market to Hit $1,383.65M by 2032, 6.95% CAGR
By pmarketresearch, 2026-09-16
Global Reformer Unit Market Outlook 2026: Strategic Intelligence for Industrial Decision Makers
Market Trajectory and Structural Resilience
The Worldwide Reformer Unit Market represents a critical nexus in global industrial infrastructure, underpinning hydrogen generation, ammonia synthesis, methanol production, and oil refining operations. As organizations navigate capital allocation decisions through the late 2020s, understanding the revenue trajectory and structural drivers within this sector has become indispensable. Our latest market research delivers a comprehensive assessment of an industry that expanded from 620.5 Million USD in 2020 to an estimated 864.5 Million USD in 2025, reflecting consistent year-over-year momentum through evolving feedstock landscapes and shifting regulatory environments.
Worldwide Reformer Unit Market
Looking ahead, the forecast horizon spanning 2026 through 2032 projects sustained expansion with a compound annual growth rate of 6.95 percent. This trajectory points toward a market exceeding 1.3 Billion USD by the close of the forecast window. The underlying demand architecture is multifaceted, driven by expanding hydrogen economy initiatives, low-carbon ammonia ventures, and ongoing refinery modernization programs. Critically, this growth narrative is not a simplistic extrapolation of historical volumes. It reflects transformative shifts in reformer technology selection, geographic deployment patterns, and the commercial calculus surrounding decarbonization compliance.
For executives evaluating procurement strategies, capacity expansion plans, or technology licensing partnerships, the distinction between historical performance and forward-looking inflection points carries substantial financial weight. The market's acceleration trajectory is increasingly tied to regulatory timelines, feedstock flexibility requirements, and the competitive positioning of engineering firms that can deliver integrated, low-emission reformer solutions at commercial scale. Our research dissects these variables with granular precision while maintaining the analytical ambiguity necessary for proprietary advantage.
Segmentation Architecture and Demand Concentration
Reformer unit procurement decisions are inherently segmented across type, application, and geographic deployment zones, each carrying distinct technical specifications and commercial implications. The market ecosystem encompasses steam methane reforming configurations, catalytic reforming platforms, and autothermal reformer designs, with procurement volumes and revenue contribution varying across industrial end-uses including hydrogen production, ammonia manufacturing, methanol synthesis, and oil refining operations. Understanding the precise weighting of these segments informs everything from supplier negotiation leverage to long-term technology roadmapping.
Geographic distribution patterns further complicate strategic planning. Industrial development across Asia Pacific, North America, Europe, the Middle East and Africa, and Latin America exhibits divergent pacing driven by localized energy transition mandates, feedstock availability, and infrastructure investment cycles. Buyers operating across multiple jurisdictions must reconcile these regional variances against centralized procurement targets, a complexity that standard industry summaries rarely capture with sufficient operational granularity.
Market concentration metrics offer additional insight into the competitive equilibrium. The industry remains moderately consolidated, with the top three firms commanding significant revenue share and the top five collectively representing a substantial majority of market activity. This concentration shapes pricing dynamics, licensing negotiations, and the strategic behavior of both incumbent technology providers and emerging equipment manufacturers. Organizations seeking to enter supplier relationships or evaluate partnership opportunities must account for the bargaining power embedded within this concentration structure.
Competitive Landscape: Major Players and Strategic Moves
The reformer unit market features a diversified competitive field spanning engineering contractors, technology licensors, catalyst specialists, and high-temperature component manufacturers. Each participant brings distinct capability profiles that influence procurement decisions across different application verticals and project scales.
Linde Engineering has established a formidable footprint through the delivery of over 250 reforming furnaces worldwide, offering top-fired, side-fired, and wall-fired configurations alongside its HYDROPRIME modular cylindrical and skid-mounted solutions. The company's emphasis on heat recovery optimization and low-emission revamps positions it favorably within hydrogen, syngas, ammonia, and methanol applications. Recent activity underscores this strategic direction: in February 2025, Linde Engineering secured a record number of small on-site solutions including hydrogen-related plants driven by decarbonization priorities, and in June 2025, Linde signed a long-term industrial gas supply agreement for a world-scale low-carbon ammonia facility incorporating autothermal reforming.
Honeywell UOP and Axens dominate the catalytic reforming segment, supplying process technologies, catalysts, and modular equipment for refinery reformer units. Honeywell UOP focuses on semi-regenerative and continuous catalytic reforming licensing with high-octane gasoline and aromatics as primary outputs. Axens contributes its Octanizing CCR processes and semi-regenerative solutions, supported by over 130 licenses globally, with integrated offerings spanning gasoline production, aromatics, and residue upgrading. Both firms remain central to refinery modernization strategies as operators seek to balance throughput targets against emissions constraints.
Worldwide Steam Reformers Market
KBR and Technip Energies provide complementary engineering and licensing capabilities across steam methane reforming and autothermal reforming for hydrogen and syngas applications, with Technip Energies also delivering comprehensive EPC services. Johnson Matthey addresses the catalyst layer through its KATALCO series and pre-reforming formulations optimized for ammonia, methanol, hydrogen, and gas-to-liquid production, directly influencing reformer efficiency and operational lifespan.
Component-level suppliers such as MetalTek International and Kubota Corporation supply centrifugally cast reformer tubes, outlet manifolds, and heat-resistant cast steel components designed for extended creep-resistant service life of 10 to 12 years or more in high-temperature and high-pressure environments. Wood plc and Larsen & Toubro Limited round out the competitive field through engineering, consulting, and construction engagements spanning refining and hydrogen production contexts. Topsoe's October 2025 conference presentation on electrifying steam reformers as a sustainable hydrogen pathway signals growing industry focus on next-generation process electrification, reinforcing the competitive imperative around innovation velocity.
Industry Dynamics Shaping 2026 Decision-Making
Several converging forces are reshaping procurement timelines and technology selection criteria across the reformer unit ecosystem. Energy efficiency mandates and decarbonization requirements are accelerating adoption of electrified steam reformer configurations capable of reducing direct flue gas carbon dioxide emissions by substantial margins while improving thermal efficiency in existing ammonia plant installations. Concurrently, stricter greenhouse gas emission regulations and carbon pricing mechanisms are exerting financial pressure on conventional fuel-fired reformer architectures, prompting operators to evaluate electrification pathways and carbon capture integration as viable compliance strategies.
Hydrogen economy initiatives and low-carbon ammonia and hydrogen project pipelines continue to sustain demand for advanced reformer designs characterized by enhanced efficiency metrics and carbon capture compatibility. These project-level drivers interact with macroeconomic variables, particularly raw material cost trajectories. Global steel prices, which serve as the primary input for reformer tubes and pressure vessels, are positioned at or near the bottom of the current price cycle entering 2026, with subdued recovery anticipated through the year and a more meaningful upturn projected from 2027 onward. This cost dynamic carries direct implications for equipment procurement budgets, contract timing, and vendor negotiation leverage.
The interplay between regulatory pressure, technology availability, and input cost cycles creates a decision environment where timing and specificity matter enormously. Organizations that delay evaluation of electrified or hybrid reformer configurations risk exposure to rising compliance costs and potential capacity constraints as supplier order books fill. Conversely, premature commitment without accurate segment-level intelligence can result in suboptimal capital deployment, misaligned technology selection, or unfavorable commercial terms.
Research Methodology and Report Scope
Our Worldwide Reformer Unit Market research is structured to deliver actionable intelligence across multiple decision dimensions. The report integrates quantitative market sizing with qualitative technology and competitive analysis, providing a single reference point for strategic planning teams. Key components include detailed segmentation breakdowns by type, application, and region, with revenue estimates and growth trajectories mapped across the historical 2020 through 2025 period and the forecast 2026 through 2032 window.
The competitive profiling section delivers individualized company assessments encompassing headquarters location, core technology offerings, recent project activity, and strategic positioning within specific reformer sub-markets. These profiles are supplemented by a curated timeline of recent industry developments, capturing conference presentations, project award milestones, long-term supply agreements, and regulatory announcements that signal near-term market direction.
Demand-side analysis examines application-specific drivers across hydrogen, ammonia, methanol, and oil refining verticals, while regional assessments contextualize deployment pacing against localized policy frameworks, infrastructure investment cycles, and feedstock economics. The report further integrates upstream cost dynamics, including steel and alloy material trends, to inform procurement timing strategies and budget forecasting. Market concentration metrics and competitive equilibrium analysis support supplier evaluation and partnership structuring decisions.
Strategic Implications for Corporate Planning
The reformer unit market sits at the intersection of energy transition imperatives, refinery modernization requirements, and industrial gas demand growth. For executives navigating 2026 planning cycles, the strategic question is no longer whether this market will grow, but how the growth will be distributed across technologies, geographies, and supplier ecosystems. Our research provides the depth required to answer that question with confidence.
Organizations evaluating new capacity investments must weigh the technical trade-offs between steam methane, catalytic, and autothermal configurations against localized regulatory timelines and feedstock economics. Procurement teams negotiating with engineering contractors and component suppliers must incorporate steel price cycle projections and concentration-driven pricing dynamics into cost models. Technology strategists assessing electrification and carbon capture integration pathways require precise benchmarks on efficiency gains, emission reduction potential, and commercial availability timelines.
Contact our research team to access the full Worldwide Reformer Unit Market report and secure the granular data, segmentation breakdowns, and competitive intelligence necessary to sharpen your 2026 strategic positioning. The complete dataset, detailed regional and application-level analysis, and extended company profiles are available exclusively through our direct research portal.
For detailed analysis of this topic, please visit the official page: Worldwide Reformer Unit Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com