

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: 2025 Insulinoma Market Hits $166.8M, Projected 5.75% CAGR Through 2032

Navigating the Global Insulinoma Market: Strategic Imperatives for 2026 and Beyond
Market Trajectory and Core Structural Shifts
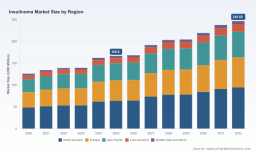
The global insulinoma landscape is entering a decisive phase of structural recalibration, driven by converging forces in clinical innovation, regulatory alignment, and shifting treatment paradigms. Over the historical window of 2020 through 2025, the worldwide insulinoma market expanded from approximately 126.12 million USD to 166.8 million USD, reflecting a compound trajectory shaped by growing diagnostic precision, refined surgical protocols, and incremental pharmacological adoption. Looking ahead to the forecast period spanning 2026 through 2032, the market is projected to continue its measured expansion, anchored by a compound annual growth rate of 5.75 percent and culminating in a total valuation of roughly 246.68 million USD by 2032. These macro-level indicators frame a sector that is simultaneously niche and clinically critical, offering strategic decision-makers a clear window into capital allocation, pipeline prioritization, and go-to-market execution during a period of accelerating therapeutic innovation.
The quantitative progression from 134.11 million USD in 2021 to 162.18 million USD in 2024 underscores an inflection point where clinical research activity, specialized care infrastructure, and targeted investment began converging at practical levels. That momentum carried forward into 2025 and is expected to sustain through 2026, with the market settling around 168.35 million USD before accelerating into the 191.62 million USD range by 2027. For healthcare strategists, pharmaceutical planners, and medical technology executives, this pattern is not merely a financial artifact. It represents a structural narrative: insulinoma management is transitioning from a predominantly surgical and symptomatic intervention model toward an ecosystem where biologic therapies, precision diagnostics, and specialized care pathways increasingly intersect.
Segmentation Dynamics and Operational Realities
Behind the aggregate market figures lies a highly stratified operational environment that demands rigorous segmentation awareness for any enterprise operating within endocrinology, oncology support, or advanced medical devices. The worldwide insulinoma market is organized across multiple interdependent dimensions, each carrying distinct commercial implications, adoption velocities, and operational constraints. Treatment type architectures continue to reflect established clinical hierarchies while simultaneously absorbing emerging modalities, and end-user configurations reveal how care delivery is being reorganized around specialized centers, hospital networks, and diagnostic and research institutions. Regional distributions similarly illustrate how infrastructure maturity, reimbursement frameworks, and clinical trial accessibility influence market penetration patterns.
What makes this segmentation landscape particularly consequential for strategic planning is the uneven pace of innovation across categories. Surgical procedures remain the foundational intervention for localized disease, but the growing recognition of refractory and metastatic subtypes is reshaping how clinicians, investors, and manufacturers position complementary modalities. Pharmacological management, peptide-based approaches, and targeted biologic candidates are steadily expanding the therapeutic arsenal, particularly for patients who cannot undergo resection or who experience persistent hypoglycemia despite conventional management. End-user dynamics further reflect a shift toward institutional specialization, where hospitals continue to function as central treatment nodes, specialty clinics manage complex follow-up pathways, and diagnostic and research centers play an increasingly vital role in case identification, trial recruitment, and biomarker validation.
For corporate strategists, the critical insight is that segmentation performance cannot be interpreted in isolation. Market share, pricing architecture, reimbursement positioning, and clinical adoption are tightly coupled, and misjudging any one dimension can compromise product launch sequencing, partnership selection, and regional prioritization. This is why advanced market intelligence must move beyond headline valuations and examine the structural mechanics that govern how demand materializes across care settings, how value is distributed among treatment modalities, and how regional ecosystems influence time-to-adoption for novel interventions.
Competitive Landscape and the Emerging Therapeutic Frontier
The current competitive environment in the worldwide insulinoma market is characterized by a high degree of clinical concentration, enabling a relatively small cohort of organizations to shape downstream innovation, reimbursement discourse, and physician adoption pathways. Market concentration metrics indicate that a core subset of participants accounts for a disproportionately large share of commercial activity, while broader ecosystem players are increasingly focused on modality-specific innovation, partnership-led development, and precision medicine positioning. This concentration has important strategic implications. It means that competitive intelligence must account not only for revenue footprint but also for intellectual property cadence, clinical trial design, regulatory engagement, and the ability to align with unmet clinical needs in refractory disease populations.
Rezolute, Inc., headquartered in Redwood City, California, exemplifies the type of focused biopharmaceutical entrant that is actively reshaping therapeutic expectations within the rare endocrine oncology space. The company is advancing ersodetug (RZ358), an anti-insulin monoclonal antibody designed for tumor-mediated hyperinsulinism, including malignant insulinoma and refractory hypoglycemia. Its development trajectory has become a central reference point for stakeholders evaluating how biologic interventions might complement or extend beyond current surgical and pharmacological standards.
Recent regulatory developments have elevated the strategic significance of this pipeline. In September 2025, the company announced FDA alignment on a streamlined single-arm, open-label Phase 3 upLIFT trial design for ersodetug in approximately 16 patients with tumor hyperinsulinism. Topline data are expected in the second half of 2026, positioning the trial timeline directly within the early window of this forecast period and making it a closely watched catalyst for both clinical practice and commercial planning. Importantly, regulatory alignment also confirms that positive results from the pivotal sunRIZE Phase 3 trial in congenital hyperinsulinism can serve as supportive or confirmatory evidence for the tumor hyperinsulinism indication. This cross-indication evidentiary strategy could materially influence how development risk, regulatory pathway feasibility, and clinical adoption scenarios are modeled by investors and R&D teams.
From a competitive strategy perspective, these developments illustrate a broader pattern: insulinoma-related innovation is increasingly leveraging rare-disease development efficiency, regulatory consultation, and indication expansion logic. Companies operating in adjacent endocrinology, hypoglycemia management, or oncology-support arenas must therefore monitor not only direct competitors but also clinical trial milestones, regulatory design nuances, and evidence-generation strategies that could redefine treatment standards. The ability to anticipate such shifts is especially valuable in a market where patient populations are limited, clinical adoption depends heavily on specialized expertise, and commercial success is closely tied to reimbursement narratives and physician confidence in novel mechanisms of action.
Epidemiology, Patient Access, and Strategic Positioning
Any credible strategic assessment of the worldwide insulinoma market must account for the epidemiological and clinical constraints that define the addressable opportunity. Insulinomas are estimated to occur at an incidence of roughly one to four cases per million persons per year, with approximately ten to fifteen percent classified as aggressive or metastatic. These figures reinforce the reality that the market is small in absolute patient volume yet highly significant in clinical intensity, economic burden, and therapeutic complexity. The relatively limited incidence means that diagnostic precision, referral pathways, and specialist engagement become decisive factors in both patient outcomes and commercial execution.
The treatment standard similarly shapes strategic assumptions. Surgical resection remains the primary curative option for localized insulinoma, and for inoperable or malignant cases, medical management typically begins with diazoxide as first-line therapy, followed by somatostatin analogs or other interventions for refractory hypoglycemia. Yet a meaningful portion of the patient population does not achieve adequate disease control through existing protocols. Approximately four in ten patients are considered refractory to surgery and medical management including diazoxide, and an estimated 1,500 initially addressable malignant insulinoma patients exist in the United States alone. These numbers are central to planning, because they highlight both the urgency of expanding therapeutic options and the commercial reality that any successful innovation must navigate narrow patient subsets, specialized clinical workflows, and highly scrutinized value propositions.
Strategic positioning in this environment requires disciplined segmentation, realistic forecasting, and an understanding of how clinical evidence translates into adoption. Decision-makers must evaluate how new therapies will integrate into existing care pathways, whether they will reshape referral patterns, and how payers, providers, and research centers will interpret efficacy, safety, and cost-effectiveness. The presence of refractory subpopulations, combined with the rarity of the disease, also means that clinical development strategies and market access plans must be tightly synchronized. Delays, misalignments, or ambiguous evidence packages can materially affect timelines, pricing expectations, and the overall commercial trajectory of an intervention.
Infrastructure, End-User Architecture, and First-Mover Advantages
The delivery of insulinoma-related care is not uniformly distributed across healthcare systems. Instead, it is organized through a layered infrastructure of hospitals, specialty clinics, and diagnostic and research centers, each playing distinct roles in diagnosis, treatment, longitudinal management, and evidence generation. Hospitals continue to anchor procedural capabilities and acute management, while specialty clinics increasingly support complex case coordination and long-term monitoring. Diagnostic and research centers are becoming critical nodes for patient identification, biomarker exploration, trial enrollment, and multidisciplinary consultation.
This end-user architecture matters for strategic planning because it influences how products and services reach the market, how adoption is reinforced, and where commercial value is concentrated. Organizations seeking to enter or expand within this market must determine which care settings offer the most credible pathways to early uptake, which institutional partners can accelerate clinical education, and how reimbursement and procurement dynamics vary across settings. In rare disease markets, the speed and credibility of early clinical endorsement often determine downstream scale. First-mover advantages are therefore not simply about being early; they are about establishing durable relationships with the institutions that define standards of care, support physician decision-making, and validate new therapeutic approaches through real-world use and research activity.
The interplay between clinical concentration, infrastructure distribution, and evidence generation also shapes partnership strategy. Companies may need to align with specialty networks for trial recruitment, collaborate with diagnostic centers for patient identification, or engage hospital-based programs for procedural and translational research. In each case, the objective is to embed commercial initiatives within the operational logic of the care ecosystem rather than treating the market as a uniform endpoint. This approach improves forecasting reliability, reduces adoption friction, and strengthens the credibility of launch planning.
Worldwide Insulinoma Market
Why the 2026 Decision Cycle Demands Precision Intelligence
The 2026 business environment places exceptional pressure on strategic teams to make informed capital, pipeline, and market-entry decisions with limited room for error. In a specialized market like insulinoma, where growth is steady rather than explosive, differentiation depends on understanding structural drivers, anticipating clinical catalysts, and identifying where value is likely to accrue across treatment types, end-user settings, and regional ecosystems. Broad market summaries are insufficient for this task because they do not reveal how demand is distributed, how competitive concentration influences pricing and access, or how regulatory milestones may alter adoption timelines.
This is precisely the type of intelligence gap that our Worldwide Insulinoma Market research is designed to address. The study offers a granular, decision-oriented assessment of the market's historical baseline, forward trajectory, and operational architecture, while deliberately maintaining confidentiality around detailed segment-level figures and proprietary analytics. In practice, this means that executives can rely on the report as a framework for benchmarking assumptions, testing strategic scenarios, and aligning internal planning with market realities, while still being compelled to obtain the complete dataset and analytical models for precise execution.
The strategic value of this approach lies in precision without dilution. For R&D leaders, the report supports assessment of therapeutic positioning, development timelines, and clinical adoption risks. For commercial teams, it informs segmentation planning, channel prioritization, and launch sequencing. For corporate development and investment functions, it clarifies concentration dynamics, competitive exposure, and the likely shape of value creation across the forecast horizon. Rather than offering generic market commentary, the analysis connects epidemiological constraints, treatment standards, regulatory alignment, and infrastructure distribution into a coherent strategic map.
What the Report Delivers and How to Use It
The Worldwide Insulinoma Market report has been structured to function as a working intelligence asset rather than a static overview. It integrates historical performance context, forward-looking market projections, segmentation dynamics, competitive profiles, and industry catalyst tracking into a single decision-support framework. Readers will find detailed coverage of market size evolution from 2020 through the forecast window extending to 2032, alongside analysis of how treatment typologies, end-user configurations, and regional distributions influence commercial behavior and adoption patterns. The report also includes competitive profiling that goes beyond corporate descriptions, examining how developer strategy, trial design, regulatory alignment, and indication expansion shape competitive positioning within a concentrated market.
Importantly, the study emphasizes operational interpretation over raw enumeration. It examines how surgical, pharmacological, targeted, and peptide-based modalities interact within the current care paradigm, how specialized institutions influence early adoption and evidence accumulation, and how rare-disease dynamics shape pricing, reimbursement, and market access logic. This orientation enables users to translate macro-level trends into actionable planning assumptions, such as where to prioritize clinical engagement, how to sequence partnership activity, and which indicators should be monitored to anticipate shifts in competitive intensity or treatment standards.
Because the report is built for strategic application, it also supports scenario planning. Decision-makers can use the analysis to evaluate how changes in regulatory outcomes, trial readouts, or reimbursement environments may affect commercial timelines, market concentration, and relative positioning among incumbents and emerging entrants. In a market where key catalysts are unfolding within the 2026 to 2032 horizon, the ability to model alternative outcomes is a practical necessity rather than an academic exercise.
Conclusion: Strategic Certainty in a Specialized Market
The worldwide insulinoma market is not defined by scale alone, but by the precision with which organizations can interpret clinical need, regulatory evolution, competitive concentration, and infrastructure dynamics. The historical growth observed between 2020 and 2025, combined with the projected trajectory through 2032, confirms that this is a market where disciplined insight can create meaningful strategic advantage. For companies operating in endocrinology, oncology support, medical technology, or specialized care delivery, the ability to read segmentation behavior, anticipate catalyst impacts, and navigate concentrated competitive structures will increasingly differentiate successful strategies from reactive ones.
Our Worldwide Insulinoma Market research is designed to provide that advantage. It offers the analytical rigor, structural clarity, and market-specific intelligence required to make high-stakes decisions with greater confidence, while preserving the detailed quantitative and proprietary elements that underscore its value. For executives who need a complete, decision-ready intelligence foundation, we invite you to access the full report and obtain the comprehensive data, segmentation detail, and competitive analysis necessary to translate strategic vision into executable planning for 2026 and the years ahead.
Lumpectomy Market
For detailed analysis of this topic, please visit the official page: Worldwide Insulinoma Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com