

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Report: Worldwide Digital Dermatoscope Market Hits $1.16B in 2025, Projects 9.2% CAGR to 2032

Unlocking Market Intelligence: Strategic Insights into the Worldwide Digital Dermatoscope Market
The global healthcare technology landscape is undergoing a profound transformation, driven by an aging population, rising prevalence of skin cancer, and the rapid integration of artificial intelligence into diagnostic workflows. Within this ecosystem, digital dermatoscopy stands out as a critical frontier, bridging the gap between traditional clinical examination and advanced digital health solutions. As we move deeper into the mid-2020s, understanding the trajectory of this market is no longer optional for stakeholders; it is a strategic imperative.
This article serves as a strategic preview to our latest comprehensive study, the Worldwide Digital Dermatoscope Market Research. Our objective is to outline the macroeconomic forces shaping the industry, highlight the competitive dynamics at play, and demonstrate why access to granular, data-backed intelligence is essential for informed decision-making in 2026 and beyond. True mastery of this landscape requires a compass grounded in precise data, which our full report provides in detail.
Market Trajectory and Growth Dynamics
The digital dermatoscope sector has demonstrated remarkable resilience and expansion over the past half-decade. Our historical analysis from 2020 through 2025 reveals a consistent upward trend in market valuation, reflecting the accelerated adoption of digital imaging tools in clinical settings. Building on this momentum, the forecast period from 2026 to 2032 projects sustained growth, with the market expected to reach new valuation milestones by the end of the decade.
Worldwide Digital Dermatoscope Market
Central to our forecast is a robust Compound Annual Growth Rate (CAGR), indicating that the industry will continue to expand at a pace well above many mature medical device categories. This growth is underpinned by several structural drivers: the increasing demand for non-invasive diagnostic procedures, the rollout of telemedicine infrastructure that relies on high-quality digital imaging, and the growing homogenization of healthcare standards across emerging markets. However, growth is not uniform across all vectors, and understanding where value is being created requires a nuanced view of product types, end-user segments, and geographic penetration.
Our full analysis dissects these trends, offering stakeholders a clear view of the total addressable market. The data indicates that while the overall market size is expanding significantly, the distribution of revenue across different segments varies considerably based on regulatory environments, reimbursement policies, and technological maturity. For investors and product leaders, identifying the high-growth pockets within this broader expansion is key to capitalizing on the opportunity.
Dermatoscope Market
Segmentation and Value Chains
To navigate this market effectively, one must look beyond aggregate numbers. The Worldwide Digital Dermatoscope Market is segmented across multiple dimensions, each presenting distinct strategic considerations. On the product front, the ecosystem is divided between portable handheld devices and integrated imaging systems. Each category serves different clinical needs, price points, and workflow requirements. Handheld units often appeal to practitioners seeking flexibility and ease of deployment, while integrated systems are favored by large-scale clinics and hospitals requiring comprehensive data management and total body mapping capabilities.
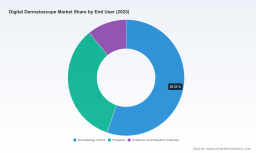
End-user segmentation further illuminates where demand is concentrated. Dermatology clinics represent a primary hub for adoption, driven by the need for efficient lesion tracking and patient monitoring. Hospitals and academic research institutes also form significant pillars of demand, often driven by complex case management and the integration of dermoscopy into broader diagnostic protocols. Understanding the specific revenue contributions and growth rates within these segments allows companies to tailor their go-to-market strategies with precision.
Regionally, the market presents a diverse landscape. North America and Europe have historically commanded the largest shares of revenue, supported by well-established healthcare reimbursement frameworks and high awareness of skin cancer screening. Meanwhile, the Asia Pacific region is emerging as a critical growth engine, fueled by expanding healthcare access and increasing investment in medical technology infrastructure. Latin America and the Middle East and Africa, while currently smaller in absolute terms, offer untapped potential as digital health initiatives gain traction. Our report provides a detailed breakdown of these regional dynamics, enabling stakeholders to prioritize markets that align with their risk appetite and strategic goals.
Competitive Landscape and Innovation Waves
The competitive environment in the digital dermatoscope market is characterized by a mix of established medical device manufacturers and specialized technology firms. Market concentration is notable, with a core group of players holding a significant portion of industry revenue. Understanding the positioning, technological differentiators, and strategic moves of these key players is vital for benchmarking and identifying partnership or acquisition opportunities.
Leading manufacturers such as Heine Optotechnik and DermLite continue to drive product innovation, focusing on enhanced imaging quality, user ergonomics, and connectivity features. Heine Optotechnik's DELTA series, for instance, has been widely recognized for its precision and AI integration capabilities aimed at melanoma detection. Similarly, DermLite has maintained a strong presence with its DL series, leveraging polarized and non-polarized light modes alongside robust connectivity solutions that support teledermatology workflows.
Complementing these device manufacturers are companies offering sophisticated software and integrated platforms. FotoFinder Systems has carved a significant niche with its Moleanalyzer and Medicam offerings, emphasizing AI-based lesion analysis and total body mapping. Recent developments, such as the launch of enhanced AI algorithms, underscore the industry's shift toward data-driven diagnostics. Canfield Scientific also contributes to this landscape with its DermaGraph and IntelliStudio systems, integrated with vision software for comprehensive dermatological imaging and tracking. Smaller yet agile players like Dinolite and AnMo Electronics Corporation provide portable and wireless solutions, often targeting cost-sensitive segments or specific clinical use cases with features like high-megapixel sensors and adjustable magnification.
The pace of innovation is rapid, and recent activity illustrates the intensity of competition. Product launches, certification updates, and strategic appearances at major medical conferences are frequent signals of market evolution. These events often signal shifts in regulatory compliance, feature sets, or market entry strategies. Our full report catalogs these developments, providing a timeline of key milestones that stakeholders can use to anticipate competitive moves and align their own roadmaps.
Regulatory, Reimbursement, and Operational Dynamics
Beyond technology and competition, the market is heavily influenced by regulatory frameworks and reimbursement policies. Compliance with medical electrical equipment safety standards, such as IEC 60601-1, is a non-negotiable requirement for manufacturers seeking to operate in major healthcare markets. Adherence to these standards not only ensures patient protection but also serves as a barrier to entry for less established players, consolidating the position of incumbents.
Reimbursement dynamics further shape market accessibility. In the United States, for example, specific CPT codes cover dermoscopy procedures using digital devices in outpatient settings. The availability and clarity of such codes directly impact the adoption rate of digital dermoscopes, as they influence the economic viability for healthcare providers. Changes in reimbursement landscapes can accelerate or decelerate demand, making it essential for stakeholders to monitor policy updates closely.
On the operational side, manufacturing costs remain a critical consideration. Medical-grade optics and LED components constitute a substantial portion of production expenses. Fluctuations in the availability or pricing of these components can affect margins and pricing strategies. Companies with strong supply chain management and vertical integration capabilities are better positioned to navigate these cost pressures while maintaining competitive pricing.
Strategic Imperatives for 2026
As we look toward 2026, several strategic imperatives emerge for participants in the digital dermatoscope market. First, differentiation through technology remains paramount. The integration of AI algorithms for lesion analysis, enhanced connectivity for telehealth, and ergonomic improvements are no longer optional features; they are baseline expectations. Companies that can innovate faster and more effectively will capture greater market share.
Second, market expansion requires a targeted approach. Given the varying maturity levels across regions and segments, a one-size-fits-all strategy is unlikely to succeed. Stakeholders must assess local regulatory requirements, reimbursement environments, and clinical workflows to tailor their offerings. In emerging markets, affordability and ease of use may take precedence, while in established markets, advanced features and integration with existing health IT systems may drive purchasing decisions.
Third, partnerships and ecosystem building are increasingly important. Collaboration with academic institutions, dermatology associations, and technology providers can accelerate R&D, validate clinical efficacy, and expand distribution networks. Additionally, as data becomes central to dermatological care, companies must address data privacy, security, and interoperability concerns to build trust with healthcare providers and patients.
Conclusion
The Worldwide Digital Dermatoscope Market represents a dynamic and growing opportunity at the intersection of healthcare, technology, and patient care. The trajectory from 2020 through 2032 points to sustained expansion, driven by technological innovation, demographic shifts, and evolving clinical standards. However, capturing value in this market requires more than a surface-level understanding. It demands deep, data-driven insights into segmentation, competition, regulatory frameworks, and regional nuances.
Our comprehensive research study provides exactly that depth. From granular revenue splits across product types, end users, and regions to detailed competitor profiles and recent industry developments, the report offers a complete intelligence package for strategic planning. It enables stakeholders to benchmark performance, identify high-growth opportunities, assess competitive threats, and formulate robust market entry or expansion strategies.
For investors, manufacturers, and healthcare providers aiming to make informed decisions in 2026 and beyond, the full report is an indispensable resource. It transforms complex market data into actionable intelligence, empowering you to navigate the digital dermatoscope landscape with confidence. We invite you to explore the complete analysis and unlock the full strategic value of this evolving market.
For detailed analysis of this topic, please visit the official page: Worldwide Digital Dermatoscope Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com