

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Category: market research
PW Consulting: Armodafinil Market to Hit $647.62M by 2032, Driven by 4.52% CAGR and North America
By pmarketresearch, 2026-09-17
Strategic Imperatives in the Global Armodafinil Market: Navigating Growth, Regulation, and Competitive Shifts Through 2032
The worldwide armodafinil market stands at a critical inflection point as it enters the 2026–2032 forecast horizon. For pharmaceutical executives, investors, and healthcare supply chain strategists, understanding the forces shaping this wakefulness-promoting agent’s commercial trajectory is no longer optional. PW Consulting’s latest Worldwide Armodafinil Market research report delivers a comprehensive, forward-looking intelligence framework designed to support evidence-based decision-making across R&D, commercialization, and market access functions. With rigorous historical tracking from 2020 through 2025 and a structured outlook extending to 2032, this study provides the analytical depth required to anticipate demand shifts, regulatory bottlenecks, and competitive repositioning in a space where intellectual property transitions and controlled-substance oversight intersect.
Market Evolution and the Strategic Relevance of Macro Forecasts
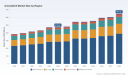
Armodafinil has established itself as a cornerstone therapy for excessive daytime sleepiness across multiple sleep-related indications, driven by clinical adoption in narcolepsy, obstructive sleep apnea, and shift work sleep disorder. Over the historical window from 2020 to 2025, the market demonstrated consistent top-line expansion, with global revenue progressing from 385.2 USD Million in 2020 to 475.25 USD Million in 2025. This trajectory reflects sustained prescription volumes alongside the gradual maturation of generic supply networks. Looking ahead, the compound annual growth rate is projected at 4.52 percent across the 2026–2032 forecast period, signaling a steady but measured expansion phase rather than a speculative surge. By 2032, aggregate market size is expected to reach 647.62 USD Million.
For corporate strategy teams, these headline figures are only the starting point. The real value lies in how growth compounds across dosage strengths, therapeutic indications, and regional distribution channels, and how structural constraints such as controlled-substance manufacturing quotas modulate supply reliability. Our analysis contextualizes the 4.52 percent CAGR within a regulatory and competitive environment where pricing pressure, generic substitution dynamics, and DEA quota cycles interact to shape realizable market share. Decision-makers relying on static sizing alone risk misallocating commercial resources; this report translates macro growth into actionable scenario planning.
Report Architecture: Translating Data into Execution-Ready Intelligence
The Worldwide Armodafinil Market report is structured to move beyond descriptive market sizing and into operational guidance. Each analytical module is designed to answer specific executive questions:
- Comprehensive historical and forecast revenue modeling that isolates baseline demand trends from one-off regulatory or supply disruptions
- Segment-level breakdowns across indications, dosage strengths, and geographic markets, with attention to adoption velocity and substitution patterns rather than surface-level share figures
- Competitive profiling of originator and generic manufacturers, mapping product portfolios, approval statuses, API sourcing strategies, and recent rights acquisitions
- Regulatory and supply chain risk assessment covering controlled-substance scheduling, DEA quota mechanics, and documented availability patterns observed in early 2026
- Strategic recommendations for market entry, portfolio expansion, generic positioning, and supply chain resilience in a quota-constrained manufacturing environment
By embedding quantitative forecasts within qualitative operational context, the report equips stakeholders to evaluate not just how large the market may become, but how value will be captured under differing competitive and regulatory conditions.
Competitive Landscape: Originator Positioning, Generic Acceleration, and Strategic Consolidation
The competitive architecture of the armodafinil market has undergone material shifts as foundational patents expired in 2024, opening the door to expanded multisource generic competition. Teva Pharmaceutical Industries Ltd., operating through its legacy Cephalon subsidiary, remains the originator of Nuvigil and continues to supply both the reference listed drug and generic formulations worldwide. Its enduring presence anchors a market where branded heritage and generic scale coexist, particularly in narcolepsy and obstructive sleep apnea segments where clinical familiarity drives prescriber behavior.
A defining strategic move in early 2025 came from Apotex Inc., via its Nuvo Pharmaceuticals affiliate. In January and February 2025, the company finalized the acquisition of U.S. marketing rights to branded NUVIGIL, integrating the asset into Apotex’s diversified portfolio. This consolidation of branded rights alongside existing generic capabilities positions Apotex to navigate both premium and value-oriented channels, a dual-strategy posture that is increasingly relevant as payers and formularies seek flexibility in wakefulness-promoting therapies.
The generic supply side is heavily anchored by Indian pharmaceutical manufacturers with FDA-approved facilities and active API-to-finished-dosage capabilities. Lupin Ltd., Natco Pharma Ltd., and Aurobindo Pharma Ltd. each maintain approved armodafinil tablet lines across multiple strengths and serve as critical nodes in global distribution. Mylan Pharms Inc., now operating under Viatris, contributes a long-standing U.S. and international generic supply footprint. Collectively, these players reinforce a market structure in which concentration is meaningful but not absolute, with the top three and top five players holding substantial combined share. This concentration shapes pricing negotiations, tender competitiveness, and supply continuity expectations.
Worldwide Armodafinil Market
API sourcing represents an equally important layer of the competitive picture. Producers such as Acura Labs, Unimark Remedies Ltd., HRV Pharma, and Wellona Pharma provide GMP-compliant armodafinil API with full documentation support for global finished-product manufacturers. The availability of qualified API sources has enabled rapid scale-up following patent expiry, but it also means that supply chain resilience depends on the reliability of quota-adjusted production planning and the ability of API suppliers to align output with DEA semi-annual allocation cycles.
Regulatory and Supply Chain Dynamics: The Quota Constraint as a Strategic Variable
Armodafinil’s classification as a Schedule IV controlled substance in the United States introduces structural complexity that extends well beyond routine pharmaceutical compliance. The DEA manufacturing quota system imposes production limits and licensing requirements that directly affect annual output volumes. Implementation of semi-annual quota allocations since 2023 has introduced timing challenges for manufacturers, requiring closer coordination between API procurement, finished-dose production scheduling, and distribution logistics.
While armodafinil is not listed on official FDA or ASHP drug shortage databases as of early 2026, patient and channel reports of intermittent availability issues persist. These disruptions are typically attributable to the interaction of quota constraints, manufacturing concentration, and demand variability rather than a single systemic failure. For market participants, this environment rewards proactive capacity planning, diversified supplier relationships, and scenario-based inventory strategies. Companies that treat quota cycles as a fixed background condition rather than a manageable variable risk exposing their commercial timelines to avoidable volatility.
Why 2026 Decision-Makers Need This Research Now
The 2026 landscape demands a more granular understanding of how growth, regulation, and competition interact. With patent expiry already enabling broader generic participation and branded rights consolidating under new ownership, the window for strategic positioning is active. Simultaneously, controlled-substance oversight continues to influence production cadence, making supply-side intelligence as important as demand forecasting. PW Consulting’s report is built to support:
Vinpocetine Market
- Portfolio and launch planning that accounts for dosage strength preferences and indication-specific adoption curves
- Competitive response strategies in a market where originator presence, branded rights acquisition, and generic scale are all in flux
- Risk-adjusted supply planning that incorporates DEA quota timing and API sourcing redundancy
- Market access and pricing considerations shaped by concentration dynamics and regional demand distribution
Rather than presenting isolated statistics, the study integrates segmentation context, corporate profiles, regulatory mechanisms, and recent proprietary developments into a unified strategic narrative. This allows executives to evaluate opportunity sizing alongside execution risk, a distinction that separates reactive market participation from deliberate value capture.
Conclusion: From Market Awareness to Strategic Advantage
The worldwide armodafinil market is entering a phase where steady growth coexists with evolving competitive ownership and persistent regulatory constraints. The projected expansion from 482.41 USD Million in 2026 toward 647.62 USD Million by 2032 reflects a market that is maturing, not saturating, and where share dynamics will be determined by execution quality as much as by underlying demand. PW Consulting’s Worldwide Armodafinil Market research provides the structured intelligence needed to navigate this environment with confidence. For leaders seeking detailed segmentation analysis, competitive benchmarking, regulatory scenario modeling, and region-specific demand context, the full report offers the complete evidence base required to translate market insight into operational advantage.
For detailed analysis of this topic, please visit the official page: Worldwide Armodafinil Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: SMA Market Hits $163.1M in 2025, Projected 5.48% CAGR Through 2032
By pmarketresearch, 2026-09-16
Strategic Horizons in the Global Stearyl Methacrylate Market: A 2026 Executive Briefing
The global specialty chemicals sector continues to demonstrate remarkable resilience and adaptability, with niche intermediates playing increasingly critical roles in downstream performance formulations. Among these, Stearyl Methacrylate (SMA) has emerged as a vital functional monomer bridging the gap between polymer science and industrial application. As we move further into the mid-2020s, executives and strategic planners across coatings, lubricant, and personal care industries require a precise, data-backed understanding of market trajectories to navigate supply chain complexities, pricing volatility, and shifting regulatory landscapes.
This article serves as a strategic preview of our latest comprehensive research initiative: the Worldwide Stearyl Methacrylate (SMA) Market study. Drawing on extensive historical analysis and forward-looking modeling, this report is designed to empower decision-makers with the intelligence necessary to capitalize on growth opportunities from 2026 through 2032. Below, we explore the macro-economic foundations, competitive architectures, and operational dynamics that define this evolving landscape, offering a compelling case for why deep-dive intelligence is indispensable for your next strategic move.
Styrene-Maleic Anhydride Copolymer Market
Market Trajectory: A Decade of Resilient Expansion
Understanding the historical baseline and future velocity of the SMA market is fundamental to capacity planning and investment allocation. Our analysis tracks a robust growth curve that underscores the material's entrenched position across multiple high-value sectors. From a market valuation in the early 2020s, the global Stearyl Methacrylate market has demonstrated consistent upward momentum, driven by steady industrial demand and the ongoing innovation in polymer-modified formulations.
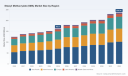
Looking at the macro data, the market closed the base year of 2025 at approximately 163.1 million USD. This figure represents the culmination of a steady historical climb from 2020 onwards, reflecting the sector's ability to maintain demand even amidst global macroeconomic headwinds. More critically, the forecast period projects a sustained compound annual growth rate (CAGR) of 5.48 percent from 2026 to 2032. By the end of this forecast window, the market is anticipated to approach a valuation nearing 237 million USD.
Such growth is not merely linear expansion; it signals structural intensification. The mid-to-late 2020s forecast indicates a phase where demand creation begins to outpace basic replacement cycles, fueled by advanced applications in high-performance lubricants and next-generation personal care formulations. Recognizing these inflection points is vital for stakeholders aiming to align their production capacities, inventory strategies, and R&D investments with market realities. Our report dissects these temporal shifts, providing a granular timeline that highlights when specific growth accelerants are expected to materialize across the value chain.
Application Dynamics: The Multifaceted Demand Engine
Stearyl Methacrylate is not a commodity chemical; its value lies in its functional versatility. The demand landscape is shaped by several key application verticals, each with distinct consumption patterns, pricing sensitivities, and technical requirements. Lubricant additives represent a dominant force within the market, where SMA functions as a critical component in viscosity index improvers and pour point depressants for paraffinic oils. As the automotive and industrial machinery sectors push toward longer drain intervals and improved fuel efficiency, the reliance on advanced polymeric additives continues to deepen.
Parallel to the industrial sector, the personal care and cosmetics industry leverages the emollient and film-forming properties of SMA. The shift toward high-performance, aesthetically pleasing skincare and haircare formulations has sustained demand in this segment, particularly in premium product lines where texture and stability are paramount. Furthermore, applications in adhesives, sealants, and coatings showcase the monomer's ability to enhance adhesion, durability, and chemical resistance, making it indispensable in construction, packaging, and protective coating formulations.
Our market study goes beyond mere application identification. It maps the interplay between these sectors, analyzing how fluctuations in one vertical—such as a surge in automotive lubricant demand—can ripple through supply allocations and pricing structures for others. By understanding the relative weight and growth trajectories of these application verticals, companies can better predict where demand spikes will occur and how to prioritize their customer engagement and product development pipelines. The report provides a systematic breakdown of these application dynamics, revealing which segments are poised for the most significant volume shifts and value creation over the coming years.
Geographic & Segment Dimensions: Unpacking Regional Strengths
Geography remains a decisive factor in market strategy, influencing everything from raw material sourcing to competitive positioning. The Asia Pacific region stands out as a formidable hub of consumption and production, reflecting the broader shift of global manufacturing and chemical processing capabilities toward this highly industrialized zone. North America and Europe continue to hold substantial market footprints, driven by mature industrial bases, stringent quality standards, and steady demand in specialty coatings and personal care sectors.
In addition to regional consumption patterns, purity specifications play a critical role in market segmentation. The market is broadly divided between standard purity grades, which cater to volume-driven industrial applications, and high-purity variants that serve niche, high-performance requirements where impurity thresholds are strictly controlled. The balance between these purity tiers is not static; it evolves alongside technological advancements in synthesis and downstream processing capabilities. Companies that fail to appreciate the nuance between standard and high-purity demand risk misalignment in their product portfolios and pricing strategies.
This research deliverable includes a detailed geographic and segment analysis that maps these regional and purity-based dimensions. It illuminates where the highest concentration of value is generated, how regional supply-demand balances interact, and what strategic implications arise from shifting production footprints. For executives evaluating potential market entry, diversification, or capacity expansion, this geographic and segment intelligence is a cornerstone of risk mitigation and opportunity capture.
Competitive Landscape: Key Players and Strategic Positioning
The Stearyl Methacrylate market exhibits a moderately concentrated structure, with a select group of global specialty chemical manufacturers commanding significant market share. Our analysis highlights a competitive environment where established players leverage integrated production capabilities, global distribution networks, and deep technical expertise to maintain their positions. Key companies profiled in our research include industry giants such as BASF SE, headquartered in Ludwigshafen, Germany, which offers specialized SMA grades such as SMA 1618 and SMA 1618 F, utilized across coatings, oil additives as flow improvers and pour point depressants, and as feedstock for chemical syntheses.
From the Asian market, Mitsubishi Gas Chemical Company, Inc. and NOF Corporation stand as pivotal suppliers. Mitsubishi Gas Chemical produces and supplies SMA for applications encompassing fiber treatment agents, coating compounds, and adhesive compounds, reflecting a broad application portfolio. NOF Corporation lists and supplies stearyl methacrylate as part of its comprehensive functional monomers and oleo & specialty chemicals portfolio, underscoring its strategic integration within a wider high-performance chemicals ecosystem. Additionally, Jamorin International, operating globally with headquarters in Luxembourg, supplies SMA 1618 F specifically tailored for oil additives, functioning as a viscosity index improver and pour point depressant for paraffinic oils.
The competitive dynamics are further shaped by market concentration metrics, indicating that a relatively small number of firms control a substantial portion of the market revenue. This concentration suggests that competitive responses to price changes, capacity adjustments, or technological innovations can have amplified effects across the entire supply chain. Our report provides a deep-dive competitive analysis, examining the strategic profiles of these key players, their product diversification strategies, and their positioning relative to market segments. By understanding the strengths, vulnerabilities, and potential moves of these incumbents, new entrants and existing participants can craft more effective competitive strategies.
Raw Material Dynamics & Supply Chain Resilience
Any robust market analysis must account for the upstream factors that influence production costs and supply stability. Stearyl Methacrylate is produced via the esterification of methacrylic acid with stearyl alcohol, also known as octadecan-1-ol. This means that the availability, pricing, and quality of stearyl alcohol are primary drivers of SMA production economics. Stearyl alcohol itself is a key upstream fatty alcohol feedstock, derived from either natural oils or petrochemical sources, introducing a degree of volatility tied to agricultural commodity markets and energy pricing.
Historically, variations in raw material supply have impacted production schedules and margin structures for manufacturers. The synthesis process requires precise control over reaction conditions and purification steps to meet the purity specifications demanded by downstream customers. Consequently, supply chain resilience depends not only on securing reliable sources of methacrylic acid and stearyl alcohol but also on maintaining robust processing infrastructure capable of handling both standard and high-purity production runs.
Our market study integrates a thorough examination of these raw material dynamics. It explores the historical context of feedstock availability, the interplay between natural and synthetic sourcing routes, and the implications of input cost fluctuations for end-market pricing. For procurement teams, operations managers, and strategic planners, understanding these upstream linkages is essential for building cost models that withstand volatility and for negotiating contracts that hedge against supply disruptions.
Strategic Imperatives for 2026 and Beyond
As we step into 2026, the Stearyl Methacrylate market presents a confluence of opportunities and challenges that demand proactive strategic planning. The projected growth trajectory suggests that demand will continue to outpace simple population or GDP growth, pointing to genuine value creation in high-performance applications. However, realizing this growth requires companies to navigate a complex environment characterized by regional supply-demand imbalances, evolving purity requirements, and an increasingly sophisticated competitive landscape.
Strategic decisions in the coming year must be grounded in precise intelligence. Whether an organization is considering capacity expansion, product line optimization, geographic market entry, or vertical integration, the ability to quantify opportunity and assess risk is paramount. This includes evaluating how shifts in lubricant formulation standards, cosmetic ingredient trends, or adhesive performance requirements will reshape demand profiles. It also involves anticipating how major market players might adjust their inventories, pricing, or M&A activities in response to macroeconomic signals.
The findings contained in our Worldwide Stearyl Methacrylate Market research are structured to support these high-stakes decisions. By combining historical data, forward-looking forecasts, competitive profiling, and application-specific insights, the report provides a 360-degree view of the market. It enables stakeholders to move beyond anecdotal assessments and base their strategies on rigorous, validated analysis.
For executives and analysts seeking to secure a competitive edge, the depth of information available in this comprehensive market study is indispensable. To explore the full suite of data, detailed regional breakdowns, segment-specific projections, and an exhaustive competitive intelligence dossier, we invite you to access the complete research deliverable. The full report offers the granular detail and actionable insights necessary to translate market understanding into tangible business growth.
Worldwide Stearyl Methacrylate (SMA) Market
For detailed analysis of this topic, please visit the official page: Worldwide Stearyl Methacrylate (SMA) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Industrial Diaphragm Pump Market Hits $6.86B in 2025, Projected 5.15% CAGR to 2032
By pmarketresearch, 2026-09-16
Strategic Intelligence for 2026: Navigating the Worldwide Industrial Diaphragm Pump Market
As industrial operations grow increasingly complex, the demand for reliable, efficient, and compliant fluid handling solutions has never been more critical. The global industrial diaphragm pump market stands at a pivotal juncture, shaped by evolving regulatory frameworks, raw material volatility, and a decisive shift toward energy-efficient and digitally integrated pumping technologies. For executives, procurement leaders, and strategy teams operating in 2026, understanding the structural forces driving this market is no longer optional—it is a prerequisite for competitive positioning, supply chain resilience, and long-term capital allocation.
This strategic overview introduces our latest comprehensive research on the Worldwide Industrial Diaphragm Pump Market, a publication designed to translate macroeconomic trajectories, competitive dynamics, and technology adoption patterns into actionable intelligence. Rather than offering static snapshots, the study maps the market from its 2020 baseline through a detailed forecast horizon extending to 2032, providing decision-makers with a forward-looking lens calibrated for real-world operational planning.
Market Trajectory & Structural Growth Drivers
The industrial diaphragm pump sector has demonstrated consistent expansion over the past half-decade, supported by sustained capital expenditure in water infrastructure, chemical processing, and pharmaceutical manufacturing. Historical data reveals a market that has steadily scaled from 2020 through 2025, culminating in a base-year valuation of USD 6,860.68 million in 2025. This momentum carries forward into the forecast period, with the market projected to reach USD 7,379.6 million in 2026 and continue its upward trajectory toward a 2032 valuation of USD 9,750.61 million.
At the heart of this growth lies a compound annual growth rate of 5.15 percent across the 2026 to 2032 forecast window. This moderate yet persistent expansion reflects a maturing industrial landscape where demand is increasingly driven by replacement cycles, regulatory compliance upgrades, and the gradual electrification of fluid handling systems. Rather than experiencing explosive, disruption-led spikes, the market is characterized by steady volume growth, incremental technological refinement, and a competitive environment that rewards operational efficiency and material innovation.
Several overarching dynamics are reinforcing this trajectory. Stricter environmental regulations governing wastewater discharge and effluent treatment continue to accelerate adoption of diaphragm pumps in industrial water and wastewater management, where seal-less designs and chemically resistant constructions offer distinct compliance advantages. Simultaneously, energy efficiency mandates and advancements in electrically operated diaphragm pumps are reshaping procurement criteria, with certain next-generation models delivering significant power reductions compared to traditional air-operated alternatives. These factors collectively position the diaphragm pump segment as a critical enabler of sustainable industrial fluid transfer.
Competitive Landscape: Consolidation, Innovation, and Regional Footprints
The competitive architecture of the worldwide industrial diaphragm pump market is defined by a blend of established multinational enterprises, specialized engineering firms, and increasingly capable regional manufacturers. Market concentration metrics indicate that the top three players command approximately 32.4 percent of total revenue, while the top five collectively account for 46.85 percent. This moderate concentration suggests a market that remains sufficiently fragmented to allow niche players and regional specialists to compete on customization, application expertise, and localized service networks, even as larger conglomerates leverage portfolio breadth and global distribution channels.
Leading participants span multiple geographies and operational philosophies. North American-headquartered firms such as Xylem Inc., Wanner Engineering Inc., Graco Inc., Dover Corporation (through its PSG division encompassing Wilden, Blackmer, and All-Flo), Ingersoll Rand's ARO division, IDEX Corporation (via Warren Rupp and Sandpiper), Flowserve Corporation, and Finish Thompson Inc. maintain strong positions across chemical transfer, industrial fluid handling, and sanitary applications. Their portfolios frequently emphasize air-operated double diaphragm designs, seal-less positive displacement architectures, and specialized material paths for corrosive or hazardous fluids.
European manufacturers contribute heavily to precision dosing, high-pressure metering, and compliance-driven applications. Grundfos A/S, Tapflo Group, Verder Group, KNF Neuberger GmbH, ProMinent GmbH, LEWA GmbH, and FLUX-GERÄTE GMBH are widely recognized for engineered solutions targeting water treatment, pharmaceutical processes, viscous liquid handling, and analytical or laboratory-grade fluid control. Meanwhile, Asian enterprises such as Yamada Corporation in Japan and GODO Manufacturing Co. Ltd. in China are expanding their footprints through cost-competitive electric models, environmental application focus, and integrated control features. Additional specialists like Albin Pump in Sweden and SAVINO BARBERA Srl in Italy further enrich the competitive matrix with compact designs and hazardous-chemical certifications.
Recent product launches underscore the pace of innovation. In March 2026, KNF Group introduced four advanced diaphragm pumps incorporating integrated sensor technology for flow, pressure, and vacuum control, extending their applicability across industrial, medical, and analytical use cases. The same month, Finish Thompson Inc. unveiled the FTI Air FT30P, a three-inch plastic air-operated double diaphragm pump engineered for high-flow chemical transfer. Earlier in 2025, GODO PUMPS showcased a new electric diaphragm pump with pressure relief controller at IE Expo, targeting environmental and high-flow scenarios, while ARO launched the EVO 210 electric diaphragm pump in September 2025 to improve efficiency and reliability in industrial settings. These releases illustrate a broader industry trend: manufacturers are embedding intelligence, enhancing material compatibility, and broadening electric offerings to meet evolving operational and sustainability expectations.
Segmentation Insights & Application-Side Demand Patterns
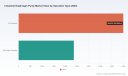
Understanding how demand distributes across operational types, end-user industries, and geographic regions is essential for targeted market entry, capacity planning, and product portfolio strategy. The market's revenue base reflects a clear preference for air-operated configurations, which continue to dominate industrial fluid handling due to their robustness, simplicity, and suitability for hazardous or abrasive environments. Electrically operated diaphragm pumps, while representing a smaller share of current revenue, are gaining traction as energy efficiency requirements intensify and facilities modernize legacy pneumatic infrastructure.
End-user demand is dispersed across multiple verticals, with water and wastewater management, chemicals and petrochemicals, food and beverage, oil and gas, pharmaceuticals, and a diversified remainder each contributing meaningfully to total consumption. This breadth indicates that diaphragm pumps are not confined to a single flagship application but rather serve as cross-industry workhorses where leak-free operation, chemical resistance, and precise metering are paramount. The multiplicity of end-use sectors also provides natural demand hedging: downturns in one vertical can be partially offset by sustained or growing requirements in another.
Geographically, the market's revenue distribution highlights the importance of regional industrialization rates, regulatory environments, and infrastructure investment cycles. Asia Pacific represents the largest regional revenue pool, followed by North America and Europe, with Latin America and the Middle East and Africa contributing smaller yet strategically significant volumes. These regional differentials matter because they shape localized competitive dynamics, service expectations, and the relative attractiveness of electric versus air-operated solutions. Decision-makers evaluating expansion, sourcing, or partnership opportunities must align their strategies with region-specific demand drivers rather than relying on global averages alone.
Material Supply, Regulatory Pressures, and Operational Implications
Market performance is inseparable from the underlying supply chain and regulatory environment. Raw material conditions have emerged as a critical variable for manufacturers and buyers alike. Since 2024, volatility in stainless steel, aluminum, and high-grade elastomer pricing has influenced manufacturing costs and average selling prices across the diaphragm pump segment. These fluctuations affect margin structures, lead times, and the economics of proprietary material formulations, making supplier diversification and forward contracting increasingly relevant for both producers and large-scale end users.
Material innovation continues to play a strategic role, particularly in chemically aggressive environments. PTFE remains a cornerstone material for chemical-resistant diaphragms, with global market volume reaching approximately 238.40 kilotons in 2026 and sustained demand from pump components in chemical processing. The availability, processing quality, and cost trajectory of such specialized materials directly affect product reliability, certification pathways, and the feasibility of sealing hazardous or corrosive fluids without compromising operational integrity.
Regulatory compliance is equally influential. Stricter environmental standards on wastewater discharge and effluent treatment are accelerating the deployment of diaphragm pumps in industrial water management, where sealless construction and compatible wet-end materials help facilities meet discharge limits and reduce maintenance interruptions. At the same time, compliance with explosion-proof design standards such as ATEX and adherence to ISO fugitive-emission limits are promoting the use of sealless diaphragm pumps built with advanced materials in hazardous industrial environments. These regulatory pressures do not merely constrain design choices; they actively redirect demand toward technologies that reduce leakage, improve containment, and simplify compliance documentation.
Sustainability objectives are further reshaping procurement logic. Energy efficiency mandates and demonstrable performance improvements in electric diaphragm pumps are encouraging facilities to reassess pneumatic dependencies. Certain electric models claim substantial energy reductions relative to traditional air-operated units, making them attractive in contexts where electricity costs, carbon targets, and total cost of ownership calculations intersect. For strategy teams, this trend signals a gradual but meaningful realignment in capital equipment specifications, with long-term implications for installed base composition and aftermarket service demand.
What the Full Study Delivers: A Practical Toolkit for 2026 Decision-Making
Our Worldwide Industrial Diaphragm Pump Market research is constructed to move beyond high-level commentary and equip teams with a structured, decision-ready analytical framework. The report integrates historical performance data, baseline valuations, and a multi-year forecast to clarify growth pacing, demand inflection points, and the relative contribution of different market segments. It maps revenue distribution across operational types, end-user industries, and regions, enabling readers to identify where volume is concentrated and where emerging opportunities may be underappreciated.
The study also provides a detailed competitive landscape assessment, examining the strategic positioning, product architectures, and market approaches of key participants. By contextualizing recent product launches, technology upgrades, and application-specific engineering focus, the report helps readers gauge how incumbents and challengers are shaping future supply dynamics. This competitive intelligence is paired with an analysis of market concentration, allowing stakeholders to evaluate competitive intensity, substitution risk, and the potential impact of consolidation or portfolio expansion.
Operational and supply-side factors are addressed with equal rigor. The research incorporates material market context, cost-structure considerations, and regulatory developments that influence product design, pricing, and adoption timelines. It further explores the interplay between energy efficiency expectations, electrification trends, and compliance requirements, offering a consolidated view of the forces that will determine which specifications win in procurement evaluations and which legacy configurations face gradual displacement.
Importantly, the study is designed to support scenario planning rather than prescribe a single path. Readers will find context for evaluating regional entry strategies, assessing supplier dependencies, benchmarking product roadmaps, and anticipating shifts in end-user preferences. By aligning quantitative forecasts with qualitative drivers, the report gives executives a coherent basis for investment prioritization, risk management, and cross-functional alignment between engineering, procurement, and commercial teams.
Worldwide Industrial Diaphragm Pump Market
Why This Research Matters Now
The 2026 decision environment demands more than retrospective reporting. Industrial buyers and suppliers alike are navigating material price variability, evolving compliance expectations, and a technology transition that favors smarter, more efficient fluid handling. In this context, a disciplined understanding of market size, growth pacing, segmentation structure, and competitive behavior becomes a strategic asset. It informs where to invest, which specifications to prioritize, how to structure supplier relationships, and when to anticipate shifts in regional demand intensity.
Diaphragm Valve Market
The Worldwide Industrial Diaphragm Pump Market study is built to serve as that strategic reference point. It combines a robust historical foundation with a forward-looking forecast through 2032, situates key industry players within a clear competitive framework, and ties market movements to the regulatory, material, and sustainability forces that are actively reshaping procurement and engineering decisions. For organizations seeking to reduce uncertainty and act with precision in 2026 and beyond, the full report provides the depth, structure, and operational relevance required to convert market intelligence into concrete business advantage.
For detailed analysis of this topic, please visit the official page: Worldwide Industrial Diaphragm Pump Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Cell Controller Market Reaches $745.5M in 2025, Projected at 8.45% CAGR to 2032
By pmarketresearch, 2026-09-16
The Worldwide Cell Controller Market: Strategic Imperatives for the 2026–2032 Horizon
The global transition toward electrification, smart manufacturing, and advanced energy storage is fundamentally reshaping the architecture of power management systems. At the core of this transformation lies the cell controller—a critical component responsible for monitoring, balancing, and safeguarding individual battery cells within complex packs. As industries from automotive to aerospace demand higher energy density, longer cycle life, and uncompromising functional safety, the cell controller market has evolved from a niche engineering requirement into a standalone strategic growth vector. Our newly published Worldwide Cell Controller Market research delivers a comprehensive, data-rich panorama of this transition, offering enterprise leaders the clarity needed to navigate an increasingly complex competitive and regulatory landscape through 2032.
This analysis is not merely a retrospective ledger of growth figures. It is a forward-looking strategic instrument designed to inform capital allocation, product roadmap decisions, supply chain resilience planning, and partnership strategies. By synthesizing historical performance, macro-industry tailwinds, and emerging technology paradigms, the report provides a structured framework for executives who must act decisively in a market defined by rapid innovation cycles and stringent safety mandates.
Macro Trajectory and Growth Architecture
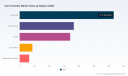
The cell controller market has demonstrated consistent upward momentum over the past half-decade, reflecting the broader acceleration of battery-dependent applications across multiple verticals. Historical revenue data from 2020 through 2025 reveals a structured expansion trajectory, with the market scaling from approximately 498 million USD in 2020 to an estimated 745.5 million USD by 2025. This historical baseline establishes a clear inflection point, setting the stage for a forecast period that projects continued, though progressively maturing, growth.
Our forward-looking projections for 2026 through 2032 indicate that the market will surpass the 849 million USD threshold in 2026 and continue its ascent toward an estimated 1.315 billion USD by the end of the forecast window. The compound annual growth rate across this period is calculated at 8.45 percent, a figure that reflects both sustained demand pull and the incremental penetration of advanced cell monitoring architectures in legacy and emerging applications alike. This growth rate is neither speculative nor overly conservative; it emerges from a careful reconciliation of deployment forecasts, supply-side capacity expansions, and the gradual standardization of high-channel-count controller topologies across diverse industrial and automotive platforms.
The revenue trajectory underscores a market that is moving beyond early-adopter saturation into broader industrial adoption. As battery pack architectures grow in complexity—incorporating higher series cell counts, tighter thermal tolerances, and integrated communication layers—the reliance on precision cell controllers becomes a structural requirement rather than an optional enhancement. This shift is visibly reflected in the steady year-over-year revenue increments observed throughout the forecast horizon, signaling that demand is being driven by both volume expansion and architectural upgrades in existing installations.
Structural Segmentation and Application Diversification
While the aggregate market figures provide directional clarity, the true strategic value of this research lies in its granular segmentation framework. The report dissects the market across multiple analytical dimensions, enabling executives to identify where growth is concentrating, which application verticals are driving incremental adoption, and how regional deployment patterns are evolving. The segmentation analysis reveals a market that is no longer monolithic; it is increasingly defined by divergent adoption curves, distinct regulatory pressures, and varying performance thresholds across sectors.
By examining regional distribution patterns, the report highlights how manufacturing footprints, localized supply chain strategies, and region-specific electrification mandates are shaping demand geography. Historical and projected revenue distributions across major geographic zones illustrate where infrastructure investment, automotive production scaling, and industrial battery deployment are converging to create sustained procurement cycles. These regional insights are critical for companies evaluating market entry strategies, localizing production capabilities, or optimizing logistics and distributor networks.
The application-side segmentation further clarifies where cell controller integration is becoming mission-critical. High-voltage battery management in mobility and energy storage, precision monitoring in semiconductor and electronics manufacturing, and safety-critical deployments in aerospace and defense represent distinct adoption profiles, each with 고유한 performance expectations and compliance burdens. Additional verticals, including food and beverage processing and specialized industrial use cases, contribute incremental but strategically meaningful demand, particularly where battery-backed control systems must meet stringent operational reliability standards. The report maps these application pathways in detail, enabling readers to assess where their existing product portfolios align with market needs and where adjacent opportunities may be underpenetrated.
A type-based breakdown distinguishes between hardware-centric controller solutions and the expanding domain of software and services that accompany modern battery management architectures. As cell controllers become more integrated into broader system-level diagnostics, remote monitoring, and predictive maintenance workflows, the service and software layer is increasingly contributing to total addressable value. This bifurcation is essential for suppliers deciding whether to compete purely on silicon performance or to build differentiated value through integrated firmware, calibration services, and system-level validation support.
Competitive Landscape and Strategic Positioning
The cell controller ecosystem is characterized by a relatively concentrated leadership tier, yet it remains open to innovation-driven differentiation. Market concentration indicators suggest that a limited number of established players command a substantial share of revenue, but the competitive environment is far from static. Continuous architectural improvements, functional safety certifications, and ecosystem partnerships are actively reshaping positioning. Our report provides a detailed competitive profiling framework that moves beyond headline market shares to examine how leading firms are structuring their technology roadmaps, securing supply chain advantages, and aligning with end-market compliance requirements.
NXP Semiconductors has maintained a prominent role in the cell controller space, offering a broad portfolio of battery cell controller ICs that span multiple safety and channel-count requirements. Its product families, including the MC3377x series and the BMA7318/BMA7518 18-channel architectures, reflect a deliberate strategy centered on high-voltage battery management systems for electric vehicles, energy storage systems, and 48V platform applications. These solutions emphasize daisy-chain communication, precision voltage and temperature monitoring, cell balancing, and rigorous functional safety integration. The recent introduction of the BMx7318/7518 family in mid-2025 further illustrates this trajectory, delivering per-channel dedicated ADCs, hardware alarm capabilities for overcurrent scenarios, and compliance aligned with ASIL-C and SIL-2 standards. This launch signals a continued commitment to supporting both automotive and industrial customers who require scalable, safety-certified monitoring hardware.
Texas Instruments continues to compete through its battery management system IC portfolio, with cell controller solutions such as the BQ79616 family supporting cell monitoring, balancing, and communication across automotive and industrial battery packs. TI’s approach emphasizes integration, manufacturability, and broad ecosystem compatibility, positioning its devices as foundational elements in pack-level architectures that require reliable communication and balanced charge-discharge performance.
Cell Fenders Market
Analog Devices contributes to the landscape through precision monitoring and controller ICs designed for high-voltage battery management applications. Its controller families focus on accurate voltage, temperature, and current measurement, supporting system designs that demand tight tolerance management and robust diagnostics. In markets where measurement fidelity directly influences pack longevity and safety margins, ADI’s positioning reflects a clear emphasis on performance-grade instrumentation integrated into controller architectures.
Beyond silicon suppliers, the competitive ecosystem also includes tooling and validation providers such as dSPACE, which offers Cell Controller Virtualization solutions for testing and simulation of battery management systems. By supporting controller validation across multiple hardware providers, dSPACE illustrates how the market is expanding beyond component manufacturing into system-level test infrastructure. This development is significant for enterprises seeking to reduce validation cycles, de-risk functional safety certification, and accelerate time-to-market for complex battery pack designs.
The report’s competitive analysis extends beyond company profiles to examine how these players interact with regulatory frameworks, standard-setting bodies, and downstream system integrators. Understanding these relationships is essential for executives evaluating partnership opportunities, assessing supplier risk, or planning acquisitions and technology licensing strategies.
Regulatory and Technical Dynamics Shaping Adoption
Market growth in cell controllers cannot be analyzed in isolation from the regulatory and technical standards that govern battery system design. Functional safety requirements have become a defining architectural constraint, particularly in automotive applications where battery management systems must align with ISO 26262 expectations. Many contemporary cell controller devices are engineered to support ASIL-C or ASIL-D compliance, incorporating built-in diagnostics, fault detection mechanisms, and fail-safe communication pathways. This safety-centric design philosophy is no longer optional for high-voltage applications; it is a baseline procurement requirement that directly influences component selection and system architecture decisions.
Parallel standards such as ISO 12405-3 and ISO 12405-4 further codify performance and safety expectations for electrically propelled road vehicles, explicitly referencing cell electronics and controller functions for monitoring and balancing. As these standards continue to shape engineering practices and certification processes, suppliers that can demonstrate measurable alignment with established protocols gain a meaningful advantage in qualifying for Tier-1 and OEM procurement pipelines. The research examines how these regulatory touchpoints are influencing product development cycles, validation methodologies, and market entry timing across different application segments.
In addition to safety standards, communication architecture has emerged as a critical technical differentiator. Modern battery management systems increasingly rely on isolated daisy-chain communication protocols and transformer-based physical layers to maintain signal integrity across large cell strings. This design approach supports reliable operation in high-noise electrical environments and enables scalable pack configurations that may incorporate hundreds of cells per series. The report evaluates how communication topology choices affect system cost, thermal design, fault isolation, and overall pack reliability, providing context for engineering leaders evaluating next-generation controller deployments.
Operational Content and Decision-Executing Frameworks
A market intelligence report is only as valuable as the operational clarity it provides. Accordingly, this research is structured to translate macro trends into actionable decision support. The publication includes detailed historical and forecast data tables, allowing readers to model revenue scenarios, track growth velocity, and benchmark internal performance against market trajectories. Segmentation breakdowns are presented across region, type, and application dimensions, enabling targeted analysis for product managers, regional sales directors, and strategic planning teams.
The report also provides competitive profiling, recent development tracking, and regulatory mapping, ensuring that readers can connect technical evolution with commercial implications. Recent product launches, functional safety certification milestones, and system-level validation innovations are contextualized within broader adoption patterns, helping executives anticipate where supplier capabilities are heading and how procurement requirements may shift. Strategic frameworks are embedded throughout the analysis to support use cases such as market entry assessment, portfolio gap analysis, supply chain localization planning, and partnership identification.
By combining quantitative market architecture with qualitative competitive and regulatory context, the publication is designed to serve as a reference point for cross-functional decision-making. Engineering leadership can use the segmentation and standard-compliance sections to guide architecture choices; commercial teams can leverage regional and application breakdowns to prioritize go-to-market resource allocation; and executive leadership can rely on the forecast trajectory and concentration analysis to inform long-term investment thesis development.
Why This Research Matters for 2026 Decision-Making
The 2026–2032 period will be defined by the maturation of battery system architectures, the tightening of safety and performance expectations, and the continued expansion of cell controller adoption beyond early-adopter verticals. Enterprises that enter this window with fragmented market intelligence risk misallocating R&D focus, underestimating compliance-driven procurement shifts, or overlooking regional demand concentrations that could shape revenue timing. This research was developed to close that intelligence gap.
Worldwide Cell Controller Market
The strategic value of the report lies in its ability to connect high-level growth data with the operational realities of product planning, supplier evaluation, and market prioritization. It does not simply report that the market is expanding; it explains where that expansion is concentrating, which technical and regulatory forces are accelerating adoption, and how the competitive field is evolving in response. For organizations operating in automotive electrification, energy storage integration, industrial battery deployment, or precision electronics manufacturing, the insights contained here are directly applicable to roadmap alignment and risk mitigation.
The complete dataset, segmentation detail, competitive profiles, and scenario-ready forecasting tables are available in the full Worldwide Cell Controller Market research publication. We invite executives, strategy teams, and industry analysts to access the complete report for the comprehensive intelligence required to make confident, evidence-based decisions in the 2026 planning cycle and beyond.
For detailed analysis of this topic, please visit the official page: Worldwide Cell Controller Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Global Alternate Light Sources Market to Hit $694.05M by 2032 with 5.72% CAGR
By pmarketresearch, 2026-09-16
Strategic Intelligence in the Worldwide Alternate Light Sources Market: A 2026 Decision Framework
The global landscape for Alternate Light Sources (ALS) is undergoing a period of structural refinement, driven by sustained demand across forensic, medical, and industrial applications. As enterprises navigate an environment defined by technological maturation and regulatory standardization, the necessity for precise, forward-looking market intelligence has never been more critical. PW Consulting's latest Worldwide Alternate Light Sources Market research study offers a comprehensive strategic lens designed specifically to inform high-stakes corporate decisions throughout 2026 and beyond.
This analysis serves as a foundational brief for executive teams, product strategists, and investment committees seeking to align their portfolios with the evolving dynamics of the ALS sector. By synthesizing historical performance data, forward-looking projections, and granular competitive profiling, the report eliminates the ambiguity that often plagues strategic planning in specialized lighting and photonics markets.
Macro-Market Trajectory and Growth Dynamics
Understanding the baseline momentum of the alternate light sources industry is the first step in any robust strategic assessment. Our research tracks the market's revenue evolution from the base year of 2025 backward through 2020, while simultaneously projecting performance through the forecast horizon of 2032. The data reveals a consistent expansion trajectory that reflects both steady historical adoption and anticipated future acceleration.
Between 2020 and 2025, the worldwide ALS market demonstrated resilient growth, climbing from an aggregate revenue baseline of approximately USD 365 million to a 2025 valuation of nearly USD 471 million. This historical progression underscores the technology's transition from specialized niche equipment to broader operational staples within law enforcement agencies, clinical diagnostic facilities, and quality assurance laboratories. The market's momentum carries forward into the forecast period, with 2026 expected to mark a significant inflection point as the aggregate valuation surpasses the USD 507 million threshold.
Looking across the full forecast window extending to 2032, the compound annual growth rate (CAGR) is calculated at 5.72 percent. This sustained growth profile suggests that market expansion will be characterized by methodical, dependable increases in procurement spend rather than volatile spikes. By the end of the decade, revenue projections indicate that the market will approach an annual valuation exceeding USD 600 million, with continued upward pressure through the early 2030s as next-generation portable systems and laboratory-grade multi-spectral platforms gain deeper integration into standard operating procedures worldwide.
Demand Drivers Shaping the 2026 Horizon
Several converging factors are positioning the ALS sector for continued relevance and procurement growth during 2026. The interplay between regulatory standardization, operational efficiency requirements, and technological miniaturization is reshaping how end-users evaluate and deploy alternate light solutions.
- Regulatory and Standardization Tailwinds: Industry definitions and equipment classifications are becoming increasingly formalized. For instance, authoritative bodies now formally recognize alternate light sources as specialized equipment designed to produce light at precise wavelengths to enhance or visualize potential evidentiary items. Simultaneously, portable forensic light kits—which must integrate an alternate light source, a barrier filter, a dedicated power source, and a carrying case—have been codified within recognized authorized equipment listings for law enforcement crime scene operations. These standardization efforts reduce procurement ambiguity and create clearer pathways for vendor qualification.
- Operational Protocol Evolution: Professional guidelines are increasingly specifying how ALS technologies should be deployed in low-light documentation scenarios. Established protocols now emphasize controlled photographic conditions, including tripod mounting, manual or aperture-priority exposure modes, and strict adherence to wavelength-specific eye protection requirements. These standards elevate the importance of purchasing certified, guideline-compliant equipment rather than ad-hoc lighting solutions, thereby strengthening the addressable market for professional-grade ALS providers.
- Safety and Compliance Emphasis: As shortwave UV configurations remain widely utilized for evidence detection and specialized inspection tasks, manufacturers and procurement officers alike are placing greater weight on integrated safety features. Vendor documentation increasingly highlights mandatory eye and skin protection protocols, reinforcing the market's shift toward systems that bundle protective accessories and operator training materials alongside core illumination hardware.
Report Scope and Operational Content Architecture
The Worldwide Alternate Light Sources Market research deliverable is structured to provide actionable intelligence rather than abstract market commentary. PW Consulting's analytical framework ensures that every section of the report translates directly into executable strategy for product development, regional expansion, pricing optimization, and competitive positioning.
At its core, the study delivers a multi-dimensional segmentation analysis that dissects the market across critical operational axes. Readers will find dedicated evaluations of the primary technology categories that define the ALS product universe, including an in-depth examination of LED-based illumination platforms, which currently represent the dominant share of deployed systems, alongside detailed profiles of Xenon and Laser light source segments. Each technology category is assessed for its distinct adoption curves, price band positioning, and suitability for specific end-use environments ranging from field-deployed crime scene units to controlled laboratory screening workflows.
The application-driven segmentation module provides equal granularity, mapping market activity across the principal domains where alternate light technologies generate measurable value. Forensic investigation remains the most substantial demand pillar, with specialized ALS kits and multi-wavelength laboratory screening systems forming an integral component of modern evidence processing pipelines. Medical diagnostics represents a secondary but growing application vector, where wavelength-specific illumination supports diagnostic visualization and procedural guidance. Industrial inspection rounds out the core application landscape, encompassing quality assurance, defect detection, and material analysis workflows that rely on precise spectral output to identify anomalies invisible under standard lighting conditions.
Geographic coverage within the report is comprehensive, capturing revenue distribution and growth characteristics across North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa. Rather than presenting raw figure tables in isolation, the regional analysis contextualizes each market's procurement environment, regulatory maturity, agency budget cycles, and technology adoption timelines. This approach enables readers to identify not only which regions represent the largest current revenue pools, but also which territories exhibit the strongest forward indicators for incremental market entry or distribution partnership development.
Competitive Landscape and Strategic Positioning
The ALS market features a diverse ecosystem of specialized manufacturers and distributors, each competing across different price tiers, feature sets, and end-user segments. Our competitive analysis module evaluates the strategic posture of key market participants, mapping their product portfolios, innovation trajectories, and recent commercial activities to provide a clear picture of where competitive intensity is concentrated and where whitespace opportunities may exist.
Leading Participant Profiles
Several established firms anchor the competitive structure of the worldwide ALS market, with leadership positions often correlated to deep domain specialization, regional distribution strength, and the ability to deliver certified, guideline-compliant equipment.
- Foster + Freeman: Headquartered in the United Kingdom, this organization has built a reputation as a pioneer in high-intensity LED forensic illumination, anchored by its widely deployed Crime-lite product family. The portfolio spans handheld crime scene series, multi-wavelength laboratory configurations, and advanced multi-spectral and laser-enabled screening platforms. Recent commercial activity has highlighted next-generation evidence screening tools designed for forensic laboratory environments, reinforcing a strategic emphasis on laboratory-grade throughput and multi-wavelength integration.
- Labino AB: Based in Vallentuna, Sweden, this manufacturer focuses on waterproof LED alternate light source kits engineered specifically for crime scene investigation workflows. Product design emphasizes operational simplicity, with straightforward on/off functionality and robust field-ready engineering. Recent catalog updates have expanded specification transparency for core ALS kits, reflecting a broader industry trend toward clearer technical documentation and streamlined procurement evaluation.
- Sirchie: Operating from the United States, this supplier provides a range of forensic alternate light solutions tailored for law enforcement evidence detection. Its product lines include high-output three-watt illumination systems, tactical field kits, and shortwave UV configurations optimized for crime scene processing. The emphasis on law enforcement readiness and tactical deployment architecture positions this participant strongly within public-sector procurement channels.
- HORIBA Scientific (SPEX Forensics): This United States-based entity offers compact handheld and laboratory-focused LED alternate light platforms designed for visualizing latent prints, body fluids, and other forensic evidence markers. The brand's positioning centers on precision visualization tools that bridge field collection and laboratory confirmation workflows.
- FoxFury: Also headquartered in the United States, this supplier specializes in rugged, cordless forensic lighting and alternate light source configurations intended for field investigators. Product families include portable series designed for cordless operation, emphasizing durability, rapid deployment, and flexible wavelength options across multiple kit configurations.
- Lynn Peavey Company: A United States-based distributor and supplier, this organization provisions portable ALS units alongside complementary forensic processing materials. Its distribution-centric model enables broad catalog reach across evidence processing workflows, making it a significant channel presence within the North American supply ecosystem.
- UltraLite ALS: Operating as a specialized provider of portable forensic alternate light sources, this participant focuses on compact, wavelength-configurable kits intended for direct crime scene deployment. The product emphasis aligns with the broader market shift toward lightweight, field-portable systems that maintain professional-grade spectral output in a streamlined form factor.
Concentration Dynamics and Portfolio Strategy Implications
The competitive structure of the worldwide ALS market exhibits meaningful concentration at the top tier, with the largest players collectively commanding a substantial share of aggregate revenue. This concentration pattern reflects the importance of brand certification, regulatory familiarity, and established distribution relationships in public-sector and institutional procurement environments. Simultaneously, the market maintains a broad product diversity across more than a dozen manufacturers and upwards of fifty distinct configurations, with price points spanning a wide range from entry-level field kits to high-specification laboratory systems. This bifurcated structure creates a strategic landscape where premium differentiation, compliance documentation, and total-cost-of-ownership positioning often matter more than unit-price competition alone.
Worldwide Alternate Light Sources Market
Regulatory Context and Standardization as a Market Accelerator
One of the most important yet underappreciated drivers in the ALS sector is the accelerating pace of regulatory definition and equipment standardization. As forensic and public-safety agencies seek to formalize equipment procurement criteria, clear technical standards increasingly function as market accelerants rather than purely compliance burdens.
Shadowless Lamps Market
Authoritative glossary definitions now explicitly frame alternate light sources as equipment engineered to produce light at specific wavelengths for the enhancement and visualization of potential evidence. This definitional clarity helps procurement officers narrow their evaluation criteria and reduces the risk of acquiring non-compliant or under-specified illumination tools. In parallel, recognized authorized equipment frameworks now list portable forensic light kits—comprising at least one alternate light source, a barrier filter, a dedicated power source, and a carrying case—as qualified equipment categories for law enforcement crime scene operations.
These standardization developments carry direct strategic implications. For manufacturers, they create clearer specifications around what constitutes a qualified kit, potentially raising the barrier to entry for non-integrated or non-certified alternatives. For procurement leaders, they streamline the justification process for capital expenditure by linking equipment purchases to documented operational standards. For channel partners and distributors, they reinforce the value of carrying portfolios that explicitly reference these compliance frameworks in sales collateral and technical documentation.
Furthermore, professional guidelines governing low-light crime scene photography now specify operational requirements that emphasize controlled imaging conditions, tripod stability, manual or aperture-priority exposure modes, and wavelength-appropriate operator protection. Equipment vendors that design their systems with these documentation and safety protocols in mind are better positioned to meet institutional purchasing requirements and to reduce the friction associated with evidence admissibility and chain-of-custody considerations.
360-Degree Market Intelligence for 2026 Strategic Planning
Effective market strategy in 2026 requires more than a simple revenue forecast. It demands an integrated understanding of how technology readiness, regulatory evolution, competitive maneuvering, and application-specific procurement cycles interact to shape demand. PW Consulting's Worldwide Alternate Light Sources Market report is constructed to deliver that integrated view.
Readers will obtain a structured basis for evaluating product roadmap priorities, identifying which technology segments are most likely to capture incremental budget allocation, and determining whether regional expansion efforts should prioritize high-revenue incumbency or higher-growth developmental markets. The report also supports pricing strategy calibration by illuminating how different product tiers—from compact handheld units to sophisticated multi-wavelength laboratory platforms—are positioned across the broader ecosystem.
For investors and corporate development teams, the concentration analysis and participant profiling provide a practical framework for assessing acquisition targets, distribution partnership opportunities, and whitespace entry points. The combination of historical revenue validation, forecast-period trajectory modeling, and competitive activity tracking ensures that strategic decisions are grounded in observable market behavior rather than speculative sentiment.
Conclusion: Converting Market Intelligence into 2026 Advantage
The worldwide alternate light sources market stands at a point where steady structural growth intersects with meaningful technological and regulatory evolution. For organizations operating in, adjacent to, or seeking entry into this sector, the difference between reactive positioning and proactive advantage lies in the quality of market intelligence available at the planning table.
PW Consulting's comprehensive study equips decision-makers with the analytical depth required to navigate this landscape confidently. By linking macro-level revenue trajectories, segmented demand patterns, regulatory standardization momentum, and competitive portfolio dynamics into a single strategic framework, the report enables enterprises to align their 2026 initiatives with demonstrable market realities. The full dataset, detailed segmentation breakdowns, complete competitor evaluations, and forward forecast tables are available through the complete research release. For teams ready to move beyond surface-level industry overviews and into execution-ready intelligence, the full report provides the definitive reference point for the year ahead.
For detailed analysis of this topic, please visit the official page: Worldwide Alternate Light Sources Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Condensation Silicone Rubber Market Hits $2.25 Billion in 2025, Projects 4.82% CAGR to 2032
By pmarketresearch, 2026-09-16
Strategic Horizons for the Global Condensation Cure Silicone Rubber Market: Navigating the 2026 to 2032 Era
The industrial materials landscape is entering a pivotal consolidation phase, and nowhere is this more evident than in the condensation cure silicone rubber (CCSR) sector. Our latest Worldwide Condensation Cure Silicone Rubber Market research report delivers the definitive intelligence framework required to navigate the forecast period from 2026 through 2032. For procurement directors, R&D strategists, and market expansion leaders, this study transforms macroeconomic signals into executable roadmaps, enabling precise capacity positioning, pricing architecture design, and competitive maneuvering in a market defined by steady structural growth and evolving technological trade-offs.
The condensation cure segment occupies a distinct competitive position within the broader elastomers ecosystem. Its room-temperature vulcanizing (RTV) characteristics, cost-effective tin-catalyzed chemistry, and proven compatibility with casting, molding, and sealant workflows continue to drive sustained demand across advanced manufacturing, construction, and specialized industrial applications. Understanding where this value chain is heading requires more than headline figures; it demands a rigorous dissection of historical trajectory, forward-looking velocity, regional polarization, product architecture shifts, and the dynamic pressures of raw material economics and regulatory evolution.
The Macro Trajectory: From Consolidation to Accelerated Expansion
Historical data reveals a market that has successfully weathered cyclical volatility to establish a robust baseline. Between the early baseline years and 2025, global revenue demonstrated clear upward momentum, reflecting sustained downstream adoption and manufacturing efficiency gains. The current market year has already settled into a trajectory that positions the sector for predictable expansion. Looking ahead, our forecast modeling outlines continued growth through 2032, supported by compounding demand from high-durability sealing solutions, precision mold making, and industrial maintenance workflows.
- The market has evolved from post-pandemic recalibration to a phase of measured, high-confidence scaling.
- Forecast modeling captures a compound annual growth rate that underscores steady structural expansion rather than speculative hype.
- Revenue progression across the decade points toward sustained valuation appreciation, creating clear windows for market share capture and premiumization strategies.
Absolute Scale and Growth Velocity: The Numbers That Redefine Opportunity
The financial architecture of this market provides a compelling foundation for long-term investment and commercial planning. At its historical baseline, the sector commanded a substantial global valuation measured in billions of dollars, confirming its entrenched role across multiple industrial verticals. By the current market year, revenue figures reflected both recovery resilience and expanded application penetration, setting a higher floor for the forecast horizon.
Silicone Resin Market
As we project forward, the market is positioned to traverse a multi-year expansion corridor, reaching a significantly elevated valuation by the end of the forecast window. The compound annual growth rate of the period translates into a powerful compounding effect, where territorial diversification, product line extensions, and application migration can amplify realized returns far beyond aggregate market growth. For strategic planners, this backdrop validates disciplined capacity allocation, targeted geographic entry, and formulation innovation as core value-creation levers.
Regional Polarization: Where Demand Converges and Where It Diversifies
Geographic demand distribution reveals a market that is simultaneously concentrated and diversifying. Asia Pacific commands the largest share of global revenue, driven by dense manufacturing ecosystems, expansive construction activity, and rapidly scaling production of molding and casting applications. North America and Europe maintain strong secondary positions, characterized by higher value-add specialization, stringent performance requirements in electronics and automotive-adjacent workflows, and mature maintenance-repair-overhaul (MRO) channels. Meanwhile, Latin America and the Middle East and Africa represent emerging expansion vectors, where infrastructure development and localized industrial supply chains are progressively unlocking new consumption nodes.
This geographic architecture carries a crucial strategic implication: competitive advantage no longer belongs solely to the largest aggregate player. It belongs to organizations that understand regional pricing elasticity, regulatory nuance, supply chain proximity, and application-specific formulation preferences. The report maps these regional demand signatures in detail, equipping stakeholders with the context required to align distribution footprints, formulation localization, and channel partnerships with the territories that offer the highest marginal returns.
Product Architecture and Application Migration: The Battlefield of Differentiation
The condensation cure market is structurally divided between one-component and two-component RTV systems, each serving distinct performance and processing philosophies. One-component formats continue to dominate in ease-of-use workflows, rapid deployment scenarios, and applications where operational simplicity outweighs the need for advanced formulation tuning. Two-component systems, by contrast, offer enhanced control over cure kinetics, depth-of-cure performance, and mechanical property optimization, making them the preferred architecture for precision tooling, demanding casting processes, and environments where cure inhibition sensitivity must be managed.
On the application side, demand concentration is both revealing and instructive. Mold making and tooling remains a central pillar, reflecting the enduring need for high-tear-strength, dimensionally stable elastomeric matrices in casting workflows ranging from wax and gypsum to urethane, epoxy, and polyester resins. Construction sealants form another major demand block, driven by durability requirements in architectural and infrastructure contexts. Electronics and electrical potting represent a high-growth specialization, where encapsulation reliability and thermal-responsiveness considerations continue to attract material innovation. Automotive components and general industrial maintenance round out the application footprint, providing steady-replacement demand streams that stabilize revenue during cyclical fluctuations.
The strategic question for formulators and distributors is not simply which segment is larger, but which segment offers the steepest trajectory for margin expansion, technical differentiation, and barrier creation. The report isolates these migration patterns and maps the competitive inflection points where formulation leadership can be converted into durable commercial advantage.
The Competitive Field: Who Is Defining the Next Standard of Performance
The competitive environment is defined by a blend of specialized formulators, regional manufacturing strength, and multinational technology presence. The market exhibits a moderately concentrated structure, with the top three players commanding a significant combined share and the top five extending that influence further. This concentration creates both a challenge and an opening: incumbents maintain formidable distribution, technical support, and formulation ranges, but the remaining share is large enough to reward focused differentiation, especially in application-specific customization, cure-time modulation, and localized service models.
Several companies illustrate the archetypes shaping market behavior. Smooth-On, Inc. has built a deep reputation around tin-cure mold rubbers, with product families engineered for varied hardness requirements and broad compatibility with casting materials. Polytek Development Corp. emphasizes flexible mold making with formulations noted for high tear strength and favorable release characteristics, alongside lower sensitivity to cure inhibition relative to addition-cure alternatives. Silicones, Inc. has maintained a long-standing focus on condensation cure RTV-2 silicones, offering both standard and custom formulations across mold-making, electronics potting, and special effects use cases.
CHT Group contributes a European formulation perspective, supplying condensation cure silicones for moulding applications compatible with a wide spectrum of casting substrates, plus catalysts and thixotroping agents for property modification and custom development. BBN Materials Co., Limited reflects the expanding capabilities within China's specialty silicone ecosystem, concentrating on tin-cured mold making for crafts, candles, soaps, resin, GFRC, and concrete products, with customizable operation and curing times. Silpak, Inc. continues to produce two-component condensation-cure RTV systems that deliver high-strength room-temperature curing for mold making and allied applications.
Worldwide Condensation Cure Silicone Rubber Market
On the global technology side, Elkem Silicones offers polycondensation tin-kit condensation cure silicones suitable for architectural molding, including plaster, gypsum, and concrete applications. Shin-Etsu Chemical Co., Ltd. extends its broad silicone portfolio with two-component condensation cure RTV rubbers, including rapid cure types and high-thermal-stability one-component grades. Momentive Performance Materials rounds out the competitive field with condensation cure RTV silicones tailored for mold making rubber applications, supported by catalyst systems that influence cure behavior and processing consistency.
These firms collectively demonstrate that performance leadership is increasingly defined by application engineering, cure robustness, and the ability to customize formulation parameters to user workflows. The report translates these competitive dynamics into actionable intelligence, mapping strategic positioning, capability overlaps, and whitespace opportunities for entrants and incumbents alike.
Raw Material Economics and Regulatory Flux: The Hidden Cost Structures
Market growth does not occur in a vacuum. Recent industry context signals point to tightening cost structures and regulatory complexity that are reshaping upstream economics and downstream margin expectations. Industrial-grade silicone oil prices in China have shown a moderate upward trend, with high-viscosity and modified grades commanding premium levels, driven by rising feedstock costs. D4 price movements have contributed meaningfully to higher production costs for silicone-based materials, including condensation cure systems. This input pressure interacts with broader cost dynamics in catalyst supply, packaging, and logistics, placing renewed emphasis on formulation efficiency and value engineering.
Simultaneously, stricter environmental policies have impacted silicone production costs and supply conditions in key manufacturing regions. For buyers and producers, this means resilience planning is no longer optional. Dual-sourcing strategies, regional inventory buffering, and formulation adaptability are becoming essential components of cost-containment roadmaps. Companies that can maintain performance consistency while navigating input volatility will capture disproportionate share in markets where competitors face throughput constraints or margin compression.
What the Report Delivers: The Operational Intelligence You Need
This study is designed as an execution-focused intelligence package rather than a static market snapshot. It provides a full historical-to-forecast value chain view, segmentation architecture across regions and product types, application-level demand mapping, and competitive profiling that connects corporate capabilities with market behavior. Procurement teams will gain clarity on volume trajectory, pricing pressure indicators, and regional sourcing considerations. R&D and formulation leaders will receive the structural context needed to prioritize cure optimization, inhibition management, and application-specific property tuning. Commercial and strategy teams will obtain the geographic and segment insights required to evaluate market entry, channel expansion, and customer-facing value propositions.
From Insight to Advantage: Why 2026 Decisions Depend on This Research
The condensation cure silicone rubber market is entering a phase where steady aggregate expansion will be matched by sharper competitive differentiation, regional complexity, and input-driven cost sensitivity. Organizations that act on incomplete intelligence risk misallocating capacity, undervaluing application-specific niches, or underestimating the strategic impact of raw material and regulatory shifts. Our Worldwide Condensation Cure Silicone Rubber Market report closes that intelligence gap by converting macro trends into precise operational guidance.
For decision-makers preparing for the 2026 planning cycle, this research offers the evidence base needed to align investment timing, commercial positioning, formulation strategy, and regional execution with the market's most probable trajectory. The full analysis, including granular segmentation, competitive benchmarking, and forward-looking scenario framing, is available through our complete report. Access the detailed intelligence now and position your organization to convert market momentum into durable strategic advantage.
For detailed analysis of this topic, please visit the official page: Worldwide Condensation Cure Silicone Rubber Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Military Off-Road Vehicle Market to Hit $26.17B by 2032 at 5.12% CAGR
By pmarketresearch, 2026-09-16
Strategic Imperatives in the Global Military Off-Road Vehicles Market: A 2026 Outlook
Navigating Terrain and Tactics in an Evolving Defense Landscape
The worldwide military off-road vehicles market stands at a critical juncture where operational necessity intersects with technological transformation. As defense organizations recalibrate their ground mobility strategies, the demand for vehicles capable of traversing complex terrains while maintaining tactical superiority has become increasingly pronounced. Our latest market research provides a comprehensive examination of this sector, offering decision-makers a clear view of the forces shaping procurement, production, and deployment patterns through the end of the decade.
Between 2020 and 2025, the global market expanded from approximately USD 14,500 million to USD 18,450 million, reflecting sustained investment in ground mobility capabilities and a consistent upward trajectory. Looking ahead, the forecast period from 2026 to 2032 projects continued growth, with the market expected to reach USD 26,169 million by the close of the forecast window. This expansion is supported by a compound annual growth rate of 5.12 percent, signaling a resilient demand environment even as defense budgets face periodic scrutiny and procurement cycles grow more complex.
Off-road Engines Market
For executives and strategists operating in this space, the numbers alone do not tell the full story. The underlying dynamics—technological integration, supply chain constraints, regulatory distinctions, and shifting operational requirements—are what ultimately determine competitive positioning and commercial success. This research is designed to translate macro-level momentum into actionable intelligence, enabling organizations to anticipate disruptions, identify partnership opportunities, and align product development with emerging military needs.
Market Structure and Segment Intelligence
A thorough understanding of how military off-road vehicles are categorized and deployed across different mission profiles is essential for strategic planning. The market encompasses a diverse range of vehicle types, each serving distinct operational functions and procurement priorities. Light tactical vehicles continue to hold significant relevance, driven by their versatility in rapid deployment scenarios and their adaptability to both combat and support roles. Medium and heavy tactical platforms remain integral to logistics, troop transportation, and combat support operations, particularly in theaters where payload capacity and survivability are prioritized alongside mobility.
Unmanned ground vehicles represent a growing dimension of the market, reflecting broader defense modernization efforts. The integration of autonomous navigation, sensor suites, and remote operation capabilities is reshaping how military organizations approach reconnaissance, breaching, and high-risk terrain traversal. These platforms are no longer conceptual prototypes; they are advancing through rigorous testing and integration programs that underscore a strategic shift toward reducing personnel exposure in contested environments.
Application-wise, the market is anchored by core mission requirements including troop transportation, combat operations, logistics and supply, and medical and command post support. Each of these application areas imposes different engineering, performance, and logistical demands, and procurement decisions increasingly reflect a balance between immediate operational needs and long-term capability development. The research provides granular segmentation analysis that examines how these categories interact with regional procurement patterns, production capacity, and evolving mission profiles, without relying on oversimplified assumptions about uniform demand across theaters.
Competitive Landscape and Organizational Positioning
The competitive environment in the military off-road vehicles market is characterized by a mix of established defense manufacturers, specialized tactical vehicle producers, and organizations increasingly focused on hybridization, modularity, and next-generation mobility solutions. Market concentration data indicates that a relatively small group of leading firms commands a substantial share of total revenue, with the top three companies accounting for approximately 42.15 percent and the top five reaching 58.4 percent. This concentration underscores the importance of scale, program continuity, and long-term procurement relationships, while also leaving room for specialized entrants that can differentiate through technology, platform flexibility, or regional partnerships.
Oshkosh Defense remains a prominent force in the tactical wheeled vehicle segment, with its portfolio including platforms designed for high off-road mobility, protection, and payload performance. Its continued emphasis on combat-proven systems and independent suspension technology reinforces its relevance in programs where terrain adaptability and survivability are paramount. AM General, widely recognized for its light tactical vehicle heritage, continues to support global armed forces with high-mobility platforms and enhanced tactical kits, maintaining a strong footprint in both legacy and next-generation vehicle families.
General Dynamics Land Systems brings a focused approach to wheeled armored vehicles and tactical platforms, emphasizing mobility, survivability, and system integration. Its development work, including hybrid-electric demonstrators, reflects a broader industry interest in power architecture innovation and mission flexibility. BAE Systems contributes armored and tactical wheeled vehicles with off-road capability, supporting a diverse set of global customers with platforms adapted for combat and support missions. Rheinmetall AG has expanded its presence through modular wheeled armored vehicle offerings that prioritize protection, mobility, and variant flexibility for troop transport and support roles.
Additional participants such as Navistar Defense, GM Defense, Iveco Defence Vehicles, Mack Defense, Arquus, Tata Motors, and Hanwha Defense each bring distinct strengths to the market. Some emphasize logistical truck platforms engineered for rigorous off-road military conditions, while others focus on light tactical and hybrid-electric solutions or armed forces mobility programs tailored to regional requirements. The presence of both multinational primes and regional specialists creates a layered competitive environment where procurement decisions often weigh proven performance, industrial base considerations, and technology roadmaps in combination rather than in isolation.
Recent Developments Shaping the Operational Agenda
Recent activity across the defense mobility sector illustrates how rapidly the strategic conversation is evolving. In late 2025, Oshkosh Defense showcased its combat-proven light tactical vehicle at the International Armoured Vehicles Conference, reinforcing the continued relevance of platforms that combine off-road mobility with protection and reliability in operational settings. Around the same time, GM Defense demonstrated its light vehicle lineup in the United Kingdom for the first time, signaling accelerated delivery planning and a broader push to position next-generation mobility solutions within international procurement considerations.
One of the most significant developments in the broader ecosystem has been the advancing role of autonomy in ground operations. DARPA's final tests of RACER autonomous platforms in early 2026 demonstrated complex terrain navigation in support of Army combat breaching operations, highlighting the operational value of autonomous mobility in high-consequence environments. In parallel, the U.S. Army selected Overland AI, Forterra, and Scout AI to integrate autonomous mobility into Infantry Squad Vehicles for off-road operations, with prototypes expected by May 2026. These initiatives point toward a future in which unmanned and semi-autonomous capabilities are not separate from the core vehicle market, but increasingly embedded within it.
Worldwide Military Off-road Vehicles Market
These developments matter because they illustrate how procurement priorities are shifting from purely mechanical performance to integrated mission systems, software-enabled mobility, and platform adaptability. Organizations that can align vehicle design, autonomy integration, and sustainment strategies with these emerging requirements will be better positioned to participate in next-generation programs.
Regulatory and Supply Chain Dynamics as Strategic Variables
Market performance in the military off-road vehicles sector is influenced not only by operational demand but also by regulatory frameworks and industrial supply conditions. A notable feature of this market is the regulatory environment surrounding military tactical vehicles, which distinguishes them from civilian on-road and off-road standards. U.S. Armed Forces tactical military off-road trucks are exempt from standard EPA on-road and off-road exhaust emissions regulations, allowing continued use of higher-sulfur JP-8 fuel and older engine configurations without aftertreatment devices. Similarly, military tactical vehicles are not subject to the same stringent civilian emissions standards, enabling optimized mobility and performance in off-road conditions. These distinctions matter because they preserve design flexibility for military platforms while also shaping fuel logistics, maintenance approaches, and engineering trade-offs.
On the industrial side, supply-chain fragility remains a defining challenge. The availability of armor steel and power electronics has affected production timelines and costs, introducing uncertainty into program planning and budgeting. Steel price volatility has had a measurable impact on armor production costs, with industry data indicating a significant increase in costs between 2022 and 2023 for military land vehicles. Such pressures can influence not only vehicle pricing but also lead times, configuration decisions, and the feasibility of certain platform upgrades.
For market participants, these dynamics are not peripheral concerns; they are central to risk management and program execution. The research examines how regulatory exemptions, material constraints, and production economics interact with procurement behavior, helping organizations anticipate where bottlenecks may emerge and where adaptation strategies can create competitive advantage. Understanding these variables is especially important as manufacturers balance performance requirements with cost discipline and delivery reliability.
Why This Research Matters for 2026 Decision-Making
The 2026 outlook for the worldwide military off-road vehicles market presents a landscape defined by sustained growth, technological differentiation, and an increasingly complex set of procurement and production variables. For defense contractors, vehicle integrators, component suppliers, and strategic investors, the ability to interpret market momentum in relation to segment dynamics, competitive positioning, and operational trends is a core strategic capability. This research is built to support that capability by providing a structured, evidence-based view of the market rather than a superficial summary of headline figures.
The report offers detailed segmentation analysis, historical performance tracking, and forward-looking forecasts that extend through the end of the forecast period. It examines vehicle type and application categories in the context of mission requirements and procurement logic, explores regional demand patterns without reducing them to isolated percentages, and analyzes the competitive environment through the lens of program relevance, technological direction, and market concentration. Equally important, it integrates recent developments and structural dynamics—including autonomy advancement, regulatory distinctions, and supply-chain pressures—into a coherent framework for strategic planning.
In practice, this means the research can support a range of high-value decisions. It can inform product roadmap prioritization, highlight where platform capabilities align with emerging mission demands, and identify which competitive differentiators are likely to carry the most weight in procurement evaluations. It can also help organizations assess where market concentration and program continuity create barriers, and where regional specialization or technology-led positioning may open more accessible opportunities. By combining quantitative trajectory data with qualitative insight into industry dynamics, the study is designed to reduce uncertainty and improve the quality of strategic judgment.
Prepared for Actionable Intelligence
The military off-road vehicles market is not defined solely by vehicle mobility; it is shaped by the interplay of operational doctrine, procurement timing, platform survivability, industrial capacity, and technology integration. As the market moves through the 2026 to 2032 forecast horizon, organizations that can read these signals clearly will be better equipped to allocate resources, plan partnerships, and respond to shifting requirements with discipline and speed.
Our Worldwide Military Off-road Vehicles Market research is intended to serve as a strategic reference point for that effort. It provides the analytical depth needed to move beyond surface-level trends and the structured insight required to translate market conditions into concrete decisions. The full report contains the detailed segmentation breakdowns, competitive profiles, and market trajectory data necessary to support planning at the executive and operational levels.
For leaders seeking a more complete view of segment performance, regional demand patterns, and the specific intelligence behind the forecasts discussed here, the full report offers the comprehensive dataset and analysis required to guide next steps with confidence.
For detailed analysis of this topic, please visit the official page: Worldwide Military Off-road Vehicles Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Elapegademase-lvlr Market Hits $61.2M in 2025, Driven by 8.5% CAGR to 2032
By pmarketresearch, 2026-09-16
Strategic Intelligence for 2026: Navigating the Worldwide Elapegademase-lvlr Drugs Market
As the pharmaceutical landscape continues to evolve at an unprecedented pace, precision medicine and orphan drug therapies have emerged as critical frontiers for strategic investment and operational planning. PW Consulting is pleased to present the Worldwide Elapegademase-lvlr Drugs Market Market Research, a comprehensive analytical report designed to equip executives, portfolio managers, and healthcare strategists with actionable intelligence for 2026 decision-making. This overview outlines the structural dynamics, competitive intensity, and growth trajectory of a niche but rapidly expanding therapeutic segment, while highlighting the methodological rigor embedded in our full report. Readers seeking granular forecasts, distributor-level breakdowns, and scenario modeling will find the complete dataset and strategic frameworks through our official research portal.
Market Trajectory and Historical Context
Elapegademase-lvlr, marketed globally as Revcovi, represents a highly specialized PEGylated recombinant human adenosine deaminase enzyme replacement therapy. Its clinical positioning addresses adenosine deaminase severe combined immunodeficiency (ADA-SCID) across both pediatric and adult populations. Over the past five years, the global market for this therapy has demonstrated consistent expansion, supported by steady clinical adoption, regulatory clarity, and structured reimbursement frameworks in key healthcare systems. Historical revenue progression from 2020 through 2025 reflects a mature yet growth-oriented trajectory, with annualized figures scaling from the low forty-million-dollar range to just above sixty-one million dollars. This upward movement underscores sustained demand drivers, including improved screening protocols, earlier diagnosis pathways, and expanding access to enzyme replacement regimens in specialized clinical settings.
Looking forward, the forecast window through the early 2030s projects continued value accumulation, with compound annual growth rates positioned at a robust 8.5 percent. By the close of the forecast horizon, market revenue is expected to surpass the one-hundred-million-dollar threshold, reflecting both base-case adoption expansion and the incremental impact of supply chain stabilization, dosing optimization, and regional market penetration. For strategic planners, these macro-trends signal more than top-line expansion. They highlight the importance of aligning commercial operations, manufacturing resilience, and payer engagement strategies with a product class that operates under tight clinical constraints, specialized distribution requirements, and concentrated market participation.
Structural Segmentation and Operational Implications
The market architecture for elapegademase-lvlr is defined by distinct operational channels and patient-segment dynamics that directly influence commercial execution. Distribution pathways are heavily weighted toward institutional and specialty pharmacy ecosystems, with hospital pharmacies representing the dominant fulfillment channel and specialty pharmacies capturing a meaningful secondary share. This channel composition reflects the therapy's administration complexity, patient monitoring requirements, and the need for coordinated clinical support services. For manufacturers and distributors, this structure implies that supply continuity, cold-chain or specialized handling protocols where applicable, and clinician-facing education programs are not ancillary considerations. They are central to market access and patient retention.
Worldwide Grazoprevir Market
Patient demographic segmentation further clarifies where commercial emphasis should be concentrated. Pediatric ADA-SCID represents the largest patient cohort by treatment volume, while adult ADA-SCID constitutes a smaller but strategically significant segment. This imbalance has direct implications for long-term therapy management, adherence support, and lifecycle planning. Pediatric cases often involve longer treatment horizons and more intensive coordination across immunology, pediatrics, and genetic counseling services. Adult cases, while numerically smaller, may present differentiated reimbursement conversations, transition-of-care challenges, and distinct clinical monitoring patterns. A successful market strategy must therefore balance cohort-specific service design with enterprise-wide supply and access planning.
Competitive Concentration and Strategic Risk
One of the most defining features of this market is its exceptional concentration. The competitive landscape is dominated by a single principal sponsor, Chiesi Farmaceutici S.p.A., headquartered in Parma, Italy, which markets Revcovi injection worldwide. Chiesi's positioning as the global steward of this PEGylated enzyme replacement therapy places the company at the intersection of product lifecycle management, manufacturing execution, and global access strategy. The concentration levels observed in this segment are unusually high, reflecting the orphan drug nature of the indication, the specialized production requirements, and the limited number of alternative therapeutic pathways for ADA-SCID.
From a strategic standpoint, such concentration creates both advantages and vulnerabilities. On the upside, a focused market architecture can support coordinated clinical communication, streamlined regulatory engagement, and stronger relationships with specialty treatment centers. On the downside, it heightens sensitivity to supply interruptions, manufacturing scale-up challenges, and single-source risk. Industry context from mid-2023 illustrates this dynamic clearly: FDA reporting indicated resupply availability for elapegademase-lvlr injection vials in both 2.5 mg/0.5 mL and 10 mg/2 mL presentations following manufacturing delays. This episode reinforces the importance of redundancy planning, demand forecasting precision, and proactive communication with clinical stakeholders.
For competitors evaluating adjacent opportunities, and for investors assessing portfolio exposure, the market structure suggests that differentiation will likely come from operational excellence, access infrastructure, and service-layer innovation rather than immediate product proliferation. Any strategic entry or partnership must account for the entrenched position of the incumbent sponsor, the specialized manufacturing pathway, and the clinical expectations of centers managing rare immunodeficiency patients.
Regulatory, Reimbursement, and Supply Chain Dynamics
Market dynamics for elapegademase-lvlr are shaped by an intersecting set of regulatory protections, reimbursement pathways, and operational constraints. The product's orphan drug status has historically been reinforced by a seven-year exclusivity framework granted by the FDA around the time of initial approval, extending protective coverage through early October 2025. This exclusivity window has implications for competitive timing, lifecycle planning, and the strategic sequencing of any follow-on development activities. Organizations monitoring the market must track not only current exclusivity boundaries but also the post-exclusivity transition environment, including potential formulation improvements, delivery innovations, or complementary therapy strategies that could alter the value equation over time.
Supply chain conditions have also become a defining element of market behavior. The product entered an FDA-reported shortage situation beginning in late 2022, driven by a combination of increased demand and manufacturing delays. Such disruptions are not merely logistical events. They affect patient continuity, clinical trust, and payer confidence, and they can reshape long-term purchasing and inventory strategies among hospital and specialty pharmacy channels. For market participants, the lessons from this period are clear: resilience must be engineered into the supply chain rather than retrofitted after disruption. That includes visibility into demand signals, manufacturing contingency planning, and coordinated response protocols that minimize interruptions to therapy schedules.
On the reimbursement side, the therapy's eligibility for orphan drug reimbursement pathways under US Medicare Part B reflects an important access enabler. Structured coverage frameworks reduce friction for eligible patients and support predictable revenue flow within the US healthcare system. At the same time, reimbursement strategy cannot be viewed as static. Evolving payer policies, cost-containment pressures, and the growing emphasis on real-world outcomes data mean that manufacturers and market access teams must continually align clinical evidence, health economics narratives, and patient support programs. The interplay between coverage eligibility and commercial execution remains a central strategic lever in this market.
Clinical and safety considerations also influence market dynamics. The prescribing framework includes contraindication guidance for patients with confirmed hypersensitivity to polyethylene glycol. While this is a well-defined clinical parameter, it has operational relevance for patient screening, risk communication, and pharmacovigilance workflows. Organizations operating in this space should ensure that clinical education, pharmacy protocols, and patient-facing materials consistently reflect these constraints to support safe administration and reduce avoidable access barriers.
Commercial Architecture and Payer Strategy
The distribution split between hospital pharmacies and specialty pharmacies suggests a commercial architecture that depends on strong institutional relationships and specialized service delivery. Hospital pharmacies, as the leading channel, are closely tied to inpatient and acute-transition care pathways, clinical protocols, and immunology or transplant-adjacent service lines. Specialty pharmacies, while a smaller share of distribution, often serve as long-term dispensing partners for chronic or maintenance regimens, offering adherence support, patient monitoring coordination, and home-delivery logistics where appropriate. Together, these channels form a complementary access network that requires distinct engagement models.
For commercial teams, this means that sales force deployment, key account management, and patient support infrastructure must be tailored to channel-specific expectations. Hospital-facing strategies may emphasize protocol integration, supply reliability during high-acuity periods, and clinician education. Specialty-pharmacy-facing strategies may prioritize adherence programs, refill continuity, and coordination with prescriber offices for ongoing monitoring. In both cases, the objective is not simply transaction volume. It is sustained therapy continuity for a patient population that depends on reliable access to a highly specialized biologic therapy.
Payer strategy must similarly be calibrated to the realities of orphan drug economics. Coverage pathways exist, but they are embedded within broader cost-management and outcomes-assessment environments. Manufacturers and distributors should therefore invest in evidence-generation plans that address clinical durability, quality-of-life impact, and resource utilization where feasible. Aligning these narratives with payer priorities can strengthen formulary positioning, support consistent reimbursement outcomes, and improve predictability of patient access across treatment settings.
Why the PW Consulting Report Matters for 2026 Decisions
As organizations plan their 2026 priorities, the Worldwide Elapegademase-lvlr Drugs Market Market Research offers a structured foundation for strategic action. The report is designed to translate market-level signals into operational guidance across multiple planning functions. It examines demand drivers, channel behavior, competitive concentration, supply chain vulnerability, reimbursement context, and the regulatory timeline that shapes the product's commercial horizon. Rather than presenting a static snapshot, the analysis emphasizes the dynamic interactions among these forces and their implications for forecasting, capacity planning, access strategy, and risk management.
Decision-makers in manufacturing, commercial operations, market access, and corporate development will find the report especially useful for stress-testing assumptions. The forecast period extends through the early 2030s, allowing readers to evaluate multiple scenarios around supply stabilization, regulatory transitions, channel evolution, and patient-segment growth. This longer view is essential for any organization that must balance short-term execution with medium-term strategic positioning in a concentrated orphan drug market.
Worldwide Elapegademase-lvlr Drugs Market
The full report also includes detailed assessments of competitive positioning, recent supply chain developments, and the regulatory and reimbursement environment that governs market access. These components are integrated to help readers understand not only what is happening in the market, but why it matters for planning, investment, and operational design. Given the high degree of market concentration and the specialized nature of the therapy, even small shifts in supply reliability, reimbursement clarity, or clinical adoption patterns can have outsized effects on commercial performance. The report is built to surface those sensitivities early.
What Is Inside the Full Market Research
The complete PW Consulting report provides a multi-layered examination of the worldwide elapegademase-lvlr market, structured to support both strategic and tactical planning. Key components include a retrospective analysis of historical market performance, a forward-looking forecast through the early 2030s, and an exploration of the structural factors shaping demand and supply. The report details distribution-channel behavior across hospital and specialty pharmacy settings, examines patient demographic patterns across pediatric and adult ADA-SCID treatment, and analyzes the strategic implications of extreme market concentration.
Additional sections address the regulatory and exclusivity environment, reimbursement pathways, supply chain events and their operational consequences, and clinical constraints that influence prescribing and patient management. The report also includes competitive profiling centered on the incumbent global sponsor, with context on market stewardship, product availability dynamics, and the broader orphan drug landscape. Practical frameworks are provided to help readers evaluate entry feasibility, partnership structures, supply resilience strategies, and commercial execution priorities.
For organizations requiring granular planning inputs, the full dataset contains multi-year projections, segment-level context, and analytical tools designed to support scenario planning and sensitivity analysis. These elements are intended to help executives move from high-level market awareness to specific decisions about capacity, commercialization, payer engagement, and risk mitigation.
Conclusion: Positioning for a Concentrated, High-Stakes Orphan Market
The worldwide elapegademase-lvlr market sits at the intersection of specialized biologics, rare disease care, and concentrated commercial execution. Its growth trajectory, channel structure, competitive concentration, and supply chain sensitivity make it a compelling subject for strategic planning in 2026 and beyond. Organizations that approach this space with disciplined forecasting, robust supply resilience, channel-aligned commercial strategies, and proactive payer engagement will be better positioned to navigate its complexities and capture durable value.
PW Consulting's Worldwide Elapegademase-lvlr Drugs Market Market Research is designed to support that effort with rigorous analysis and practical strategic guidance. For full quantitative forecasts, detailed segmentation context, competitive assessments, and scenario-based planning tools, please access the complete report through our official research portal. The insights contained in the full study are intended to help leaders convert market intelligence into executable strategy in a market where precision, continuity, and concentration all matter.
For detailed analysis of this topic, please visit the official page: Worldwide Elapegademase-lvlr Drugs Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Embedded Systems Market Hits $126.5B in 2025, Driven by 6.85% CAGR to $201.1B by 2032
By pmarketresearch, 2026-09-16
Navigating the Embedded System Landscape: Strategic Intelligence for 2026 Decision-Making
The global embedded system market stands at a critical inflection point. As industries increasingly weave intelligent processing into the fabric of everyday products and critical infrastructure, the demand for robust, secure, and efficient embedded solutions has never been more pronounced. For executives, investors, and strategic planners, the period from 2026 through 2032 represents a complex landscape of unprecedented growth opportunities tempered by significant supply chain volatility, evolving regulatory frameworks, and intensifying competition.
PW Consulting's latest Worldwide Embedded System Market study is designed specifically to cut through this complexity. This comprehensive report does not merely present historical data; it offers a forward-looking strategic compass, synthesizing macro-level market trajectories with granular insights into components, applications, and regional dynamics. The following analysis highlights the core strategic value embedded within this research, providing a preview of the intelligence available to guide your organization's decisions in 2026 and beyond.
Market Trajectory: Context for Strategic Planning
Understanding the sheer scale and momentum of the embedded system sector is the first step in calibrating strategic expectations. The market has demonstrated remarkable resilience and expansion over the past five years. Valued at approximately 89,450 million USD in 2020, the market surged to a revenue base of 126,500 million USD by the base year of 2025. This trajectory underscores a sustained acceleration in the adoption of embedded technologies across diverse verticals.
Looking forward, the forecast period from 2026 to 2032 points toward continued robust expansion, driven by the proliferation of IoT devices, the electrification and autonomy of vehicles, and the increasing digitization of industrial processes. The analysis projects a compound annual growth rate (CAGR) of 6.85% over this forecast horizon. By 2032, the market revenue is anticipated to reach a substantial milestone, reflecting the deep integration of embedded intelligence into global manufacturing, healthcare, consumer electronics, and aerospace ecosystems.
While these macroeconomic indicators set the stage, the true strategic value lies in understanding the nuanced drivers behind these numbers. Our report deconstructs this growth, revealing which component segments are capturing the lion's share of investment, which application verticals are outpacing the broader curve, and how geographic dynamics are shifting in response to geopolitical and supply chain factors. The 2026 snapshot provided in the study captures the immediate post-base-year reality, offering a baseline against which all subsequent growth can be measured with precision.
Decoding the Segmented Landscape: Where Value is Created
One size does not fit all in the embedded system market. The strategic allocation of resources depends on a granular understanding of how value is distributed across the ecosystem. The report provides a detailed segmentation analysis that allows decision-makers to benchmark their own market positions and identify whitespace opportunities.
Component Dynamics: Hardware vs. Software
The division between hardware and software is no longer a simple binary. While hardware remains the foundational revenue driver, the software layer is increasingly becoming the differentiator in terms of total cost of ownership, security, and performance optimization. The study quantifies the revenue contribution of each component category, highlighting the interplay between silicon procurement, embedded software development, and the emerging need for integrated hardware-software stacks. Readers will gain clarity on the relative maturity and growth velocity of these segments, enabling more informed decisions regarding R&D investment and vendor partnerships.
Application Verticals: Divergent Growth Engines
Embedded systems are the invisible architecture of modern industry, but the penetration and growth rates vary dramatically by application. Automotive and consumer electronics continue to be massive anchors for the market, driven by advanced driver-assistance systems (ADAS), infotainment, and smart connectivity. However, the industrial sector is undergoing a transformation fueled by machine vision, predictive maintenance, and Industry 4.0 automation. Healthcare is experiencing a surge in demand for wearable diagnostics and implantable devices, while telecommunications and aerospace/defense are demanding ever-higher reliability and performance. This report isolates the revenue dynamics for each of these key application areas, revealing which verticals are converging, diverging, or creating new cross-industry demand.
Regional Perspectives: Global vs. Local
Geography plays a pivotal role in market access and competition. The analysis breaks down revenue contributions across major regions, including North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa. Beyond simple revenue figures, the report contextualizes these splits with insights into regional regulatory environments, supply chain footprints, and the localization of embedded development. Decision-makers can assess regional market saturation, identify high-growth corridors, and understand the strategic implications of shifting manufacturing capabilities.
Competitive Intelligence: Navigating a Dense Vendor Field
The embedded system market is characterized by a diverse array of players, ranging from semiconductor giants to specialized software and connectivity providers. Market concentration data indicates a moderately fragmented landscape, with the top five companies holding a combined share of approximately 28%, and the top three accounting for roughly 18%. This structure suggests that while market leaders exert significant influence, there remains ample room for strategic positioning and competitive differentiation.
PW Consulting's report includes comprehensive profiles of key incumbents and emerging players who are shaping the competitive dynamics. These profiles go beyond basic corporate information, analyzing the specific portfolios, strategic focus areas, and capabilities that define each player's value proposition.
- Semiconductor and Processor Leaders: Companies such as Intel Corporation, Texas Instruments Incorporated, NXP Semiconductors N.V., STMicroelectronics N.V., and Renesas Electronics Corporation are central to the hardware ecosystem. Their strategies around long-life availability, industrial-grade reliability, and automotive-grade solutions are critical for OEMs designing for multi-year product lifecycles.
- Edge AI and High-Performance Computing: Qualcomm Incorporated and NVIDIA Corporation are pushing the boundaries of edge intelligence, offering platforms that bring AI inference and GPU-accelerated computing to embedded and autonomous systems. AMD, Inc. is also expanding its footprint with adaptive computing solutions for high-performance embedded applications.
- Connectivity and Infrastructure: Broadcom Inc. and Samsung Electronics Co., Ltd. contribute essential networking, wireless, memory, and display solutions that integrate deeply into consumer and industrial embedded architectures.
- Specialized Control and Analog Solutions: Microchip Technology Inc. and Analog Devices, Inc. provide critical breadth in microcontrollers, analog mixed-signal processing, and connectivity products that address the precise control and signal integrity needs of industrial and automotive sectors.
- Security and Power Electronics: Infineon Technologies AG and NXP Semiconductors N.V. are increasingly focused on secure microcontrollers and power management, responding to the growing demand for robust embedded security and energy-efficient designs.
Understanding the strategic moves of these companies is essential. The report tracks their product launches, acquisitions, and technology focus, providing the context needed to anticipate supply constraints, technology shifts, and partnership opportunities.
2026 Market Dynamics: Forces Reshaping the Landscape
The embedded system environment in 2026 is defined by a convergence of technological innovation, regulatory pressure, and supply chain realities. Our market dynamics analysis captures these forces in real-time, offering a snapshot of the factors that will influence market execution over the next several years.
Regulatory and Compliance Evolution: The regulatory landscape has become a primary consideration for embedded product design and market entry. The European Union's Cyber Resilience Act, adopted with a transition period, now mandates comprehensive cybersecurity risk assessments, secure development practices, vulnerability handling, and the generation of Software Bill of Materials (SBOM) for hardware and software products bearing CE marking. This regulation extends beyond Europe, setting a de facto standard for global embedded security compliance. Simultaneously, functional safety standards such as ISO 26262 for automotive and IEC 61508 for industrial safety-related systems remain non-negotiable core requirements for safety-critical applications. Furthermore, the ISO/IEC/IEEE 12207:2026 standard provides updated requirements for systems and software engineering processes, aligning technical development with ISO 9001 quality management frameworks. Companies that fail to integrate these regulatory and standardization shifts into their product roadmaps face significant risks of market exclusion and liability.
Supply Chain Volatility and Component Constraints: The availability and pricing of critical embedded components are subject to external market pressures. Notably, RAM and memory prices for embedded systems, particularly LPDDR4X and LPDDR5X variants, have risen sharply. This is driven by the AI-driven reallocation of production capacity by major memory manufacturers, with constraints expected to persist into 2027. This dynamic directly impacts BOM costs and product margins for embedded device manufacturers. The report analyzes the implications of these memory constraints and provides guidance on sourcing strategies, design optimization, and inventory management to mitigate supply-side risks.
Talent Scarcity and Development Methodology Shifts: A growing demand for connected devices is straining the limited pool of skilled embedded engineers. This talent gap is accelerating the adoption of AI-assisted coding tools and model-based design methodologies to maintain development velocity and reduce time-to-market. Organizations that do not adapt their engineering workflows and talent strategies risk falling behind competitors who can rapidly iterate and deploy complex embedded software solutions. The study highlights the implications of this labor dynamic for project planning, outsourcing decisions, and technology selection.
Recent Industry Developments as Strategic Signals: Recent events underscore the pace of change. For instance, developments in ultra-low-power edge AI are highlighted by new SoC architectures targeting multi-GOPS inference at minimal power consumption, reshaping the feasibility of AI capabilities in battery-constrained embedded nodes. In the automotive sector, new I/O interface chips and companion microcontrollers are being launched to support real-time ADAS/AD data acquisition and pre-processing in high-performance embedded computers. Additionally, the condensation of the microcontroller-to-cloud stack through acquisitions that combine Zephyr-based SDKs with Ubuntu Core demonstrates the industry's move toward unified software ecosystems across different silicon vendors. Participation by major distributors and partners at industry events further signals the breadth of new embedded products and demos hitting the market, indicating a vibrant and rapidly shifting product landscape.
The Strategic Utility of This Report for 2026 Decisions
Armed with the insights contained in the Worldwide Embedded System Market study, organizations can make more informed, confident, and strategic decisions across multiple dimensions.
Worldwide Embedded System Market
Market Entry and Expansion Strategy: For companies considering new markets, the segmentation data on applications and regions provides a clear map of where growth is concentrated and where competition is fierce or opportunity is open. The analysis of market concentration helps assess the feasibility of entry strategies, from niche specialization to broader platform plays.
Embedded Systems Market
Product Portfolio and Roadmap Planning: The component analysis and application breakdown enable product leaders to align their development roadmaps with the highest-value segments. Understanding the balance between hardware and software revenue, as well as the specific demands of verticals like automotive, healthcare, and industrial, allows for prioritized investment in the features and capabilities that matter most to customers and regulators.
Risk Management and Supply Chain Resilience: By integrating the analysis of memory price volatility, regulatory mandates like the Cyber Resilience Act, and functional safety standards, the report equips executives with the intelligence needed to build resilient supply chains and compliant product architectures. Early awareness of regulatory requirements and component constraints can prevent costly redesigns and market delays.
Competitive Positioning and Partnership Strategy: The detailed competitive profiles and tracking of recent developments provide a real-time view of the moves being made by key players. This intelligence supports decisions on vendor selection, technology partnerships, and M&A opportunities. It helps organizations anticipate which technologies will become standard and where differentiation can be achieved through unique value propositions or strategic alliances.
Investment and Valuation Context: For investors and financial decision-makers, the market size trajectory, CAGR projections, and segmentation growth rates provide a quantitative foundation for valuation models and investment theses. The report offers the depth required to evaluate the relative attractiveness of different market subsegments and the sustainability of growth across the forecast period.
Conclusion: A Foundation for Informed Strategy
The Worldwide Embedded System Market research from PW Consulting is more than a data repository; it is a strategic asset designed to empower decision-makers in a rapidly evolving global market. By combining macro-level market sizing and forecasts with deep dives into segmentation, competitive dynamics, and real-time industry developments, the report bridges the gap between high-level market awareness and actionable operational intelligence.
As the embedded system ecosystem continues to expand toward 2032, the ability to anticipate regional shifts, regulatory mandates, supply chain disruptions, and technological breakthroughs will define the winners and laggards. The insights provided in this study offer the clarity and confidence needed to navigate these complexities, optimize resource allocation, and capitalize on the substantial opportunities unfolding in the global embedded landscape.
To access the full depth of analysis, including detailed regional breakdowns, component revenue splits, application-specific growth drivers, and comprehensive competitive profiling, we invite you to explore the complete study. The complete report provides the precise data points and nuanced interpretations necessary to translate market intelligence into tangible strategic advantage for your organization in 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Worldwide Embedded System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global CRPG Market Hits $2.54B in 2025, to Reach $3.95B by 2032 at 6.48% CAGR
By pmarketresearch, 2026-09-16
Strategic Horizons: The Worldwide CRPG Games Market Through 2032
The computer role-playing game segment has evolved from a niche enthusiast category into a structurally significant pillar of the global interactive entertainment economy. As narrative depth, player agency, and complex mechanics regain commercial prominence, the CRPG market presents a uniquely resilient demand profile that rewards studios capable of balancing artistic ambition with disciplined production economics. Our newly released Worldwide CRPG Games Market research is designed to give executives, investors, and product leaders a precise analytical foundation for navigating this shifting landscape through 2032.
This report is built for decision-makers who need more than headline revenue figures. It translates historical trajectory, platform allocation, distribution behavior, and competitive intensity into actionable intelligence for portfolio strategy, pipeline prioritization, capital allocation, and go-to-market planning. The following overview outlines the analytical framework, the strategic questions the research answers, and why the 2026 planning cycle makes this intelligence especially timely.
Market Trajectory and the Reshaping of Demand
Over the historical review window from 2020 through 2025, the worldwide CRPG market expanded from approximately USD 1,350.5 million to USD 2,540.0 million, reflecting an acceleration that outpaced earlier expectations. That trajectory was not simply a function of a single breakout release; it emerged from converging demand shifts, including renewed interest in deep narrative systems, stronger audience willingness to invest in premium single-player experiences, and expanding modding ecosystems that extend product lifecycles.
Looking forward across the 2026 to 2032 forecast period, the research projects sustained growth with a compound annual growth rate of 6.48 percent. The market is forecast to reach approximately USD 2,801.97 million in 2026 and continue climbing toward USD 3,947.12 million by 2032. Importantly, this path reflects a maturing category rather than a speculative bubble. The growth curve indicates a market increasingly shaped by franchise continuity, post-launch engagement, and distribution choices that determine how effectively studios monetize long-tail audiences.
For enterprise planning, the strategic implication is clear: CRPG demand is becoming more predictable in direction but more complex in execution. Companies that rely solely on broad genre assumptions will miss the structural nuances that separate durable franchises from short-lived hype cycles.
What the Research Covers and Why It Matters for 2026 Decisions
The Worldwide CRPG Games Market study was engineered to support practical strategic use rather than abstract market description. Its scope spans historical performance mapping, forward-looking demand modeling, segmentation analysis, competitive profiling, and infrastructure-adjacent market dynamics that increasingly shape digital entertainment Economics.
Executives can use the report to answer core questions such as:
- How should organizations size their exposure to CRPG development, publishing, or adjacent service opportunities over the next planning cycle?
- Which platform and distribution behaviors signal durable monetization versus temporary concentration?
- Where do competitive pressures intensify most quickly, and what does that mean for differentiation strategy?
- How do infrastructure, data regulation, and chip availability trends affect development roadmaps and operational cost assumptions?
The report integrates these questions into a decision-oriented structure. Rather than presenting isolated statistics, it contextualizes market sizing within the behaviors that drive value: player retention, franchise lifecycle management, digital distribution dominance, and the strategic choices studios make when balancing scope, narrative complexity, and release cadence.
Segmentation Insight: Platform, Distribution, and Regional Structure
Segmentation is where the CRPG market becomes especially instructive. The research breaks down revenue behavior across platform environments, distribution channels, and regional demand patterns, allowing stakeholders to see where value concentrates and where structural shifts are underway.
Worldwide Roguelike Game Market
Platform allocation reveals a market still strongly anchored by PC, with consoles representing a substantial secondary base and mobile and handheld devices forming a smaller but strategically relevant segment. This configuration matters because platform choice affects design scope, release timing, audience acquisition cost, and post-launch support models. It also influences how studios plan cross-platform ambitions versus platform-specific optimization. The full segmentation detail in the report allows teams to benchmark platform exposure and model scenario outcomes without relying on assumptions from adjacent genres.
Distribution channel analysis similarly shows a market defined by digital downloads as the dominant commercial pathway, with physical retail maintaining a much smaller footprint. The strategic significance lies not only in the scale difference but in what it implies for logistics, pricing flexibility, direct consumer relationships, and the economics of recurring content updates. Companies evaluating publishing partnerships, storefront strategy, or bundled release models can use the segmentation framework to assess which channel dynamics will shape margin and visibility.
Regional analysis further sharpens the picture by identifying where demand exerts the strongest pull. North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa each present distinct market characteristics, audience expectations, and go-to-market considerations. These regional patterns interact with platform habits, pricing sensitivity, localization priorities, and infrastructure conditions. The report provides regional context in a way that helps strategy teams align development, marketing, and investment decisions with demand geography without overgeneralizing in ways that lead to inefficient resource allocation.
To protect the analytical integrity of the research, granular regional and platform split percentages and exact sub-segment revenue figures are reserved for the full study. This allows the published introduction to demonstrate methodological rigor while ensuring that clients who depend on precise planning parameters are directed to the complete dataset for execution-level work.
Competitive Landscape and Strategic Positioning
CRPG competition is defined less by pure scale than by franchise identity, narrative credibility, system depth, and the ability to sustain active communities over time. The report profiles a range of influential developers and publishers whose approaches illustrate different viable strategies within the category.
Larian Studios demonstrates the commercial power of narrative-driven, choice-rich CRPG design paired with strong post-launch engagement. Obsidian Entertainment highlights the value of dialogue-heavy storytelling and branching narrative systems that cultivate dedicated audiences. BioWare remains associated with cinematic, companion-centered RPG experiences and moral-choice frameworks that influenced broader audience expectations for the genre. CD Projekt Red illustrates the scale achievable through open-world CRPG design with mature themes and strong player agency, along with the operational complexity such ambition entails.
The competitive set also includes studios with more specialized strategic positions. inXile Entertainment reflects sustained interest in classic-style, isometric, party-based design. Owlcat Games shows how licensed intellectual property can be translated into deep CRPG experiences with strong strategic and narrative mechanics. Tactical Adventures underscores demand for turn-based systems inspired by tabletop frameworks. Paradox Interactive bridges grand strategy and role-playing mechanics in ways that expand the definition of audience overlap. Bethesda Game Studios represents expansive open-world design with strong modding ecosystems and player freedom. Square Enix contributes a global publishing and development perspective tied to narrative-heavy RPG output with CRPG influences across certain titles.
Recent developments reinforce how active this competitive field remains. Owlcat Games advanced development on Warhammer 40,000: Dark Heresy with alpha and beta signals and expanded party-based mechanics. Tactical Adventures announced Solasta II with larger environments, refined storytelling, and broader D&D-inspired worldbuilding. Larian Studios continued post-launch support for Baldur's Gate 3, demonstrating how sustained updates and modding pathways can maintain active audience engagement within the CRPG segment.
From a strategy perspective, these moves matter because they reveal how studios balance originality, licensing, sequel development, and community retention. The report uses these examples not as promotional highlights but as strategic evidence points within a broader competitive intensity framework. Market concentration is also examined through a structured lens, showing how competitive share is distributed and where consolidation risk, differentiation opportunity, and audience loyalty converge. Exact concentration metrics beyond the top-level concentration overview are reserved for the full report so that stakeholders can evaluate positioning with the precision required for partnership, investment, and launch planning.
Infrastructure and Regulatory Forces Shaping the Next Cycle
CRPG market strategy cannot be separated from the operational environment in which games are built, distributed, and maintained. The report integrates current industry-context dynamics that increasingly affect cost structures, release feasibility, and regional deployment decisions.
One important backdrop is the pressure on digital infrastructure. Primary North American data center supply increased 36 percent year-over-year to 9,432 MW in 2025, supported by record net absorption of 2,497.6 MW driven by hyperscale demand relevant to game distribution and online features. At the same time, vacancy rates in key North American data center markets reached a record low of 1.4 percent at the end of 2025, limiting large-scale deployments for digital entertainment platforms. The strategic implication is that infrastructure availability and cost conditions can influence hosting plans, online service scaling, update delivery, and broader digital ecosystem planning.
Regulatory forces are equally consequential. Data sovereignty and privacy regulations are driving demand for local or edge data center deployments to comply with cross-border data flow restrictions. In parallel, U.S. export controls on high-performance AI chips are affecting hardware availability for data centers that support game development and cloud features, influencing regional deployment strategies. For CRPG stakeholders, these conditions do more than raise costs; they shape where and how online features, distribution infrastructure, and development pipelines can be scaled.
These factors are included in the report because they connect market opportunity to execution risk. A CRPG strategy that ignores infrastructure constraints or regulatory exposure may overestimate flexibility in digital service design, regional launch sequencing, or post-launch content delivery. By embedding these dynamics into the market analysis, the research gives leaders a more realistic operational frame for planning in 2026 and beyond.
How Organizations Should Use This Research
The Worldwide CRPG Games Market study is intended to support several practical applications. Product and portfolio teams can use it to validate demand assumptions, assess whether proposed CRPG investments align with category trajectory, and benchmark scope decisions against segment realities. Publishing and distribution leaders can use the segmentation and channel analysis to refine storefront strategy, launch sequencing, and digital-versus-physical planning. Investment and business development teams can use the competitive profiling and concentration context to evaluate partnership opportunities, acquisition rationale, and market entry risk.
Worldwide CRPG Games Market
The report also supports scenario thinking. Because CRPG growth is not uniform across platforms, regions, and distribution behaviors, organizations benefit from understanding where resilience is strongest and where volatility may emerge. The 2026 to 2032 forecast framework provides a forward view that can anchor multi-year roadmaps without creating overconfidence in linear outcomes.
Clients relying on the full dataset can further drill into the exact split structures, sub-segment comparisons, and concentration detail needed for quantitative modeling. That is why the complete report is structured to serve both strategic orientation and operational precision.
Conclusion: Why the 2026 Planning Window Is Critical
The CRPG market has entered a phase where narrative quality, system depth, community longevity, and infrastructure-aware planning all influence commercial outcomes. With a forecast CAGR of 6.48 percent and a projected market trajectory from approximately USD 2,801.97 million in 2026 toward nearly USD 3,947.12 million by 2032, the opportunity is real, but so is the need for disciplined segmentation, competitive intelligence, and operational awareness.
This research is designed to help organizations move from general confidence in the category to specific, defensible decisions. The introduction provided here establishes the strategic logic and analytical depth of the study; the full market research delivers the detailed figures, segment-level breakdowns, and competition-specific intelligence necessary for execution. For leadership teams preparing CRPG-related strategy in 2026, the complete report offers the evidence base needed to prioritize investment, shape pipeline direction, and anticipate the infrastructure and regulatory conditions that will increasingly define market performance.
For detailed analysis of this topic, please visit the official page: Worldwide CRPG Games Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com