

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Cell Controller Market Reaches $745.5M in 2025, Projected at 8.45% CAGR to 2032

The Worldwide Cell Controller Market: Strategic Imperatives for the 2026–2032 Horizon
The global transition toward electrification, smart manufacturing, and advanced energy storage is fundamentally reshaping the architecture of power management systems. At the core of this transformation lies the cell controller—a critical component responsible for monitoring, balancing, and safeguarding individual battery cells within complex packs. As industries from automotive to aerospace demand higher energy density, longer cycle life, and uncompromising functional safety, the cell controller market has evolved from a niche engineering requirement into a standalone strategic growth vector. Our newly published Worldwide Cell Controller Market research delivers a comprehensive, data-rich panorama of this transition, offering enterprise leaders the clarity needed to navigate an increasingly complex competitive and regulatory landscape through 2032.
This analysis is not merely a retrospective ledger of growth figures. It is a forward-looking strategic instrument designed to inform capital allocation, product roadmap decisions, supply chain resilience planning, and partnership strategies. By synthesizing historical performance, macro-industry tailwinds, and emerging technology paradigms, the report provides a structured framework for executives who must act decisively in a market defined by rapid innovation cycles and stringent safety mandates.
Macro Trajectory and Growth Architecture
The cell controller market has demonstrated consistent upward momentum over the past half-decade, reflecting the broader acceleration of battery-dependent applications across multiple verticals. Historical revenue data from 2020 through 2025 reveals a structured expansion trajectory, with the market scaling from approximately 498 million USD in 2020 to an estimated 745.5 million USD by 2025. This historical baseline establishes a clear inflection point, setting the stage for a forecast period that projects continued, though progressively maturing, growth.
Our forward-looking projections for 2026 through 2032 indicate that the market will surpass the 849 million USD threshold in 2026 and continue its ascent toward an estimated 1.315 billion USD by the end of the forecast window. The compound annual growth rate across this period is calculated at 8.45 percent, a figure that reflects both sustained demand pull and the incremental penetration of advanced cell monitoring architectures in legacy and emerging applications alike. This growth rate is neither speculative nor overly conservative; it emerges from a careful reconciliation of deployment forecasts, supply-side capacity expansions, and the gradual standardization of high-channel-count controller topologies across diverse industrial and automotive platforms.
The revenue trajectory underscores a market that is moving beyond early-adopter saturation into broader industrial adoption. As battery pack architectures grow in complexity—incorporating higher series cell counts, tighter thermal tolerances, and integrated communication layers—the reliance on precision cell controllers becomes a structural requirement rather than an optional enhancement. This shift is visibly reflected in the steady year-over-year revenue increments observed throughout the forecast horizon, signaling that demand is being driven by both volume expansion and architectural upgrades in existing installations.
Structural Segmentation and Application Diversification
While the aggregate market figures provide directional clarity, the true strategic value of this research lies in its granular segmentation framework. The report dissects the market across multiple analytical dimensions, enabling executives to identify where growth is concentrating, which application verticals are driving incremental adoption, and how regional deployment patterns are evolving. The segmentation analysis reveals a market that is no longer monolithic; it is increasingly defined by divergent adoption curves, distinct regulatory pressures, and varying performance thresholds across sectors.
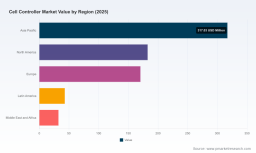
By examining regional distribution patterns, the report highlights how manufacturing footprints, localized supply chain strategies, and region-specific electrification mandates are shaping demand geography. Historical and projected revenue distributions across major geographic zones illustrate where infrastructure investment, automotive production scaling, and industrial battery deployment are converging to create sustained procurement cycles. These regional insights are critical for companies evaluating market entry strategies, localizing production capabilities, or optimizing logistics and distributor networks.
The application-side segmentation further clarifies where cell controller integration is becoming mission-critical. High-voltage battery management in mobility and energy storage, precision monitoring in semiconductor and electronics manufacturing, and safety-critical deployments in aerospace and defense represent distinct adoption profiles, each with 고유한 performance expectations and compliance burdens. Additional verticals, including food and beverage processing and specialized industrial use cases, contribute incremental but strategically meaningful demand, particularly where battery-backed control systems must meet stringent operational reliability standards. The report maps these application pathways in detail, enabling readers to assess where their existing product portfolios align with market needs and where adjacent opportunities may be underpenetrated.
A type-based breakdown distinguishes between hardware-centric controller solutions and the expanding domain of software and services that accompany modern battery management architectures. As cell controllers become more integrated into broader system-level diagnostics, remote monitoring, and predictive maintenance workflows, the service and software layer is increasingly contributing to total addressable value. This bifurcation is essential for suppliers deciding whether to compete purely on silicon performance or to build differentiated value through integrated firmware, calibration services, and system-level validation support.
Competitive Landscape and Strategic Positioning
The cell controller ecosystem is characterized by a relatively concentrated leadership tier, yet it remains open to innovation-driven differentiation. Market concentration indicators suggest that a limited number of established players command a substantial share of revenue, but the competitive environment is far from static. Continuous architectural improvements, functional safety certifications, and ecosystem partnerships are actively reshaping positioning. Our report provides a detailed competitive profiling framework that moves beyond headline market shares to examine how leading firms are structuring their technology roadmaps, securing supply chain advantages, and aligning with end-market compliance requirements.
NXP Semiconductors has maintained a prominent role in the cell controller space, offering a broad portfolio of battery cell controller ICs that span multiple safety and channel-count requirements. Its product families, including the MC3377x series and the BMA7318/BMA7518 18-channel architectures, reflect a deliberate strategy centered on high-voltage battery management systems for electric vehicles, energy storage systems, and 48V platform applications. These solutions emphasize daisy-chain communication, precision voltage and temperature monitoring, cell balancing, and rigorous functional safety integration. The recent introduction of the BMx7318/7518 family in mid-2025 further illustrates this trajectory, delivering per-channel dedicated ADCs, hardware alarm capabilities for overcurrent scenarios, and compliance aligned with ASIL-C and SIL-2 standards. This launch signals a continued commitment to supporting both automotive and industrial customers who require scalable, safety-certified monitoring hardware.
Texas Instruments continues to compete through its battery management system IC portfolio, with cell controller solutions such as the BQ79616 family supporting cell monitoring, balancing, and communication across automotive and industrial battery packs. TI’s approach emphasizes integration, manufacturability, and broad ecosystem compatibility, positioning its devices as foundational elements in pack-level architectures that require reliable communication and balanced charge-discharge performance.
Cell Fenders Market
Analog Devices contributes to the landscape through precision monitoring and controller ICs designed for high-voltage battery management applications. Its controller families focus on accurate voltage, temperature, and current measurement, supporting system designs that demand tight tolerance management and robust diagnostics. In markets where measurement fidelity directly influences pack longevity and safety margins, ADI’s positioning reflects a clear emphasis on performance-grade instrumentation integrated into controller architectures.
Beyond silicon suppliers, the competitive ecosystem also includes tooling and validation providers such as dSPACE, which offers Cell Controller Virtualization solutions for testing and simulation of battery management systems. By supporting controller validation across multiple hardware providers, dSPACE illustrates how the market is expanding beyond component manufacturing into system-level test infrastructure. This development is significant for enterprises seeking to reduce validation cycles, de-risk functional safety certification, and accelerate time-to-market for complex battery pack designs.
The report’s competitive analysis extends beyond company profiles to examine how these players interact with regulatory frameworks, standard-setting bodies, and downstream system integrators. Understanding these relationships is essential for executives evaluating partnership opportunities, assessing supplier risk, or planning acquisitions and technology licensing strategies.
Regulatory and Technical Dynamics Shaping Adoption
Market growth in cell controllers cannot be analyzed in isolation from the regulatory and technical standards that govern battery system design. Functional safety requirements have become a defining architectural constraint, particularly in automotive applications where battery management systems must align with ISO 26262 expectations. Many contemporary cell controller devices are engineered to support ASIL-C or ASIL-D compliance, incorporating built-in diagnostics, fault detection mechanisms, and fail-safe communication pathways. This safety-centric design philosophy is no longer optional for high-voltage applications; it is a baseline procurement requirement that directly influences component selection and system architecture decisions.
Parallel standards such as ISO 12405-3 and ISO 12405-4 further codify performance and safety expectations for electrically propelled road vehicles, explicitly referencing cell electronics and controller functions for monitoring and balancing. As these standards continue to shape engineering practices and certification processes, suppliers that can demonstrate measurable alignment with established protocols gain a meaningful advantage in qualifying for Tier-1 and OEM procurement pipelines. The research examines how these regulatory touchpoints are influencing product development cycles, validation methodologies, and market entry timing across different application segments.
In addition to safety standards, communication architecture has emerged as a critical technical differentiator. Modern battery management systems increasingly rely on isolated daisy-chain communication protocols and transformer-based physical layers to maintain signal integrity across large cell strings. This design approach supports reliable operation in high-noise electrical environments and enables scalable pack configurations that may incorporate hundreds of cells per series. The report evaluates how communication topology choices affect system cost, thermal design, fault isolation, and overall pack reliability, providing context for engineering leaders evaluating next-generation controller deployments.
Operational Content and Decision-Executing Frameworks
A market intelligence report is only as valuable as the operational clarity it provides. Accordingly, this research is structured to translate macro trends into actionable decision support. The publication includes detailed historical and forecast data tables, allowing readers to model revenue scenarios, track growth velocity, and benchmark internal performance against market trajectories. Segmentation breakdowns are presented across region, type, and application dimensions, enabling targeted analysis for product managers, regional sales directors, and strategic planning teams.
The report also provides competitive profiling, recent development tracking, and regulatory mapping, ensuring that readers can connect technical evolution with commercial implications. Recent product launches, functional safety certification milestones, and system-level validation innovations are contextualized within broader adoption patterns, helping executives anticipate where supplier capabilities are heading and how procurement requirements may shift. Strategic frameworks are embedded throughout the analysis to support use cases such as market entry assessment, portfolio gap analysis, supply chain localization planning, and partnership identification.
By combining quantitative market architecture with qualitative competitive and regulatory context, the publication is designed to serve as a reference point for cross-functional decision-making. Engineering leadership can use the segmentation and standard-compliance sections to guide architecture choices; commercial teams can leverage regional and application breakdowns to prioritize go-to-market resource allocation; and executive leadership can rely on the forecast trajectory and concentration analysis to inform long-term investment thesis development.
Why This Research Matters for 2026 Decision-Making
The 2026–2032 period will be defined by the maturation of battery system architectures, the tightening of safety and performance expectations, and the continued expansion of cell controller adoption beyond early-adopter verticals. Enterprises that enter this window with fragmented market intelligence risk misallocating R&D focus, underestimating compliance-driven procurement shifts, or overlooking regional demand concentrations that could shape revenue timing. This research was developed to close that intelligence gap.
Worldwide Cell Controller Market
The strategic value of the report lies in its ability to connect high-level growth data with the operational realities of product planning, supplier evaluation, and market prioritization. It does not simply report that the market is expanding; it explains where that expansion is concentrating, which technical and regulatory forces are accelerating adoption, and how the competitive field is evolving in response. For organizations operating in automotive electrification, energy storage integration, industrial battery deployment, or precision electronics manufacturing, the insights contained here are directly applicable to roadmap alignment and risk mitigation.
The complete dataset, segmentation detail, competitive profiles, and scenario-ready forecasting tables are available in the full Worldwide Cell Controller Market research publication. We invite executives, strategy teams, and industry analysts to access the complete report for the comprehensive intelligence required to make confident, evidence-based decisions in the 2026 planning cycle and beyond.
For detailed analysis of this topic, please visit the official page: Worldwide Cell Controller Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com