

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Condensation Silicone Rubber Market Hits $2.25 Billion in 2025, Projects 4.82% CAGR to 2032

Strategic Horizons for the Global Condensation Cure Silicone Rubber Market: Navigating the 2026 to 2032 Era
The industrial materials landscape is entering a pivotal consolidation phase, and nowhere is this more evident than in the condensation cure silicone rubber (CCSR) sector. Our latest Worldwide Condensation Cure Silicone Rubber Market research report delivers the definitive intelligence framework required to navigate the forecast period from 2026 through 2032. For procurement directors, R&D strategists, and market expansion leaders, this study transforms macroeconomic signals into executable roadmaps, enabling precise capacity positioning, pricing architecture design, and competitive maneuvering in a market defined by steady structural growth and evolving technological trade-offs.
The condensation cure segment occupies a distinct competitive position within the broader elastomers ecosystem. Its room-temperature vulcanizing (RTV) characteristics, cost-effective tin-catalyzed chemistry, and proven compatibility with casting, molding, and sealant workflows continue to drive sustained demand across advanced manufacturing, construction, and specialized industrial applications. Understanding where this value chain is heading requires more than headline figures; it demands a rigorous dissection of historical trajectory, forward-looking velocity, regional polarization, product architecture shifts, and the dynamic pressures of raw material economics and regulatory evolution.
The Macro Trajectory: From Consolidation to Accelerated Expansion
Historical data reveals a market that has successfully weathered cyclical volatility to establish a robust baseline. Between the early baseline years and 2025, global revenue demonstrated clear upward momentum, reflecting sustained downstream adoption and manufacturing efficiency gains. The current market year has already settled into a trajectory that positions the sector for predictable expansion. Looking ahead, our forecast modeling outlines continued growth through 2032, supported by compounding demand from high-durability sealing solutions, precision mold making, and industrial maintenance workflows.
- The market has evolved from post-pandemic recalibration to a phase of measured, high-confidence scaling.
- Forecast modeling captures a compound annual growth rate that underscores steady structural expansion rather than speculative hype.
- Revenue progression across the decade points toward sustained valuation appreciation, creating clear windows for market share capture and premiumization strategies.
Absolute Scale and Growth Velocity: The Numbers That Redefine Opportunity
The financial architecture of this market provides a compelling foundation for long-term investment and commercial planning. At its historical baseline, the sector commanded a substantial global valuation measured in billions of dollars, confirming its entrenched role across multiple industrial verticals. By the current market year, revenue figures reflected both recovery resilience and expanded application penetration, setting a higher floor for the forecast horizon.
Silicone Resin Market
As we project forward, the market is positioned to traverse a multi-year expansion corridor, reaching a significantly elevated valuation by the end of the forecast window. The compound annual growth rate of the period translates into a powerful compounding effect, where territorial diversification, product line extensions, and application migration can amplify realized returns far beyond aggregate market growth. For strategic planners, this backdrop validates disciplined capacity allocation, targeted geographic entry, and formulation innovation as core value-creation levers.
Regional Polarization: Where Demand Converges and Where It Diversifies
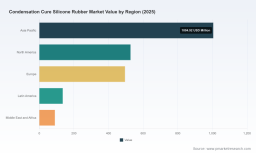
Geographic demand distribution reveals a market that is simultaneously concentrated and diversifying. Asia Pacific commands the largest share of global revenue, driven by dense manufacturing ecosystems, expansive construction activity, and rapidly scaling production of molding and casting applications. North America and Europe maintain strong secondary positions, characterized by higher value-add specialization, stringent performance requirements in electronics and automotive-adjacent workflows, and mature maintenance-repair-overhaul (MRO) channels. Meanwhile, Latin America and the Middle East and Africa represent emerging expansion vectors, where infrastructure development and localized industrial supply chains are progressively unlocking new consumption nodes.
This geographic architecture carries a crucial strategic implication: competitive advantage no longer belongs solely to the largest aggregate player. It belongs to organizations that understand regional pricing elasticity, regulatory nuance, supply chain proximity, and application-specific formulation preferences. The report maps these regional demand signatures in detail, equipping stakeholders with the context required to align distribution footprints, formulation localization, and channel partnerships with the territories that offer the highest marginal returns.
Product Architecture and Application Migration: The Battlefield of Differentiation
The condensation cure market is structurally divided between one-component and two-component RTV systems, each serving distinct performance and processing philosophies. One-component formats continue to dominate in ease-of-use workflows, rapid deployment scenarios, and applications where operational simplicity outweighs the need for advanced formulation tuning. Two-component systems, by contrast, offer enhanced control over cure kinetics, depth-of-cure performance, and mechanical property optimization, making them the preferred architecture for precision tooling, demanding casting processes, and environments where cure inhibition sensitivity must be managed.
On the application side, demand concentration is both revealing and instructive. Mold making and tooling remains a central pillar, reflecting the enduring need for high-tear-strength, dimensionally stable elastomeric matrices in casting workflows ranging from wax and gypsum to urethane, epoxy, and polyester resins. Construction sealants form another major demand block, driven by durability requirements in architectural and infrastructure contexts. Electronics and electrical potting represent a high-growth specialization, where encapsulation reliability and thermal-responsiveness considerations continue to attract material innovation. Automotive components and general industrial maintenance round out the application footprint, providing steady-replacement demand streams that stabilize revenue during cyclical fluctuations.
The strategic question for formulators and distributors is not simply which segment is larger, but which segment offers the steepest trajectory for margin expansion, technical differentiation, and barrier creation. The report isolates these migration patterns and maps the competitive inflection points where formulation leadership can be converted into durable commercial advantage.
The Competitive Field: Who Is Defining the Next Standard of Performance
The competitive environment is defined by a blend of specialized formulators, regional manufacturing strength, and multinational technology presence. The market exhibits a moderately concentrated structure, with the top three players commanding a significant combined share and the top five extending that influence further. This concentration creates both a challenge and an opening: incumbents maintain formidable distribution, technical support, and formulation ranges, but the remaining share is large enough to reward focused differentiation, especially in application-specific customization, cure-time modulation, and localized service models.
Several companies illustrate the archetypes shaping market behavior. Smooth-On, Inc. has built a deep reputation around tin-cure mold rubbers, with product families engineered for varied hardness requirements and broad compatibility with casting materials. Polytek Development Corp. emphasizes flexible mold making with formulations noted for high tear strength and favorable release characteristics, alongside lower sensitivity to cure inhibition relative to addition-cure alternatives. Silicones, Inc. has maintained a long-standing focus on condensation cure RTV-2 silicones, offering both standard and custom formulations across mold-making, electronics potting, and special effects use cases.
CHT Group contributes a European formulation perspective, supplying condensation cure silicones for moulding applications compatible with a wide spectrum of casting substrates, plus catalysts and thixotroping agents for property modification and custom development. BBN Materials Co., Limited reflects the expanding capabilities within China's specialty silicone ecosystem, concentrating on tin-cured mold making for crafts, candles, soaps, resin, GFRC, and concrete products, with customizable operation and curing times. Silpak, Inc. continues to produce two-component condensation-cure RTV systems that deliver high-strength room-temperature curing for mold making and allied applications.
Worldwide Condensation Cure Silicone Rubber Market
On the global technology side, Elkem Silicones offers polycondensation tin-kit condensation cure silicones suitable for architectural molding, including plaster, gypsum, and concrete applications. Shin-Etsu Chemical Co., Ltd. extends its broad silicone portfolio with two-component condensation cure RTV rubbers, including rapid cure types and high-thermal-stability one-component grades. Momentive Performance Materials rounds out the competitive field with condensation cure RTV silicones tailored for mold making rubber applications, supported by catalyst systems that influence cure behavior and processing consistency.
These firms collectively demonstrate that performance leadership is increasingly defined by application engineering, cure robustness, and the ability to customize formulation parameters to user workflows. The report translates these competitive dynamics into actionable intelligence, mapping strategic positioning, capability overlaps, and whitespace opportunities for entrants and incumbents alike.
Raw Material Economics and Regulatory Flux: The Hidden Cost Structures
Market growth does not occur in a vacuum. Recent industry context signals point to tightening cost structures and regulatory complexity that are reshaping upstream economics and downstream margin expectations. Industrial-grade silicone oil prices in China have shown a moderate upward trend, with high-viscosity and modified grades commanding premium levels, driven by rising feedstock costs. D4 price movements have contributed meaningfully to higher production costs for silicone-based materials, including condensation cure systems. This input pressure interacts with broader cost dynamics in catalyst supply, packaging, and logistics, placing renewed emphasis on formulation efficiency and value engineering.
Simultaneously, stricter environmental policies have impacted silicone production costs and supply conditions in key manufacturing regions. For buyers and producers, this means resilience planning is no longer optional. Dual-sourcing strategies, regional inventory buffering, and formulation adaptability are becoming essential components of cost-containment roadmaps. Companies that can maintain performance consistency while navigating input volatility will capture disproportionate share in markets where competitors face throughput constraints or margin compression.
What the Report Delivers: The Operational Intelligence You Need
This study is designed as an execution-focused intelligence package rather than a static market snapshot. It provides a full historical-to-forecast value chain view, segmentation architecture across regions and product types, application-level demand mapping, and competitive profiling that connects corporate capabilities with market behavior. Procurement teams will gain clarity on volume trajectory, pricing pressure indicators, and regional sourcing considerations. R&D and formulation leaders will receive the structural context needed to prioritize cure optimization, inhibition management, and application-specific property tuning. Commercial and strategy teams will obtain the geographic and segment insights required to evaluate market entry, channel expansion, and customer-facing value propositions.
From Insight to Advantage: Why 2026 Decisions Depend on This Research
The condensation cure silicone rubber market is entering a phase where steady aggregate expansion will be matched by sharper competitive differentiation, regional complexity, and input-driven cost sensitivity. Organizations that act on incomplete intelligence risk misallocating capacity, undervaluing application-specific niches, or underestimating the strategic impact of raw material and regulatory shifts. Our Worldwide Condensation Cure Silicone Rubber Market report closes that intelligence gap by converting macro trends into precise operational guidance.
For decision-makers preparing for the 2026 planning cycle, this research offers the evidence base needed to align investment timing, commercial positioning, formulation strategy, and regional execution with the market's most probable trajectory. The full analysis, including granular segmentation, competitive benchmarking, and forward-looking scenario framing, is available through our complete report. Access the detailed intelligence now and position your organization to convert market momentum into durable strategic advantage.
For detailed analysis of this topic, please visit the official page: Worldwide Condensation Cure Silicone Rubber Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com