

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Report: Global Alternate Light Sources Market to Hit $694.05M by 2032 with 5.72% CAGR

Strategic Intelligence in the Worldwide Alternate Light Sources Market: A 2026 Decision Framework
The global landscape for Alternate Light Sources (ALS) is undergoing a period of structural refinement, driven by sustained demand across forensic, medical, and industrial applications. As enterprises navigate an environment defined by technological maturation and regulatory standardization, the necessity for precise, forward-looking market intelligence has never been more critical. PW Consulting's latest Worldwide Alternate Light Sources Market research study offers a comprehensive strategic lens designed specifically to inform high-stakes corporate decisions throughout 2026 and beyond.
This analysis serves as a foundational brief for executive teams, product strategists, and investment committees seeking to align their portfolios with the evolving dynamics of the ALS sector. By synthesizing historical performance data, forward-looking projections, and granular competitive profiling, the report eliminates the ambiguity that often plagues strategic planning in specialized lighting and photonics markets.
Macro-Market Trajectory and Growth Dynamics
Understanding the baseline momentum of the alternate light sources industry is the first step in any robust strategic assessment. Our research tracks the market's revenue evolution from the base year of 2025 backward through 2020, while simultaneously projecting performance through the forecast horizon of 2032. The data reveals a consistent expansion trajectory that reflects both steady historical adoption and anticipated future acceleration.
Between 2020 and 2025, the worldwide ALS market demonstrated resilient growth, climbing from an aggregate revenue baseline of approximately USD 365 million to a 2025 valuation of nearly USD 471 million. This historical progression underscores the technology's transition from specialized niche equipment to broader operational staples within law enforcement agencies, clinical diagnostic facilities, and quality assurance laboratories. The market's momentum carries forward into the forecast period, with 2026 expected to mark a significant inflection point as the aggregate valuation surpasses the USD 507 million threshold.
Looking across the full forecast window extending to 2032, the compound annual growth rate (CAGR) is calculated at 5.72 percent. This sustained growth profile suggests that market expansion will be characterized by methodical, dependable increases in procurement spend rather than volatile spikes. By the end of the decade, revenue projections indicate that the market will approach an annual valuation exceeding USD 600 million, with continued upward pressure through the early 2030s as next-generation portable systems and laboratory-grade multi-spectral platforms gain deeper integration into standard operating procedures worldwide.
Demand Drivers Shaping the 2026 Horizon
Several converging factors are positioning the ALS sector for continued relevance and procurement growth during 2026. The interplay between regulatory standardization, operational efficiency requirements, and technological miniaturization is reshaping how end-users evaluate and deploy alternate light solutions.
- Regulatory and Standardization Tailwinds: Industry definitions and equipment classifications are becoming increasingly formalized. For instance, authoritative bodies now formally recognize alternate light sources as specialized equipment designed to produce light at precise wavelengths to enhance or visualize potential evidentiary items. Simultaneously, portable forensic light kits—which must integrate an alternate light source, a barrier filter, a dedicated power source, and a carrying case—have been codified within recognized authorized equipment listings for law enforcement crime scene operations. These standardization efforts reduce procurement ambiguity and create clearer pathways for vendor qualification.
- Operational Protocol Evolution: Professional guidelines are increasingly specifying how ALS technologies should be deployed in low-light documentation scenarios. Established protocols now emphasize controlled photographic conditions, including tripod mounting, manual or aperture-priority exposure modes, and strict adherence to wavelength-specific eye protection requirements. These standards elevate the importance of purchasing certified, guideline-compliant equipment rather than ad-hoc lighting solutions, thereby strengthening the addressable market for professional-grade ALS providers.
- Safety and Compliance Emphasis: As shortwave UV configurations remain widely utilized for evidence detection and specialized inspection tasks, manufacturers and procurement officers alike are placing greater weight on integrated safety features. Vendor documentation increasingly highlights mandatory eye and skin protection protocols, reinforcing the market's shift toward systems that bundle protective accessories and operator training materials alongside core illumination hardware.
Report Scope and Operational Content Architecture
The Worldwide Alternate Light Sources Market research deliverable is structured to provide actionable intelligence rather than abstract market commentary. PW Consulting's analytical framework ensures that every section of the report translates directly into executable strategy for product development, regional expansion, pricing optimization, and competitive positioning.
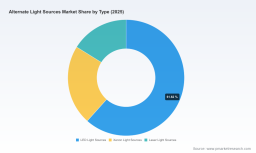
At its core, the study delivers a multi-dimensional segmentation analysis that dissects the market across critical operational axes. Readers will find dedicated evaluations of the primary technology categories that define the ALS product universe, including an in-depth examination of LED-based illumination platforms, which currently represent the dominant share of deployed systems, alongside detailed profiles of Xenon and Laser light source segments. Each technology category is assessed for its distinct adoption curves, price band positioning, and suitability for specific end-use environments ranging from field-deployed crime scene units to controlled laboratory screening workflows.
The application-driven segmentation module provides equal granularity, mapping market activity across the principal domains where alternate light technologies generate measurable value. Forensic investigation remains the most substantial demand pillar, with specialized ALS kits and multi-wavelength laboratory screening systems forming an integral component of modern evidence processing pipelines. Medical diagnostics represents a secondary but growing application vector, where wavelength-specific illumination supports diagnostic visualization and procedural guidance. Industrial inspection rounds out the core application landscape, encompassing quality assurance, defect detection, and material analysis workflows that rely on precise spectral output to identify anomalies invisible under standard lighting conditions.
Geographic coverage within the report is comprehensive, capturing revenue distribution and growth characteristics across North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa. Rather than presenting raw figure tables in isolation, the regional analysis contextualizes each market's procurement environment, regulatory maturity, agency budget cycles, and technology adoption timelines. This approach enables readers to identify not only which regions represent the largest current revenue pools, but also which territories exhibit the strongest forward indicators for incremental market entry or distribution partnership development.
Competitive Landscape and Strategic Positioning
The ALS market features a diverse ecosystem of specialized manufacturers and distributors, each competing across different price tiers, feature sets, and end-user segments. Our competitive analysis module evaluates the strategic posture of key market participants, mapping their product portfolios, innovation trajectories, and recent commercial activities to provide a clear picture of where competitive intensity is concentrated and where whitespace opportunities may exist.
Leading Participant Profiles
Several established firms anchor the competitive structure of the worldwide ALS market, with leadership positions often correlated to deep domain specialization, regional distribution strength, and the ability to deliver certified, guideline-compliant equipment.
- Foster + Freeman: Headquartered in the United Kingdom, this organization has built a reputation as a pioneer in high-intensity LED forensic illumination, anchored by its widely deployed Crime-lite product family. The portfolio spans handheld crime scene series, multi-wavelength laboratory configurations, and advanced multi-spectral and laser-enabled screening platforms. Recent commercial activity has highlighted next-generation evidence screening tools designed for forensic laboratory environments, reinforcing a strategic emphasis on laboratory-grade throughput and multi-wavelength integration.
- Labino AB: Based in Vallentuna, Sweden, this manufacturer focuses on waterproof LED alternate light source kits engineered specifically for crime scene investigation workflows. Product design emphasizes operational simplicity, with straightforward on/off functionality and robust field-ready engineering. Recent catalog updates have expanded specification transparency for core ALS kits, reflecting a broader industry trend toward clearer technical documentation and streamlined procurement evaluation.
- Sirchie: Operating from the United States, this supplier provides a range of forensic alternate light solutions tailored for law enforcement evidence detection. Its product lines include high-output three-watt illumination systems, tactical field kits, and shortwave UV configurations optimized for crime scene processing. The emphasis on law enforcement readiness and tactical deployment architecture positions this participant strongly within public-sector procurement channels.
- HORIBA Scientific (SPEX Forensics): This United States-based entity offers compact handheld and laboratory-focused LED alternate light platforms designed for visualizing latent prints, body fluids, and other forensic evidence markers. The brand's positioning centers on precision visualization tools that bridge field collection and laboratory confirmation workflows.
- FoxFury: Also headquartered in the United States, this supplier specializes in rugged, cordless forensic lighting and alternate light source configurations intended for field investigators. Product families include portable series designed for cordless operation, emphasizing durability, rapid deployment, and flexible wavelength options across multiple kit configurations.
- Lynn Peavey Company: A United States-based distributor and supplier, this organization provisions portable ALS units alongside complementary forensic processing materials. Its distribution-centric model enables broad catalog reach across evidence processing workflows, making it a significant channel presence within the North American supply ecosystem.
- UltraLite ALS: Operating as a specialized provider of portable forensic alternate light sources, this participant focuses on compact, wavelength-configurable kits intended for direct crime scene deployment. The product emphasis aligns with the broader market shift toward lightweight, field-portable systems that maintain professional-grade spectral output in a streamlined form factor.
Concentration Dynamics and Portfolio Strategy Implications
The competitive structure of the worldwide ALS market exhibits meaningful concentration at the top tier, with the largest players collectively commanding a substantial share of aggregate revenue. This concentration pattern reflects the importance of brand certification, regulatory familiarity, and established distribution relationships in public-sector and institutional procurement environments. Simultaneously, the market maintains a broad product diversity across more than a dozen manufacturers and upwards of fifty distinct configurations, with price points spanning a wide range from entry-level field kits to high-specification laboratory systems. This bifurcated structure creates a strategic landscape where premium differentiation, compliance documentation, and total-cost-of-ownership positioning often matter more than unit-price competition alone.
Worldwide Alternate Light Sources Market
Regulatory Context and Standardization as a Market Accelerator
One of the most important yet underappreciated drivers in the ALS sector is the accelerating pace of regulatory definition and equipment standardization. As forensic and public-safety agencies seek to formalize equipment procurement criteria, clear technical standards increasingly function as market accelerants rather than purely compliance burdens.
Shadowless Lamps Market
Authoritative glossary definitions now explicitly frame alternate light sources as equipment engineered to produce light at specific wavelengths for the enhancement and visualization of potential evidence. This definitional clarity helps procurement officers narrow their evaluation criteria and reduces the risk of acquiring non-compliant or under-specified illumination tools. In parallel, recognized authorized equipment frameworks now list portable forensic light kits—comprising at least one alternate light source, a barrier filter, a dedicated power source, and a carrying case—as qualified equipment categories for law enforcement crime scene operations.
These standardization developments carry direct strategic implications. For manufacturers, they create clearer specifications around what constitutes a qualified kit, potentially raising the barrier to entry for non-integrated or non-certified alternatives. For procurement leaders, they streamline the justification process for capital expenditure by linking equipment purchases to documented operational standards. For channel partners and distributors, they reinforce the value of carrying portfolios that explicitly reference these compliance frameworks in sales collateral and technical documentation.
Furthermore, professional guidelines governing low-light crime scene photography now specify operational requirements that emphasize controlled imaging conditions, tripod stability, manual or aperture-priority exposure modes, and wavelength-appropriate operator protection. Equipment vendors that design their systems with these documentation and safety protocols in mind are better positioned to meet institutional purchasing requirements and to reduce the friction associated with evidence admissibility and chain-of-custody considerations.
360-Degree Market Intelligence for 2026 Strategic Planning
Effective market strategy in 2026 requires more than a simple revenue forecast. It demands an integrated understanding of how technology readiness, regulatory evolution, competitive maneuvering, and application-specific procurement cycles interact to shape demand. PW Consulting's Worldwide Alternate Light Sources Market report is constructed to deliver that integrated view.
Readers will obtain a structured basis for evaluating product roadmap priorities, identifying which technology segments are most likely to capture incremental budget allocation, and determining whether regional expansion efforts should prioritize high-revenue incumbency or higher-growth developmental markets. The report also supports pricing strategy calibration by illuminating how different product tiers—from compact handheld units to sophisticated multi-wavelength laboratory platforms—are positioned across the broader ecosystem.
For investors and corporate development teams, the concentration analysis and participant profiling provide a practical framework for assessing acquisition targets, distribution partnership opportunities, and whitespace entry points. The combination of historical revenue validation, forecast-period trajectory modeling, and competitive activity tracking ensures that strategic decisions are grounded in observable market behavior rather than speculative sentiment.
Conclusion: Converting Market Intelligence into 2026 Advantage
The worldwide alternate light sources market stands at a point where steady structural growth intersects with meaningful technological and regulatory evolution. For organizations operating in, adjacent to, or seeking entry into this sector, the difference between reactive positioning and proactive advantage lies in the quality of market intelligence available at the planning table.
PW Consulting's comprehensive study equips decision-makers with the analytical depth required to navigate this landscape confidently. By linking macro-level revenue trajectories, segmented demand patterns, regulatory standardization momentum, and competitive portfolio dynamics into a single strategic framework, the report enables enterprises to align their 2026 initiatives with demonstrable market realities. The full dataset, detailed segmentation breakdowns, complete competitor evaluations, and forward forecast tables are available through the complete research release. For teams ready to move beyond surface-level industry overviews and into execution-ready intelligence, the full report provides the definitive reference point for the year ahead.
For detailed analysis of this topic, please visit the official page: Worldwide Alternate Light Sources Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com