

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global Industrial Diaphragm Pump Market Hits $6.86B in 2025, Projected 5.15% CAGR to 2032

Strategic Intelligence for 2026: Navigating the Worldwide Industrial Diaphragm Pump Market
As industrial operations grow increasingly complex, the demand for reliable, efficient, and compliant fluid handling solutions has never been more critical. The global industrial diaphragm pump market stands at a pivotal juncture, shaped by evolving regulatory frameworks, raw material volatility, and a decisive shift toward energy-efficient and digitally integrated pumping technologies. For executives, procurement leaders, and strategy teams operating in 2026, understanding the structural forces driving this market is no longer optional—it is a prerequisite for competitive positioning, supply chain resilience, and long-term capital allocation.
This strategic overview introduces our latest comprehensive research on the Worldwide Industrial Diaphragm Pump Market, a publication designed to translate macroeconomic trajectories, competitive dynamics, and technology adoption patterns into actionable intelligence. Rather than offering static snapshots, the study maps the market from its 2020 baseline through a detailed forecast horizon extending to 2032, providing decision-makers with a forward-looking lens calibrated for real-world operational planning.
Market Trajectory & Structural Growth Drivers
The industrial diaphragm pump sector has demonstrated consistent expansion over the past half-decade, supported by sustained capital expenditure in water infrastructure, chemical processing, and pharmaceutical manufacturing. Historical data reveals a market that has steadily scaled from 2020 through 2025, culminating in a base-year valuation of USD 6,860.68 million in 2025. This momentum carries forward into the forecast period, with the market projected to reach USD 7,379.6 million in 2026 and continue its upward trajectory toward a 2032 valuation of USD 9,750.61 million.
At the heart of this growth lies a compound annual growth rate of 5.15 percent across the 2026 to 2032 forecast window. This moderate yet persistent expansion reflects a maturing industrial landscape where demand is increasingly driven by replacement cycles, regulatory compliance upgrades, and the gradual electrification of fluid handling systems. Rather than experiencing explosive, disruption-led spikes, the market is characterized by steady volume growth, incremental technological refinement, and a competitive environment that rewards operational efficiency and material innovation.
Several overarching dynamics are reinforcing this trajectory. Stricter environmental regulations governing wastewater discharge and effluent treatment continue to accelerate adoption of diaphragm pumps in industrial water and wastewater management, where seal-less designs and chemically resistant constructions offer distinct compliance advantages. Simultaneously, energy efficiency mandates and advancements in electrically operated diaphragm pumps are reshaping procurement criteria, with certain next-generation models delivering significant power reductions compared to traditional air-operated alternatives. These factors collectively position the diaphragm pump segment as a critical enabler of sustainable industrial fluid transfer.
Competitive Landscape: Consolidation, Innovation, and Regional Footprints
The competitive architecture of the worldwide industrial diaphragm pump market is defined by a blend of established multinational enterprises, specialized engineering firms, and increasingly capable regional manufacturers. Market concentration metrics indicate that the top three players command approximately 32.4 percent of total revenue, while the top five collectively account for 46.85 percent. This moderate concentration suggests a market that remains sufficiently fragmented to allow niche players and regional specialists to compete on customization, application expertise, and localized service networks, even as larger conglomerates leverage portfolio breadth and global distribution channels.
Leading participants span multiple geographies and operational philosophies. North American-headquartered firms such as Xylem Inc., Wanner Engineering Inc., Graco Inc., Dover Corporation (through its PSG division encompassing Wilden, Blackmer, and All-Flo), Ingersoll Rand's ARO division, IDEX Corporation (via Warren Rupp and Sandpiper), Flowserve Corporation, and Finish Thompson Inc. maintain strong positions across chemical transfer, industrial fluid handling, and sanitary applications. Their portfolios frequently emphasize air-operated double diaphragm designs, seal-less positive displacement architectures, and specialized material paths for corrosive or hazardous fluids.
European manufacturers contribute heavily to precision dosing, high-pressure metering, and compliance-driven applications. Grundfos A/S, Tapflo Group, Verder Group, KNF Neuberger GmbH, ProMinent GmbH, LEWA GmbH, and FLUX-GERÄTE GMBH are widely recognized for engineered solutions targeting water treatment, pharmaceutical processes, viscous liquid handling, and analytical or laboratory-grade fluid control. Meanwhile, Asian enterprises such as Yamada Corporation in Japan and GODO Manufacturing Co. Ltd. in China are expanding their footprints through cost-competitive electric models, environmental application focus, and integrated control features. Additional specialists like Albin Pump in Sweden and SAVINO BARBERA Srl in Italy further enrich the competitive matrix with compact designs and hazardous-chemical certifications.
Recent product launches underscore the pace of innovation. In March 2026, KNF Group introduced four advanced diaphragm pumps incorporating integrated sensor technology for flow, pressure, and vacuum control, extending their applicability across industrial, medical, and analytical use cases. The same month, Finish Thompson Inc. unveiled the FTI Air FT30P, a three-inch plastic air-operated double diaphragm pump engineered for high-flow chemical transfer. Earlier in 2025, GODO PUMPS showcased a new electric diaphragm pump with pressure relief controller at IE Expo, targeting environmental and high-flow scenarios, while ARO launched the EVO 210 electric diaphragm pump in September 2025 to improve efficiency and reliability in industrial settings. These releases illustrate a broader industry trend: manufacturers are embedding intelligence, enhancing material compatibility, and broadening electric offerings to meet evolving operational and sustainability expectations.
Segmentation Insights & Application-Side Demand Patterns
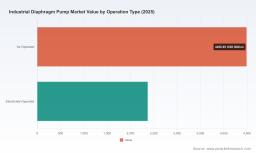
Understanding how demand distributes across operational types, end-user industries, and geographic regions is essential for targeted market entry, capacity planning, and product portfolio strategy. The market's revenue base reflects a clear preference for air-operated configurations, which continue to dominate industrial fluid handling due to their robustness, simplicity, and suitability for hazardous or abrasive environments. Electrically operated diaphragm pumps, while representing a smaller share of current revenue, are gaining traction as energy efficiency requirements intensify and facilities modernize legacy pneumatic infrastructure.
End-user demand is dispersed across multiple verticals, with water and wastewater management, chemicals and petrochemicals, food and beverage, oil and gas, pharmaceuticals, and a diversified remainder each contributing meaningfully to total consumption. This breadth indicates that diaphragm pumps are not confined to a single flagship application but rather serve as cross-industry workhorses where leak-free operation, chemical resistance, and precise metering are paramount. The multiplicity of end-use sectors also provides natural demand hedging: downturns in one vertical can be partially offset by sustained or growing requirements in another.
Geographically, the market's revenue distribution highlights the importance of regional industrialization rates, regulatory environments, and infrastructure investment cycles. Asia Pacific represents the largest regional revenue pool, followed by North America and Europe, with Latin America and the Middle East and Africa contributing smaller yet strategically significant volumes. These regional differentials matter because they shape localized competitive dynamics, service expectations, and the relative attractiveness of electric versus air-operated solutions. Decision-makers evaluating expansion, sourcing, or partnership opportunities must align their strategies with region-specific demand drivers rather than relying on global averages alone.
Material Supply, Regulatory Pressures, and Operational Implications
Market performance is inseparable from the underlying supply chain and regulatory environment. Raw material conditions have emerged as a critical variable for manufacturers and buyers alike. Since 2024, volatility in stainless steel, aluminum, and high-grade elastomer pricing has influenced manufacturing costs and average selling prices across the diaphragm pump segment. These fluctuations affect margin structures, lead times, and the economics of proprietary material formulations, making supplier diversification and forward contracting increasingly relevant for both producers and large-scale end users.
Material innovation continues to play a strategic role, particularly in chemically aggressive environments. PTFE remains a cornerstone material for chemical-resistant diaphragms, with global market volume reaching approximately 238.40 kilotons in 2026 and sustained demand from pump components in chemical processing. The availability, processing quality, and cost trajectory of such specialized materials directly affect product reliability, certification pathways, and the feasibility of sealing hazardous or corrosive fluids without compromising operational integrity.
Regulatory compliance is equally influential. Stricter environmental standards on wastewater discharge and effluent treatment are accelerating the deployment of diaphragm pumps in industrial water management, where sealless construction and compatible wet-end materials help facilities meet discharge limits and reduce maintenance interruptions. At the same time, compliance with explosion-proof design standards such as ATEX and adherence to ISO fugitive-emission limits are promoting the use of sealless diaphragm pumps built with advanced materials in hazardous industrial environments. These regulatory pressures do not merely constrain design choices; they actively redirect demand toward technologies that reduce leakage, improve containment, and simplify compliance documentation.
Sustainability objectives are further reshaping procurement logic. Energy efficiency mandates and demonstrable performance improvements in electric diaphragm pumps are encouraging facilities to reassess pneumatic dependencies. Certain electric models claim substantial energy reductions relative to traditional air-operated units, making them attractive in contexts where electricity costs, carbon targets, and total cost of ownership calculations intersect. For strategy teams, this trend signals a gradual but meaningful realignment in capital equipment specifications, with long-term implications for installed base composition and aftermarket service demand.
What the Full Study Delivers: A Practical Toolkit for 2026 Decision-Making
Our Worldwide Industrial Diaphragm Pump Market research is constructed to move beyond high-level commentary and equip teams with a structured, decision-ready analytical framework. The report integrates historical performance data, baseline valuations, and a multi-year forecast to clarify growth pacing, demand inflection points, and the relative contribution of different market segments. It maps revenue distribution across operational types, end-user industries, and regions, enabling readers to identify where volume is concentrated and where emerging opportunities may be underappreciated.
The study also provides a detailed competitive landscape assessment, examining the strategic positioning, product architectures, and market approaches of key participants. By contextualizing recent product launches, technology upgrades, and application-specific engineering focus, the report helps readers gauge how incumbents and challengers are shaping future supply dynamics. This competitive intelligence is paired with an analysis of market concentration, allowing stakeholders to evaluate competitive intensity, substitution risk, and the potential impact of consolidation or portfolio expansion.
Operational and supply-side factors are addressed with equal rigor. The research incorporates material market context, cost-structure considerations, and regulatory developments that influence product design, pricing, and adoption timelines. It further explores the interplay between energy efficiency expectations, electrification trends, and compliance requirements, offering a consolidated view of the forces that will determine which specifications win in procurement evaluations and which legacy configurations face gradual displacement.
Importantly, the study is designed to support scenario planning rather than prescribe a single path. Readers will find context for evaluating regional entry strategies, assessing supplier dependencies, benchmarking product roadmaps, and anticipating shifts in end-user preferences. By aligning quantitative forecasts with qualitative drivers, the report gives executives a coherent basis for investment prioritization, risk management, and cross-functional alignment between engineering, procurement, and commercial teams.
Worldwide Industrial Diaphragm Pump Market
Why This Research Matters Now
The 2026 decision environment demands more than retrospective reporting. Industrial buyers and suppliers alike are navigating material price variability, evolving compliance expectations, and a technology transition that favors smarter, more efficient fluid handling. In this context, a disciplined understanding of market size, growth pacing, segmentation structure, and competitive behavior becomes a strategic asset. It informs where to invest, which specifications to prioritize, how to structure supplier relationships, and when to anticipate shifts in regional demand intensity.
Diaphragm Valve Market
The Worldwide Industrial Diaphragm Pump Market study is built to serve as that strategic reference point. It combines a robust historical foundation with a forward-looking forecast through 2032, situates key industry players within a clear competitive framework, and ties market movements to the regulatory, material, and sustainability forces that are actively reshaping procurement and engineering decisions. For organizations seeking to reduce uncertainty and act with precision in 2026 and beyond, the full report provides the depth, structure, and operational relevance required to convert market intelligence into concrete business advantage.
For detailed analysis of this topic, please visit the official page: Worldwide Industrial Diaphragm Pump Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com