

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Embedded Systems Market Hits $126.5B in 2025, Driven by 6.85% CAGR to $201.1B by 2032

Navigating the Embedded System Landscape: Strategic Intelligence for 2026 Decision-Making
The global embedded system market stands at a critical inflection point. As industries increasingly weave intelligent processing into the fabric of everyday products and critical infrastructure, the demand for robust, secure, and efficient embedded solutions has never been more pronounced. For executives, investors, and strategic planners, the period from 2026 through 2032 represents a complex landscape of unprecedented growth opportunities tempered by significant supply chain volatility, evolving regulatory frameworks, and intensifying competition.
PW Consulting's latest Worldwide Embedded System Market study is designed specifically to cut through this complexity. This comprehensive report does not merely present historical data; it offers a forward-looking strategic compass, synthesizing macro-level market trajectories with granular insights into components, applications, and regional dynamics. The following analysis highlights the core strategic value embedded within this research, providing a preview of the intelligence available to guide your organization's decisions in 2026 and beyond.
Market Trajectory: Context for Strategic Planning
Understanding the sheer scale and momentum of the embedded system sector is the first step in calibrating strategic expectations. The market has demonstrated remarkable resilience and expansion over the past five years. Valued at approximately 89,450 million USD in 2020, the market surged to a revenue base of 126,500 million USD by the base year of 2025. This trajectory underscores a sustained acceleration in the adoption of embedded technologies across diverse verticals.
Looking forward, the forecast period from 2026 to 2032 points toward continued robust expansion, driven by the proliferation of IoT devices, the electrification and autonomy of vehicles, and the increasing digitization of industrial processes. The analysis projects a compound annual growth rate (CAGR) of 6.85% over this forecast horizon. By 2032, the market revenue is anticipated to reach a substantial milestone, reflecting the deep integration of embedded intelligence into global manufacturing, healthcare, consumer electronics, and aerospace ecosystems.
While these macroeconomic indicators set the stage, the true strategic value lies in understanding the nuanced drivers behind these numbers. Our report deconstructs this growth, revealing which component segments are capturing the lion's share of investment, which application verticals are outpacing the broader curve, and how geographic dynamics are shifting in response to geopolitical and supply chain factors. The 2026 snapshot provided in the study captures the immediate post-base-year reality, offering a baseline against which all subsequent growth can be measured with precision.
Decoding the Segmented Landscape: Where Value is Created
One size does not fit all in the embedded system market. The strategic allocation of resources depends on a granular understanding of how value is distributed across the ecosystem. The report provides a detailed segmentation analysis that allows decision-makers to benchmark their own market positions and identify whitespace opportunities.
Component Dynamics: Hardware vs. Software
The division between hardware and software is no longer a simple binary. While hardware remains the foundational revenue driver, the software layer is increasingly becoming the differentiator in terms of total cost of ownership, security, and performance optimization. The study quantifies the revenue contribution of each component category, highlighting the interplay between silicon procurement, embedded software development, and the emerging need for integrated hardware-software stacks. Readers will gain clarity on the relative maturity and growth velocity of these segments, enabling more informed decisions regarding R&D investment and vendor partnerships.
Application Verticals: Divergent Growth Engines
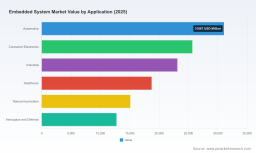
Embedded systems are the invisible architecture of modern industry, but the penetration and growth rates vary dramatically by application. Automotive and consumer electronics continue to be massive anchors for the market, driven by advanced driver-assistance systems (ADAS), infotainment, and smart connectivity. However, the industrial sector is undergoing a transformation fueled by machine vision, predictive maintenance, and Industry 4.0 automation. Healthcare is experiencing a surge in demand for wearable diagnostics and implantable devices, while telecommunications and aerospace/defense are demanding ever-higher reliability and performance. This report isolates the revenue dynamics for each of these key application areas, revealing which verticals are converging, diverging, or creating new cross-industry demand.
Regional Perspectives: Global vs. Local
Geography plays a pivotal role in market access and competition. The analysis breaks down revenue contributions across major regions, including North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa. Beyond simple revenue figures, the report contextualizes these splits with insights into regional regulatory environments, supply chain footprints, and the localization of embedded development. Decision-makers can assess regional market saturation, identify high-growth corridors, and understand the strategic implications of shifting manufacturing capabilities.
Competitive Intelligence: Navigating a Dense Vendor Field
The embedded system market is characterized by a diverse array of players, ranging from semiconductor giants to specialized software and connectivity providers. Market concentration data indicates a moderately fragmented landscape, with the top five companies holding a combined share of approximately 28%, and the top three accounting for roughly 18%. This structure suggests that while market leaders exert significant influence, there remains ample room for strategic positioning and competitive differentiation.
PW Consulting's report includes comprehensive profiles of key incumbents and emerging players who are shaping the competitive dynamics. These profiles go beyond basic corporate information, analyzing the specific portfolios, strategic focus areas, and capabilities that define each player's value proposition.
- Semiconductor and Processor Leaders: Companies such as Intel Corporation, Texas Instruments Incorporated, NXP Semiconductors N.V., STMicroelectronics N.V., and Renesas Electronics Corporation are central to the hardware ecosystem. Their strategies around long-life availability, industrial-grade reliability, and automotive-grade solutions are critical for OEMs designing for multi-year product lifecycles.
- Edge AI and High-Performance Computing: Qualcomm Incorporated and NVIDIA Corporation are pushing the boundaries of edge intelligence, offering platforms that bring AI inference and GPU-accelerated computing to embedded and autonomous systems. AMD, Inc. is also expanding its footprint with adaptive computing solutions for high-performance embedded applications.
- Connectivity and Infrastructure: Broadcom Inc. and Samsung Electronics Co., Ltd. contribute essential networking, wireless, memory, and display solutions that integrate deeply into consumer and industrial embedded architectures.
- Specialized Control and Analog Solutions: Microchip Technology Inc. and Analog Devices, Inc. provide critical breadth in microcontrollers, analog mixed-signal processing, and connectivity products that address the precise control and signal integrity needs of industrial and automotive sectors.
- Security and Power Electronics: Infineon Technologies AG and NXP Semiconductors N.V. are increasingly focused on secure microcontrollers and power management, responding to the growing demand for robust embedded security and energy-efficient designs.
Understanding the strategic moves of these companies is essential. The report tracks their product launches, acquisitions, and technology focus, providing the context needed to anticipate supply constraints, technology shifts, and partnership opportunities.
2026 Market Dynamics: Forces Reshaping the Landscape
The embedded system environment in 2026 is defined by a convergence of technological innovation, regulatory pressure, and supply chain realities. Our market dynamics analysis captures these forces in real-time, offering a snapshot of the factors that will influence market execution over the next several years.
Regulatory and Compliance Evolution: The regulatory landscape has become a primary consideration for embedded product design and market entry. The European Union's Cyber Resilience Act, adopted with a transition period, now mandates comprehensive cybersecurity risk assessments, secure development practices, vulnerability handling, and the generation of Software Bill of Materials (SBOM) for hardware and software products bearing CE marking. This regulation extends beyond Europe, setting a de facto standard for global embedded security compliance. Simultaneously, functional safety standards such as ISO 26262 for automotive and IEC 61508 for industrial safety-related systems remain non-negotiable core requirements for safety-critical applications. Furthermore, the ISO/IEC/IEEE 12207:2026 standard provides updated requirements for systems and software engineering processes, aligning technical development with ISO 9001 quality management frameworks. Companies that fail to integrate these regulatory and standardization shifts into their product roadmaps face significant risks of market exclusion and liability.
Supply Chain Volatility and Component Constraints: The availability and pricing of critical embedded components are subject to external market pressures. Notably, RAM and memory prices for embedded systems, particularly LPDDR4X and LPDDR5X variants, have risen sharply. This is driven by the AI-driven reallocation of production capacity by major memory manufacturers, with constraints expected to persist into 2027. This dynamic directly impacts BOM costs and product margins for embedded device manufacturers. The report analyzes the implications of these memory constraints and provides guidance on sourcing strategies, design optimization, and inventory management to mitigate supply-side risks.
Talent Scarcity and Development Methodology Shifts: A growing demand for connected devices is straining the limited pool of skilled embedded engineers. This talent gap is accelerating the adoption of AI-assisted coding tools and model-based design methodologies to maintain development velocity and reduce time-to-market. Organizations that do not adapt their engineering workflows and talent strategies risk falling behind competitors who can rapidly iterate and deploy complex embedded software solutions. The study highlights the implications of this labor dynamic for project planning, outsourcing decisions, and technology selection.
Recent Industry Developments as Strategic Signals: Recent events underscore the pace of change. For instance, developments in ultra-low-power edge AI are highlighted by new SoC architectures targeting multi-GOPS inference at minimal power consumption, reshaping the feasibility of AI capabilities in battery-constrained embedded nodes. In the automotive sector, new I/O interface chips and companion microcontrollers are being launched to support real-time ADAS/AD data acquisition and pre-processing in high-performance embedded computers. Additionally, the condensation of the microcontroller-to-cloud stack through acquisitions that combine Zephyr-based SDKs with Ubuntu Core demonstrates the industry's move toward unified software ecosystems across different silicon vendors. Participation by major distributors and partners at industry events further signals the breadth of new embedded products and demos hitting the market, indicating a vibrant and rapidly shifting product landscape.
The Strategic Utility of This Report for 2026 Decisions
Armed with the insights contained in the Worldwide Embedded System Market study, organizations can make more informed, confident, and strategic decisions across multiple dimensions.
Worldwide Embedded System Market
Market Entry and Expansion Strategy: For companies considering new markets, the segmentation data on applications and regions provides a clear map of where growth is concentrated and where competition is fierce or opportunity is open. The analysis of market concentration helps assess the feasibility of entry strategies, from niche specialization to broader platform plays.
Embedded Systems Market
Product Portfolio and Roadmap Planning: The component analysis and application breakdown enable product leaders to align their development roadmaps with the highest-value segments. Understanding the balance between hardware and software revenue, as well as the specific demands of verticals like automotive, healthcare, and industrial, allows for prioritized investment in the features and capabilities that matter most to customers and regulators.
Risk Management and Supply Chain Resilience: By integrating the analysis of memory price volatility, regulatory mandates like the Cyber Resilience Act, and functional safety standards, the report equips executives with the intelligence needed to build resilient supply chains and compliant product architectures. Early awareness of regulatory requirements and component constraints can prevent costly redesigns and market delays.
Competitive Positioning and Partnership Strategy: The detailed competitive profiles and tracking of recent developments provide a real-time view of the moves being made by key players. This intelligence supports decisions on vendor selection, technology partnerships, and M&A opportunities. It helps organizations anticipate which technologies will become standard and where differentiation can be achieved through unique value propositions or strategic alliances.
Investment and Valuation Context: For investors and financial decision-makers, the market size trajectory, CAGR projections, and segmentation growth rates provide a quantitative foundation for valuation models and investment theses. The report offers the depth required to evaluate the relative attractiveness of different market subsegments and the sustainability of growth across the forecast period.
Conclusion: A Foundation for Informed Strategy
The Worldwide Embedded System Market research from PW Consulting is more than a data repository; it is a strategic asset designed to empower decision-makers in a rapidly evolving global market. By combining macro-level market sizing and forecasts with deep dives into segmentation, competitive dynamics, and real-time industry developments, the report bridges the gap between high-level market awareness and actionable operational intelligence.
As the embedded system ecosystem continues to expand toward 2032, the ability to anticipate regional shifts, regulatory mandates, supply chain disruptions, and technological breakthroughs will define the winners and laggards. The insights provided in this study offer the clarity and confidence needed to navigate these complexities, optimize resource allocation, and capitalize on the substantial opportunities unfolding in the global embedded landscape.
To access the full depth of analysis, including detailed regional breakdowns, component revenue splits, application-specific growth drivers, and comprehensive competitive profiling, we invite you to explore the complete study. The complete report provides the precise data points and nuanced interpretations necessary to translate market intelligence into tangible strategic advantage for your organization in 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Worldwide Embedded System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com