

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global Elapegademase-lvlr Market Hits $61.2M in 2025, Driven by 8.5% CAGR to 2032

Strategic Intelligence for 2026: Navigating the Worldwide Elapegademase-lvlr Drugs Market
As the pharmaceutical landscape continues to evolve at an unprecedented pace, precision medicine and orphan drug therapies have emerged as critical frontiers for strategic investment and operational planning. PW Consulting is pleased to present the Worldwide Elapegademase-lvlr Drugs Market Market Research, a comprehensive analytical report designed to equip executives, portfolio managers, and healthcare strategists with actionable intelligence for 2026 decision-making. This overview outlines the structural dynamics, competitive intensity, and growth trajectory of a niche but rapidly expanding therapeutic segment, while highlighting the methodological rigor embedded in our full report. Readers seeking granular forecasts, distributor-level breakdowns, and scenario modeling will find the complete dataset and strategic frameworks through our official research portal.
Market Trajectory and Historical Context
Elapegademase-lvlr, marketed globally as Revcovi, represents a highly specialized PEGylated recombinant human adenosine deaminase enzyme replacement therapy. Its clinical positioning addresses adenosine deaminase severe combined immunodeficiency (ADA-SCID) across both pediatric and adult populations. Over the past five years, the global market for this therapy has demonstrated consistent expansion, supported by steady clinical adoption, regulatory clarity, and structured reimbursement frameworks in key healthcare systems. Historical revenue progression from 2020 through 2025 reflects a mature yet growth-oriented trajectory, with annualized figures scaling from the low forty-million-dollar range to just above sixty-one million dollars. This upward movement underscores sustained demand drivers, including improved screening protocols, earlier diagnosis pathways, and expanding access to enzyme replacement regimens in specialized clinical settings.
Looking forward, the forecast window through the early 2030s projects continued value accumulation, with compound annual growth rates positioned at a robust 8.5 percent. By the close of the forecast horizon, market revenue is expected to surpass the one-hundred-million-dollar threshold, reflecting both base-case adoption expansion and the incremental impact of supply chain stabilization, dosing optimization, and regional market penetration. For strategic planners, these macro-trends signal more than top-line expansion. They highlight the importance of aligning commercial operations, manufacturing resilience, and payer engagement strategies with a product class that operates under tight clinical constraints, specialized distribution requirements, and concentrated market participation.
Structural Segmentation and Operational Implications
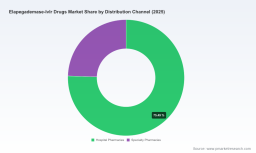
The market architecture for elapegademase-lvlr is defined by distinct operational channels and patient-segment dynamics that directly influence commercial execution. Distribution pathways are heavily weighted toward institutional and specialty pharmacy ecosystems, with hospital pharmacies representing the dominant fulfillment channel and specialty pharmacies capturing a meaningful secondary share. This channel composition reflects the therapy's administration complexity, patient monitoring requirements, and the need for coordinated clinical support services. For manufacturers and distributors, this structure implies that supply continuity, cold-chain or specialized handling protocols where applicable, and clinician-facing education programs are not ancillary considerations. They are central to market access and patient retention.
Worldwide Grazoprevir Market
Patient demographic segmentation further clarifies where commercial emphasis should be concentrated. Pediatric ADA-SCID represents the largest patient cohort by treatment volume, while adult ADA-SCID constitutes a smaller but strategically significant segment. This imbalance has direct implications for long-term therapy management, adherence support, and lifecycle planning. Pediatric cases often involve longer treatment horizons and more intensive coordination across immunology, pediatrics, and genetic counseling services. Adult cases, while numerically smaller, may present differentiated reimbursement conversations, transition-of-care challenges, and distinct clinical monitoring patterns. A successful market strategy must therefore balance cohort-specific service design with enterprise-wide supply and access planning.
Competitive Concentration and Strategic Risk
One of the most defining features of this market is its exceptional concentration. The competitive landscape is dominated by a single principal sponsor, Chiesi Farmaceutici S.p.A., headquartered in Parma, Italy, which markets Revcovi injection worldwide. Chiesi's positioning as the global steward of this PEGylated enzyme replacement therapy places the company at the intersection of product lifecycle management, manufacturing execution, and global access strategy. The concentration levels observed in this segment are unusually high, reflecting the orphan drug nature of the indication, the specialized production requirements, and the limited number of alternative therapeutic pathways for ADA-SCID.
From a strategic standpoint, such concentration creates both advantages and vulnerabilities. On the upside, a focused market architecture can support coordinated clinical communication, streamlined regulatory engagement, and stronger relationships with specialty treatment centers. On the downside, it heightens sensitivity to supply interruptions, manufacturing scale-up challenges, and single-source risk. Industry context from mid-2023 illustrates this dynamic clearly: FDA reporting indicated resupply availability for elapegademase-lvlr injection vials in both 2.5 mg/0.5 mL and 10 mg/2 mL presentations following manufacturing delays. This episode reinforces the importance of redundancy planning, demand forecasting precision, and proactive communication with clinical stakeholders.
For competitors evaluating adjacent opportunities, and for investors assessing portfolio exposure, the market structure suggests that differentiation will likely come from operational excellence, access infrastructure, and service-layer innovation rather than immediate product proliferation. Any strategic entry or partnership must account for the entrenched position of the incumbent sponsor, the specialized manufacturing pathway, and the clinical expectations of centers managing rare immunodeficiency patients.
Regulatory, Reimbursement, and Supply Chain Dynamics
Market dynamics for elapegademase-lvlr are shaped by an intersecting set of regulatory protections, reimbursement pathways, and operational constraints. The product's orphan drug status has historically been reinforced by a seven-year exclusivity framework granted by the FDA around the time of initial approval, extending protective coverage through early October 2025. This exclusivity window has implications for competitive timing, lifecycle planning, and the strategic sequencing of any follow-on development activities. Organizations monitoring the market must track not only current exclusivity boundaries but also the post-exclusivity transition environment, including potential formulation improvements, delivery innovations, or complementary therapy strategies that could alter the value equation over time.
Supply chain conditions have also become a defining element of market behavior. The product entered an FDA-reported shortage situation beginning in late 2022, driven by a combination of increased demand and manufacturing delays. Such disruptions are not merely logistical events. They affect patient continuity, clinical trust, and payer confidence, and they can reshape long-term purchasing and inventory strategies among hospital and specialty pharmacy channels. For market participants, the lessons from this period are clear: resilience must be engineered into the supply chain rather than retrofitted after disruption. That includes visibility into demand signals, manufacturing contingency planning, and coordinated response protocols that minimize interruptions to therapy schedules.
On the reimbursement side, the therapy's eligibility for orphan drug reimbursement pathways under US Medicare Part B reflects an important access enabler. Structured coverage frameworks reduce friction for eligible patients and support predictable revenue flow within the US healthcare system. At the same time, reimbursement strategy cannot be viewed as static. Evolving payer policies, cost-containment pressures, and the growing emphasis on real-world outcomes data mean that manufacturers and market access teams must continually align clinical evidence, health economics narratives, and patient support programs. The interplay between coverage eligibility and commercial execution remains a central strategic lever in this market.
Clinical and safety considerations also influence market dynamics. The prescribing framework includes contraindication guidance for patients with confirmed hypersensitivity to polyethylene glycol. While this is a well-defined clinical parameter, it has operational relevance for patient screening, risk communication, and pharmacovigilance workflows. Organizations operating in this space should ensure that clinical education, pharmacy protocols, and patient-facing materials consistently reflect these constraints to support safe administration and reduce avoidable access barriers.
Commercial Architecture and Payer Strategy
The distribution split between hospital pharmacies and specialty pharmacies suggests a commercial architecture that depends on strong institutional relationships and specialized service delivery. Hospital pharmacies, as the leading channel, are closely tied to inpatient and acute-transition care pathways, clinical protocols, and immunology or transplant-adjacent service lines. Specialty pharmacies, while a smaller share of distribution, often serve as long-term dispensing partners for chronic or maintenance regimens, offering adherence support, patient monitoring coordination, and home-delivery logistics where appropriate. Together, these channels form a complementary access network that requires distinct engagement models.
For commercial teams, this means that sales force deployment, key account management, and patient support infrastructure must be tailored to channel-specific expectations. Hospital-facing strategies may emphasize protocol integration, supply reliability during high-acuity periods, and clinician education. Specialty-pharmacy-facing strategies may prioritize adherence programs, refill continuity, and coordination with prescriber offices for ongoing monitoring. In both cases, the objective is not simply transaction volume. It is sustained therapy continuity for a patient population that depends on reliable access to a highly specialized biologic therapy.
Payer strategy must similarly be calibrated to the realities of orphan drug economics. Coverage pathways exist, but they are embedded within broader cost-management and outcomes-assessment environments. Manufacturers and distributors should therefore invest in evidence-generation plans that address clinical durability, quality-of-life impact, and resource utilization where feasible. Aligning these narratives with payer priorities can strengthen formulary positioning, support consistent reimbursement outcomes, and improve predictability of patient access across treatment settings.
Why the PW Consulting Report Matters for 2026 Decisions
As organizations plan their 2026 priorities, the Worldwide Elapegademase-lvlr Drugs Market Market Research offers a structured foundation for strategic action. The report is designed to translate market-level signals into operational guidance across multiple planning functions. It examines demand drivers, channel behavior, competitive concentration, supply chain vulnerability, reimbursement context, and the regulatory timeline that shapes the product's commercial horizon. Rather than presenting a static snapshot, the analysis emphasizes the dynamic interactions among these forces and their implications for forecasting, capacity planning, access strategy, and risk management.
Decision-makers in manufacturing, commercial operations, market access, and corporate development will find the report especially useful for stress-testing assumptions. The forecast period extends through the early 2030s, allowing readers to evaluate multiple scenarios around supply stabilization, regulatory transitions, channel evolution, and patient-segment growth. This longer view is essential for any organization that must balance short-term execution with medium-term strategic positioning in a concentrated orphan drug market.
Worldwide Elapegademase-lvlr Drugs Market
The full report also includes detailed assessments of competitive positioning, recent supply chain developments, and the regulatory and reimbursement environment that governs market access. These components are integrated to help readers understand not only what is happening in the market, but why it matters for planning, investment, and operational design. Given the high degree of market concentration and the specialized nature of the therapy, even small shifts in supply reliability, reimbursement clarity, or clinical adoption patterns can have outsized effects on commercial performance. The report is built to surface those sensitivities early.
What Is Inside the Full Market Research
The complete PW Consulting report provides a multi-layered examination of the worldwide elapegademase-lvlr market, structured to support both strategic and tactical planning. Key components include a retrospective analysis of historical market performance, a forward-looking forecast through the early 2030s, and an exploration of the structural factors shaping demand and supply. The report details distribution-channel behavior across hospital and specialty pharmacy settings, examines patient demographic patterns across pediatric and adult ADA-SCID treatment, and analyzes the strategic implications of extreme market concentration.
Additional sections address the regulatory and exclusivity environment, reimbursement pathways, supply chain events and their operational consequences, and clinical constraints that influence prescribing and patient management. The report also includes competitive profiling centered on the incumbent global sponsor, with context on market stewardship, product availability dynamics, and the broader orphan drug landscape. Practical frameworks are provided to help readers evaluate entry feasibility, partnership structures, supply resilience strategies, and commercial execution priorities.
For organizations requiring granular planning inputs, the full dataset contains multi-year projections, segment-level context, and analytical tools designed to support scenario planning and sensitivity analysis. These elements are intended to help executives move from high-level market awareness to specific decisions about capacity, commercialization, payer engagement, and risk mitigation.
Conclusion: Positioning for a Concentrated, High-Stakes Orphan Market
The worldwide elapegademase-lvlr market sits at the intersection of specialized biologics, rare disease care, and concentrated commercial execution. Its growth trajectory, channel structure, competitive concentration, and supply chain sensitivity make it a compelling subject for strategic planning in 2026 and beyond. Organizations that approach this space with disciplined forecasting, robust supply resilience, channel-aligned commercial strategies, and proactive payer engagement will be better positioned to navigate its complexities and capture durable value.
PW Consulting's Worldwide Elapegademase-lvlr Drugs Market Market Research is designed to support that effort with rigorous analysis and practical strategic guidance. For full quantitative forecasts, detailed segmentation context, competitive assessments, and scenario-based planning tools, please access the complete report through our official research portal. The insights contained in the full study are intended to help leaders convert market intelligence into executable strategy in a market where precision, continuity, and concentration all matter.
For detailed analysis of this topic, please visit the official page: Worldwide Elapegademase-lvlr Drugs Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com