

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Category: market research
PW Consulting Report: Global Recruitment Market Hits $38.1B in 2025, Projected 7.34% CAGR to $62.5B by 2032
By pmarketresearch, 2026-09-17
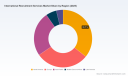
Global Talent Mobility: Strategic Imperatives in the International Recruitment Services Market Through 2032
The global talent landscape is undergoing a structural shift defined by cross-border mobility, regulatory tightening, and an accelerating demand for specialized human capital. As organizations scale operations internationally, the function of international recruitment has evolved from a transactional hiring support service to a strategic capability that directly influences market entry velocity, operational resilience, and long-term competitiveness. Our latest Worldwide International Recruitment Services Market research provides a comprehensive intelligence framework designed to help enterprise leaders navigate these intersecting forces with precision. This article outlines the strategic value of the study for 2026 decision-making, highlights the analytical architecture of the report, and maps the competitive and regulatory terrain that will shape procurement, partnership, and expansion strategies in the years ahead.
Macro Trajectory: Scale, Growth, and the Strategic Window of 2026-2032
The international recruitment services industry has demonstrated remarkable resilience and consistent expansion over the past half-decade. Evaluating the historical trajectory from 2020 through 2025 reveals a market that navigated macroeconomic volatility, shifting immigration policies, and supply chain disruptions without losing its fundamental growth momentum. Building on that foundation, the forecast period extending to 2032 points to a sustained upward curve, underpinned by structural labor imbalances, digital transformation across industries, and the continued globalization of high-value talent pools.
At the base year of 2025, the global market for international recruitment services reached an estimated valuation of approximately 38.1 billion USD, a notable increase from the 34.3 billion USD recorded in 2024 and a steady climb from the 33.1 billion USD registered in 2022. This progression reflects not only organic demand but also the maturation of compliance-driven recruitment models, the expansion of remote and hybrid cross-border work arrangements, and the strategic outsourcing of talent acquisition functions by multinational enterprises. The forecast period beginning in 2026 projects the market to advance to roughly 40.2 billion USD in the immediate year ahead, before accelerating toward the mid-40 billion USD range by 2027 and 2028. Over the full forecast horizon, the market is expected to reach approximately 62.5 billion USD by 2032, supported by a compound annual growth rate of 7.34 percent.
For enterprise strategists, this trajectory carries several implications. First, the scale of growth confirms that international recruitment is no longer a peripheral HR function but a substantial, independently viable market with its own pricing dynamics, supplier ecosystems, and contract structures. Second, the projected acceleration underscores the importance of proactive supplier evaluation and partnership architecture: organizations that enter the market with clearly defined talent requirements, compliance standards, and geographic priorities will be positioned to secure preferred access to high-demand talent segments. Third, the breadth of the forecast window provides ample horizon for long-cycle workforce planning, allowing executive teams to align capital allocation, geographic expansion roadmaps, and capability-building investments with a credible market growth baseline.
Analytical Architecture: What the Research Delivers to Decision-Makers
A robust market intelligence study must do more than report headline figures; it must translate quantitative baselines into actionable decision frameworks. This research is structured to give procurement leaders, HR executives, corporate development teams, and investment analysts a multi-dimensional view of the international recruitment landscape. The study is organized around several interconnected analytical pillars, each designed to surface practical insights rather than abstract observations.
- Market sizing and growth mapping: The report establishes a rigorous baseline for total market value across the historical window and projects forward through the forecast period. These figures are contextualized within demand drivers, supply-side capacity constraints, and the evolving pricing environment for cross-border talent placement.
- Service-type segmentation: The analysis disaggregates market activity across permanent placement, contractual and temporary staffing, executive search, and recruitment process outsourcing. By examining the structural preferences, contract lengths, and operational models associated with each service category, the study helps organizations match procurement strategies to their specific workforce needs and risk tolerance.
- Industry vertical mapping: Demand patterns are evaluated across key sectors, including information technology and telecommunications, healthcare and life sciences, manufacturing and engineering, financial services, and other verticals. The research highlights where talent scarcity is most acute, where compliance complexity is highest, and how vertical-specific hiring cycles influence supplier capacity and service design.
- Competitive and supplier evaluation: Profiles of leading international recruitment providers are presented with attention to geographic reach, service specialization, operational footprint, and strategic positioning. These assessments support vendor benchmarking, partnership due diligence, and the identification of suppliers capable of supporting multi-jurisdiction deployment.
- Regulatory and compliance environment: The report tracks policy shifts affecting international recruitment, including fee-charging restrictions, cross-border data handling requirements, and labor protection frameworks that influence engagement models, candidate experience, and contractual risk allocation.
- Strategic recommendations and scenario frameworks: Rather than leaving the data as a static snapshot, the study translates findings into guidance for market entry planning, supplier diversification, compliance readiness, and capability investments that align with anticipated demand curves.
Within these pillars, the research provides granular segmentation data, supplier-level benchmarking, and operational indicators that are essential for building defensible sourcing strategies. Because the full spectrum of segment-level estimates, regional intensity breakdowns, and supplier scoring matrices is detailed in the complete report, we encourage strategy and procurement teams to consult the full publication for the precise figures required to calibrate internal models and negotiation frameworks.
Competitive Landscape: The Leaders Shaping the Market
The international recruitment services market is characterized by a mix of global workforce giants, specialist recruitment firms, and consultative talent organizations that blend placement capabilities with leadership assessment and organizational advisory services. Market concentration remains moderate, with the top three providers collectively accounting for a share that reflects a competitive, fragmented landscape rather than a consolidated monopoly. This structure creates both opportunity and complexity for buyers: there is ample supplier choice and specialized expertise available, but it also demands disciplined evaluation to ensure alignment with compliance standards, geographic coverage, and service-level expectations.
Adecco Group, headquartered in Switzerland, operates across more than 60 countries and provides temporary, permanent, and contract staffing solutions with a pronounced focus on international placements spanning IT, engineering, finance, and healthcare. Its scale and cross-industry reach make it a central reference point for organizations seeking broad geographic coverage and multi-vertical capacity. Randstad, based in the Netherlands, delivers global recruitment, staffing, and HR services with emphasis on international talent acquisition, temporary agency work, and workforce solutions across more than 39 countries. Its model underscores the importance of integrated workforce services that extend beyond individual placements to broader labor market participation.
ManpowerGroup, rooted in the United States, delivers workforce solutions including international recruitment, staffing, and talent management for permanent, temporary, and project-based roles in over 80 countries. Its breadth of operational presence supports enterprises with complex, multi-region staffing requirements and project-driven mobilization needs. Hays plc, a United Kingdom-based specialist, focuses on permanent and temporary specialist recruitment with international reach in sectors such as IT, construction, finance, and engineering across 33 countries. Its specialization-oriented model is relevant for organizations that prioritize domain expertise and sector-specific candidate pipelines.
Robert Half, also headquartered in the United States, concentrates on international recruitment for finance, accounting, IT, and administrative roles across numerous countries. Its vertical focus illustrates how specialized recruitment can command premium positioning when candidate profiles, credential verification, and regulatory compliance intersect. Korn Ferry, based in the United States, provides executive search and international talent acquisition services integrated with organizational consulting and leadership assessment, positioning the firm at the intersection of human capital strategy and senior-level mobility.
Additional players reinforce the competitive diversity of the market. Allegis Group, headquartered in the United States, offers staffing and recruitment solutions with significant international capabilities, particularly in engineering, IT, and professional services. Kelly Services, also United States-based, delivers temporary, permanent, and outsourced staffing with international recruitment support across various industries, reflecting the enduring relevance of flexible staffing models in global operations. Michael Page, headquartered in the United Kingdom, specializes in mid-to-senior level international recruitment in finance, marketing, engineering, and other professional sectors, highlighting the demand for experienced talent that can drive operational and strategic execution across borders.
Worldwide Job Search Recruitment Services Market
For enterprise buyers, this competitive mosaic is not merely a list of vendors; it is a sourcing architecture to be navigated strategically. The right supplier mix depends on the organization's geographic footprint, the seniority mix of required talent, the degree of compliance sensitivity in target markets, and the need for integrated workforce solutions versus discrete placement engagements. The full report provides a comparative evaluation framework that supports supplier selection, contract structuring, and partnership governance.
Regulatory and Operational Dynamics: Compliance as a Strategic Differentiator
The international recruitment market does not operate in a policy vacuum. Regulatory developments in recent years have reshaped how talent is sourced, engaged, and transferred across borders, making compliance capability a core dimension of supplier evaluation and internal process design. These shifts are particularly salient for organizations that rely on third-party recruitment partners or plan to scale hiring in jurisdictions with evolving labor protections.
A significant regulatory theme centers on recruitment fees and related costs. International standards increasingly prohibit charging workers for fees associated with international recruitment, reflecting a broader effort to protect migrant workers and reduce exploitation risk. In Europe and Central Asia, policy frameworks in a substantial majority of reviewed countries prohibit fee-charging for both national and international recruitment, signaling a compliance environment where transparent cost structures and employer-covered relocation expenses are becoming baseline expectations rather than optional best practices. In parts of Africa, legislation on recruitment fees often applies specifically to international recruitment, with many laws requiring employers to cover transportation costs for relocated workers. These provisions have direct implications for budgeting, supplier contracting, and the design of candidate experience workflows.
Beyond fee regulation, the ethical dimensions of international recruitment have gained prominence. Research has highlighted how recruitment fees and related costs can contribute to debt bondage, with a meaningful share of forced labor cases linked to such practices and a substantial annual extraction of resources from migrants in vulnerable situations. This reality elevates the importance of due diligence, ethical recruitment standards, and supplier accountability. For enterprises, compliance is no longer a legal checkbox; it is a reputational and operational imperative that affects brand trust, talent retention, and the sustainability of international hiring programs.
Data privacy regulation further complicates the recruitment operating environment. Requirements for transparency, consent, and accountability in handling candidate data are increasingly enforced, with ongoing guidance updates influencing cross-border data transfers and the use of automated decision-making in hiring. Organizations that deploy international recruitment at scale must ensure that candidate data flows, screening tools, and reporting mechanisms are designed to meet jurisdictional expectations without compromising speed or candidate experience.
Labor regulation and sector-specific visa frameworks also shape recruitment dynamics. In markets where specialized visa routes have been used to meet care and health workforce needs, reports of exploitation have prompted government responses, including rematching funds and renewed emphasis on ethical recruitment practices. These developments illustrate that international recruitment is subject to continuous policy recalibration, and that suppliers and enterprise buyers alike must maintain adaptive compliance processes, monitoring mechanisms, and escalation pathways.
Taken together, the regulatory environment reinforces a central theme of this research: international recruitment is a governance-intensive market. Organizations that treat compliance, data handling, and ethical sourcing as core design parameters—rather than after-the-fact controls—will be better positioned to manage risk, negotiate favorable terms, and build durable supplier relationships. The complete report details how these regulatory currents interact with market demand, supplier capabilities, and contract models across the forecast period.
Strategic Value for 2026 Decision-Making
The 2026 planning cycle presents a decisive moment for organizations that depend on international talent. The market's projected growth trajectory, combined with evolving regulatory expectations and a competitive supplier landscape, creates both expansion opportunities and execution risks. The strategic value of this research lies in its ability to convert macro trends into decision-ready intelligence across several core areas.
First, the study supports market-entry and geographic expansion planning. By connecting demand intensity with service-type preferences and vertical-specific hiring patterns, it helps leaders prioritize regions, sectors, and talent categories where recruitment partnerships can accelerate operational ramp-up and reduce time-to-productivity. Second, it strengthens procurement and vendor management. The competitive profiles and structural analysis enable more precise benchmarking, clearer service-level expectations, and better-aligned contracting strategies, particularly when organizations need to balance scale, specialization, and compliance assurance.
Third, the research informs compliance and risk frameworks. The integration of regulatory developments into the market analysis helps organizations anticipate changes in fee structures, data handling requirements, and ethical sourcing expectations, allowing procurement and legal teams to build forward-looking controls rather than react to incidents. Fourth, it supports workforce planning and capital allocation. With a credible growth baseline and an extended forecast horizon, executive teams can align hiring budgets, partnership investments, and capability-building initiatives with a market trajectory that reflects both demand continuity and structural change.
Finally, the study provides a foundation for scenario-based strategy. Because international recruitment is influenced by policy shifts, economic cycles, and sector-specific labor dynamics, organizations benefit from understanding how different demand patterns, supplier capacities, and compliance regimes could reshape sourcing outcomes over time. The full report offers the detailed segmentation, benchmarking, and scenario insights needed to construct these scenarios with specificity.
Worldwide International Recruitment Services Market
Closing Perspective
The Worldwide International Recruitment Services Market is entering a phase in which scale, specialization, and governance converge. Growth is sustained, competition is diverse, and regulatory expectations are tightening across multiple jurisdictions. For leaders responsible for talent acquisition, global operations, procurement, and corporate strategy, the ability to interpret these forces with precision is a competitive advantage. This research is designed to provide that precision: a comprehensive, analytically rigorous, and operationally relevant intelligence asset that supports informed decision-making throughout the 2026-2032 horizon.
The complete report delivers the full market sizing, segment-level analysis, regional and vertical breakdowns, supplier benchmarking, and compliance-informed strategic guidance necessary to translate high-level trends into concrete action plans. We invite strategy, HR, procurement, and investment teams to access the full publication to obtain the detailed figures and frameworks required to calibrate sourcing strategies, evaluate supplier portfolios, and prepare for the next phase of international talent mobility.
For detailed analysis of this topic, please visit the official page: Worldwide International Recruitment Services Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Absorbable Antibacterial Envelope Market to Hit $338.18M by 2032, 9.0% CAGR
By pmarketresearch, 2026-09-17
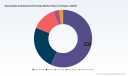
Strategic Imperatives in the Absorbable Antibacterial Envelope Market: Navigating Growth and Infection Control Through 2032
The global healthcare landscape is undergoing a profound transformation driven by an aging demographic, the rising prevalence of cardiovascular conditions, and an intensified focus on reducing hospital-acquired infections. Within this context, cardiac implantable electronic devices (CIEDs) have become indispensable for managing arrhythmias and heart failure. However, the associated risk of device-related infections remains a critical challenge, impacting patient outcomes, increasing readmission rates, and imposing significant economic burdens on healthcare systems. As the industry seeks advanced solutions to mitigate these risks, the absorbable antibacterial envelope market has emerged as a vital segment, offering innovative technologies designed to protect implanted devices while eliminating the need for permanent foreign materials.
For executives, investors, and strategic planners operating in the medical device and healthcare sectors, understanding the trajectory of this specialized market is no longer optional; it is a strategic necessity. Our latest comprehensive research, Worldwide Absorbable Antibacterial Envelope Market , provides an in-depth analysis of this evolving landscape, offering the granular intelligence and forward-looking insights required to navigate the complexities of 2026 and beyond. This article serves as a strategic preamble, highlighting the key dynamics, growth catalysts, and competitive forces that define the market, while underscoring the indispensable value of our full research report for data-driven decision-making.
Market Trajectory: From Resilience to Sustained Expansion
The absorbable antibacterial envelope market has demonstrated remarkable resilience and consistent growth over the past half-decade, reflecting the increasing adoption of infection prevention protocols in electrophysiology and cardiac surgery. Our analysis tracks a clear upward trajectory, with the global market valuation rising from 110.0 million USD in 2020 to an estimated 185.0 million USD by 2025. This growth underscores the market's transition from a niche application to a mainstream component of CIED implantation procedures, fueled by heightened awareness of infection-related complications and the clinical efficacy of absorbable drug-eluting technologies.
Looking ahead, the forecast period from 2026 to 2032 projects a compelling expansion path. The market is anticipated to reach approximately 203.23 million USD in 2026, accelerating toward a peak valuation of 338.18 million USD by 2032. This long-term outlook is anchored by a compound annual growth rate (CAGR) of 9.0 percent, signaling robust demand drivers that extend well beyond short-term fluctuations. Such sustained growth indicates a maturing ecosystem where absorbable envelopes are increasingly integrated into standard care pathways, supported by favorable clinical evidence, regulatory validations, and evolving reimbursement frameworks. For stakeholders, this trajectory represents both a significant revenue opportunity and a call to action for strategic positioning in a rapidly consolidating space.
Segmentation Dynamics: Unpacking Value Across Types, Applications, and Regions
The structural composition of the absorbable antibacterial envelope market reveals distinct value pools that warrant careful strategic consideration. Our research dissects the market across multiple dimensions, providing a granular view of how different segments contribute to overall performance and where future growth vectors are likely to concentrate.
In terms of product architecture, the market is delineated by the distinction between drug-eluting and non-drug-eluting envelopes. The drug-eluting category, which incorporates antimicrobial agents directly into the bioabsorbable matrix, has established itself as the dominant paradigm, reflecting the clinical preference for active infection prophylaxis over passive barrier methods. This segment captures the lion's share of market value, driven by the widespread utilization of envelopes that release rifampin and minocycline to combat a broad spectrum of pathogens. The non-drug-eluting segment, while smaller in comparison, serves specific clinical niches and continues to evolve as material science advances. Understanding the relative performance, adoption rates, and pricing dynamics of these categories is essential for manufacturers and distributors aiming to align their portfolios with clinical demand.
Worldwide Absorbable Antibacterial Envelope Market
Application-wise, the market is heavily influenced by the underlying volume and complexity of CIED procedures. Pacemaker implantation remains the cornerstone application, accounting for a substantial portion of envelope utilization due to the high global volume of pacemaker placements and the established protocols for infection reduction in these procedures. Implantable cardioverter-defibrillator (ICD) implantation represents another major application segment, where the higher energy requirements and complex lead configurations often necessitate additional protection against pocket infections. Beyond these primary uses, the category of other CIED implantations, including cardiac resynchronization therapy devices, contributes to the broader demand landscape. Each application presents unique clinical requirements, reimbursement considerations, and growth potentials that our report analyzes in detail.
Geographically, the market exhibits a pronounced concentration in developed regions, with North America commanding a leading position in terms of revenue generation and adoption maturity. This dominance is supported by advanced healthcare infrastructure, high rates of CIED implantation, favorable reimbursement policies, and the early availability of innovative technologies. Europe follows as a significant market, characterized by robust clinical standards and a growing emphasis on infection control mandates across national health systems. Meanwhile, the Asia Pacific region represents an emerging frontier with substantial untapped potential, driven by expanding access to cardiac care, rising healthcare expenditures, and a growing patient population. Latin America and the Middle East and Africa, though currently smaller in absolute terms, are beginning to show incremental growth as awareness of advanced infection prevention technologies permeates these markets. Our full analysis explores the regional nuances, including regulatory environments, competitive intensity, and local demand drivers, without relying on superficial breakdowns, enabling stakeholders to identify the most promising geographic avenues for expansion.
Competitive Landscape: Concentration, Innovation, and the Medtronic Benchmark
The absorbable antibacterial envelope market is defined by a high degree of competitive concentration, a characteristic that shapes pricing strategies, innovation cycles, and market entry barriers. Our research highlights that the top three companies collectively command an estimated 88.5 percent of the market, while the top five firms account for approximately 95.2 percent. This oligopolistic structure reflects the significant clinical validation, regulatory expertise, and distribution networks required to succeed in a specialized medical device segment. For new entrants, the barriers are formidable; for incumbents, the challenge lies in defending market share while driving continuous product improvement and expanding into adjacent therapeutic areas.
At the forefront of this competitive arena stands Medtronic, a company whose TYRX Absorbable Antibacterial Envelope has become synonymous with innovation in CIED infection prevention. Headquartered in Dublin, Ireland, Medtronic has leveraged its global scale and clinical research capabilities to establish TYRX Absorb as a leading solution. The device is a fully absorbable envelope that incorporates the antimicrobial agents rifampin and minocycline within a bioabsorbable polymer matrix, designed to reduce the risk of clinical infection when used with CIEDs in patients at higher infection risk. A key feature of the envelope is its complete resorption profile, with the material fully absorbed within approximately nine months, eliminating the long-term presence of a foreign body while providing sustained antimicrobial protection during the critical healing period.
Medtronic's strategic momentum in this space has been reinforced by recent regulatory and clinical milestones that carry significant implications for the broader market. In October 2024, the company received FDA approval for the TYRX Absorb fully absorbable antibacterial envelope for use with cardiac implantable electronic devices, a clearance that validated the device's safety and efficacy profile and expanded its addressable patient population. This regulatory achievement was complemented by clinical evidence presented in March 2025 at the American College of Cardiology Annual Scientific Session, where Medtronic shared five-year data from the ABSORB registry demonstrating low infection rates associated with the TYRX Absorb envelope. Such long-term real-world evidence not only strengthens the clinical value proposition but also serves as a powerful differentiator in a market where payer and provider confidence hinges on robust outcomes data.
The competitive dynamics are further influenced by evolving reimbursement frameworks that directly impact market accessibility and adoption velocities. Notably, the Centers for Medicare and Medicaid Services (CMS) assigned HCPCS code C1831 for the absorbable antibacterial envelope used with implantable devices, a development that streamlines billing processes and enhances the financial viability of envelope utilization in clinical practice. For stakeholders, reimbursement clarity is a critical enabler of market growth, reducing administrative friction and encouraging broader implementation. However, it also raises the stakes for competitive positioning, as manufacturers must demonstrate not only clinical efficacy but also value-based benefits that align with payer priorities.
Beyond the dominant players, the market landscape includes a constellation of smaller firms and regional players that pursue differentiated strategies, such as specialized materials, niche applications, or cost-effective alternatives. Our report provides a comprehensive competitive profiling of key companies, examining their product pipelines, strategic partnerships, manufacturing capabilities, and market share trajectories. This analysis enables readers to assess the relative strengths and vulnerabilities of competitors, identify potential consolidation targets, and anticipate shifts in market leadership. For investors, this intelligence is invaluable for evaluating the sustainability of margins and the risk-return profiles of companies operating in this concentrated environment.
Industry Dynamics: Regulatory, Clinical, and Reimbursement Forces Shaping the Future
The trajectory of the absorbable antibacterial envelope market is inextricably linked to a complex interplay of regulatory, clinical, and reimbursement dynamics. Our research delves into these forces, unraveling how they interact to create both opportunities and constraints for market participants.
On the regulatory front, the landscape is evolving as health authorities increasingly recognize the importance of infection prevention technologies in reducing healthcare costs and improving patient safety. The FDA's recent clearance of TYRX Absorb under the 510(k) pathway, with specific indications for reducing clinical infection risk in higher-risk CIED patients, exemplifies the regulatory trend toward evidence-based approvals that reflect real-world clinical utility. Such clearances not only validate the technology but also set precedents for the types of clinical data required for market authorization, influencing the development strategies of other manufacturers. Our report analyzes the regulatory pathways, submission requirements, and approval trends across key markets, providing guidance for companies navigating the complexities of global regulatory compliance.
Clinical considerations also play a pivotal role in market adoption and expansion. The contraindications associated with absorbable antibacterial envelopes, such as known hypersensitivity to rifampin, minocycline, or absorbable polymers, highlight the importance of patient selection and clinical judgment in optimizing outcomes. As the body of clinical evidence grows, including long-term registry data and comparative studies, the understanding of which patient populations derive the greatest benefit will continue to refine. This evolution has direct implications for market sizing, as the definition of the addressable patient base expands or contracts based on clinical guidelines and practitioner behavior. Our research incorporates a thorough review of clinical literature, registry data, and expert insights to map the current state of evidence and project future shifts in clinical practice patterns.
Reimbursement dynamics represent another critical axis of market influence. The assignment of specific HCPCS codes, such as C1831 for absorbable antibacterial envelopes, facilitates reimbursement for procedural use, but the broader reimbursement ecosystem is subject to ongoing negotiations, policy changes, and value-based care initiatives. Hospitals and healthcare systems are increasingly scrutinizing the cost-effectiveness of infection prevention technologies, weighing the upfront cost of envelopes against the potential savings from reduced infection-related complications, shorter hospital stays, and fewer readmissions. Our analysis explores the reimbursement landscape across major markets, identifying the key payers, coding structures, and coverage policies that affect market penetration. For manufacturers, understanding these dynamics is essential for developing effective market access strategies and for communicating value propositions that resonate with economic decision-makers.
Why This Research Is Indispensable for 2026 Decision-Making
As we enter 2026, the absorbable antibacterial envelope market stands at a inflection point where historical growth is giving way to a more complex, competitive, and regulated future. The decisions made today by market participants will determine their ability to capture value, mitigate risks, and capitalize on emerging opportunities over the next decade. Our Worldwide Absorbable Antibacterial Envelope Market report is designed to be the definitive strategic tool for navigating this environment, offering a depth of analysis that goes far beyond high-level market summaries.
The full report provides an exhaustive dissection of market sizing and forecasting, with detailed projections across multiple scenarios that account for varying assumptions about clinical adoption, regulatory changes, and economic conditions. It delivers a granular segmentation analysis that breaks down the market by type, application, and region, revealing the specific growth rates, revenue contributions, and strategic implications of each segment. This level of detail is crucial for companies seeking to allocate resources effectively, tailor their marketing and sales efforts, and identify underserved niches where competitive advantage can be gained.
Antimicrobial Suture Market
Furthermore, the report includes an in-depth competitive landscape assessment that profiles the key players, analyzes their strategic moves, and evaluates the overall market structure. It examines recent developments, such as Medtronic's FDA approval and clinical data presentations, to illustrate the types of events that can shift market dynamics and to provide lessons for competitive positioning. The analysis also considers the potential impact of industry consolidation, technological innovation, and emerging market entry strategies, helping stakeholders anticipate disruptions and adapt their plans accordingly.
In addition to quantitative analysis, the report offers qualitative insights into the industry dynamics that drive market behavior. It explores the regulatory, reimbursement, and clinical factors that influence adoption, providing a holistic view of the ecosystem in which companies operate. The inclusion of frequently asked questions (FAQs) addresses common uncertainties, such as contraindications, material properties, and procedural considerations, offering practical guidance for both commercial and clinical audiences. This combination of data-driven rigor and actionable insight makes the report a versatile resource for a wide range of stakeholders, including medical device manufacturers, strategic investors, healthcare providers, and policy analysts.
Positioning for Success in a High-Growth, High-Stakes Market
The absorbable antibacterial envelope market is not merely a segment of the medical device industry; it is a critical component of the broader effort to enhance the safety and efficacy of cardiac implantable electronic devices. As the global burden of cardiovascular disease continues to rise and the demand for CIEDs expands, the role of infection prevention technologies will become increasingly central to clinical practice and healthcare economics. Companies that can navigate the complexities of this market with agility, evidence-based confidence, and strategic foresight will be well-positioned to achieve sustainable growth and market leadership.
However, success in this environment requires more than intuition; it demands comprehensive, accurate, and forward-looking intelligence. Our research provides the foundation for such intelligence, equipping decision-makers with the knowledge they need to assess market opportunities, benchmark competitive performance, evaluate regulatory and reimbursement risks, and develop robust strategies for 2026 and beyond. Whether you are considering a market entry, expanding an existing portfolio, investing in a competitor, or formulating a market access strategy, the insights contained in this report are tailored to inform your choices and sharpen your competitive edge.
We invite you to access the full Worldwide Absorbable Antibacterial Envelope Market research to gain a complete understanding of the market's size, structure, dynamics, and future trajectory. The detailed segmentation data, competitive profiles, regional analyses, and scenario-based forecasts contained in the report are essential for making informed, high-impact decisions in a market that is poised for significant transformation. In an environment where information is the currency of advantage, this research offers the clarity and depth required to navigate the absorbable antibacterial envelope market with confidence and precision.
For detailed analysis of this topic, please visit the official page: Worldwide Absorbable Antibacterial Envelope Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Expectoration Machine Market to Reach $792.27 Million by 2032 at 8.12% CAGR
By pmarketresearch, 2026-09-17
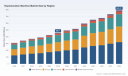
Navigating the Respiratory Critical Care Frontier: Strategic Insights into the 2026 Global Expectoration Machine Market
The global healthcare landscape is undergoing a structural transformation driven by an aging population, the rising prevalence of neuromuscular and chronic respiratory conditions, and an accelerated shift toward value-based care. At the intersection of these macro trends lies a highly specialized yet increasingly vital segment: the Worldwide Expectoration Machine Market. As medical institutions and home care providers confront the clinical imperative of effective airway clearance, expectoration machines have evolved from niche therapeutic tools into essential components of respiratory management protocols. This industry is no longer defined solely by incremental engineering improvements; it is being reshaped by reimbursement policy realignment, regulatory classification frameworks, and intensifying competitive consolidation.
Our recently released Worldwide Expectoration Machine Market research delivers a comprehensive, decision-grade examination of this sector, spanning historical performance from 2020 through 2025 and projecting forward across the 2026 to 2032 forecast window. The analysis is engineered specifically for executive teams, product strategists, clinical procurement leaders, and investment professionals who require granular operational intelligence rather than surface-level market summaries. By mapping demand elasticity across care environments, dissecting product architecture shifts, and evaluating the evolving regulatory and reimbursement terrain, this report provides a strategic blueprint for navigating a market characterized by both robust growth and complex stakeholder dynamics.
Macro Trajectory and Growth Architecture
The foundation of any forward-looking strategy begins with a clear understanding of market momentum. Over the past half-decade, the expectoration machine sector has demonstrated consistent expansion, moving from a 2020 baseline of $310.45 million to a 2025 valuation of $458.70 million. This trajectory reflects sustained adoption of mechanical insufflation-exsufflation (MIE) technologies, broader clinical recognition of airway clearance as a critical intervention for patients with impaired cough reflexes, and ongoing procurement modernization across acute and post-acute care facilities. The momentum is projected to continue through the end of the decade, with the market advancing to $494.23 million in 2026 and approaching $792.27 million by 2032.
Worldwide Expectoration Machine Market
This expansion is underpinned by a compound annual growth rate of 8.12 percent across the forecast horizon, signaling a market that is not merely recovering from historical disruptions but entering a structurally elevated growth phase. Several forces are converging to sustain this trajectory. First, clinical protocols are increasingly standardizing airway clearance interventions for neuromuscular diseases, bronchiectasis, and post-surgical pulmonary complications, expanding the addressable patient population. Second, healthcare delivery models are shifting toward decentralized and home-based care, creating demand for compact, user-friendly, and remotely manageable expectoration systems. Third, manufacturers are investing in integrated device ecosystems that combine cough assistance with broader respiratory support functionalities, thereby increasing clinical utility and procurement stickiness. The strategic implication for market participants is unambiguous: growth will increasingly favor organizations that align product development with care-pathway integration, reimbursement navigability, and real-world usability.
Strategic Segmentation: Where Value Is Being Created
A high-level revenue curve tells only part of the story. The true strategic value of this research lies in its dissection of how demand is distributed across product architectures, end-user environments, and geographic markets. Understanding these allocation patterns enables executives to optimize R&D pipelines, refine pricing architectures, and design targeted commercial strategies.
Product Architecture and Engineering Differentiation
The market divides into two primary mechanical paradigms: automatic mechanical in-exsufflation devices and manual mechanical in-exsufflation devices. Automatic systems dominate the revenue conversation by a considerable margin, reflecting their integration into hospital-grade respiratory workflows, their ability to deliver repeatable and programmable cough simulations, and their alignment with clinical staffing constraints. Manual devices, while generating lower aggregate revenue, maintain a distinct presence in settings where portability, cost sensitivity, and clinician-directed control are prioritized. The engineering frontier is shifting toward hybrid capabilities, improved pressure regulation algorithms, and interfaces that reduce clinician training burden. Companies that can demonstrate superior outcomes in secretion clearance efficiency, patient tolerance, and interface ergonomics are positioning themselves for durable share gains.
End-User ecosystems and Procurement Realities
Demand is not evenly distributed across care settings. Hospitals and clinics represent a substantial share of current procurement, driven by acute-care utilization, in-patient respiratory management, and the availability of specialized clinical staff. Home care settings constitute an equally critical and rapidly expanding demand pool, reflecting the broader migration of chronic respiratory management outside institutional walls. In home environments, device selection is heavily influenced by usability, patient and caregiver training requirements, service coverage, and reimbursement eligibility. Rehabilitation centers, while smaller in relative scale, represent a high-value niche where repeated therapeutic sessions and specialized respiratory programs create steady utilization cycles. Each end-user segment demands a different commercial playbook: hospital sales require clinical evidence packages, group purchasing organization engagement, and service-level agreements; home care distribution depends on durable medical equipment channels, patient support infrastructure, and reimbursement clarity; rehabilitation procurement emphasizes therapy integration and operational durability.
Geographic allocation and regional maturity curves
Regional demand patterns reveal a mature, high-capacity market in North America, where established clinical adoption, reimbursement infrastructure, and a dense concentration of respiratory therapy provider networks support sustained utilization. Europe follows as a substantial market, characterized by diversified national procurement systems, varying reimbursement environments, and strong clinical advocacy for airway clearance standardization. Asia Pacific represents a growth-intensive region where expanding healthcare access, rising chronic disease awareness, and local manufacturing capabilities are accelerating adoption curves. Latin America and the Middle East and Africa, while smaller in current scale, are emerging as incremental growth zones where targeted clinical education, distributor partnerships, and adjusted pricing architectures can unlock meaningful demand over time. The strategic takeaway is that geographic expansion cannot rely on uniform playbooks; each region requires tailored engagement models that account for procurement governance, reimbursement pathways, and clinical ecosystem maturity.
Competitive Landscape and Enterprise Positioning
The expectoration machine market is marked by a concentrated yet dynamically contested competitive field. Our analysis indicates that the top three players command approximately 64.85 percent of market revenue, while the top five extend their collective footprint to roughly 81.4 percent. This concentration signals mature competitive dynamics in the core revenue tiers, but it does not imply stagnation. Instead, it highlights a landscape where incumbents defend share through clinical reputation, regulatory clearances, and broad respiratory portfolios, while challengers and regional specialists compete through product differentiation, targeted usability improvements, and strategic distribution partnerships.
Several enterprise profiles illustrate the competitive archetypes shaping the market. Baxter, operating through its Hillrom platform, brings established clinical brand equity and integrates airway clearance technologies such as the Vest Airway Clearance System and Synclara Cough System into broader hospital respiratory ecosystems. ABM Respiratory Care competes with the BiWaze Cough System, emphasizing dual-airway pathway engineering designed to simulate natural cough mechanics for patients with neuromuscular and respiratory compromise. Koninklijke Philips N.V., through its Respironics lineage, offers the CoughAssist T70 and related MIE devices, leveraging a global respiratory brand and extensive clinical service networks. United Hayek Industries and Hayek Medical maintain a specialized footprint around high-frequency chest wall oscillation and insufflation-exsufflation solutions, including the Hayek RTX oscillator. Dima Italia Srl contributes the PEGASO series, targeting mechanical insufflation-exsufflation bronchial drainage and expectoration support with regional clinical credibility.
The competitive field also includes manufacturers expanding airway clearance through complementary modalities. Electromed promotes the SmartVest Airway Clearance System as a high-frequency chest wall oscillation platform for secretion mobilization. Jinan Qijia Medical Equipment produces airway clearance systems and vest-type sputum expectoration machines for non-invasive respiratory therapy, reflecting the growing capabilities of regional manufacturing hubs. Trudell Medical International offers the AEROBIKA OPEP device, addressing mucus clearance through oscillating positive expiratory pressure. ICU Medical, formerly Smiths Medical, supplies Acapella vibratory PEP therapy systems for patients with secretory management needs. Breas Medical incorporates cough assist and airway clearance devices into a broader respiratory support portfolio, while Air Liquide Medical Systems, through its EOVE offering, delivers mechanical insufflation-exsufflation and related airway clearance solutions. Ventec Life Systems adds another strategic dimension with the VOCSN multi-function ventilator, integrating cough assistance via embedded MIE functionality and illustrating the industry trend toward consolidated respiratory platforms.
Worldwide Phlegm Suction Tube Market
This competitive diversity creates both opportunity and risk. Incumbents with multi-product respiratory portfolios can cross-sell and bundle airway clearance into broader care contracts, but they also face higher expectations for clinical integration and service reliability. Smaller or regionally focused manufacturers can move faster on specialized design and localized service, but they must navigate reimbursement complexity and scale constraints. The 2026 decision-maker must therefore evaluate competitors not only by current revenue share but by their ability to combine regulatory agility, reimbursement navigation, clinical evidence generation, and service coverage into a durable competitive moat.
Regulatory and Reimbursement Dynamics as Strategic Multipliers
Market growth in the expectoration machine sector is deeply intertwined with regulatory classification and reimbursement architecture. In the United States, mechanical insufflation-exsufflation devices are generally classified as Class II medical devices with a 510(k) clearance pathway for airway secretion clearance. This classification framework shapes time-to-market timelines, product documentation expectations, and the competitive barrier to entry for new designs. Organizations that build robust regulatory strategy early can convert clearance velocity into commercial first-mover advantages, particularly when paired with clinical evidence that supports differentiated claims.
Reimbursement policy is equally decisive. Medicare coverage exists for mechanical in-exsufflation devices under HCPCS E0482 for beneficiaries with neuromuscular diseases that cause significant impairment of chest wall and/or diaphragmatic movement resulting in inability to clear retained secretions. This coverage pathway is a critical demand enabler for home and outpatient use, but it also imposes documentation and eligibility requirements that shape procurement behavior. In parallel, HCPCS code A7020 addresses interfaces for cough stimulating devices, with reimbursement possible when the beneficiary owns or is purchasing the mechanical in-exsufflation device. These reimbursement nuances matter because they directly affect patient access, durable medical equipment channel economics, and the commercial viability of home-care device programs. Recent regulatory and market developments continue to reinforce the importance of compliance-forward product strategies. For example, in March 2024, BOC Limited secured ARTG inclusion for a cough assist device designed for in-exsufflation and lung-oscillation airway secretion clearance, classified as Class IIa. Such events highlight how regulatory approvals can unlock regional access and validate clinical positioning, especially in markets where reimbursement eligibility depends on formal device recognition.
For corporate strategy teams, the lesson is clear: reimbursement and regulatory landscapes are not peripheral concerns. They are core pricing and adoption drivers. Product roadmaps should be evaluated through the lens of coverage eligibility, documentation readiness, and the ability to support clinicians and patients in meeting coverage criteria. Commercial teams should align channel incentives with reimbursement navigability, while market access strategies should anticipate policy updates that can expand or contract eligible patient populations.
What the Research Delivers for Executive Decision-Making
This report is structured to convert complex market intelligence into actionable strategic direction. It provides a detailed historical baseline and forward forecast architecture that allows leadership teams to model demand scenarios, calibrate capacity plans, and set realistic revenue expectations across the 2026 to 2032 window. The analysis goes beyond macro totals to examine how product types, end-user settings, and regional markets allocate value, enabling sharper segmentation strategy and resource allocation.
The competitive assessment component delivers more than a company directory. It contextualizes each major participant within broader portfolio strategies, clinical positioning, geographic strengths, and likely strategic moves. This enables benchmarking exercises, partnership evaluations, and competitive response planning. The report also integrates market dynamics analysis that maps regulatory pathways, reimbursement mechanisms, and procurement behaviors into a coherent framework, allowing executives to anticipate structural shifts rather than react to them.
In addition, the research is designed to support practical operational decisions. Product managers can use segmentation insights to prioritize feature development and interface engineering. Commercial leaders can align sales motions with end-user procurement realities and reimbursement conditions. Strategy and corporate development teams can identify consolidation opportunities, partnership targets, and regional entry pathways. Investors and financial analysts can use the growth trajectory, concentration metrics, and market-access dynamics to stress-test assumptions and refine valuation models. By maintaining a disciplined focus on decision-useful intelligence, the report avoids generic commentary and instead delivers the kind of structure that executive teams can immediately apply.
Strategic Imperatives for 2026 and Beyond
Entering 2026, market participants face a set of interconnected imperatives. First, product strategy must increasingly account for care-environment fluidity. Devices that perform well in hospitals but fail in home-care usability or service coverage will face growing resistance as procurement decisions broaden beyond institutional buyers. Second, reimbursement alignment must be treated as a product requirement, not a post-launch afterthought. Coverage eligibility, interface reimbursement pathways, and documentation feasibility will influence adoption speed and channel economics. Third, competitive positioning should be evaluated in terms of ecosystem strength. Manufacturers that can integrate cough assistance into broader respiratory platforms, provide dependable clinical support, and build evidence-based credibility will be better positioned to defend share in a concentrated market. Fourth, regional expansion requires localized realism. High-growth regions will not automatically convert into high-margin opportunities without distributor capability, clinical education, pricing discipline, and regulatory readiness.
The broader implication is that the expectoration machine market is maturing into a strategic domain where engineering excellence, regulatory discipline, reimbursement literacy, and go-to-market precision must operate in concert. Organizations that treat airway clearance as a standalone hardware category will miss the structural forces shaping demand. Those that view it as a care-pathway-enabled solution category will be better equipped to capture durable value.
Conclusion
The Worldwide Expectoration Machine Market is entering a phase where growth is real, competition is structured, and strategic differentiation depends on operational precision. With a forecast compound annual growth rate of 8.12 percent and a market trajectory advancing from $494.23 million in 2026 toward $792.27 million by 2032, the sector offers meaningful expansion potential. Yet the distribution of that opportunity across product types, end-user environments, regions, and competitive tiers is highly nuanced. Success in 2026 and beyond will belong to organizations that can translate macro momentum into targeted segmentation strategy, reimbursement-aware product design, region-specific commercial execution, and defensible competitive positioning.
This research was built to support that decision-making process with depth, clarity, and operational relevance. The full report contains the detailed segmentation breakdowns, competitor benchmarking frameworks, regional demand allocations, reimbursement and regulatory analyses, and forward scenario structures required to guide enterprise strategy with confidence. To access the complete intelligence set and apply it directly to your planning cycle, we invite you to review the full market study and accompanying executive materials.
For detailed analysis of this topic, please visit the official page: Worldwide Expectoration Machine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Reports Push-up Paperboard Tube Market to Hit $261.96M by 2032 with 7.36% CAGR
By pmarketresearch, 2026-09-17
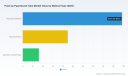
Strategic Intelligence for Sustainable Packaging: Inside the Global Push-up Paperboard Tube Market Forecast 2026-2032
The packaging industry is currently witnessing one of the most significant structural shifts in decades, driven largely by regulatory pressure and consumer sentiment regarding plastic elimination. At the center of this transformation is the push-up paperboard tube, a format that has evolved rapidly from niche alternatives in personal care to a mainstream standard for cosmetics, food, and pharmaceuticals. For executives and supply chain strategists, the 2026 fiscal year represents a critical consolidation point. Whether optimizing procurement or assessing entry into sustainable packaging, understanding the trajectory of push-up paperboard tubes is essential for competitive positioning.
The latest market research released by PW Consulting provides a comprehensive view of this evolving landscape. Drawing on historical data from 2020 through 2025 and projecting forward to 2032, this analysis offers more than surface-level observations. It delivers the analytical rigor required to navigate a market defined by volatility in raw material costs and an increasingly complex regulatory environment. This article outlines the strategic value embedded within the full report, highlighting why immediate access to these insights is necessary for informed 2026 decision-making.
Macro Market Trajectory: Momentum and Valuation
Understanding the scale of opportunity is the first step in strategic planning. The global push-up paperboard tube market has demonstrated a consistent and robust upward trajectory. Over the historical period from 2020 to 2025, the market moved from a valuation of approximately 111.45 million USD to 159.34 million USD. This growth signals more than just a temporary trend; it indicates a structural adoption of paperboard over plastic alternatives across multiple verticals.
Looking ahead, the forecast period from 2026 to 2032 suggests continued expansion. The market is projected to cross 175 million USD in 2026, accelerating toward a valuation of over 261 million USD by 2032. This translates to a compound annual growth rate (CAGR) of 7.36 percent. For strategic planners, this rate underscores the speed at which demand is scaling. It is not merely a linear increase but a momentum driven by fundamental shifts in material preference. The revenue unit remains in millions of USD, providing a clear benchmark for ROI calculations and market entry assessments.
However, raw growth numbers only tell part of the story. The real strategic value lies in understanding where the growth is concentrated and who is capturing value. The full report deconstructs these revenue streams without leaving decision-makers to guess at the drivers behind the headlines.
Segmenting the Opportunity: Material, Application, and Region
Strategic success in the packaging sector depends on precise segmentation. The report provides a granular breakdown of the market by material type, end-use application, and geographic region, allowing firms to identify their specific niche within the broader ecosystem.
Material type analysis reveals a clear preference hierarchy that dictates supplier selection and procurement strategy. Recycled kraft paper continues to dominate the landscape, reflecting the industry-wide push toward circularity and waste reduction. Virgin paperboard maintains a significant presence, particularly where structural integrity or specific cosmetic finishes are required. Specialty laminated paper rounds out the options, often serving high-performance needs where moisture resistance or barrier properties are critical. Each material type carries different cost implications and sustainability credentials, and the report details the revenue share and dynamics for each, enabling buyers to align material choices with corporate sustainability goals.
End-use application segmentation highlights where the demand is most intense. The cosmetics and personal care sector remains the primary driver of demand for push-up tubes, leveraging the format for lip balms, deodorants, and solid cosmetics. Food and beverage applications represent a distinct and growing segment, often driven by regulatory bans on single-use plastics. Pharmaceuticals and health applications add another layer of complexity, requiring specific certifications and barrier properties. By isolating these application streams, the report helps businesses pinpoint which verticals offer the highest growth potential relative to their existing capabilities.
Regional analysis further refines the strategic picture. The market is distributed across Europe, North America, Asia Pacific, Latin America, and the Middle East and Africa. While aggregate regional figures are available in the full dataset, the key takeaway for planners is the variation in maturity and regulatory pressure across these zones. Europe's strong position reflects its early adoption of extended producer responsibility laws, while North America shows dynamic growth linked to state-level EPR expansions. Asia Pacific presents both a manufacturing hub and a growing consumption market. The full report provides the detailed regional revenue splits necessary to model supply chain logistics, tariff exposures, and local market entry strategies.
Worldwide Push-up Paperboard Tube Market
Competitive Landscape: Navigating a Fragmented Ecosystem
The push-up paperboard tube market is characterized by a moderately concentrated competitive landscape. With a CR3 of 18.45 percent and a CR5 of 27.12 percent, no single entity dominates the entire value chain, suggesting ample opportunity for specialized players and regional leaders to thrive. This fragmentation also means that procurement strategies must be sophisticated, balancing quality, customization, and geographic proximity.
Several key companies define the current competitive dynamics, each bringing distinct strengths to the table. Premier Paper Tube, based in Chicago, USA, has carved out a position by offering 100 percent fiber tubes that are PFAS-free and compostable, with a strong focus on customization for cosmetic applications. Similarly, Visican in the UK provides custom eco-friendly cardboard tubes with brandable finishes, catering to brands seeking aesthetic differentiation alongside sustainability. The Packaging Company and GreenWay Containers in the USA both emphasize biodegradable and plastic-free kraft paper solutions, appealing to the zero-waste consumer segment.
Cross-border players add complexity to the sourcing landscape. UCPACK, operating with UK and China capabilities, offers FDA greaseproof and food-grade options with FSC and ISO 9001 certifications, bridging the gap between compliance and customization. In the manufacturing hub of China, companies like All Paper Tube in Shenzhen, MC Packagings, and Fortress Packaging represent the scale and variety available from Asian suppliers, offering wholesale volumes and extensive custom printing options. Fortress Packaging, in particular, highlights the capacity for large-scale biodegradable kraft paper production. Meanwhile, US-based suppliers like SKS Bottle and Packaging and Paper Tube Co. continue to serve the domestic market with ready-made and flush-fit solutions designed to remove plastic from the supply chain.
The full report goes beyond company profiles to analyze how these players are positioning themselves, their capacity constraints, and the strategic implications of sourcing from different regions. For procurement officers, this competitive intelligence is vital for mitigating supply risk and negotiating favorable terms.
Market Dynamics: Regulations, Costs, and Raw Material Volatility
No strategic forecast is complete without addressing the external forces that can disrupt margins and timelines. The 2026 outlook is heavily influenced by regulatory shifts and raw material price fluctuations, both of which are covered in depth within the research.
Worldwide Skin Care Products Tubes Market
Regulation is perhaps the most powerful driver in this market. In the United States, EPR laws have already been enacted in seven states, including California, Colorado, Maryland, Maine, Minnesota, Oregon, and Washington. These laws require producers to manage the collection, recycling, and end-of-life of packaging materials, with fee schedules and implementation details evolving throughout 2026. Furthermore, additional states such as Wisconsin and New Hampshire have introduced packaging EPR bills in late 2025 and early 2026. This patchwork of legislation creates a complex compliance environment that varies by jurisdiction, directly impacting the cost and feasibility of packaging choices. The report analyzes how these regulations are reshaping demand for paperboard tubes as brands seek to minimize EPR fees and liabilities.
Raw material costs present another layer of uncertainty. Data from the Federal Reserve Economic Data indicates that the US Producer Price Index for folding paperboard boxes and packaging components reached 143.503 in March 2026, signaling persistent inflationary pressure in the packaging sector. Regional price disparities also exist; paper board prices in Northeast Asia were observed at 0.22 USD/Kg, while European prices stood at 0.24 USD/Kg in early 2026. Additionally, packaging paper prices in 2025 rose on average by 2.6 percent compared to 2024 levels, with recovered paper prices up by 4.5 percent in the recent period. These fluctuations affect the bottom line for manufacturers and consumers alike. The full report integrates these cost dynamics into the market valuation, helping buyers forecast procurement budgets and hedge against price volatility.
Report Content and Methodology: Actionable Intelligence for 2026
The Worldwide Push-up Paperboard Tube Market report is designed to be a practical tool for strategic planning, not just a data repository. The document covers the base year of 2025 and historical years from 2020 to 2025, providing a solid foundation for trend analysis. The forecast period extends through 2032, allowing for long-term capital allocation and product lifecycle planning.
Readers of the full report will find detailed breakdowns that are essential for building business cases. This includes precise revenue valuations for each segment, allowing for accurate market sizing and share analysis. The segmentation data covers region, material type, and end-use application, providing the granularity needed to identify high-growth niches. The competitive landscape section offers profiles of key players, their headquarters, and their operational focus, giving context to the CR3 and CR5 concentration metrics.
Moreover, the report contextualizes the data within the broader industry environment. By incorporating recent developments in raw material costs and regulatory frameworks, the analysis helps stakeholders stress-test their strategies. Whether a company is evaluating a supplier switch, launching a new eco-friendly product line, or entering a new geographic market, the report provides the evidence base required to support these initiatives. The methodology ensures that all figures are consistent and comparable, reducing the risk of misinformed decisions based on fragmented data sources.
Strategic Takeaways for Decision Makers
As the market moves toward a valuation exceeding 261 million USD by 2032, the window for strategic positioning is open but narrowing. The combination of a 7.36 percent CAGR, evolving EPR regulations, and raw material inflation means that indecision carries a cost. Brands that lock in sustainable packaging solutions early may benefit from supply security and regulatory compliance, while late movers may face higher costs and capacity constraints.
The insights within this market research enable leaders to answer critical questions: Which material type offers the best balance of cost and sustainability for your specific application? How do regional regulations in the US and Europe impact your total cost of ownership? What is the competitive capacity landscape, and where are the bottlenecks likely to emerge? By accessing the full report, stakeholders gain the granular data necessary to transform these macro trends into micro-level actions.
The push-up paperboard tube market is not just about packaging; it is about aligning product delivery with a rapidly changing expectations of environmental stewardship and regulatory compliance. For those ready to move beyond general market awareness into precise strategic execution, the detailed intelligence contained in this report is indispensable. Accessing the full analysis ensures that your 2026 planning is grounded in the most current and comprehensive data available.
For the complete dataset, including all regional revenue splits, segment valuations, and competitive profiles, we invite you to explore the full Worldwide Push-up Paperboard Tube Market report. Equip your organization with the intelligence needed to lead in the sustainable packaging era.
For detailed analysis of this topic, please visit the official page: Worldwide Push-up Paperboard Tube Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Synthetic Amino Acids Market Eyes USD 35,013.75 Million by 2032, 6.55% CAGR
By pmarketresearch, 2026-09-17
Navigating the Synthetic Amino Acids Market: Strategic Intelligence for 2026 and Beyond
The global synthetic amino acids market stands at a critical inflection point as the decade progresses. Over the historical period from 2020 to 2025, the industry has demonstrated remarkable resilience and sustained expansion, with total market revenue climbing from approximately USD 16.4 billion to over USD 22.4 billion. Looking ahead through the forecast horizon of 2026 to 2032, the trajectory points toward a robust compound annual growth rate of 6.55 percent, ultimately positioning the market to surpass USD 35 billion by the close of the period. For executive leadership teams, procurement strategists, and R&D directors, this is not merely a macroeconomic statistic. It represents a complex landscape of shifting feedstock economics, evolving regulatory frameworks, and intensifying competitive dynamics that will directly impact margin structures, supply chain resilience, and long-term portfolio positioning.
As organizations prepare their 2026 strategic roadmaps, the ability to discern signal from noise in this sector has never been more vital. Market participants are operating in an environment where raw material price volatility intersects with regional production cost disparities, where consolidation pressure coexists with niche specialization opportunities, and where the balance between synthetic and fermentation-derived pathways continues to reshape competitive advantages. The latest comprehensive market intelligence, synthesized by PW Consulting, is designed to equip decision-makers with the granular analysis, actionable frameworks, and forward-looking scenarios required to navigate these complexities with confidence.
Macro Trajectory and the Imperative for Precision Intelligence
The eight-year forecast window reveals a market defined by steady, compounding growth rather than abrupt disruption. From a baseline of USD 24.34 billion in 2026, the sector is projected to scale progressively, crossing USD 26.60 billion in 2028, exceeding USD 29.85 billion by 2030, and reaching USD 35.01 billion in 2032. This expansion is underpinned by accelerating demand across industrial nutrition, clinical applications, and specialized chemical formulations, yet the underlying drivers vary significantly by region and end-use vertical. Understanding which segments will capture disproportionate value requires more than high-level trend extrapolation. It demands a structured dissection of production economics, pricing mechanisms, capacity utilization patterns, and the strategic responses of incumbent manufacturers.
Synthetic Vitamin E Market
Recent quarters have already highlighted the sensitivity of this market to upstream variables. Raw material inputs, including soybean oilseeds, wheat, and corn, have experienced pronounced price fluctuations driven by competing agricultural demand and logistical bottlenecks. In chemical synthesis pathways, ammonia constitutes an estimated sixty to seventy percent of operating costs for hydrogen cyanide production, making feedstock procurement a decisive factor in overall cost competitiveness. Regional pricing divergences further complicate procurement strategies, with benchmark prices in the United States, China, and Germany reflecting distinct local supply-demand balances and infrastructure constraints. Organizations that lack detailed visibility into these cost architectures risk suboptimal sourcing decisions, squeezed gross margins, and vulnerability to sudden market shifts.
Worldwide Synthetic Amino Acids Market
Regulatory scrutiny adds another layer of complexity. While synthetic amino acids remain indispensable to numerous high-value applications, certain jurisdictions are intensifying evaluations of chemically derived variants, alongside growing consumer and institutional preferences for fermentation-based or plant-sourced alternatives. Navigating this regulatory mosaic requires a nuanced grasp of compliance timelines, certification pathways, and the commercial implications of shifting procurement mandates across different territories. Strategic planning that ignores these dynamics will inevitably fall short.
Competitive Architecture: Consolidation, Specialization, and Strategic Realignment
The competitive landscape is characterized by a concentrated core of globally integrated producers alongside a diverse cohort of regional specialists and emerging capacity players. The top three firms command approximately forty-two percent of total market revenue, while the top five collectively account for just over fifty-eight percent. This concentration reflects the capital intensity of large-scale synthesis and fermentation operations, the importance of established quality certifications, and the value of entrenched customer relationships across feed, food, pharmaceutical, and nutraceutical channels. Yet concentration does not equate to stagnation. The market is actively reshaping itself through portfolio adjustments, targeted partnerships, and strategic divestitures that redefine competitive positioning.
Leading global players such as Ajinomoto Co., Inc. and Evonik Industries AG continue to anchor the industry through extensive production networks and diversified product portfolios. Ajinomoto leverages decades of fermentation and chemical synthesis expertise to supply high-purity synthetic and feed-grade amino acids, including methionine, lysine, threonine, and tryptophan, across animal nutrition, food, and pharmaceutical applications. Evonik, meanwhile, has sharpened its strategic focus on specialty chemicals for precision animal nutrition, offering flagship products like MetAMINO, Biolys, and ThreAMINO while integrating sustainability metrics into its operational framework. Notably, Evonik has recently undertaken a restructuring of its keto and pharmaceutical amino acid business, discontinuing certain legacy operations while simultaneously expanding its GMP-certified portfolio for clinical and pharmaceutical customers in Europe and North America. This dual move illustrates how incumbents are actively pruning legacy exposures to double down on higher-margin, compliance-intensive segments.
In Asia, major integrated producers are scaling capacity to meet both domestic and export demand. CJ CheilJedang Corporation and Daesang Corporation from South Korea, alongside large-scale Chinese manufacturers such as Fufeng Group Limited and Meihua Holdings Group Co., Ltd., have built substantial production footprints for lysine and other feed-grade amino acids. These organizations benefit from proximity to key agricultural feedstocks and increasingly sophisticated manufacturing capabilities. Their growth strategies often hinge on balancing volume-driven feed applications with higher-value food and nutraceutical segments, requiring careful calibration of production allocation and pricing architecture.
Parallel to these volume-oriented players, a distinct tier of high-purity specialists is carving out defensible niches. Amino GmbH, Kyowa Hakko Bio Co., Ltd., and Wacker Chemie AG focus on pharmaceutical, biotech, and specialty-grade synthetic amino acids, where regulatory compliance, batch consistency, and customized formulation capabilities command premium positioning. The strategic alignment between Croda International and Amino GmbH, announced in late 2025, exemplifies the trend toward collaboration between specialty suppliers and broader life sciences portfolios, reinforcing the value of targeted manufacturing partnerships for pharmaceutical-grade supply chains. Sumitomo Chemical Co., Ltd. further contributes to this ecosystem through its chemical synthesis capabilities, supporting industrial and pharmaceutical applications that demand precise intermediate and derivative production. ADM, as a diversified agribusiness, integrates amino acid production into a broader nutrition portfolio, leveraging scale and cross-segment synergies to serve feed and food customers.
For 2026 planning, the critical takeaway is that competitive advantage will not be determined solely by capacity size. It will increasingly depend on portfolio flexibility, regulatory readiness, sourcing resilience in the face of feedstock volatility, and the ability to align product grades with the most attractive margin pools. Organizations that attempt to compete across all segments without clear differentiation risk compression from both consolidated incumbents and agile specialists.
Inside Our Worldwide Synthetic Amino Acids Market Research
The newly released PW Consulting market research report is built to translate these macroeconomic signals and competitive shifts into actionable corporate strategy. Rather than offering surface-level trend summaries, the study provides a comprehensive operational playbook structured around the decision points that matter most to 2026 planning cycles. The analysis begins with a rigorous reconstructed historical baseline spanning 2020 through 2025, establishing a transparent foundation for the forecast model that extends through 2032. This historical reconstruction is not merely a retrospective exercise. It serves as a diagnostic tool to identify inflection points, validate growth assumptions, and isolate the structural factors that have consistently influenced revenue generation across different product grades and end-use channels.
A core strength of the report is its detailed segmentation architecture, which dissects the market across product types, application verticals, and regional demand centers without sacrificing analytical depth. Decision-makers will find focused assessments of methionine, lysine, threonine, glutamic acid, and other amino acid categories, each evaluated through the lens of demand drivers, production technology pathways, pricing behavior, and margin dynamics. The application-side analysis examines how animal feed, food and beverages, pharmaceuticals, and nutraceuticals and cosmetics utilize synthetic amino acids, highlighting the distinct procurement criteria, regulatory hurdles, and value proposition thresholds that define each vertical. By mapping these segments against the broader forecast trajectory, the report enables users to pinpoint where volume growth, value growth, and margin expansion are most likely to converge, and where commoditization pressures may erode returns.
Regional analysis is presented with an emphasis on competitive intensity, production cost structures, and demand localization rather than simplistic market share rankings. The study explores how Asia Pacific, Europe, North America, Latin America, and the Middle East and Africa differ in terms of feedstock access, manufacturing maturity, regulatory environments, and downstream consumption patterns. This geographic granularity is essential for organizations evaluating capacity expansion, export strategies, or supply chain diversification, as it surfaces the relative attractiveness of different operating environments under varying commodity price and trade policy scenarios.
Beyond segmentation, the report delivers a thorough competitive profiling exercise that maps the strategic postures, technological capabilities, and recent operational moves of the leading participants shaping the market. Each profiled company is assessed for its production methodology focus, product grade coverage, geographic reach, and recent portfolio or restructuring actions. This competitive intelligence is contextualized within broader industry dynamics, including capacity utilization trends, innovation pipelines, and alliance activity, enabling readers to anticipate how rival strategies may alter pricing power, channel access, or customer loyalty in the near term. The inclusion of recent developments, such as GMP portfolio expansions, specialized manufacturing partnerships, and targeted business line restructurings, ensures that the analysis reflects the market as it is actively evolving, not as it existed in prior cycles.
The report also tackles the operational and financial variables that frequently determine whether strategic initiatives succeed or stall. Dedicated sections examine the impact of raw material price volatility, ammonia cost exposure in chemical synthesis routes, and regional pricing differentials on procurement optimization and cost management. These insights are paired with practical frameworks for evaluating make-versus-buy decisions, qualifying alternative suppliers, and structuring hedging or long-term contracting strategies that mitigate exposure to unpredictable input markets. Regulatory considerations are addressed with equal rigor, outlining the implications of compliance scrutiny on synthetic variants, the growing relevance of certification standards across pharma and nutraceutical applications, and the strategic trade-offs involved in balancing synthetic efficiency against shifting preferences for fermentation-derived alternatives in certain customer segments.
Finally, the study is designed with scenario flexibility in mind. Recognizing that macroeconomic conditions, trade flows, and regulatory timelines can shift rapidly, the analytical framework supports multiple planning assumptions. Users can stress-test their strategies against variations in feedstock pricing, regional demand acceleration or deceleration, and changes in competitive concentration. This scenario-oriented approach ensures that the intelligence is not static but functions as a living decision-support tool throughout the 2026 planning and execution cycle.
Strategic Imperatives for 2026 Decision-Makers
Translating market intelligence into competitive advantage requires disciplined prioritization. The following strategic considerations emerge as central for organizations positioning themselves in the synthetic amino acids market over the coming year:
- Align product grade portfolios with margin pools rather than volume alone. High-purity pharmaceutical, nutraceutical, and specialty-grade applications increasingly reward compliance readiness, batch consistency, and customization capabilities, while bulk feed-grade segments remain highly price-sensitive and structurally competitive. Evaluating where your organization can credibly compete on quality and where it must compete on cost is essential for resource allocation.
- Build feedstock resilience into procurement and production planning. Given the sensitivity of operating costs to agricultural commodity fluctuations and ammonia price exposure in certain synthesis routes, companies should evaluate diversified sourcing options, regional cost arbitrage opportunities, and contractual structures that reduce vulnerability to sudden input shocks.
- Anticipate regulatory divergence across territories. As scrutiny of synthetic variants and preferences for fermentation-based alternatives continue to evolve, market participants must monitor compliance requirements, certification timelines, and customer procurement mandates by region. Early alignment with regulatory trends can safeguard market access while late reactions risk stranded capacity or lost contracts.
- Assess competitive moves as strategic signals, not just operational events. Portfolio expansions into GMP-certified applications, divestitures of low-margin legacy lines, and targeted partnerships for pharmaceutical-grade manufacturing all indicate where value is migrating within the industry. Tracking these moves enables proactive positioning rather than reactive catch-up.
- Use regionally nuanced analysis to guide capacity and distribution decisions. Demand density, logistics costs, local feedstock advantages, and regulatory climates vary substantially across markets. A one-size-fits-all expansion or sourcing strategy will underperform relative to a geographically calibrated approach that accounts for these differences.
Accessing the Complete Intelligence Architecture
The synthetic amino acids market in 2026 will reward organizations that combine strategic clarity with operational precision. Sustained growth, competitive concentration, feedstock complexity, and evolving regulatory expectations create an environment where high-level summaries are insufficient, and boutique intuition is too risky. Decision-makers require a structured, data-anchored analysis that connects macro forecasts to segment-level dynamics, competitive behavior, and actionable planning frameworks.
This article has provided a strategic preview of the themes, structural forces, and competitive shifts that define the current market landscape. The full dataset, detailed segment assessments, regional breakdowns, competitive profiles, pricing and cost analyses, and scenario-based planning tools are available in the complete PW Consulting Worldwide Synthetic Amino Acids Market research report. Readers seeking to translate these insights into concrete 2026 decisions, including capacity planning, sourcing optimization, portfolio rebalancing, and competitive positioning, are encouraged to access the full study for comprehensive intelligence and granular market data.
For detailed analysis of this topic, please visit the official page: Worldwide Synthetic Amino Acids Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Leakage Current Protection Receptacles Market Hits $2.45B in 2025, 6.42% CAGR to 2032
By pmarketresearch, 2026-09-17
Strategic Intelligence for the 2026 Landscape: Navigating the Global Leakage Current Protection Receptacles Market
The global electrical safety landscape is undergoing a period of rapid regulatory evolution and technological modernization. For executives operating in the building infrastructure, electrical contracting, and manufacturing sectors, the ability to distinguish between transient market noise and structural growth drivers is no longer a luxury—it is a prerequisite for capital allocation, supply chain optimization, and product positioning. Our newly published Worldwide Leakage Current Protection Receptacles Market Research Report transforms fragmented industry signals into a cohesive, forward-looking strategic framework, giving decision-makers the clarity required to thrive between 2026 and 2032.
Worldwide Leakage Current Protection Receptacles Market
As the industry navigates overlapping code revisions, high-frequency load interoperability mandates, and shifting regional adoption curves, the leakage current protection receptacle segment is transitioning from a baseline compliance necessity to a differentiated platform for safety, smart integration, and premium pricing. This market intelligence briefing outlines why a disciplined, data-enabled approach to this space will define competitive advantages in the next planning cycle, and how our comprehensive study equips leadership teams with the operational insights needed to act swiftly.
The Macro Trajectory: Sustained Growth Anchored in Safety Mandates
The foundational numbers are unambiguous. From a base valuation of approximately $2.45 billion in 2025, the worldwide leakage current protection receptacles market is projected to surpass $2.63 billion in 2026, before accelerating toward a cumulative valuation of roughly $3.79 billion by 2032. Across the historical and forecast horizon spanning 2020 through 2032, the sector has demonstrated a compound annual growth rate of 6.42%, reflecting an equilibrium between steady replacement demand and expansion driven by newly enforced protection standards.
This growth profile is not uniformly distributed. Historical trajectory data captured in our analysis reveals how macroeconomic cycles, construction activity, and regulatory timing converge to shape demand volatility. Crucially, the forecast window does not assume linear progression: our model isolates inflection points, potential plateau periods, and phase-in effects stemming from delayed code enforcement cycles. By understanding the shape of the demand curve—rather than merely its endpoint—organizations can align production capacity, inventory buffers, and sales force priorities with realistic near-term pull-through rather than aspirational headline figures.
For anyone evaluating market entry, capacity expansion, or geographic reallocation, these macro metrics serve as the essential anchor. They establish the addressable opportunity while simultaneously signaling that value capture will depend heavily on segment-specific execution. In other words, the aggregate growth narrative sets the stage, but the playbook for outperformance lives in the granular segmentation, pricing dynamics, and regulatory exposure captured in the full report.
Regulatory Acceleration and Technology Interoperability: The Dual Engines of Demand
Regulatory momentum remains the most consistent driver of leakage current protection adoption, but the nature of that momentum is changing. The 2026 National Electrical Code maintains stringent GFCI protection requirements for outdoor outlets at dwelling units supplied by single-phase branch circuits rated 150V or less to ground and 60A or less. Notably, an earlier exception for HVAC equipment is slated to expire on September 1, 2026, effectively closing a loophole that had allowed certain installations to bypass protection during prior code cycles. This deadline creates a hard compliance horizon that will compress purchasing timelines and intensify near-term demand for compliant devices.
Simultaneously, interoperability has moved from a technical curiosity to a procurement priority. In August 2025, UL Solutions issued Supplement SB to UL 943, introducing high-frequency GFCI testing requirements to ensure devices function reliably alongside modern utilization equipment referenced under the UL 101 leakage current standard. The update was driven by real-world nuisance tripping issues as electrical loads—including HVAC systems and other high-frequency equipment—grew more sophisticated. By September 2025, the NFPA Standards Council had denied appeals, reinforcing the expanded outdoor GFCI requirements and signaling that code-enforcement agencies intend to maintain a strict posture on leakage protection.
Globally, the regulatory picture is equally complex. IEC/EN 61008 and 61009 continue to form the baseline for residual current operated circuit-breakers across more than 80 countries, with ongoing revisions to tripping sensitivity and selectivity criteria. In parallel, amendments to Australia's AS/NZS 3000 Wiring Rules, finalized in 2024, extended mandatory RCD coverage to all power circuits in new buildings and renovation projects. These parallel regulatory streams mean executives cannot rely on a single-code mental model when forecasting regional demand or designing compliance-focused product architectures.
Our research unpacks how these overlapping mandates translate into concrete demand shifts, specifying which applications are most exposed to near-term code phase-ins, which product categories benefit from retrofit and upgrade cycles, and where enforcement timing creates either compressed buying windows or longer validation periods. Counterfeit product warnings issued by UL regarding unauthorized marks on GFCI devices further underscore the importance of sourcing discipline, authentication workflows, and certification visibility across distribution channels—factors we address systematically in the report's compliance and risk sections.
Competitive Landscape: Incumbents, Differentiation, and the Strategic Implications
The market's competitive architecture is moderately concentrated, with the top three players accounting for roughly 45.8% of total market share and the top five collectively representing approximately 62.1%. This concentration reflects the presence of established manufacturers with deep distribution networks, mature certification portfolios, and long-standing relationships with electrical contractors, distributors, and institutional buyers. However, concentration alone does not tell the full story. Competitive advantage in this space increasingly depends on how rapidly firms can adapt to high-frequency interoperability requirements, regional code divergence, and safety-grade differentiation.
Several global leaders anchor the competitive field, each pursuing distinct strategic positions. Leviton Manufacturing Co. has continued to expand its SmartlockPro self-test GFCI portfolio, offering slim-profile, tamper-resistant, weather-resistant, and high-frequency interoperable models aligned with UL 943 across residential, commercial, and safety-critical applications. In March 2026, Leviton upgraded its entire residential GFCI lineup to be high-frequency rated, directly addressing nuisance tripping and interoperability with modern electrical loads per updated UL 943 Supplement SB testing—an illustrative example of how technical responsiveness to regulatory changes can become a market-facing differentiator.
Hubbell Wiring Device-Kellems emphasizes durability and code compliance across industrial, commercial, and institutional installations, offering hospital-grade and standard GFCI receptacles that appeal to customers prioritizing reliability in demanding environments. Through its Bryant branding, Hubbell also maintains a strong US manufacturing focus on tamper-resistant GFCI receptacles for commercial and industrial applications, reinforcing the value of regionally positioned production and specialized wiring device expertise.
Eaton Corporation manufactures GFCI receptacles and combination AF/GF devices for residential, commercial, and industrial settings, with integrated arc-fault protection options that address customers seeking consolidated safety solutions. Legrand, through its Pass & Seymour brand, continues to build on an innovation legacy in safety devices and a history of pioneering GFCI technology for North American and global markets. Southwire Company supplies a broad line of electrical safety products including GFCI devices for leakage protection in residential and commercial wiring applications, while Schneider Electric delivers residual current devices and GFCI-equivalent receptacles alongside broader circuit protection solutions for global markets. ABB rounds out the competitive picture with residual current devices across Type A, B, and F variants, supporting low-voltage leakage protection systems worldwide and emphasizing global standard alignment.
Our research does not merely catalog company profiles. It evaluates strategic positioning through the lens of product architecture, certification breadth, distribution density, and readiness for overlapping international standards. By mapping incumbents against regulatory adoption curves, we help clients identify where incumbents are vulnerable to disruption, where premium differentiation is achievable, and where consolidation or partnership opportunities may emerge as standards tighten and interoperability requirements escalate.
What the Report Delivers: A Practical Framework for 2026 Decision-Making
This study is built as an operational instrument, not a retrospective summary. It connects high-level market sizing with actionable intelligence across technology, regulation, regional demand patterns, and competitive strategy. The full report provides a structured exploration of the following dimensions.
Comprehensive Market Sizing and Forecast Architecture
The analysis traces historical performance from 2020 through the 2025 base year, then extends forward across a forecast horizon spanning 2026 through 2032. Revenue projections are anchored in consistent methodology, allowing leadership teams to model scenarios, stress-test planning assumptions, and align internal forecasts with independently validated market direction. Beyond headline figures, the report contextualizes growth drivers and drag factors so that readers can interpret shifts in the forecast rather than treat numbers as static outputs.
Segment-Level Demand Mapping
The study examines product-type evolution, including the respective roles of GFCI receptacles, AFCI receptacles, and dual-function devices that combine both protections. It analyzes end-user demand profiles across residential construction, commercial buildings, and industrial facilities to clarify where replacement cycles, code-driven upgrades, and new construction activity generate the strongest pull. Regional demand patterns are evaluated as part of a broader geographic intelligence framework, highlighting where regulatory timing, construction velocity, and adoption maturity create the most favorable near-term opportunities.
Light Switches and Electrical Sockets Market
Regulatory and Standards Intelligence
A dedicated regulatory module examines the collision of NEC provisions, UL supplement updates, IEC baseline standards, and country-specific wiring rules. The report explains how enforcement timelines, exception expirations, and testing protocol changes affect product design requirements, channel readiness, and procurement timing. It also addresses certification integrity and counterfeit risks, helping procurement teams and compliance officers strengthen verification practices.
Competitive Benchmarking and Strategic Options
Company-level assessments cover product portfolios, geographic footprints, certification postures, and recent strategic developments. By placing these assessments alongside market-share context and regulatory exposure, the report supports go-to-market decisions such as positioning, channel prioritization, regional expansion, and capability investment. Executives can use the analysis to sharpen value propositions, anticipate competitor moves, and evaluate where differentiation is sustainable versus where price competition will intensify.
Execution-Ready Guidance for Multiple Stakeholder Roles
The research is structured to serve multiple internal audiences simultaneously—strategy, procurement, product management, sales leadership, and risk/compliance. Each section is designed to answer practical questions: which applications deserve immediate sales focus, which product categories face the steepest compliance learning curve, where certification and authenticity risk management should be reinforced, and how forecast timing should influence inventory and production planning.
Why This Intelligence Matters Now
The convergence of a September 2026 HVAC exception expiration, the high-frequency interoperability mandate introduced through UL 943 Supplement SB, and a cascade of international standards revisions means the planning window for the 2026 market cycle is already compressed. Companies that wait for fully mature code adoption curves will find themselves reacting to demand rather than shaping it. Those that understand regional enforcement timing, product-type substitution dynamics, and competitive positioning early will be better placed to secure channel access, tailor product assortments, and optimize capacity allocation.
At the same time, market growth is not just a function of compliance. As electrical loads grow more complex and safety expectations rise across residential, commercial, and industrial settings, leakage current protection receptacles are increasingly evaluated not only on code conformance but also on reliability, nuisance-tripping performance, integration with modern equipment, and brand trust in safety-critical environments. That shift opens the door to premium positioning, but only for organizations that can substantiate performance claims, maintain certification visibility, and communicate value clearly to specifiers and installers.
Furthermore, the concentration profile of the market indicates that scale, distribution depth, and portfolio breadth confer advantages. Yet concentration also invites scrutiny. As more jurisdictions expand protection requirements and as standards bodies tighten interoperability and sensitivity criteria, mid-tier and regional players may find pockets of opportunity where incumbents are slower to adapt or where specialized certification and local code knowledge create temporary barriers. Identifying those pockets requires the kind of segmented, scenario-aware analysis only a comprehensive study can provide.
From Insight to Action: The Case for Full Access
This article offers a calibrated preview of the strategic logic underpinning our market research. It demonstrates the scale of the opportunity, the regulatory forces reshaping demand, the competitive forces defining positioning, and the operational questions that leaders must answer before the 2026 planning cycle settles into execution. Yet the full strategic value lies in the details that cannot be responsibly summarized in a high-level brief: the segment-by-segment demand architecture, the regional timing differentials, the certification and counterfeit risk map, the company-by-company strategic posture, and the scenario frameworks that translate forecast curves into procurement and production decisions.
Our Worldwide Leakage Current Protection Receptacles Market Research Report is designed to give leadership teams exactly that level of clarity. It closes the gap between macro growth signals and micro execution requirements, enabling informed decisions about where to invest, how to position, and when to move. For organizations serious about capturing value in a market shaped by tightening standards, evolving load profiles, and intensifying competitive dynamics, the full report is the essential next step.
Access the complete study to unlock the segmented forecasts, competitive assessments, regulatory impact analysis, and strategic recommendations that will inform confident 2026 decision-making and the years that follow.
For detailed analysis of this topic, please visit the official page: Worldwide Leakage Current Protection Receptacles Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Cryogenic Ball Valve Market Worth $1.54B in 2025, Projected 6% CAGR Through 2032
By pmarketresearch, 2026-09-17
Strategic Intelligence for a Low-Temperature Economy: Introducing the Worldwide Cryogenic Ball Valve Market Report
The global industrial landscape is undergoing a structural shift toward low-carbon energy systems, advanced industrial gases, and ultra-low temperature fluid handling. At the center of this transition sits a highly specialized component: the cryogenic ball valve. As LNG infrastructure expands, hydrogen pathways mature, and air separation capacity scales, manufacturers, EPC contractors, and procurement leaders face a complex environment defined by stringent material requirements, rigorous certification regimes, and a competitive field of international suppliers. Our newly released Worldwide Cryogenic Ball Valve Market research provides the analytical backbone required to navigate these dynamics with confidence.
This article previews the strategic architecture of the study and demonstrates why it is positioned as a decision-grade intelligence asset for 2026 planning cycles. Rather than offering surface-level summaries, the report connects macro market trajectories with operational realities, competitive positioning, and the technical standards that shape procurement, expansion, and partnership choices across the cryogenic valve ecosystem.
Why Cryogenic Ball Valves Have Become a Strategic Focus
Cryogenic ball valves are engineered to maintain sealing integrity, material ductility, and operational reliability at temperatures that would compromise conventional valve designs. Service conditions often extend down to -196°C and below, requiring careful selection of austenitic stainless steel grades such as 304L and 316L, validated trim configurations, and specialized packing technologies that mitigate fugitive emissions while preserving low-temperature performance.
The demand environment is being reshaped by several overlapping forces. LNG liquefaction, transportation, storage, and regasification continue to drive substantial valve procurement. At the same time, industrial gas production, air separation plants, petrochemical processing, and emerging hydrogen applications are broadening the addressable market. These sectors share a common requirement: flow control components that can withstand thermal shock, maintain leak-tight performance, and satisfy fire-safe and low-emission certification expectations.
The result is a market where engineering maturity, testing rigor, and compliance documentation are not optional enhancements but foundational competitive differentiators. This is precisely the environment in which a data-rich, technically grounded market study becomes indispensable.
Market Trajectory and the 2026–2032 Outlook
The report places current market behavior in the context of a multi-year growth arc. Drawing on historical data from 2020 through 2025 and extending forecast modeling through 2032, the study shows a market that has progressed from approximately 1,152.0 million USD in 2020 to an estimated 1,540.0 million USD in 2025, with continued expansion projected into the forecast window. The baseline year is 2025, and the analysis forecasts a compound annual growth rate of 6.0 percent through 2032.
This trajectory reflects more than simple volume growth. It captures a market in which revenue composition is being reshaped by shifting project pipelines, regional procurement patterns, and the increasing importance of specialized valve architectures for severe-service applications. The report translates these shifts into a structured view of where demand intensity is accumulating, how different valve configurations are being prioritized, and what this means for sourcing strategies, capacity planning, and competitive benchmarking.
Importantly, the study keeps its analytical lens broad enough to support executive-level direction while preserving enough granularity to inform product management, regional planning, and technical procurement teams. Readers can expect a balanced presentation of historical evolution, forward estimates, and the structural drivers that support those estimates.
What the Report Delivers: An Operational Blueprint
The study is built to be actionable. It moves beyond high-level market sizing and provides a detailed operational blueprint for organizations that need to align strategy with the realities of cryogenic valve procurement and production. The core content areas are organized to support multiple decision-making functions.
Market Structure and Segmentation Logic
The report breaks the market down along dimensions that matter to buyers and suppliers alike. It examines type-based demand patterns across major valve architectures relevant to cryogenic service, explores application-level demand concentration across LNG, industrial gases, energy and power, and other end-use segments, and maps regional demand distributions to help readers understand where project activity and procurement volumes are most concentrated. Rather than presenting isolated figures, the analysis connects segmentation outcomes to underlying drivers such as project geography, processing requirements, and standards compliance needs.
Competitive Positioning and Company Profiles
A central strength of the study is its competitive mapping. The report profiles a focused set of companies that shape the global cryogenic ball valve landscape, drawing on product portfolios, certification capabilities, material expertise, and application emphasis. These profiles are designed to support benchmarking, partnership evaluation, and market-entry assessment.
The analysis includes companies such as Habonim, which emphasizes certified cryogenic performance for LNG, industrial gases, air separation, petrochemical, and aerospace applications, with a strong focus on safety, fugitive emission prevention, and regulatory compliance. Flowserve, through its Worcester Controls, Valbart, and McCANNA lineage, provides cryogenic ball valve designs for LNG liquefaction, transportation, regasification, and severe service, aligned with standards including BS 6364, API 6D, and fire-safe certifications. KITZ Corporation contributes stainless steel and carbon steel cryogenic ball valve capabilities for LNG, LPG, ethylene, and other low-temperature fluids down to -196°C, with an emphasis on precision engineering and material integrity.
The study also examines Neway Valve, which offers top-entry cryogenic floating and trunnion-mounted designs for LNG, LPG, hydrogen, and air separation service down to -196°C, featuring low-emission packing and lip seal technology in compliance with API 6D and BS 6364. Parker Bestobell, part of Parker Hannifin, supplies uni-directional cryogenic ball valves as shut-off solutions for low-temperature gas production, industrial gases, and LNG, with an emphasis on reliable storage and transportation performance. Powell Valves manufactures ASME Class 150 and 200 cryogenic valve variants, including ball valve options in multiple sizes, materials, and trim configurations. IMI PBM provides fire-safe cryogenic ball valves with live-loaded stem packings across a defined size range, rated for extreme temperature service and designed for leak-free performance.
Additional profiles extend the competitive view across Europe, Asia, and North America. OMB Valves produces cryogenic and low-temperature ball valves for LNG compression, carriers, receiving terminals, and storage, supported by testing capabilities down to -196°C. Sesto Valves manufactures premium Italian cryogenic ball valves tested per industry standards at -196°C with full compliance to international certifications. Bürkert delivers cryogenic valves and systems for measuring, controlling, and regulating cryogenic fluids and gases in industrial applications. Velan Inc. includes cryogenic ball valves within its broader flow control solutions for severe service and low-temperature environments. Herose GmbH specializes in cryogenic valves for industrial gases such as oxygen, nitrogen, and argon, as well as LNG applications, with service capability at very low temperatures.
Standards, Testing, and Compliance Architecture
Cryogenic valve procurement is heavily conditioned by standards and testing protocols. The report addresses the regulatory and technical frameworks that buyers and suppliers rely on, including common alignment with BS 6364 for low-temperature service, ISO 15848 for fugitive emissions, API 607 fire-safe requirements, and ASME B16.34. It also discusses cryogenic testing practices aligned with ISO 28921 and BS 6364, which are used to validate sealing integrity and material performance after exposure to ultra-low temperatures followed by ambient testing.
By consolidating this compliance landscape, the study helps readers evaluate supplier claims more systematically, anticipate qualification requirements, and understand why technical documentation increasingly functions as a commercial asset in bidding, sourcing, and partnership discussions.
Competitive Concentration and Strategic Implications
Market structure matters. The study notes a moderately fragmented competitive environment, with a CR3 of 18.5 percent and a CR5 of 27.8 percent. This level of concentration implies that while leading specialists and multinational players hold meaningful positions, a broader field of regional and application-focused manufacturers also competes effectively through engineering differentiation, cost positioning, and localized service capabilities.
Worldwide Cryogenic Market
For buyers, this structure underscores the importance of multi-supplier evaluation, qualification strategy, and total-cost considerations that go beyond unit price. For suppliers, it highlights the value of credible certification portfolios, application-specific demonstrations, and consistent low-temperature performance documentation. The report uses this competitive context to frame where scale advantages matter, where specialization creates defensible positions, and where customer expectations are shifting most rapidly.
Industry Dynamics Shaping Decisions in 2026
Several current industry developments are woven into the market narrative to illustrate how the landscape is evolving in real time. Recent trade show activity and product announcements reflect growing attention to ultra-low temperature valve solutions for LNG, industrial gases, and low-carbon applications.
In March 2026, Teji Valve Group showcased cryogenic ball valves at NEFTEGAZ 2026 in Moscow, highlighting an ultra-low temperature top-loading online repairable ball valve positioned for energy and low-carbon applications. In September 2025, StelsPromMash / SPE Ltd. presented SPM cryogenic ball valves in DN 15–200 sizes, rated down to -269°C, for LNG, nitrogen, oxygen, and other media at Cryogen-Expo. Industrial Gases 2025 in Moscow. The Valve World Expo 2026 is scheduled to feature cryogenic valve solutions for LNG and green hydrogen applications, signaling continued event-level focus on the sector. Separately, Magival Valves announced an expansion into cryogenic valve production and presented related innovations at IVS 2024.
These developments point to a market where visibility, technical demonstration, and application-specific messaging are increasingly central to commercial positioning. They also reinforce the importance of monitoring exhibition activity, regional project exposure, and expansion announcements as early indicators of shifting supply-side priorities.
Material Realities and Procurement Considerations
The report also integrates material-sector context because cryogenic valve economics cannot be separated from raw material behavior. Austenitic stainless steel grades such as 304L and 316L remain dominant for cryogenic ball valves due to their retained ductility and toughness at -196°C. Yet material pricing and regional cost structures create meaningful procurement variability.
For example, public sector analysis indicates that in Q3 2024, stainless steel prices averaged approximately 3,985 USD per MT in the United States, 3,670 USD per MT in Germany, and 1,615 USD per MT in China. These differences affect manufacturing cost bases, sourcing decisions, and competitive positioning across regions. The study incorporates this kind of material context to help readers interpret price dynamics, anticipate input-cost exposure, and assess where regional manufacturing advantages may influence supply strategies.
Macro Demand Drivers and Application Expansion
Beyond immediate project cycles, the report frames several macro trends that are influencing long-term demand. Expansion in LNG infrastructure continues to be a major catalyst. Industrial gas production and air separation plant activity add durable demand. At the same time, emerging hydrogen applications are introducing new requirements for reliable performance at temperatures down to -196°C or lower. These pathways share a common need for flow control components that can operate safely in extreme conditions while meeting emission and fire-safety expectations.
The study explores how these drivers interact with application segmentation and regional deployment patterns. Rather than treating demand as a single curve, the analysis differentiates the forces shaping LNG-led procurement, industrial gas consumption, energy and power requirements, and other end-use contexts. This multi-driver framework allows readers to stress-test assumptions and evaluate how changes in one sector could ripple through the broader cryogenic valve market.
How to Use This Study for 2026 Decision-Making
The report is designed to serve several decision functions simultaneously. For strategic planners, it provides a structured market narrative that links historical data, forecast direction, and the competitive environment. For product and engineering leaders, it offers a standards-and-application lens that clarifies where technical differentiation is most valued. For procurement and sourcing teams, it supports supplier evaluation by combining segmentation insight with company-level profiling and compliance context. For investors and market entrants, it presents a concise but rigorous view of concentration, expansion signals, and the material and regulatory factors that shape commercial viability.
In practice, the study can be used to compare regional opportunity emphasis, assess which valve types and applications are attracting the most demand attention, evaluate where certification and testing capabilities create competitive advantage, and identify how material cost variability may influence supplier selection. It also helps organizations align internal assumptions with market-level evidence, reducing reliance on fragmented or anecdotal intelligence.
Why This Report Differentiates Itself
The Worldwide Cryogenic Ball Valve Market study distinguishes itself through the integration of technical substance, competitive mapping, and forward-looking market structure. It does not treat cryogenic valves as a generic valve category. Instead, it reflects the reality that low-temperature service is a specialized market where material integrity, sealing reliability, testing protocols, and standards compliance directly affect commercial outcomes.
Worldwide Cryogenic Ball Valve Market
By combining company profiles, segmentation analysis, market concentration data, material-sector context, and recent trade and product developments, the report offers a comprehensive vantage point for organizations that need to make informed choices in 2026 and beyond. It is built to support both strategic positioning and operational follow-through.
Access the Full Intelligence
This article provides a structured preview of the study’s scope, analytical approach, and strategic relevance. To access the complete market sizing, segmentation detail, competitive profiles, standards framework, and forecast architecture, we invite you to explore the full Worldwide Cryogenic Ball Valve Market report. The complete version is designed to deliver the depth required for supplier evaluation, regional planning, product strategy, and investment decision-making in a market where precision matters at every temperature.
For detailed analysis of this topic, please visit the official page: Worldwide Cryogenic Ball Valve Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Pressure-Sensitive Tapes Market Hits $78.45 Billion in 2025, Projects 5.12% CAGR Through 2032
By pmarketresearch, 2026-09-17
Beyond Adhesion: Strategic Imperatives in the Global Pressure-Sensitive Tapes Market Through 2032
The pressure-sensitive tape (PSA) industry is no longer a commodity aftermarket or a passive manufacturing supplement. It has evolved into a strategic enabler of lightweighting, electrification, sustainable packaging, and precision assembly across multiple end-use sectors. As production volumes scale and performance thresholds tighten, executives must look beyond roll-per-roll comparisons and evaluate the structural economics, regulatory trajectories, and innovation pipelines that will define competitive positioning from 2026 through 2032. The newly updated Worldwide Pressure-Sensitive Tapes Market study translates these macro shifts into decision-grade intelligence for procurement, R&D, M&A, and market-entry teams operating at the intersection of materials science and industrial demand.
A Multiyear Trajectory Anchored in 2026 Decision-Making
The global market for pressure-sensitive tapes has demonstrated steady expansion over the past half-decade, supported by industrial recovery, packaging modernization, and downstream demand from electronics and automotive value chains. Historical records from 2020 through 2025 show a consistent upward curve, with market revenue reaching an estimated USD 78.45 billion in the base year of 2025. The forecast window extends through 2032, charting a forward path that begins at approximately USD 82.9 billion in 2026 and progresses toward an anticipated USD 111.27 billion by the close of the projection period. This growth trajectory, equivalent to a compound annual growth rate of roughly 5.12 percent, is not merely a function of volume expansion. It reflects deepening application penetration, formulation sophistication, and the substitution of mechanical fasteners with engineered adhesive systems in demanding environments.
Worldwide Pressure-Sensitive Tapes Market
For strategy teams, the 2026 inflection is especially timely. Executives are now calibrating capacity plans, sourcing relationships, and product roadmaps against a backdrop of shifting raw material economics, tightening environmental specifications, and the emergence of multi-functional PSA architectures. The study treats 2026 not as an isolated baseline but as the operational launchpad for a seven-year strategic arc. It reconciles historical momentum with forward-looking demand signals, enabling readers to stress-test capacity assumptions, assess regional investment logic, and identify where performance differentiation will yield margin protection in a moderately concentrated market structure.
What the Study Delivers: From Macro Signals to Actionable Playbooks
The core objective of this research is to convert rich market structure into practical guidance. Rather than offering a single headline figure, the analysis decomposes the market along three strategic axes—geography, backing material, and application—while maintaining strict focus on decision relevance. Each dimension is examined through the lens of cost structure, switching dynamics, substitution risk, and value-chain positioning. The report is designed to answer the questions that line managers actually face when allocating capital or re-engineering supply plans:
- Where is demand most durable across the forecast period, and which applications are gaining share as a result of structural product changes rather than cyclical lifts?
- Which backing materials are absorbing investment and formulation attention, and how do substrate choices influence performance trade-offs, processing speed, and recyclability claims?
- How do regional demand profiles differ in terms of growth intensity, industrial composition, and regulatory exposure, and what does that imply for local production, sourcing, and go-to-market strategy?
- Which competitive behaviors are shaping price realization, differentiation, and customer retention, and where do market leaders concentrate their innovation and commercial resources?
- What procurement and formulation strategies can offset volatility in key inputs while satisfying the environmental and performance requirements now entering specifications?
Each analysis module pairs quantitative structure with qualitative interpretation, allowing readers to move from observed patterns to prioritized actions. The study also flags where end-use cycles diverge from raw material trends, helping procurement and finance teams separate noise from structural cost pressure. Importantly, the report intentionally withholds the deeper drill-down breakdowns that underpin these conclusions. The intent is deliberate: the executive summary and segment overview establish the logic and scale of opportunity, while the full ship-to-ship, application-level, and formulation-specific intelligence remains reserved for stakeholders who need to build models, negotiate contracts, or commit investment. Decision-makers who require precise volume splits, material-level pricing correlations, and granular regional overlays are directed to the complete dataset, where those figures can be integrated directly into internal planning systems.
Competitive Architecture: Scale Leaders, Specialty Specialists, and the New Innovation Frontier
The competitive landscape is defined by a mix of diversified industrial groups, adhesive-focused specialists, and regional manufacturing platforms. A handful of established players command a meaningful share of global volume, but the remainder of the market remains fragmented enough to reward targeted innovation and application-specific engineering. Among the organizations profiled in the study are globally recognized leaders and highly specialized contributors whose product architectures, end-use coverage, and development cadence shape the market’s direction.
3M Company continues to anchor its PSA portfolio around broad application coverage, spanning VHB bonding tapes, specialty industrial grades, packaging solutions, and medical-grade formats for electronics, automotive, construction, and healthcare. Avery Dennison Corporation leverages its Performance Tapes division to supply acrylic foam bonding tapes, double-sided constructions, and solutions for automotive, electronics, industrial assembly, and specialty applications. tesa SE concentrates on industrial, electronics, automotive, and consumer segments with double-sided foam tapes, masking grades, and high-performance bonding systems. Nitto Denko Corporation brings depth in pressure-sensitive tapes for electronics, automotive, industrial, and medical uses, with an emphasis on functional materials and high-tech applications. Intertape Polymer Group Inc. focuses on pressure-sensitive packaging tapes, industrial tapes, and specialty PSA products, placing notable weight on sustainable and recyclable packaging and industrial solutions. LINTEC Corporation addresses labeling, industrial, electronics, and healthcare requirements with advanced functional tapes and PSA materials. Berry Global Group, Inc. contributes engineered materials for packaging, industrial, and specialty applications through its broader film and tape portfolio. Lohmann GmbH & Co. KG develops high-performance PSA tapes and bonding solutions for industrial, electronics, automotive, and medical sectors. Scapa Group plc, under Mativ Holdings, supplies PSA tapes for healthcare, industrial, and specialty bonding, including custom die-cut services. Saint-Gobain S.A. offers performance PSA tapes and films through its Performance Plastics division for industrial, electronics, and high-temperature environments. Shurtape Technologies, LLC serves packaging, industrial, HVAC, and construction markets with a broad PSA range. Henkel AG & Co. KGaA provides PSA technologies and tapes for industrial assembly, packaging, and consumer applications via its Adhesive Technologies segment. American Biltrite Inc. rounds out the competitive map with tapes for automotive, graphics, HVAC, industrial, insulation, and surface protection uses.
This roster is not simply a list of incumbents. It reveals where specialization is being monetized and where consolidation logic may emerge. The study examines how these players compete on formulation performance, application engineering, and service models such as custom die-cutting and bonded assemblies, rather than on price alone. It also tracks recent developments that signal where the industry is placing its bets. In April 2026, multiple manufacturers including 3M, Henkel, and Sika accelerated bio-based and low-VOC PSA formulations alongside UV-curable PSA technologies for packaging, medical, and industrial applications. In May 2025, 3M Company introduced new high-performance acrylic PSA tapes designed for electric vehicle battery assembly and thermal management. That same year, 3M reported full-year 2024 sales with 2025 guidance pointing to low single-digit growth in industrial tapes and bonding systems. Separately, Intertape Polymer Group achieved a sustainability milestone in September 2025, reaching 75 percent of packaging products by revenue classified as recyclable, reusable, or compostable, thus meeting its 2025 target ahead of schedule. These events collectively illustrate a market in which product performance, regulatory compliance, and circularity claims are becoming inseparable from commercial positioning.
From Formulation Volatility to Application Resilience: What Is Moving the Market Now
The PSA market does not expand in a vacuum. Its near-term rhythm is shaped by raw material economics, regulatory pressure, and end-use system design. Recent data points highlight the tension between input cost variability and the need for consistent performance. The U.S. Producer Price Index for adhesive manufacturing primary products stood at approximately 379.21 in June 2025, reflecting a year-over-year increase of about 4.6 percent. At the same time, polypropylene film backing prices were reported around USD 1,525 per metric ton in the U.S. during the same period. These figures matter because substrate costs and adhesive formulations jointly determine total cost of ownership, line speed compatibility, and the economics of converting and downstream assembly.
Beyond finished inputs, the underlying chemistry is vulnerable to feedstock dynamics. Acrylate monomer prices, critical for water-based PSAs used in pressure-sensitive tapes, are influenced by propylene feedstock costs, with historical volatility exceeding 50 percent during prior shortage periods. Hydrocarbon tackifier resins for hot melt PSAs have also faced tight supply conditions, particularly in the U.S., adding further cost pressure to specific product families. At the same time, regulatory momentum is accelerating the adoption of low-VOC and bio-based PSA formulations, particularly in Europe and North America for packaging and medical applications. This creates a dual imperative: manage near-term input volatility while investing in formulations that satisfy environmental specifications without compromising adhesion, tack, or aging performance.
These dynamics are not isolated cost stories. They interact with application-level demand in ways that determine which product families gain traction and which face margin compression. Packaging continues to be a dominant demand driver, supported by e-commerce, labeling evolution, and sustainability-driven specification changes. Building and construction, electrical and electronics, automotive, and healthcare each bring distinct performance requirements and procurement cycles. The study analyzes how these demand pillars interact with backing material choices, adhesive chemistry, and regional regulatory regimes to shape growth intensity and competitive positioning. The precise magnitude of each application’s contribution and the exact regional revenue splits are presented in the full report, where they can be used to calibrate portfolio priorities, scenario planning, and sourcing strategies with precision.
Pressure Sensitive Adhesive Tapes Market
Where the Market Is Heading and Why the Full Intelligence Set Matters
Looking toward 2032, the pressure-sensitive tape industry is positioned for continued expansion, but the composition of that growth will matter more than the headline trajectory. Electrification, lightweight assembly, high-performance bonding in electronics, and recyclable packaging architectures are reshaping demand at the application frontier. At the same time, formulation innovation around bio-based chemistry, low-VOC systems, and UV-curable processes is redefining what “acceptable performance” means in regulated and sustainability-conscious markets. The question for executives is no longer whether the market will grow, but where value will accrue as performance standards rise and input economics remain sensitive to feedstock cycles and supply tightness.
This is precisely where the complete Worldwide Pressure-Sensitive Tapes Market study adds decision-grade value. It connects the macro trajectory from 2020 through 2032 with segment-level logic, competitive behavior, and the raw material and regulatory forces that influence margin and speed-to-market. The report’s structure enables readers to identify durable demand, assess substitution risk, evaluate regional opportunity, and map competitive differentiation without relying on generic industry narratives. To preserve analytical integrity while encouraging rigorous use, the executive overview establishes scale, direction, and strategic logic, while the deeper regional, application, and material-level breakdowns are reserved for the full dataset. That design ensures that the organizations relying on these figures for capacity planning, contract negotiation, product roadmap decisions, and market-entry analysis can work from the precise numbers rather than rounded proxies.
For leaders who need to move from directional confidence to executable strategy, the complete report provides the structured intelligence required to turn market momentum into disciplined advantage. The full segmentation details, regional overlays, application contrasts, competitive benchmarks, and formulation-related cost context are available in the complete study, where they can be integrated directly into internal models and planning cycles. In a market where performance, compliance, and cost must be managed together, access to the underlying data architecture is not a luxury—it is the foundation of credible decision-making.
For detailed analysis of this topic, please visit the official page: Worldwide Pressure-Sensitive Tapes Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Arc Suppression Reactors Market to Hit $1.5B by 2032 at 5.24% CAGR
By pmarketresearch, 2026-09-17
Strategic Horizons: The Worldwide Arc Suppression Reactors Market Through 2032
The global landscape for arc suppression reactors is undergoing a measured but decisive transformation. As distribution networks age, renewable integration accelerates, and safety standards tighten, utilities and industrial operators are revisiting the fundamentals of neutral grounding. Our latest Worldwide Arc Suppression Reactors Market research translates this complex shift into a structured, decision-ready intelligence framework. Built on a rigorous historical reconstruction and a forward-looking forecast horizon, the study is designed to help engineering leaders, procurement directors, and corporate strategists align capital allocation with the technical and regulatory realities of the next decade.
The market has already crossed a meaningful threshold. From a baseline of 845.5 million USD in 2020, revenue expanded steadily to 1050.0 million USD by 2025, reflecting sustained demand across transmission, distribution, and industrial power environments. The trajectory continues upward through the forecast period, reaching an estimated 1075.73 million USD in 2026 and climbing toward 1501.27 million USD by 2032. This expansion is anchored by a compound annual growth rate of 5.24 percent, a pace that signals durable structural demand rather than a temporary procurement cycle. For organizations planning multi-year equipment roadmaps, this cadence offers a reliable baseline for budgeting, capacity planning, and supplier engagement.
What sets this research apart is its emphasis on actionable segmentation and competitive clarity. Rather than presenting a single aggregate figure, the analysis decomposes the market into type, application, and regional dimensions, allowing decision makers to identify where growth is genuinely concentrated and where saturation or substitution risk may be emerging. The report also maps the competitive field with precision, profiling the manufacturers that are shaping product evolution, certification practices, and intelligent control integration. The result is a reference document that can be used directly in vendor qualification, technology selection, and regional expansion planning.
Market Trajectory and the Case for Early Positioning
The growth path from 2026 through 2032 is not uniform, and that unevenness is precisely where strategic advantage is created. Early forecast years show a steady climb from 1075.73 million USD in 2026 to 1124.86 million USD in 2027, followed by a step-up to 1191.88 million USD in 2028. The later years accelerate further, with the market reaching 1320.11 million USD in 2029, 1403.29 million USD in 2030, and continuing toward 1447.89 million USD in 2031 before settling at 1501.27 million USD in 2032. This pattern suggests that the most significant demand uplift will arrive as legacy substations undergo modernization and as newer grid architectures adopt resonant grounding as a default safety and reliability measure.
For executives, the implication is clear: waiting until a procurement need becomes urgent often means entering a more crowded, less flexible negotiating environment. Companies that map their required specifications against the evolving product landscape now can secure better technical fit, smoother integration with existing protection schemes, and more predictable lead times. The forecast also provides a useful sanity check for internal projections. If an organization's planned growth assumptions deviate sharply from the market's documented cadence, the discrepancy is worth investigating before it becomes a budget or supply-chain surprise.
The research further supports scenario planning by linking volume movement to the underlying drivers that govern adoption. These include the phase-out of aging equipment, the expansion of medium-voltage distribution in dense urban and industrial corridors, and the technical requirements associated with connecting distributed generation to resilient network topologies. By treating these drivers as interlocking forces rather than isolated trends, the study helps teams build investment cases that hold up under regulatory review and operational stress testing.
Segment Architecture and Where Growth Concentrates
Understanding the market's internal structure is essential for targeting the right opportunities. The report divides the landscape along three practical axes: product type, application setting, and geographic region. Each axis reveals a different part of the story, and together they give leaders a multi-dimensional view of where value is being created and where competition is intensifying.
Product Type Dynamics
The type segmentation captures the spread between conventional fixed designs and more adaptable tuning architectures. Automatic plunger-type reactors represent the largest share of market activity, reflecting their wide applicability in networks that require responsive compensation and streamlined maintenance. Fixed gap reactors continue to serve specialized installations where simplicity, proven performance, and cost predictability remain priorities. Step-adjustable reactors occupy a strategically important niche for operators that need flexibility without adopting fully automatic systems. This triad of options means that specification decisions should be driven by fault-current behavior, network capacitance variability, and the operator's tolerance for manual intervention versus automated tuning.
Application Contexts
Application segmentation shows how arc suppression reactors are deployed across the power ecosystem. Power substations form the dominant usage environment, where resonant grounding is closely tied to protection coordination and continuous service during single-phase earth faults. Industrial power grids represent a substantial second pillar, driven by facilities that cannot tolerate unplanned downtime and that require grounding solutions matched to their load profiles and fault levels. Renewable energy integration is an increasingly visible segment, as connecting wind, solar, and storage assets to medium- and high-voltage networks places new demands on fault management and voltage stability. The interplay among these application areas helps explain why demand is not simply a function of grid size, but of grid function, reliability expectations, and the pace of generation mix change.
Regional Footprints
Regional segmentation provides a compass for where capacity, supply chains, and project pipelines are most active. The analysis highlights a broad geographic distribution, with significant activity across Asia Pacific, Europe, North America, the Middle East and Africa, and Latin America. Each region carries its own mix of drivers: legacy network renewal, expansion of distribution infrastructure, industrial electrification, and the modernization of protection philosophy. Importantly, regional dynamics are not interchangeable. A strategy that works in one market may underperform in another if it fails to account for local standards, procurement habits, and the prevalence of specific grounding practices. The report's regional breakdown helps teams avoid one-size-fits-all assumptions and instead calibrate entry timing, partner selection, and specification emphasis to the realities of each market.
Competitive Landscape: Capability, Certification, and Intelligent Control
The competitive environment is defined by a mix of established specialists and regionally strong manufacturers, each pursuing distinct value propositions. The study profiles the companies that matter most to procurement and engineering teams, focusing on product architecture, compliance posture, insulation technology, and the growing importance of intelligent monitoring and remote diagnostics.
Specialist Leaders and Technical Differentiation
Trench Group remains a reference point for resonant earthing solutions in distribution networks up to 36 kV, with offerings that span Eco Fluid and conventional fluid arc suppression coils, stepless adjustment, and IEC 60076-6 compliance. Its emphasis on sustainable ester-based insulation under the Regenera label, along with air-core and oil-immersed variants, illustrates how product portfolios are being shaped by both performance and environmental considerations. Swedish Neutral AB continues to advance the concept of combining arc suppression coils with residual current compensation through ground fault neutralizer systems, targeting near-zero fault current reduction in medium- and high-voltage networks. Its automatic tuning devices reflect a broader industry shift toward continuous monitoring and dynamic inductance adjustment. SUNTEN reinforces the practical side of this evolution with automatic tuning arc suppression coils designed for 35 kV and below substations, offering capacities that range from 10 to 4000 kvar, low-noise operation, and insulation classes suited to demanding distribution environments.
Regional Manufacturing Strength
A strong contingent of manufacturers in China and India adds scale, customization, and cost-competitive options to the market. Shrihans Electricals produces oil-immersed iron-core arc suppression reactors as single-phase variable inductance units for resonant neutral grounding. Zhejiang Nengrong Electric Power Equipment Co., Ltd. supplies reactors with high-precision compensation, stability, and intelligent control for urban, rural, and industrial power systems, and has been emphasized in recent supplier rankings for its intelligent control focus. Xi'an XD Power Capacitor Co., Ltd. provides customized design options using high-quality materials and advanced manufacturing methods. Baoding Tianwei Baobian Electric Co., Ltd. leverages transformer technology to deliver low-loss, high-insulation designs with effective heat dissipation. Shandong Taikai Electric Group Co., Ltd. integrates intelligent monitoring, remote control, and fault diagnosis functions. Henan Pinggao Electric Co., Ltd. focuses on high-voltage resistant designs with safety features and modular construction. Changzhou Huadian Electric Co., Ltd. offers compact, high-efficiency coil reactors for space-limited substations. Farady Electric Co., Ltd. supplies Petersen coils and arc suppression coils for 11-35 kV, including ground-fault neutralizers. These companies collectively broaden the choices available to operators and increase the importance of specification-driven evaluation rather than brand-only selection.
European and Specialized Players
Beyond the large manufacturing centers, several European and specialty firms contribute important design depth. SEA Trasformatori produces Petersen coils regulated by steps or stepless, often combined with earthing transformers and shunt reactors. Ardan Transformers manufactures Peterson coils compliant with IEC 60076-6, with designs adapted to specific project requirements. Together, these players reinforce the market's technical diversity and remind buyers that compliance, mechanical adaptation, and integration with surrounding equipment can be just as decisive as base inductance rating.
Industry Dynamics: Standards, Materials, and Automatic Tuning
Three dynamics are reshaping how arc suppression reactors are specified and evaluated. First, the IEC 60076-6 standard continues to anchor product expectations, covering the ability to withstand rated short-time neutral current and temperature rise requirements. Compliance is no longer a background checkbox; it is a fundamental filter in procurement and engineering review. Second, the shift toward eco-friendly ester-based insulating fluids is gaining relevance as operators seek higher flash points, improved fire safety, and reduced environmental impact compared with conventional mineral oil. This transition affects not only safety cases but also maintenance planning, disposal considerations, and long-term operational risk.
Third, automatic tuning is becoming central to the value proposition of modern reactors. By continuously monitoring network conditions and adjusting inductance to match capacitance changes, automatic tuning devices help maintain minimal residual fault current even as network configuration evolves. This capability is especially important in networks where distributed generation, load switching, and sectionalizing changes alter capacitive current profiles over time. Combined with intelligent monitoring and remote diagnostics, automatic tuning supports a shift from reactive maintenance toward condition-aware operation. The report examines how these capabilities are being incorporated into product designs and what they mean for protection coordination, commissioning, and lifecycle cost.
Worldwide Arc Suppression Reactors Market
Recent developments reinforce the direction of travel. In early 2025, Zhejiang Nengrong Electric Power Equipment Co., Ltd. was featured as a top supplier of arc suppression reactors in China, with emphasis on intelligent control systems. Later in the year, A. Eberle received special recognition in the TOP 100 Awards 2025 for innovation in energy future, related to arc suppression coil regulators. Trench Group also maintained active sustainability certification for its arc suppression coils, reflecting ongoing attention to environmental and operational performance. These events are not isolated headlines; they are indicators of where product development, supplier reputation, and customer expectations are converging.
Concentration, Procurement, and the Rhythm of Decision Making
The market's competitive structure matters because it influences pricing behavior, availability, and the negotiating leverage of buyers. Concentration metrics show that the top three firms account for approximately 38.45 percent of market revenue, while the top five reach roughly 52.18 percent. This level of concentration indicates a market where scale, certification, and product breadth confer real advantages, but it also leaves meaningful room for specialized players and regional manufacturers to compete on fit, customization, and service. For procurement teams, the practical takeaway is that supplier selection should balance breadth and depth: large portfolios can simplify multi-project standardization, while focused manufacturers can deliver sharper alignment with particular voltage classes, substation layouts, or control requirements.
From a decision-making standpoint, the forecast period creates a clear rhythm for action. The 2026-2032 window is long enough to justify technology selection and supplier partnership decisions, yet near enough that assumptions must be tested against current standards, available intelligent features, and realistic project pipelines. Organizations that use this research to align internal requirements with external market structure can reduce specification rework, improve tender quality, and avoid late-stage surprises when lead times tighten or certification expectations change.
Why This Research Matters for 2026 Strategy
The strategic value of this study lies in its ability to convert a broad market narrative into deployable intelligence. The headline figures establish context, but the real power is in the segmentation logic, the competitive profiles, and the mapping of technical trends to procurement consequences. Leaders can use the report to answer questions that directly affect 2026 planning: which product types are most relevant to a given network profile, which application environments will drive demand in the near term, which regions offer the strongest opportunities for expansion or partnership, and which suppliers combine compliance, innovation, and practical deployment experience.
Equally important, the research is structured to support comparison without oversimplifying. It allows engineering and commercial teams to evaluate trade-offs among automatic, fixed, and step-adjustable designs; to weigh the implications of ester-based insulation and intelligent monitoring; and to assess whether a regional sourcing strategy should be broadened or deepened. By presenting these choices within a coherent market framework, the study reduces the risk of decisions made on incomplete technical or competitive information.
For organizations that need to move quickly but carefully, the report serves as both a reference and a planning tool. It helps quantify the scale of the opportunity, clarifies where differentiation is possible, and identifies the points in the value chain where informed selection creates the greatest downstream benefit. In a market where reliability, safety, and compliance are non-negotiable, that clarity is not a luxury; it is a prerequisite for sound capital deployment.
Looking Ahead: From Market Intelligence to Execution
The next phase of market development will reward organizations that connect strategic insight to operational execution. That means aligning specification practices with the realities of automatic tuning and condition monitoring, evaluating supplier claims against the standards and certification signals that matter, and selecting regional pathways that reflect local network needs rather than generic growth narratives. It also means using the forecast not as a fixed prediction, but as a structured baseline against which internal assumptions can be challenged and refined.
The full research report expands each of these themes into detailed analysis, company profiles, segmentation insight, and decision-oriented commentary. It is designed for teams that need more than a market summary: teams that want to understand how the worldwide arc suppression reactors market is structured today, how it is likely to evolve through 2032, and how to position their organizations to act with confidence in 2026 and beyond. For readers ready to move from overview to execution, the complete study provides the deeper intelligence required to make those choices with precision.
Worldwide Anode Saturable Reactor Market
For detailed analysis of this topic, please visit the official page: Worldwide Arc Suppression Reactors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Baobab Powder Market to Hit $568.91M by 2032, Reflecting 7.28% CAGR in New PW Consulting Report
By pmarketresearch, 2026-09-17
Strategic Intelligence in the Global Baobab Powder Market 2026-2032: Navigating Growth, Regulation, and Competitive Dynamics
The global baobab powder market stands at a pivotal inflection point. As consumer demand for plant-based superfoods, clean-label ingredients, and sustainable sourcing continues to accelerate, baobab fruit powder has transitioned from a niche wellness additive to a mainstream category across food and beverage, nutraceutical, and cosmetics applications. Our latest Worldwide Baobab Powder Market study delivers a comprehensive, decision-ready intelligence framework designed specifically for executives, procurement leaders, and strategic planners operating between 2026 and 2032.
Built on extensive primary research, analyst triangulation, and rigorous valuation modeling, this report equips organizations with the macro and micro insights required to allocate capital, secure supply chains, and position product portfolios ahead of structural market shifts. Rather than offering static snapshots, the analysis maps the trajectory of demand, evaluates the competitive landscape, and isolates the regulatory and operational variables that will define profitability in the coming years. This article provides a strategic preview of the report’s scope, methodology, and actionable architecture, demonstrating why it has become an essential reference for enterprise decision-making.
Market Trajectory and Strategic Context
The baobab powder market has demonstrated consistent expansion over the past half-decade, with the sector surpassing 324 million USD in 2024 and reaching approximately 347.87 million USD in 2025. Looking forward, our baseline projections indicate that market revenue will climb to 373.19 million USD in 2026, followed by a steady ascent toward 568.91 million USD by 2032. This trajectory translates into a compound annual growth rate of 7.28 percent across the forecast horizon, reflecting sustained institutional and consumer adoption, expanding formulation possibilities, and deepening global distribution networks.
Several structural factors underpin this momentum. Regulatory clarity has improved considerably across key import markets, with baobab fruit pulp and powder securing novel food approvals and regulatory endorsements in both the European Union and the United States. These milestones remove historical barriers to entry for food and beverage manufacturers, enabling faster product development cycles and broader retail penetration. Simultaneously, the U.S. Food and Drug Administration proposed a front-of-package nutrition labeling framework in 2025 that introduces simplified Low, Medium, and High indicators for saturated fat, sodium, and added sugar across most packaged goods, including superfood powders. While compliance requirements will reshape packaging and formulation strategies, they also create an opportunity for ingredient suppliers and brands that can position baobab powder as a clean, nutrient-dense, and label-friendly alternative.
Trade policy further shapes the competitive environment. The African Growth and Opportunity Act was renewed by the United States through December 31, 2026, preserving duty-free access for qualifying African exports, including baobab products from eligible countries. This provision reinforces the strategic importance of African-origin sourcing for North American importers and provides a measurable cost advantage for supply chains that align with AGOA eligibility criteria. On the pricing side, raw material economics have shifted meaningfully. Global export and import prices for baobab fruit powder trended downward in 2024, settling in a range of roughly 0.54 to 0.77 USD per kilogram, compared with elevated levels observed in 2023. This compression introduces both margin considerations and procurement opportunities, making it essential for buyers to distinguish between volatile spot pricing and long-term contract structures.
Worldwide Blackcurrant Powder Market
Report Architecture and Decision-Ready Intelligence
The Worldwide Baobab Powder Market report is engineered to translate complex market signals into executable strategy. It opens with a foundational market overview that establishes baseline sizing, growth velocity, and the macroeconomic and consumer trends shaping end-use demand. From there, the analysis moves into segmentation and demand mapping, examining how different natures of baobab powder and distinct end-use verticals contribute to overall revenue generation. Rather than presenting isolated percentages, the report contextualizes each segment through volume dynamics, pricing behavior, formulation trends, and buyer procurement patterns, enabling stakeholders to identify where demand is consolidating and where whitespace opportunities are forming.
A substantial portion of the study is dedicated to competitive intelligence. The report profiles the organizations that define pricing norms, control distribution pathways, and set quality expectations across multiple geographies. Coverage includes harvesters, bulk suppliers, wholesale distributors, and specialty ingredient formulators operating from North America, Europe, Southern Africa, and West Africa. Profiles capture headquarters locations, supply chain configurations, certification portfolios, product range breadth, and recent commercial activities. By mapping these players against their operational footprints and strategic positioning, the report provides a realistic view of who controls supply at each tier and how value is distributed across the chain.
The regulatory and compliance section addresses the practical requirements that govern market entry and ongoing operations. It details novel food obligations, food safety and quality standards, labeling expectations, and the documentation needed to maintain consistent import eligibility. This guidance is particularly valuable for brands expanding into the European Union, where quality control consistency and certification alignment directly influence clearance speed and retailer acceptance. The report also examines how proposed packaging and nutrition labeling frameworks will influence ingredient positioning, especially for superfood applications that depend on transparent front-of-pack communication.
Supply chain and raw material dynamics receive dedicated analysis, including export and import price movements, logistical considerations, and the impact of trade policy on landed costs. The study further incorporates a forward-looking risk and opportunity assessment that highlights concentration patterns, sourcing dependencies, certification requirements, and the commercial implications of sustainability verification. By integrating these elements, the report gives procurement teams, product developers, and strategy leaders a single reference point for evaluating cost structures, supply resilience, and market entry feasibility.
Competitive Landscape and Strategic Positioning
The baobab powder market is characterized by a broad, multi-tiered supplier base rather than heavy consolidation. Our concentration analysis indicates that the top three firms account for approximately 18.42 percent of market revenue, while the top five represent about 25.16 percent. This fragmented structure creates both challenges and opportunities. On one hand, it means that no single organization dominates pricing across all regions or end-use segments. On the other hand, it requires buyers to navigate a diverse ecosystem of harvesters, bulk exporters, regional warehouses, and specialty distributors, each with distinct capabilities, certification statuses, and commercial models.
Worldwide Baobab Powder Market
Several organizations define the market’s operational center of gravity. Baobest, also known as Baobab Foods LLC, operates from the United States and supplies organic baobab fruit powder to food, beverage, and wellness brands worldwide, supported by global shipping and premium quality certifications. B'Ayoba, based in Zimbabwe, is widely recognized as one of the largest global producers of ethically and sustainably harvested baobab products, sourcing from Southern African rural communities and standing as the first entity certified under the FairWild label. Baobab Exports, headquartered in South Africa with warehouses in the Netherlands and the United States, functions as a leading bulk organic supplier with international distribution reach and a foundational role in the African Baobab Alliance. KAIBAE, based in the United States, provides wild-harvested, certified organic baobab fruit powder, oil, and leaf to food, beverage, nutraceutical, and cosmetic markets, and recently expanded its North American footprint through a distribution partnership with Caldic North America to support nutrition companies seeking natural vitamins, minerals, fiber, and polyphenols.
Beyond these anchor players, the market includes a wide range of specialized and regional participants. Baobab Fruit Company Senegal serves as a major global producer of organic wholesale baobab powder and oil for food products, cosmetics, and animal feeds. Afriplex Pty Ltd produces baobab powder alongside oil and pulp, actively expanding its product lines for the ingredient market. Abbott Blackstone operates as a European wholesale distributor of organic baobab powder sourced from East Africa, supplying bulk quantities to food manufacturers and retailers. Nutriboost Superfoods functions as a B2B supplier offering high-quality organic powder in bulk, including private label options for superfood applications. Woodland Foods integrates baobab powder into chef-focused and foodservice applications, while Nexira supplies processed powder for food and nutraceutical uses with quality testing and formulation support. Additional contributors such as Eco-Products, Aduna Limited, Mighty Baobab Limited, and Organic Africa extend the supply base across Africa and Europe, each emphasizing distinct sourcing models, certification strategies, and application focuses.
This competitive breadth means that strategic success depends less on identifying a single dominant supplier and more on aligning sourcing decisions with product positioning, compliance requirements, volume needs, and sustainability expectations. The report evaluates these players not as a static roster, but as a living competitive field in which distribution partnerships, certification milestones, and regional warehouse networks continuously reshape access and pricing power.
Regulatory, Trade, and Sourcing Dynamics
Regulatory alignment remains one of the most decisive variables for market participants. Baobab powder’s progression through novel food approvals and regulatory endorsements in the European Union and United States has opened substantial application scope, but it has also raised the bar for documentation, traceability, and quality consistency. Importers and manufacturers must navigate evolving food safety expectations, maintain rigorous quality control across batches, and ensure that sourcing documentation supports both regulatory compliance and retailer requirements. The report details these obligations in practical terms, helping teams anticipate clearance requirements and reduce the risk of disruption.
Trade policy continues to influence landed cost and supply strategy. The renewal of AGOA through the end of 2026 preserves preferential access for qualifying African exports, reinforcing the commercial rationale for sourcing from eligible countries. For organizations building or expanding North American supply chains, this framework offers a measurable advantage, but it also requires careful eligibility verification and supply chain alignment. At the same time, raw material pricing dynamics remain fluid. The decline in global export and import prices during 2024 illustrates how market conditions can shift quickly, rewarding organizations that combine strategic contracting with active price monitoring and diversified sourcing options.
On the consumer and retail side, emerging labeling frameworks are poised to affect product architecture. The FDA’s proposed front-of-package indicators for saturated fat, sodium, and added sugar will influence how superfood powders are presented and evaluated by shoppers. Brands and ingredient suppliers that can demonstrate clean nutritional profiles, transparent sourcing, and formulation flexibility will be better positioned to adapt packaging and marketing strategies without compromising product integrity. The report integrates these dynamics into a broader assessment of how regulatory and retail trends will shape demand across applications.
Why This Research Matters for 2026 Decision-Making
Enterprise decisions made in 2026 will set the tone for competitive positioning through the end of the decade. Whether the objective is to secure reliable bulk supply, launch a new baobab-based formulation, evaluate private label opportunities, or assess regional expansion potential, organizations need a clear view of how market size, growth rate, competitive structure, and regulatory conditions interact. The Worldwide Baobab Powder Market report provides that view in a format built for action.
The study gives procurement leaders a framework for evaluating supplier options against volume requirements, certification expectations, and price trends. It supports product developers by mapping end-use demand patterns and identifying application areas where baobab powder’s functional and nutritional properties align with consumer priorities. It helps strategy and finance teams assess margin implications arising from raw material pricing, trade policy, and concentration dynamics. And it equips market access and compliance teams with the regulatory context needed to plan entries into the European Union and United States with greater confidence.
Equally important, the report is structured to support scenario planning. Because the market is influenced by certification evolution, trade policy renewal timelines, raw material price variability, and shifting retail labeling requirements, decision-makers benefit from an analysis that does more than report historical performance. It connects the dots between supply chain structure, regulatory momentum, and end-use adoption, allowing organizations to test assumptions and prepare for multiple plausible outcomes.
How to Use the Full Report
The preview above outlines the strategic architecture of the study, but the complete report delivers the detailed segmentation analysis, company profiling, regulatory guidance, and forward-looking scenario frameworks required for execution. Readers who need precise regional demand interpretations, application-level growth dynamics, sourcing cost considerations, and competitor benchmarking will find the full document designed to support those decisions directly.
The report is intended for use for cross-functional planning sessions, supplier evaluations, portfolio reviews, and market entry assessments. It combines quantitative framing with qualitative competitive insight, ensuring that executives can move from high-level market understanding to specific operational choices. For teams responsible for ingredient sourcing, product innovation, or international expansion, the analysis offers a structured basis for aligning commercial objectives with market realities.
Conclusion
The worldwide baobab powder market is expanding within a favorable but increasingly complex environment. Sustained revenue growth, improving regulatory access, active trade policy support, and a broad competitive landscape create meaningful opportunity, while pricing volatility, certification requirements, and evolving labeling expectations demand disciplined strategy. Our Worldwide Baobab Powder Market report translates these forces into a clear, decision-oriented intelligence platform for 2026 and the forecast period through 2032.
Organizations that engage with the full study will gain a more precise understanding of where demand is forming, how supply is structured, which players are shaping competitive norms, and what regulatory and trade conditions will influence cost and access. For decision-makers seeking to act with confidence in a fast-moving category, the report provides the depth, structure, and strategic context needed to convert market insight into executable advantage.
For detailed analysis of this topic, please visit the official page: Worldwide Baobab Powder Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com