

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global Cryogenic Ball Valve Market Worth $1.54B in 2025, Projected 6% CAGR Through 2032

Strategic Intelligence for a Low-Temperature Economy: Introducing the Worldwide Cryogenic Ball Valve Market Report
The global industrial landscape is undergoing a structural shift toward low-carbon energy systems, advanced industrial gases, and ultra-low temperature fluid handling. At the center of this transition sits a highly specialized component: the cryogenic ball valve. As LNG infrastructure expands, hydrogen pathways mature, and air separation capacity scales, manufacturers, EPC contractors, and procurement leaders face a complex environment defined by stringent material requirements, rigorous certification regimes, and a competitive field of international suppliers. Our newly released Worldwide Cryogenic Ball Valve Market research provides the analytical backbone required to navigate these dynamics with confidence.
This article previews the strategic architecture of the study and demonstrates why it is positioned as a decision-grade intelligence asset for 2026 planning cycles. Rather than offering surface-level summaries, the report connects macro market trajectories with operational realities, competitive positioning, and the technical standards that shape procurement, expansion, and partnership choices across the cryogenic valve ecosystem.
Why Cryogenic Ball Valves Have Become a Strategic Focus
Cryogenic ball valves are engineered to maintain sealing integrity, material ductility, and operational reliability at temperatures that would compromise conventional valve designs. Service conditions often extend down to -196°C and below, requiring careful selection of austenitic stainless steel grades such as 304L and 316L, validated trim configurations, and specialized packing technologies that mitigate fugitive emissions while preserving low-temperature performance.
The demand environment is being reshaped by several overlapping forces. LNG liquefaction, transportation, storage, and regasification continue to drive substantial valve procurement. At the same time, industrial gas production, air separation plants, petrochemical processing, and emerging hydrogen applications are broadening the addressable market. These sectors share a common requirement: flow control components that can withstand thermal shock, maintain leak-tight performance, and satisfy fire-safe and low-emission certification expectations.
The result is a market where engineering maturity, testing rigor, and compliance documentation are not optional enhancements but foundational competitive differentiators. This is precisely the environment in which a data-rich, technically grounded market study becomes indispensable.
Market Trajectory and the 2026–2032 Outlook
The report places current market behavior in the context of a multi-year growth arc. Drawing on historical data from 2020 through 2025 and extending forecast modeling through 2032, the study shows a market that has progressed from approximately 1,152.0 million USD in 2020 to an estimated 1,540.0 million USD in 2025, with continued expansion projected into the forecast window. The baseline year is 2025, and the analysis forecasts a compound annual growth rate of 6.0 percent through 2032.
This trajectory reflects more than simple volume growth. It captures a market in which revenue composition is being reshaped by shifting project pipelines, regional procurement patterns, and the increasing importance of specialized valve architectures for severe-service applications. The report translates these shifts into a structured view of where demand intensity is accumulating, how different valve configurations are being prioritized, and what this means for sourcing strategies, capacity planning, and competitive benchmarking.
Importantly, the study keeps its analytical lens broad enough to support executive-level direction while preserving enough granularity to inform product management, regional planning, and technical procurement teams. Readers can expect a balanced presentation of historical evolution, forward estimates, and the structural drivers that support those estimates.
What the Report Delivers: An Operational Blueprint
The study is built to be actionable. It moves beyond high-level market sizing and provides a detailed operational blueprint for organizations that need to align strategy with the realities of cryogenic valve procurement and production. The core content areas are organized to support multiple decision-making functions.
Market Structure and Segmentation Logic
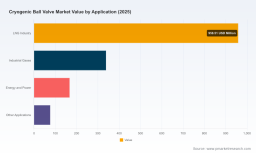
The report breaks the market down along dimensions that matter to buyers and suppliers alike. It examines type-based demand patterns across major valve architectures relevant to cryogenic service, explores application-level demand concentration across LNG, industrial gases, energy and power, and other end-use segments, and maps regional demand distributions to help readers understand where project activity and procurement volumes are most concentrated. Rather than presenting isolated figures, the analysis connects segmentation outcomes to underlying drivers such as project geography, processing requirements, and standards compliance needs.
Competitive Positioning and Company Profiles
A central strength of the study is its competitive mapping. The report profiles a focused set of companies that shape the global cryogenic ball valve landscape, drawing on product portfolios, certification capabilities, material expertise, and application emphasis. These profiles are designed to support benchmarking, partnership evaluation, and market-entry assessment.
The analysis includes companies such as Habonim, which emphasizes certified cryogenic performance for LNG, industrial gases, air separation, petrochemical, and aerospace applications, with a strong focus on safety, fugitive emission prevention, and regulatory compliance. Flowserve, through its Worcester Controls, Valbart, and McCANNA lineage, provides cryogenic ball valve designs for LNG liquefaction, transportation, regasification, and severe service, aligned with standards including BS 6364, API 6D, and fire-safe certifications. KITZ Corporation contributes stainless steel and carbon steel cryogenic ball valve capabilities for LNG, LPG, ethylene, and other low-temperature fluids down to -196°C, with an emphasis on precision engineering and material integrity.
The study also examines Neway Valve, which offers top-entry cryogenic floating and trunnion-mounted designs for LNG, LPG, hydrogen, and air separation service down to -196°C, featuring low-emission packing and lip seal technology in compliance with API 6D and BS 6364. Parker Bestobell, part of Parker Hannifin, supplies uni-directional cryogenic ball valves as shut-off solutions for low-temperature gas production, industrial gases, and LNG, with an emphasis on reliable storage and transportation performance. Powell Valves manufactures ASME Class 150 and 200 cryogenic valve variants, including ball valve options in multiple sizes, materials, and trim configurations. IMI PBM provides fire-safe cryogenic ball valves with live-loaded stem packings across a defined size range, rated for extreme temperature service and designed for leak-free performance.
Additional profiles extend the competitive view across Europe, Asia, and North America. OMB Valves produces cryogenic and low-temperature ball valves for LNG compression, carriers, receiving terminals, and storage, supported by testing capabilities down to -196°C. Sesto Valves manufactures premium Italian cryogenic ball valves tested per industry standards at -196°C with full compliance to international certifications. Bürkert delivers cryogenic valves and systems for measuring, controlling, and regulating cryogenic fluids and gases in industrial applications. Velan Inc. includes cryogenic ball valves within its broader flow control solutions for severe service and low-temperature environments. Herose GmbH specializes in cryogenic valves for industrial gases such as oxygen, nitrogen, and argon, as well as LNG applications, with service capability at very low temperatures.
Standards, Testing, and Compliance Architecture
Cryogenic valve procurement is heavily conditioned by standards and testing protocols. The report addresses the regulatory and technical frameworks that buyers and suppliers rely on, including common alignment with BS 6364 for low-temperature service, ISO 15848 for fugitive emissions, API 607 fire-safe requirements, and ASME B16.34. It also discusses cryogenic testing practices aligned with ISO 28921 and BS 6364, which are used to validate sealing integrity and material performance after exposure to ultra-low temperatures followed by ambient testing.
By consolidating this compliance landscape, the study helps readers evaluate supplier claims more systematically, anticipate qualification requirements, and understand why technical documentation increasingly functions as a commercial asset in bidding, sourcing, and partnership discussions.
Competitive Concentration and Strategic Implications
Market structure matters. The study notes a moderately fragmented competitive environment, with a CR3 of 18.5 percent and a CR5 of 27.8 percent. This level of concentration implies that while leading specialists and multinational players hold meaningful positions, a broader field of regional and application-focused manufacturers also competes effectively through engineering differentiation, cost positioning, and localized service capabilities.
Worldwide Cryogenic Market
For buyers, this structure underscores the importance of multi-supplier evaluation, qualification strategy, and total-cost considerations that go beyond unit price. For suppliers, it highlights the value of credible certification portfolios, application-specific demonstrations, and consistent low-temperature performance documentation. The report uses this competitive context to frame where scale advantages matter, where specialization creates defensible positions, and where customer expectations are shifting most rapidly.
Industry Dynamics Shaping Decisions in 2026
Several current industry developments are woven into the market narrative to illustrate how the landscape is evolving in real time. Recent trade show activity and product announcements reflect growing attention to ultra-low temperature valve solutions for LNG, industrial gases, and low-carbon applications.
In March 2026, Teji Valve Group showcased cryogenic ball valves at NEFTEGAZ 2026 in Moscow, highlighting an ultra-low temperature top-loading online repairable ball valve positioned for energy and low-carbon applications. In September 2025, StelsPromMash / SPE Ltd. presented SPM cryogenic ball valves in DN 15–200 sizes, rated down to -269°C, for LNG, nitrogen, oxygen, and other media at Cryogen-Expo. Industrial Gases 2025 in Moscow. The Valve World Expo 2026 is scheduled to feature cryogenic valve solutions for LNG and green hydrogen applications, signaling continued event-level focus on the sector. Separately, Magival Valves announced an expansion into cryogenic valve production and presented related innovations at IVS 2024.
These developments point to a market where visibility, technical demonstration, and application-specific messaging are increasingly central to commercial positioning. They also reinforce the importance of monitoring exhibition activity, regional project exposure, and expansion announcements as early indicators of shifting supply-side priorities.
Material Realities and Procurement Considerations
The report also integrates material-sector context because cryogenic valve economics cannot be separated from raw material behavior. Austenitic stainless steel grades such as 304L and 316L remain dominant for cryogenic ball valves due to their retained ductility and toughness at -196°C. Yet material pricing and regional cost structures create meaningful procurement variability.
For example, public sector analysis indicates that in Q3 2024, stainless steel prices averaged approximately 3,985 USD per MT in the United States, 3,670 USD per MT in Germany, and 1,615 USD per MT in China. These differences affect manufacturing cost bases, sourcing decisions, and competitive positioning across regions. The study incorporates this kind of material context to help readers interpret price dynamics, anticipate input-cost exposure, and assess where regional manufacturing advantages may influence supply strategies.
Macro Demand Drivers and Application Expansion
Beyond immediate project cycles, the report frames several macro trends that are influencing long-term demand. Expansion in LNG infrastructure continues to be a major catalyst. Industrial gas production and air separation plant activity add durable demand. At the same time, emerging hydrogen applications are introducing new requirements for reliable performance at temperatures down to -196°C or lower. These pathways share a common need for flow control components that can operate safely in extreme conditions while meeting emission and fire-safety expectations.
The study explores how these drivers interact with application segmentation and regional deployment patterns. Rather than treating demand as a single curve, the analysis differentiates the forces shaping LNG-led procurement, industrial gas consumption, energy and power requirements, and other end-use contexts. This multi-driver framework allows readers to stress-test assumptions and evaluate how changes in one sector could ripple through the broader cryogenic valve market.
How to Use This Study for 2026 Decision-Making
The report is designed to serve several decision functions simultaneously. For strategic planners, it provides a structured market narrative that links historical data, forecast direction, and the competitive environment. For product and engineering leaders, it offers a standards-and-application lens that clarifies where technical differentiation is most valued. For procurement and sourcing teams, it supports supplier evaluation by combining segmentation insight with company-level profiling and compliance context. For investors and market entrants, it presents a concise but rigorous view of concentration, expansion signals, and the material and regulatory factors that shape commercial viability.
In practice, the study can be used to compare regional opportunity emphasis, assess which valve types and applications are attracting the most demand attention, evaluate where certification and testing capabilities create competitive advantage, and identify how material cost variability may influence supplier selection. It also helps organizations align internal assumptions with market-level evidence, reducing reliance on fragmented or anecdotal intelligence.
Why This Report Differentiates Itself
The Worldwide Cryogenic Ball Valve Market study distinguishes itself through the integration of technical substance, competitive mapping, and forward-looking market structure. It does not treat cryogenic valves as a generic valve category. Instead, it reflects the reality that low-temperature service is a specialized market where material integrity, sealing reliability, testing protocols, and standards compliance directly affect commercial outcomes.
Worldwide Cryogenic Ball Valve Market
By combining company profiles, segmentation analysis, market concentration data, material-sector context, and recent trade and product developments, the report offers a comprehensive vantage point for organizations that need to make informed choices in 2026 and beyond. It is built to support both strategic positioning and operational follow-through.
Access the Full Intelligence
This article provides a structured preview of the study’s scope, analytical approach, and strategic relevance. To access the complete market sizing, segmentation detail, competitive profiles, standards framework, and forecast architecture, we invite you to explore the full Worldwide Cryogenic Ball Valve Market report. The complete version is designed to deliver the depth required for supplier evaluation, regional planning, product strategy, and investment decision-making in a market where precision matters at every temperature.
For detailed analysis of this topic, please visit the official page: Worldwide Cryogenic Ball Valve Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com