

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Report: Pressure-Sensitive Tapes Market Hits $78.45 Billion in 2025, Projects 5.12% CAGR Through 2032

Beyond Adhesion: Strategic Imperatives in the Global Pressure-Sensitive Tapes Market Through 2032
The pressure-sensitive tape (PSA) industry is no longer a commodity aftermarket or a passive manufacturing supplement. It has evolved into a strategic enabler of lightweighting, electrification, sustainable packaging, and precision assembly across multiple end-use sectors. As production volumes scale and performance thresholds tighten, executives must look beyond roll-per-roll comparisons and evaluate the structural economics, regulatory trajectories, and innovation pipelines that will define competitive positioning from 2026 through 2032. The newly updated Worldwide Pressure-Sensitive Tapes Market study translates these macro shifts into decision-grade intelligence for procurement, R&D, M&A, and market-entry teams operating at the intersection of materials science and industrial demand.
A Multiyear Trajectory Anchored in 2026 Decision-Making
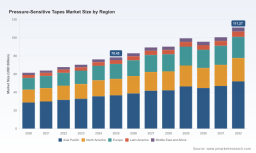
The global market for pressure-sensitive tapes has demonstrated steady expansion over the past half-decade, supported by industrial recovery, packaging modernization, and downstream demand from electronics and automotive value chains. Historical records from 2020 through 2025 show a consistent upward curve, with market revenue reaching an estimated USD 78.45 billion in the base year of 2025. The forecast window extends through 2032, charting a forward path that begins at approximately USD 82.9 billion in 2026 and progresses toward an anticipated USD 111.27 billion by the close of the projection period. This growth trajectory, equivalent to a compound annual growth rate of roughly 5.12 percent, is not merely a function of volume expansion. It reflects deepening application penetration, formulation sophistication, and the substitution of mechanical fasteners with engineered adhesive systems in demanding environments.
Worldwide Pressure-Sensitive Tapes Market
For strategy teams, the 2026 inflection is especially timely. Executives are now calibrating capacity plans, sourcing relationships, and product roadmaps against a backdrop of shifting raw material economics, tightening environmental specifications, and the emergence of multi-functional PSA architectures. The study treats 2026 not as an isolated baseline but as the operational launchpad for a seven-year strategic arc. It reconciles historical momentum with forward-looking demand signals, enabling readers to stress-test capacity assumptions, assess regional investment logic, and identify where performance differentiation will yield margin protection in a moderately concentrated market structure.
What the Study Delivers: From Macro Signals to Actionable Playbooks
The core objective of this research is to convert rich market structure into practical guidance. Rather than offering a single headline figure, the analysis decomposes the market along three strategic axes—geography, backing material, and application—while maintaining strict focus on decision relevance. Each dimension is examined through the lens of cost structure, switching dynamics, substitution risk, and value-chain positioning. The report is designed to answer the questions that line managers actually face when allocating capital or re-engineering supply plans:
- Where is demand most durable across the forecast period, and which applications are gaining share as a result of structural product changes rather than cyclical lifts?
- Which backing materials are absorbing investment and formulation attention, and how do substrate choices influence performance trade-offs, processing speed, and recyclability claims?
- How do regional demand profiles differ in terms of growth intensity, industrial composition, and regulatory exposure, and what does that imply for local production, sourcing, and go-to-market strategy?
- Which competitive behaviors are shaping price realization, differentiation, and customer retention, and where do market leaders concentrate their innovation and commercial resources?
- What procurement and formulation strategies can offset volatility in key inputs while satisfying the environmental and performance requirements now entering specifications?
Each analysis module pairs quantitative structure with qualitative interpretation, allowing readers to move from observed patterns to prioritized actions. The study also flags where end-use cycles diverge from raw material trends, helping procurement and finance teams separate noise from structural cost pressure. Importantly, the report intentionally withholds the deeper drill-down breakdowns that underpin these conclusions. The intent is deliberate: the executive summary and segment overview establish the logic and scale of opportunity, while the full ship-to-ship, application-level, and formulation-specific intelligence remains reserved for stakeholders who need to build models, negotiate contracts, or commit investment. Decision-makers who require precise volume splits, material-level pricing correlations, and granular regional overlays are directed to the complete dataset, where those figures can be integrated directly into internal planning systems.
Competitive Architecture: Scale Leaders, Specialty Specialists, and the New Innovation Frontier
The competitive landscape is defined by a mix of diversified industrial groups, adhesive-focused specialists, and regional manufacturing platforms. A handful of established players command a meaningful share of global volume, but the remainder of the market remains fragmented enough to reward targeted innovation and application-specific engineering. Among the organizations profiled in the study are globally recognized leaders and highly specialized contributors whose product architectures, end-use coverage, and development cadence shape the market’s direction.
3M Company continues to anchor its PSA portfolio around broad application coverage, spanning VHB bonding tapes, specialty industrial grades, packaging solutions, and medical-grade formats for electronics, automotive, construction, and healthcare. Avery Dennison Corporation leverages its Performance Tapes division to supply acrylic foam bonding tapes, double-sided constructions, and solutions for automotive, electronics, industrial assembly, and specialty applications. tesa SE concentrates on industrial, electronics, automotive, and consumer segments with double-sided foam tapes, masking grades, and high-performance bonding systems. Nitto Denko Corporation brings depth in pressure-sensitive tapes for electronics, automotive, industrial, and medical uses, with an emphasis on functional materials and high-tech applications. Intertape Polymer Group Inc. focuses on pressure-sensitive packaging tapes, industrial tapes, and specialty PSA products, placing notable weight on sustainable and recyclable packaging and industrial solutions. LINTEC Corporation addresses labeling, industrial, electronics, and healthcare requirements with advanced functional tapes and PSA materials. Berry Global Group, Inc. contributes engineered materials for packaging, industrial, and specialty applications through its broader film and tape portfolio. Lohmann GmbH & Co. KG develops high-performance PSA tapes and bonding solutions for industrial, electronics, automotive, and medical sectors. Scapa Group plc, under Mativ Holdings, supplies PSA tapes for healthcare, industrial, and specialty bonding, including custom die-cut services. Saint-Gobain S.A. offers performance PSA tapes and films through its Performance Plastics division for industrial, electronics, and high-temperature environments. Shurtape Technologies, LLC serves packaging, industrial, HVAC, and construction markets with a broad PSA range. Henkel AG & Co. KGaA provides PSA technologies and tapes for industrial assembly, packaging, and consumer applications via its Adhesive Technologies segment. American Biltrite Inc. rounds out the competitive map with tapes for automotive, graphics, HVAC, industrial, insulation, and surface protection uses.
This roster is not simply a list of incumbents. It reveals where specialization is being monetized and where consolidation logic may emerge. The study examines how these players compete on formulation performance, application engineering, and service models such as custom die-cutting and bonded assemblies, rather than on price alone. It also tracks recent developments that signal where the industry is placing its bets. In April 2026, multiple manufacturers including 3M, Henkel, and Sika accelerated bio-based and low-VOC PSA formulations alongside UV-curable PSA technologies for packaging, medical, and industrial applications. In May 2025, 3M Company introduced new high-performance acrylic PSA tapes designed for electric vehicle battery assembly and thermal management. That same year, 3M reported full-year 2024 sales with 2025 guidance pointing to low single-digit growth in industrial tapes and bonding systems. Separately, Intertape Polymer Group achieved a sustainability milestone in September 2025, reaching 75 percent of packaging products by revenue classified as recyclable, reusable, or compostable, thus meeting its 2025 target ahead of schedule. These events collectively illustrate a market in which product performance, regulatory compliance, and circularity claims are becoming inseparable from commercial positioning.
From Formulation Volatility to Application Resilience: What Is Moving the Market Now
The PSA market does not expand in a vacuum. Its near-term rhythm is shaped by raw material economics, regulatory pressure, and end-use system design. Recent data points highlight the tension between input cost variability and the need for consistent performance. The U.S. Producer Price Index for adhesive manufacturing primary products stood at approximately 379.21 in June 2025, reflecting a year-over-year increase of about 4.6 percent. At the same time, polypropylene film backing prices were reported around USD 1,525 per metric ton in the U.S. during the same period. These figures matter because substrate costs and adhesive formulations jointly determine total cost of ownership, line speed compatibility, and the economics of converting and downstream assembly.
Beyond finished inputs, the underlying chemistry is vulnerable to feedstock dynamics. Acrylate monomer prices, critical for water-based PSAs used in pressure-sensitive tapes, are influenced by propylene feedstock costs, with historical volatility exceeding 50 percent during prior shortage periods. Hydrocarbon tackifier resins for hot melt PSAs have also faced tight supply conditions, particularly in the U.S., adding further cost pressure to specific product families. At the same time, regulatory momentum is accelerating the adoption of low-VOC and bio-based PSA formulations, particularly in Europe and North America for packaging and medical applications. This creates a dual imperative: manage near-term input volatility while investing in formulations that satisfy environmental specifications without compromising adhesion, tack, or aging performance.
These dynamics are not isolated cost stories. They interact with application-level demand in ways that determine which product families gain traction and which face margin compression. Packaging continues to be a dominant demand driver, supported by e-commerce, labeling evolution, and sustainability-driven specification changes. Building and construction, electrical and electronics, automotive, and healthcare each bring distinct performance requirements and procurement cycles. The study analyzes how these demand pillars interact with backing material choices, adhesive chemistry, and regional regulatory regimes to shape growth intensity and competitive positioning. The precise magnitude of each application’s contribution and the exact regional revenue splits are presented in the full report, where they can be used to calibrate portfolio priorities, scenario planning, and sourcing strategies with precision.
Pressure Sensitive Adhesive Tapes Market
Where the Market Is Heading and Why the Full Intelligence Set Matters
Looking toward 2032, the pressure-sensitive tape industry is positioned for continued expansion, but the composition of that growth will matter more than the headline trajectory. Electrification, lightweight assembly, high-performance bonding in electronics, and recyclable packaging architectures are reshaping demand at the application frontier. At the same time, formulation innovation around bio-based chemistry, low-VOC systems, and UV-curable processes is redefining what “acceptable performance” means in regulated and sustainability-conscious markets. The question for executives is no longer whether the market will grow, but where value will accrue as performance standards rise and input economics remain sensitive to feedstock cycles and supply tightness.
This is precisely where the complete Worldwide Pressure-Sensitive Tapes Market study adds decision-grade value. It connects the macro trajectory from 2020 through 2032 with segment-level logic, competitive behavior, and the raw material and regulatory forces that influence margin and speed-to-market. The report’s structure enables readers to identify durable demand, assess substitution risk, evaluate regional opportunity, and map competitive differentiation without relying on generic industry narratives. To preserve analytical integrity while encouraging rigorous use, the executive overview establishes scale, direction, and strategic logic, while the deeper regional, application, and material-level breakdowns are reserved for the full dataset. That design ensures that the organizations relying on these figures for capacity planning, contract negotiation, product roadmap decisions, and market-entry analysis can work from the precise numbers rather than rounded proxies.
For leaders who need to move from directional confidence to executable strategy, the complete report provides the structured intelligence required to turn market momentum into disciplined advantage. The full segmentation details, regional overlays, application contrasts, competitive benchmarks, and formulation-related cost context are available in the complete study, where they can be integrated directly into internal models and planning cycles. In a market where performance, compliance, and cost must be managed together, access to the underlying data architecture is not a luxury—it is the foundation of credible decision-making.
For detailed analysis of this topic, please visit the official page: Worldwide Pressure-Sensitive Tapes Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com