

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global Arc Suppression Reactors Market to Hit $1.5B by 2032 at 5.24% CAGR

Strategic Horizons: The Worldwide Arc Suppression Reactors Market Through 2032
The global landscape for arc suppression reactors is undergoing a measured but decisive transformation. As distribution networks age, renewable integration accelerates, and safety standards tighten, utilities and industrial operators are revisiting the fundamentals of neutral grounding. Our latest Worldwide Arc Suppression Reactors Market research translates this complex shift into a structured, decision-ready intelligence framework. Built on a rigorous historical reconstruction and a forward-looking forecast horizon, the study is designed to help engineering leaders, procurement directors, and corporate strategists align capital allocation with the technical and regulatory realities of the next decade.
The market has already crossed a meaningful threshold. From a baseline of 845.5 million USD in 2020, revenue expanded steadily to 1050.0 million USD by 2025, reflecting sustained demand across transmission, distribution, and industrial power environments. The trajectory continues upward through the forecast period, reaching an estimated 1075.73 million USD in 2026 and climbing toward 1501.27 million USD by 2032. This expansion is anchored by a compound annual growth rate of 5.24 percent, a pace that signals durable structural demand rather than a temporary procurement cycle. For organizations planning multi-year equipment roadmaps, this cadence offers a reliable baseline for budgeting, capacity planning, and supplier engagement.
What sets this research apart is its emphasis on actionable segmentation and competitive clarity. Rather than presenting a single aggregate figure, the analysis decomposes the market into type, application, and regional dimensions, allowing decision makers to identify where growth is genuinely concentrated and where saturation or substitution risk may be emerging. The report also maps the competitive field with precision, profiling the manufacturers that are shaping product evolution, certification practices, and intelligent control integration. The result is a reference document that can be used directly in vendor qualification, technology selection, and regional expansion planning.
Market Trajectory and the Case for Early Positioning
The growth path from 2026 through 2032 is not uniform, and that unevenness is precisely where strategic advantage is created. Early forecast years show a steady climb from 1075.73 million USD in 2026 to 1124.86 million USD in 2027, followed by a step-up to 1191.88 million USD in 2028. The later years accelerate further, with the market reaching 1320.11 million USD in 2029, 1403.29 million USD in 2030, and continuing toward 1447.89 million USD in 2031 before settling at 1501.27 million USD in 2032. This pattern suggests that the most significant demand uplift will arrive as legacy substations undergo modernization and as newer grid architectures adopt resonant grounding as a default safety and reliability measure.
For executives, the implication is clear: waiting until a procurement need becomes urgent often means entering a more crowded, less flexible negotiating environment. Companies that map their required specifications against the evolving product landscape now can secure better technical fit, smoother integration with existing protection schemes, and more predictable lead times. The forecast also provides a useful sanity check for internal projections. If an organization's planned growth assumptions deviate sharply from the market's documented cadence, the discrepancy is worth investigating before it becomes a budget or supply-chain surprise.
The research further supports scenario planning by linking volume movement to the underlying drivers that govern adoption. These include the phase-out of aging equipment, the expansion of medium-voltage distribution in dense urban and industrial corridors, and the technical requirements associated with connecting distributed generation to resilient network topologies. By treating these drivers as interlocking forces rather than isolated trends, the study helps teams build investment cases that hold up under regulatory review and operational stress testing.
Segment Architecture and Where Growth Concentrates
Understanding the market's internal structure is essential for targeting the right opportunities. The report divides the landscape along three practical axes: product type, application setting, and geographic region. Each axis reveals a different part of the story, and together they give leaders a multi-dimensional view of where value is being created and where competition is intensifying.
Product Type Dynamics
The type segmentation captures the spread between conventional fixed designs and more adaptable tuning architectures. Automatic plunger-type reactors represent the largest share of market activity, reflecting their wide applicability in networks that require responsive compensation and streamlined maintenance. Fixed gap reactors continue to serve specialized installations where simplicity, proven performance, and cost predictability remain priorities. Step-adjustable reactors occupy a strategically important niche for operators that need flexibility without adopting fully automatic systems. This triad of options means that specification decisions should be driven by fault-current behavior, network capacitance variability, and the operator's tolerance for manual intervention versus automated tuning.
Application Contexts
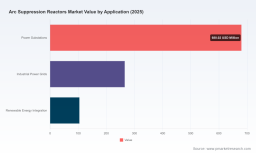
Application segmentation shows how arc suppression reactors are deployed across the power ecosystem. Power substations form the dominant usage environment, where resonant grounding is closely tied to protection coordination and continuous service during single-phase earth faults. Industrial power grids represent a substantial second pillar, driven by facilities that cannot tolerate unplanned downtime and that require grounding solutions matched to their load profiles and fault levels. Renewable energy integration is an increasingly visible segment, as connecting wind, solar, and storage assets to medium- and high-voltage networks places new demands on fault management and voltage stability. The interplay among these application areas helps explain why demand is not simply a function of grid size, but of grid function, reliability expectations, and the pace of generation mix change.
Regional Footprints
Regional segmentation provides a compass for where capacity, supply chains, and project pipelines are most active. The analysis highlights a broad geographic distribution, with significant activity across Asia Pacific, Europe, North America, the Middle East and Africa, and Latin America. Each region carries its own mix of drivers: legacy network renewal, expansion of distribution infrastructure, industrial electrification, and the modernization of protection philosophy. Importantly, regional dynamics are not interchangeable. A strategy that works in one market may underperform in another if it fails to account for local standards, procurement habits, and the prevalence of specific grounding practices. The report's regional breakdown helps teams avoid one-size-fits-all assumptions and instead calibrate entry timing, partner selection, and specification emphasis to the realities of each market.
Competitive Landscape: Capability, Certification, and Intelligent Control
The competitive environment is defined by a mix of established specialists and regionally strong manufacturers, each pursuing distinct value propositions. The study profiles the companies that matter most to procurement and engineering teams, focusing on product architecture, compliance posture, insulation technology, and the growing importance of intelligent monitoring and remote diagnostics.
Specialist Leaders and Technical Differentiation
Trench Group remains a reference point for resonant earthing solutions in distribution networks up to 36 kV, with offerings that span Eco Fluid and conventional fluid arc suppression coils, stepless adjustment, and IEC 60076-6 compliance. Its emphasis on sustainable ester-based insulation under the Regenera label, along with air-core and oil-immersed variants, illustrates how product portfolios are being shaped by both performance and environmental considerations. Swedish Neutral AB continues to advance the concept of combining arc suppression coils with residual current compensation through ground fault neutralizer systems, targeting near-zero fault current reduction in medium- and high-voltage networks. Its automatic tuning devices reflect a broader industry shift toward continuous monitoring and dynamic inductance adjustment. SUNTEN reinforces the practical side of this evolution with automatic tuning arc suppression coils designed for 35 kV and below substations, offering capacities that range from 10 to 4000 kvar, low-noise operation, and insulation classes suited to demanding distribution environments.
Regional Manufacturing Strength
A strong contingent of manufacturers in China and India adds scale, customization, and cost-competitive options to the market. Shrihans Electricals produces oil-immersed iron-core arc suppression reactors as single-phase variable inductance units for resonant neutral grounding. Zhejiang Nengrong Electric Power Equipment Co., Ltd. supplies reactors with high-precision compensation, stability, and intelligent control for urban, rural, and industrial power systems, and has been emphasized in recent supplier rankings for its intelligent control focus. Xi'an XD Power Capacitor Co., Ltd. provides customized design options using high-quality materials and advanced manufacturing methods. Baoding Tianwei Baobian Electric Co., Ltd. leverages transformer technology to deliver low-loss, high-insulation designs with effective heat dissipation. Shandong Taikai Electric Group Co., Ltd. integrates intelligent monitoring, remote control, and fault diagnosis functions. Henan Pinggao Electric Co., Ltd. focuses on high-voltage resistant designs with safety features and modular construction. Changzhou Huadian Electric Co., Ltd. offers compact, high-efficiency coil reactors for space-limited substations. Farady Electric Co., Ltd. supplies Petersen coils and arc suppression coils for 11-35 kV, including ground-fault neutralizers. These companies collectively broaden the choices available to operators and increase the importance of specification-driven evaluation rather than brand-only selection.
European and Specialized Players
Beyond the large manufacturing centers, several European and specialty firms contribute important design depth. SEA Trasformatori produces Petersen coils regulated by steps or stepless, often combined with earthing transformers and shunt reactors. Ardan Transformers manufactures Peterson coils compliant with IEC 60076-6, with designs adapted to specific project requirements. Together, these players reinforce the market's technical diversity and remind buyers that compliance, mechanical adaptation, and integration with surrounding equipment can be just as decisive as base inductance rating.
Industry Dynamics: Standards, Materials, and Automatic Tuning
Three dynamics are reshaping how arc suppression reactors are specified and evaluated. First, the IEC 60076-6 standard continues to anchor product expectations, covering the ability to withstand rated short-time neutral current and temperature rise requirements. Compliance is no longer a background checkbox; it is a fundamental filter in procurement and engineering review. Second, the shift toward eco-friendly ester-based insulating fluids is gaining relevance as operators seek higher flash points, improved fire safety, and reduced environmental impact compared with conventional mineral oil. This transition affects not only safety cases but also maintenance planning, disposal considerations, and long-term operational risk.
Third, automatic tuning is becoming central to the value proposition of modern reactors. By continuously monitoring network conditions and adjusting inductance to match capacitance changes, automatic tuning devices help maintain minimal residual fault current even as network configuration evolves. This capability is especially important in networks where distributed generation, load switching, and sectionalizing changes alter capacitive current profiles over time. Combined with intelligent monitoring and remote diagnostics, automatic tuning supports a shift from reactive maintenance toward condition-aware operation. The report examines how these capabilities are being incorporated into product designs and what they mean for protection coordination, commissioning, and lifecycle cost.
Worldwide Arc Suppression Reactors Market
Recent developments reinforce the direction of travel. In early 2025, Zhejiang Nengrong Electric Power Equipment Co., Ltd. was featured as a top supplier of arc suppression reactors in China, with emphasis on intelligent control systems. Later in the year, A. Eberle received special recognition in the TOP 100 Awards 2025 for innovation in energy future, related to arc suppression coil regulators. Trench Group also maintained active sustainability certification for its arc suppression coils, reflecting ongoing attention to environmental and operational performance. These events are not isolated headlines; they are indicators of where product development, supplier reputation, and customer expectations are converging.
Concentration, Procurement, and the Rhythm of Decision Making
The market's competitive structure matters because it influences pricing behavior, availability, and the negotiating leverage of buyers. Concentration metrics show that the top three firms account for approximately 38.45 percent of market revenue, while the top five reach roughly 52.18 percent. This level of concentration indicates a market where scale, certification, and product breadth confer real advantages, but it also leaves meaningful room for specialized players and regional manufacturers to compete on fit, customization, and service. For procurement teams, the practical takeaway is that supplier selection should balance breadth and depth: large portfolios can simplify multi-project standardization, while focused manufacturers can deliver sharper alignment with particular voltage classes, substation layouts, or control requirements.
From a decision-making standpoint, the forecast period creates a clear rhythm for action. The 2026-2032 window is long enough to justify technology selection and supplier partnership decisions, yet near enough that assumptions must be tested against current standards, available intelligent features, and realistic project pipelines. Organizations that use this research to align internal requirements with external market structure can reduce specification rework, improve tender quality, and avoid late-stage surprises when lead times tighten or certification expectations change.
Why This Research Matters for 2026 Strategy
The strategic value of this study lies in its ability to convert a broad market narrative into deployable intelligence. The headline figures establish context, but the real power is in the segmentation logic, the competitive profiles, and the mapping of technical trends to procurement consequences. Leaders can use the report to answer questions that directly affect 2026 planning: which product types are most relevant to a given network profile, which application environments will drive demand in the near term, which regions offer the strongest opportunities for expansion or partnership, and which suppliers combine compliance, innovation, and practical deployment experience.
Equally important, the research is structured to support comparison without oversimplifying. It allows engineering and commercial teams to evaluate trade-offs among automatic, fixed, and step-adjustable designs; to weigh the implications of ester-based insulation and intelligent monitoring; and to assess whether a regional sourcing strategy should be broadened or deepened. By presenting these choices within a coherent market framework, the study reduces the risk of decisions made on incomplete technical or competitive information.
For organizations that need to move quickly but carefully, the report serves as both a reference and a planning tool. It helps quantify the scale of the opportunity, clarifies where differentiation is possible, and identifies the points in the value chain where informed selection creates the greatest downstream benefit. In a market where reliability, safety, and compliance are non-negotiable, that clarity is not a luxury; it is a prerequisite for sound capital deployment.
Looking Ahead: From Market Intelligence to Execution
The next phase of market development will reward organizations that connect strategic insight to operational execution. That means aligning specification practices with the realities of automatic tuning and condition monitoring, evaluating supplier claims against the standards and certification signals that matter, and selecting regional pathways that reflect local network needs rather than generic growth narratives. It also means using the forecast not as a fixed prediction, but as a structured baseline against which internal assumptions can be challenged and refined.
The full research report expands each of these themes into detailed analysis, company profiles, segmentation insight, and decision-oriented commentary. It is designed for teams that need more than a market summary: teams that want to understand how the worldwide arc suppression reactors market is structured today, how it is likely to evolve through 2032, and how to position their organizations to act with confidence in 2026 and beyond. For readers ready to move from overview to execution, the complete study provides the deeper intelligence required to make those choices with precision.
Worldwide Anode Saturable Reactor Market
For detailed analysis of this topic, please visit the official page: Worldwide Arc Suppression Reactors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com