

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Category: market research
PW Consulting: Tendinitis Market Hits $218.65M in 2025, Forecast 4.71% CAGR Through 2032
By pmarketresearch, 2026-09-17
Strategic Intelligence for the Next Wave: Inside the Worldwide Tendinitis Treatment Market
The global landscape for tendinitis treatment is undergoing a structural transformation. Driven by an aging athletic population, rising prevalence of overuse injuries, and rapid advancements in minimally invasive procedural technologies, the market has evolved from a commoditized pain management segment into a sophisticated ecosystem of biologics, robotics, and specialized rehabilitation protocols. For healthcare providers, medical device manufacturers, and investment stakeholders, understanding the trajectory of this market is no longer optional—it is a critical component of capital allocation and product development strategy.
PW Consulting's latest comprehensive study, the Worldwide Tendinitis Treatment Market report, delivers a granular analysis of this evolving sector. Spanning historical performance from 2020 through 2025 and offering a robust forecast horizon from 2026 to 2032, this research is designed to equip decision-makers with the foresight required to navigate upcoming regulatory shifts, reimbursement changes, and competitive displacements. This article serves as a strategic preview of the report's core findings, illustrating why this intelligence is essential for 2026 enterprise planning.
Macro Trends and Growth Trajectory
The tendinitis treatment sector has demonstrated remarkable resilience and consistent expansion over the past half-decade. Historical data indicates that the global market generated revenue of approximately 172,450 million USD in 2020, climbing steadily to reach 207,737 million USD by 2024. This upward momentum continued into the base year of 2025, with the market valuation establishing itself at 218,650 million USD.
Looking forward, the growth trajectory remains positive, albeit maturing. The market is projected to breach the 219,000 million USD threshold in 2026, signaling a stabilization phase before the next acceleration cycle. By the end of the forecast period in 2032, the worldwide tendinitis treatment market is expected to surpass 301,764 million USD. This expansion is underpinned by a Compound Annual Growth Rate (CAGR) of 4.71 percent throughout the 2026 to 2032 forecast window.
For strategic planners, this CAGR suggests a market that is growing faster than general healthcare inflation but requires precise segmentation to capture value. The jump from roughly 241,717 million USD in 2027 to over 296,372 million USD by 2031 highlights a significant inflection point likely driven by the adoption of advanced biologic implants and robotic-assisted surgical suites. Organizations that position their portfolios ahead of this 2027 to 2031 acceleration window will be best placed to secure market share.
Competitive Landscape and Key Players
The market structure is characterized by moderate concentration, with the top three players holding a combined share of 18.45 percent and the top five accounting for 26.82 percent. This fragmentation indicates ample room for niche innovators and specialized boutique manufacturers to thrive alongside industry giants. However, the competitive dynamics are shifting as large conglomerates acquire specialized technologies to bolster their orthopedic portfolios.
Leading the charge is Smith & Nephew, headquartered in London, UK. Their strategy focuses heavily on biologic augmentation and minimally invasive tenotomy. Notably, in October 2024, Smith & Nephew received 510(k) clearance for the next-generation REGENETEN Bioinductive Implant, featuring an enhanced resorption profile designed to accelerate tendon healing. This regulatory milestone underscores their commitment to dominating the rotator cuff and general tendinopathy segments.
In the United States, Arthrex, based in Naples, Florida, continues to strengthen its foothold in arthroscopic interventions. Their September 2024 product launch of the FiberRing XS suture specifically targets small tendon repairs in upper extremity procedures, addressing a high-volume clinical need in tennis elbow and rotator cuff pathologies. Similarly, Stryker, headquartered in Kalamazoo, Michigan, is leveraging robotics to precision-engineer tendon repairs. Their March 2024 expansion of Mako robotic-arm assisted systems through partnerships with ambulatory surgery centers represents a strategic move to capture outpatient procedure volume, which is growing faster than inpatient settings.
Elbow Stiffness Treatment Market
The competitive field also includes major contributions from DePuy Synthes (Johnson & Johnson) and Zimmer Biomet, both of which are integrating knotless anchor systems and surgical mesh solutions like Regeneten into their standard offerings. CONMED, based in Largo, Florida, maintains a strong position in suture management with their Y-Knot RC all-suture anchors. Furthermore, the acquisition and integration of Tenex Health by Stryker highlights a pivotal industry trend: the convergence of ultrasonic tenotomy technologies with broader orthopedic distribution networks. Tenex Health's June 2024 clinical study results, showing 89 percent pain reduction in chronic tendinitis patients, provide the clinical evidence necessary to justify premium pricing and insurance coverage expansions.
Treatment Modalities and Clinical Segmentation
The market is diversified across several treatment types, each facing distinct adoption curves and reimbursement hurdles. Medication remains a foundational pillar of the market, capturing the largest share of revenue due to the high volume of initial presentations for pain management. However, the growth rate in this segment is stabilizing as clinicians and patients increasingly seek curative rather than palliative solutions.
Physical therapy constitutes a significant portion of the market value, driven by the essential role of rehabilitation in preventing recurrence. Yet, the most dynamic growth is observed in procedural interventions. Shockwave therapy has gained traction as a non-invasive middle ground, while surgical interventions remain critical for severe cases. Within the surgical segment, the shift is unequivocally toward minimally invasive techniques. Knotless anchors, bioabsorbable sutures, and robotic assistance are redefining the standard of care.
Condition-specific analysis reveals that Rotator Cuff Tendinitis and Achilles Tendinitis represent substantial portions of the clinical volume. Patellar Tendinitis and Tennis Elbow also contribute significantly, particularly in sports medicine and occupational health contexts. Each condition presents unique biomechanical challenges that require tailored implant solutions, from foot and ankle specific systems provided by Wright Medical to upper extremity sutures from Arthrex. Understanding the interplay between these condition-specific demands and the available technological solutions is vital for product managers and clinical procurement officers.
Regulatory and Economic Dynamics
Navigating the tendinitis treatment market requires a deep understanding of the regulatory and economic environment. In the United States, the FDA classifies tendon repair scaffolds as Class II devices. This classification requires 510(k) premarket notification under product code MWO, a process that shapes the timeline for new product introductions. Companies must maintain rigorous documentation to demonstrate substantial equivalence to existing predicates.
Across the Atlantic, the European Union's Medical Device Regulation (EU MDR) imposes stricter requirements. Notified Body certification is mandatory for tendon implants under Rule 8, with clinical evaluations needing to adhere to MEDDEV 2.7/1 Rev 4 guidelines. These regulatory frameworks increase the barrier to entry for new competitors but provide a moat for established players who have already secured compliance.
Worldwide Tendinitis Treatment Market
On the economic front, reimbursement policies play a pivotal role in procedure adoption. Under the 2025 Medicare Physician Fee Schedule, CPT code 28285 for tendon repair procedures reimburses an average of 1,200 USD. This reimbursement level influences the viability of outpatient surgeries versus inpatient stays. Additionally, material costs remain a key variable for hospital procurement teams. Medical-grade PLLA bioabsorbable suture anchors typically cost between 150 and 250 USD per unit in bulk procurement for tendinitis kits. Margins are tightly linked to supply chain efficiency and volume contracting.
It is also important to note specific usage limitations. For instance, the TENEX tenotomy system is cleared for research use only in investigational protocols outside its labeled indications. Stakeholders must ensure compliance with Instructions for Use (IFU) to avoid liability risks during off-label adoption campaigns.
Strategic Value for 2026 Decision Making
Why does this detailed intelligence matter for 2026 planning? The answer lies in the convergence of clinical evidence, regulatory approval, and market access. The 4.71 percent CAGR is not uniform across all segments. Growth will be disproportionately captured by companies that can demonstrate superior clinical outcomes, such as the 89 percent pain reduction data published by Tenex Health, and those that can navigate the reimbursement landscape effectively.
For device manufacturers, the report provides actionable insights into where to direct R&D spend. The data suggests that bioinductive implants and robotic-assisted precision tools are the high-growth vectors, while traditional suture anchors may face margin pressure due to commoditization and bulk pricing dynamics. For healthcare providers, understanding the regional demand shifts and the availability of ambulatory surgery center partnerships is crucial for infrastructure investment.
Furthermore, the moderate market concentration indicates that consolidation is possible. Strategic acquirors looking to enter or expand in this space should monitor the pipeline of startups focusing on ultrasonic tenotomy and biologic scaffolds. Investors need to assess which companies have cleared the regulatory hurdles of 510(k) or EU MDR certification, as these milestones are primary drivers of valuation multiples in this sector.
Conclusion and Accessing Full Intelligence
The Worldwide Tendinitis Treatment Market is at a pivotal juncture. The historical stability from 2020 to 2025 has laid a strong foundation, but the forecast period from 2026 to 2032 promises dynamic changes driven by technology and regulation. With revenues projected to exceed 300 billion USD by the end of the decade, the opportunity is vast, but so is the complexity.
This article has outlined the macro trends, competitive maneuvers, and regulatory constraints shaping the industry. However, successful execution requires granular data that goes beyond high-level summaries. Detailed segmentation breakdowns, specific regional revenue forecasts, granular competitor profiling, and proprietary supply chain analysis are essential for crafting a winning strategy.
To access the full depth of this analysis, including the complete segmentation splits, detailed company profiles, and the comprehensive forecast model, we invite you to explore the full Worldwide Tendinitis Treatment Market research report. Equip your organization with the precise data needed to lead in 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Worldwide Tendinitis Treatment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Posaconazole Market to Reach $461.59M by 2032, CAGR 5.42%
By pmarketresearch, 2026-09-17
Worldwide Pharmaceutical Grade Posaconazole Market: Strategic Intelligence for 2026 and Beyond
Executive Overview
The global pharmaceutical landscape is witnessing a significant shift in the antifungal sector, driven by the increasing prevalence of invasive fungal infections and the critical need for reliable prophylaxis in immunocompromised populations. As we move into 2026, the Worldwide Pharmaceutical Grade Posaconazole Market stands at a pivotal juncture. This market, encompassing the active pharmaceutical ingredient (API) and finished dosage formulations used in clinical settings, represents a vital component of modern infectious disease management. For stakeholders ranging from API manufacturers to global distributors and healthcare providers, understanding the trajectory of this market is not merely an academic exercise but a strategic imperative.
Our latest comprehensive market research provides a granular look at this sector, offering a bridge between historical performance and future projections. The analysis covers the period from 2020 through 2032, establishing a robust framework for forecasting growth, assessing competitive intensity, and identifying regulatory hurdles. For decision-makers operating in 2026, this intelligence serves as a foundational tool for capital allocation, supply chain optimization, and product portfolio strategy. The transition from branded dominance to a more complex generic ecosystem creates both opportunities for market penetration and challenges regarding margin preservation.
Market Size and Growth Trajectory
The financial magnitude of the pharmaceutical grade posaconazole market underscores its importance within the broader pharmaceutical supply chain. Based on historical data and forecasting models, the market has demonstrated consistent resilience and growth. In 2020, the market valuation stood at approximately 245.15 million USD. Over the subsequent five years, the sector experienced a steady upward trend, reaching an estimated 319.0 million USD by the base year of 2025. This historical performance lays the groundwork for the forecast period extending through 2032.
Looking ahead, the growth momentum is expected to accelerate moderately. Projections indicate that the market size will expand from 337.54 million USD in 2026 to 461.59 million USD by 2032. This expansion is supported by a Compound Annual Growth Rate (CAGR) of 5.42 percent throughout the forecast period. Such a growth rate suggests a mature yet expanding market, where volume increases are balanced by pricing dynamics and regulatory compliance costs. For strategic planners, this trajectory implies a steady revenue stream potential, provided that operational efficiencies are maintained and market access barriers are navigated effectively.
It is crucial to note that these figures represent the total market value in USD millions. While high-level growth is evident, the real strategic value lies in understanding the drivers behind these numbers, which are detailed extensively in the full report. The interplay between new product approvals, patent expiries, and regional healthcare spending dictates the velocity of this growth, making real-time intelligence essential for capturing market share.
Segmentation Dynamics: Forms and Applications
A deep dive into the product segmentation reveals distinct preferences and utilization patterns across different formulation types. The market is primarily divided into crystalline and amorphous forms of the pharmaceutical grade ingredient. Data indicates that the crystalline form holds a dominant position within the supply chain, reflecting its stability and suitability for a wide range of manufacturing processes. The amorphous form, while smaller in volume, serves specific niche requirements where solubility profiles are critical for bioavailability.
In terms of drug delivery applications, the market is segmented into delayed-release tablets, oral suspension, and intravenous injection. Each segment caters to different clinical scenarios and patient compliance profiles. Delayed-release tablets are a cornerstone of long-term prophylaxis, offering convenience and consistent dosing. Oral suspension provides flexibility for patients who cannot swallow tablets or require dose adjustments, often used in pediatric or geriatric care. Intravenous injection remains critical for hospital settings where rapid onset of action is required for severe systemic infections.
The distribution of value across these segments highlights the multifaceted nature of posaconazole usage. Manufacturers must align their production capabilities with the specific demand signals of each application type. For instance, the production of intravenous formulations requires stringent aseptic processing and stability controls, whereas tablet manufacturing focuses on high-volume scalability. Understanding the revenue contribution and volume splits of these segments is key to optimizing production lines and inventory management. The full report provides detailed segmentation splits that allow companies to benchmark their portfolio mix against global demand patterns.
Regional Landscape and Demand Distribution
Geographically, the market exhibits a heterogeneous distribution of demand and supply capabilities. North America continues to represent a significant portion of the global market, driven by high healthcare expenditure, established reimbursement frameworks, and the presence of key regulatory bodies like the FDA. Europe follows as a major hub, with stringent quality standards and a robust generic market influencing supply dynamics. The Asia Pacific region is emerging as a critical engine for both API manufacturing and growing domestic consumption, reflecting the expansion of healthcare infrastructure in developing nations.
Latin America and the Middle East and Africa constitute smaller but strategically important markets. In these regions, the focus often shifts to cost-effective access and the availability of essential antifungal medications. Supply chain resilience is particularly vital in these areas, where logistical challenges can impact the availability of temperature-sensitive formulations. For global players, regional strategy is not one-size-fits-all. It requires tailored approaches to regulatory filing, distribution partnerships, and pricing strategies that align with local economic conditions.
The concentration of market activity across these regions also influences competitive behavior. Companies with a strong foothold in North America and Europe often leverage these markets to fund expansion into high-growth emerging regions. Conversely, API manufacturers based in Asia are increasingly looking to secure regulatory approvals in Western markets to diversify their revenue streams. A nuanced understanding of regional market values and growth potentials is essential for mapping out expansion pathways and mitigating geographic concentration risks.
Competitive Landscape and Key Players
The competitive environment in the pharmaceutical grade posaconazole market is characterized by a mix of originator companies, large generic manufacturers, and specialized API producers. The market concentration is notably high, with the top three companies accounting for a significant share of the market revenue, and the top five firms controlling over eighty percent of the total value. This concentration suggests that scale, regulatory expertise, and established supply relationships are critical barriers to entry.
Merck & Co. (MSD) remains a central figure as the originator of the Noxafil brand. They supply the pharmaceutical grade posaconazole API and a comprehensive range of formulations, including delayed-release tablets, oral suspension, and intravenous injection. Their presence sets the benchmark for quality and clinical efficacy, influencing prescribing habits and reimbursement policies globally. However, the landscape is increasingly populated by generic competitors who are capitalizing on patent expiries and FDA approvals to offer therapeutic equivalents.
A diverse group of companies is active in the API and formulation space, particularly in India and China. Dr. Reddy's Laboratories, Hikma Pharmaceuticals, Metrochem API Private Limited, Neuland Laboratories, Biocon Pharma, MSN Labs, Cohance Lifesciences, and Bio-Synth represent key players with varying focuses on API production, generic formulations, and regulatory compliance. Hikma Pharmaceuticals, for instance, has made strategic moves such as the launch of posaconazole oral suspension in the US market. MSN Labs and Qilu Pharm Hainan have achieved recent FDA approvals for delayed-release tablets, signaling an intensifying competition in the generic tablet segment.
On the API supply side, Chinese manufacturers such as Apino Pharma Co., Ltd., Sinoway Industrial Co., Ltd., Senova Technology Co., Ltd., Changzhou Comwin Fine Chemicals Co., Ltd., BrightGene Bio-Medical Technology Co., Ltd., and Anhui Menovo are expanding their capabilities. These companies are pursuing regulatory documentation like USDMF and CDMF to access global markets. LGM Pharma serves as a global supplier and distributor, connecting GMP manufacturers with downstream demand. The presence of numerous suppliers creates a complex supply network where quality assurance and regulatory standing are the primary differentiators.
For companies operating in this space, staying abreast of recent developments is crucial. Recent FDA approvals for delayed-release tablets by companies like MSN Labs and Qilu Pharm Hainan indicate a trend toward broadened generic access. Simultaneously, WHO-GMP certifications and regulatory documentation updates from players like Bio-Synth demonstrate the ongoing emphasis on compliance for regulated markets. These events reshape the competitive hierarchy and open new avenues for market entry.
Regulatory and Manufacturing Dynamics
The regulatory framework governing pharmaceutical grade posaconazole is stringent and continuously evolving. Posaconazole remains subject to active patents on certain formulations, including specific alkylated cyclodextrin compositions expiring in 2033 and IV solution stabilization patents expiring in 2031. These patent protections create a layered market where generic entry is possible for some formulations but restricted for others, influencing strategic planning for lifecycle management.
Reimbursement dynamics are also shifting. Generic formulations, including delayed-release tablets and oral suspension, have received AB ratings for therapeutic equivalence to the reference listed drug. This rating enables substitution within reimbursement systems, driving volume toward cost-effective options and pressuring brand margins. For manufacturers, securing these ratings is a critical milestone that validates product quality and ensures market access in cost-conscious healthcare systems.
Manufacturing complexity adds another layer to the strategic landscape. Pharmaceutical grade posaconazole production involves complex multi-step synthesis requiring high-purity intermediates. This process contributes to elevated manufacturing costs under stringent GMP and FDA/EMA quality controls. API manufacturers must maintain USDMF, CEP, or equivalent filings to participate in global supply chains. With over 30 USDMFs listed for posaconazole and active GMP compliance required, the barrier to achieving and maintaining regulatory standing is significant. Companies must invest in robust quality management systems and documentation to sustain their market position.
These dynamics create a environment where technical capability and regulatory agility are as valuable as commercial reach. Suppliers that can navigate the patent landscape, maintain high purity standards, and secure timely approvals will be best positioned to capture value. The full report delves deeper into these regulatory nuances, providing actionable insights for compliance teams and strategic planners.
Strategic Value for 2026 Decision-Making
The insights derived from this market research are designed to empower strategic decisions in 2026 and beyond. For investors and executives, the growth trajectory offers a benchmark for evaluating market potential and risk. The forecasted expansion to nearly 462 million USD by 2032 suggests a sustained demand environment, but realizing this potential requires navigating competitive pressures and regulatory complexities.
Worldwide Pharmaceutical Grade Posaconazole Market
For manufacturers and suppliers, the segmentation data provides a roadmap for product development and capacity planning. Understanding the relative importance of crystalline versus amorphous forms, and the demand for tablets, suspensions, and injections, allows for optimized resource allocation. Companies can identify gaps in their portfolios and align production capabilities with high-growth segments.
Competitive intelligence is another critical output. By analyzing the positioning of key players, recent approvals, and patent expiries, firms can anticipate shifts in market share and pricing power. The high market concentration indicates that consolidation or strategic partnerships may play a role in future market evolution. Stakeholders can use this data to assess merger and acquisition opportunities, identify potential collaborators, or devise defensive strategies against emerging competitors.
Furthermore, the regional analysis supports geographic expansion strategies. Companies looking to enter new markets can leverage the data to prioritize regions with favorable growth prospects and regulatory pathways. Conversely, firms may identify regions where supply chain vulnerabilities or pricing pressures require mitigation. The detailed regional breakdowns available in the full report enable granular market entry strategies tailored to local conditions.
Ultimately, the value of this research lies in its ability to convert raw data into actionable intelligence. In a market defined by regulatory rigor, patent nuances, and competitive intensity, having access to comprehensive, up-to-date information is a decisive advantage. It allows organizations to move from reactive responses to proactive strategy formulation, ensuring resilience and growth in a dynamic global environment.
Conclusion
The Worldwide Pharmaceutical Grade Posaconazole Market presents a compelling landscape for strategic engagement in 2026. With a solid historical growth record and a projected CAGR of 5.42 percent, the market offers opportunities for those who can effectively manage the complexities of formulation competition, regulatory compliance, and supply chain integrity. The interplay between originator brands, generic entrants, and API manufacturers creates a rich ecosystem where innovation and efficiency are rewarded.
However, realizing the full potential of this market requires more than high-level trends. It demands a deep understanding of segmentation splits, regional demand patterns, competitive moves, and the regulatory fine print that governs market access. Our comprehensive market research report provides this depth, offering the detailed data and analysis necessary to make informed, high-stakes decisions. For stakeholders committed to leading in this sector, accessing the full intelligence is the next critical step.
To explore the complete segmentation data, detailed competitor profiles, and region-specific forecasts, we invite you to review the full Worldwide Pharmaceutical Grade Posaconazole Market report. This document serves as your definitive guide to navigating the opportunities and challenges of this vital pharmaceutical segment through 2032.
Prothioconazole Market
For detailed analysis of this topic, please visit the official page: Worldwide Pharmaceutical Grade Posaconazole Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Military Smart Wearables Market Hits $3,715M in 2025, Forecast 13.8% CAGR to $9,182M by 2032
By pmarketresearch, 2026-09-17
Strategic Horizons: Navigating the Worldwide Military Smart Wearable Devices Market Through 2032
Executive Overview
The contemporary battlefield is increasingly defined by data, connectivity, and the enhancement of individual soldier capabilities. As armed forces globally pivot toward modernization, the integration of smart wearable technologies has transitioned from experimental concepts to critical operational necessities. Our latest comprehensive study, Worldwide Military Smart Wearable Devices Market, offers a definitive analysis of this rapidly evolving landscape. Covering historical performance from 2020 through 2025 and projecting forward to 2032, this research provides the strategic intelligence required to navigate complex procurement cycles, technological disruptions, and shifting geopolitical demands.
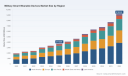
This market has demonstrated resilience and robust expansion over the past half-decade. In 2020, the global revenue stood at approximately 1950.4 million USD, reflecting the early stages of widespread adoption. By 2025, this figure had surged to 3715.06 million USD, underscoring the accelerating pace of deployment across multiple defense sectors. Looking ahead, the trajectory remains steep. The market is projected to reach 4109.98 million USD in 2026 and continue climbing to 9182.52 million USD by 2032. This growth represents a compound annual growth rate of 13.8 percent throughout the forecast period, signaling a sustained investment cycle that rewards early movers and strategic planners who understand the nuances of this domain.
Market Drivers and Technological Imperatives
The expansion of the military smart wearable sector is not merely a function of budgetary increases but is driven by fundamental changes in combat doctrine. Modern warfare requires heightened situational awareness, real-time health monitoring, and seamless communication networks. Soldiers are no longer just combatants; they are nodes within a broader Internet of Military Things (IoMT). Wearable devices facilitate this shift by enabling continuous monitoring of vital signs, environmental hazards, and tactical positioning.
Several key factors are propelling this demand. First, the need for extended dismounted operations pushes the requirement for reliable power management. Hardware bottlenecks often center on high-density, conformal batteries capable of supporting operations beyond 72 hours without resupply. Second, interoperability remains a critical priority. Defense agencies are increasingly mandating compliance with standards such as MIL-STD-810 for environmental durability, MIL-STD-461 for electromagnetic interference, and GOSSRA for Generic Open Soldier Systems Reference Architecture interoperability. These standards ensure that wearable sensors and networks integrate securely into tactical communications without compromising cybersecurity or data integrity.
Worldwide Military Wearable Market
Furthermore, regulatory frameworks are shaping market dynamics. Policies from the U.S. Department of Defense, for instance, restrict geolocation-capable wearables in certain operational areas and classified facilities, while allowing approved fitness and health monitoring devices under specific compliance criteria. Recently, updates such as the U.S. Air Force prohibition on wearing consumer smart glasses like Meta AI devices in uniform due to operational security risks highlight the delicate balance between innovation and security. Understanding these regulatory constraints is essential for any organization seeking to enter or expand within this market.
Segmentation Insights and Operational Focus
Our research dissect the market across multiple dimensions, providing granular visibility into where growth is concentrated and how technologies are categorized. The product landscape is diverse, encompassing head-mounted displays, body-worn cameras and sensors, smart watches and wrist-worn devices, exoskeletons, and power and data management devices. Each category serves distinct operational requirements, from augmented reality overlays for pilots and ground troops to haptic feedback systems for heavy lifting and endurance.
Application-wise, the market is driven by needs for situational awareness, health and vital monitoring, communication and navigation, and training and simulation. Situational awareness remains a primary focus, as forces seek to maintain a comprehensive understanding of the battlespace through real-time data feeds. Health and vital monitoring is equally critical, with programs like the U.S. Army's Wearable All-hazard Remote-monitoring Program advancing toward program of record status. This initiative utilizes patches for chemical, biological, and biometric monitoring, reflecting a broader trend toward precision health in military personnel. Training and simulation also leverage wearable tech, allowing for immersive experiences that prepare personnel for complex scenarios without the risks associated with live exercises.
Regional dynamics also play a significant role in market distribution. Investment levels vary across North America, Europe, Asia Pacific, the Middle East and Africa, and Latin America, influenced by local defense budgets, modernization programs, and geopolitical tensions. Our analysis provides a clear picture of these regional strengths without oversimplifying the unique procurement environments present in each geography.
Competitive Landscape and Strategic Positioning
The market features a mix of established defense giants and specialized technology firms, creating a competitive environment where innovation and compliance intersect. The top players hold significant market share, with the top three companies accounting for 42.5 percent of the market and the top five reaching 61.8 percent. This concentration indicates a mature market where scale and established relationships matter, yet there is still room for niche innovators who can solve specific technological hurdles.
Key contributors to the ecosystem include BAE Systems, which develops advanced soldier systems integrating health monitoring, communication, and tactical wearables for enhanced combat readiness. Elbit Systems Ltd. provides wearable systems tailored to military modernization programs, focusing on soldier health monitoring and electronic warfare solutions. Lockheed Martin Corporation invests in integrated wearable technologies including sensor systems and soldier modernization platforms for tactical operations. Honeywell International Inc. offers sensing, navigation, and wearable electronics focusing on durability and performance, while L3Harris Technologies Inc. supplies communication-focused wearables and tactical systems compliant with military standards.
European defense contractors are also highly active. Leonardo S.p.A. delivers defense electronics and wearable solutions for situational awareness, while Thales Group provides advanced sensors and communication systems for defense applications. Rheinmetall AG focuses on soldier systems and integrated wearable platforms for European and NATO forces, and Saab AB supplies tactical wearables emphasizing survivability and awareness. Aselsan A.S. develops electronic warfare and wearable sensor systems, adding regional depth to the competitive field.
Commercial technology firms are also making inroads. General Dynamics Corporation develops mission systems including communication and wearable technologies for ground forces. Garmin Ltd. provides rugged navigation and health monitoring wearables adapted for military use. Vuzix Corporation supplies AI-powered smart glasses and waveguide optics for military helmet-mounted AR/HUD systems, recently highlighting defense waveguide solutions and military helmet integration with Collins Aerospace. Microsoft Corporation develops augmented reality platforms, such as HoloLens adaptations, for military training and operational use. These collaborations between commercial innovators and defense primes illustrate the cross-pollination of technology that is defining the next generation of military wearables.
Worldwide Military Smart Wearable Devices Market
Recent Developments and Future Outlook
Recent activity underscores the momentum in this sector. In early 2026, Yank Technologies was selected for a U.S. Army Phase II SBIR contract valued at 2 million USD to advance wireless charging systems for conformal wearable batteries in military vehicles, addressing the critical power management bottleneck. Around the same time, Vuzix Corporation showcased defense waveguide solutions at major industry events, emphasizing rugged AR applications. The U.S. Army updated its Wearable All-hazard Remote-monitoring Program, noting initial fielding to special operations in late 2025 and progress toward program of record status in FY2027. Additionally, RTI International released details on the AlphaWear platform for the U.S. DoD, designed to monitor heat stress, infection risk, and mental health using wearable data for precision health.
Looking toward 2032, the market is poised for continued evolution. As cybersecurity, data interoperability, and MIL-SPEC environmental qualification become non-negotiable requirements, suppliers who can deliver secure, resilient, and interoperable solutions will capture the greatest value. The convergence of AI, advanced sensors, and ruggedized hardware will further blur the lines between consumer electronics and military-grade equipment, requiring strict adherence to operational security protocols.
How This Research Empowers Your Strategy
Our Worldwide Military Smart Wearable Devices Market report is designed to be a practical tool for decision-makers. It goes beyond high-level statistics to offer actionable intelligence on procurement trends, technology roadmaps, and competitive moves. Readers will find detailed profiles of key companies, analysis of recent contract awards and product launches, and a thorough examination of regulatory impacts. Whether you are evaluating entry opportunities, assessing competitor capabilities, or planning long-term R&D investments, this study provides the context needed to mitigate risk and identify growth vectors.
We invite you to explore the full scope of our findings. The complete report contains detailed segmentation data, regional breakdowns, and proprietary forecasts that are essential for crafting a winning strategy in this high-stakes environment. Access the full intelligence today to stay ahead of the curve in the global military smart wearable devices market.
For detailed analysis of this topic, please visit the official page: Worldwide Military Smart Wearable Devices Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Global Company Secretary Tool Revenue Hits $1.98B in 2025, Surging 12.15% CAGR Through 2032
By pmarketresearch, 2026-09-17
Navigating the New Era of Corporate Governance: Strategic Insights from the Worldwide Company Secretary Tool Market
The role of the company secretary has evolved from a largely administrative function to a cornerstone of strategic governance, risk management, and regulatory compliance. As organizations face intensifying scrutiny from regulators, shareholders, and data privacy authorities, the technology stack supporting secretarial and governance teams has become a critical differentiator. Our latest research initiative delivers a comprehensive examination of the Worldwide Company Secretary Tool Market, offering decision-makers a clear view of where value is being created, how competitive dynamics are shifting, and which operational priorities will define the 2026-to-2032 horizon.
This report is designed for executives who must translate market complexity into actionable strategy. Rather than presenting a surface-level snapshot, the analysis grounds itself in a rigorous historical baseline and a forward-looking forecast architecture that connects technology adoption, regulatory pressure, and enterprise spending patterns. The foundational market size trajectory illustrates a sector that has consistently expanded through successive years of transformation. From a baseline of approximately 1.08 billion USD in 2020, the market progressed steadily through 2021, 2022, and 2023, reflecting early digitization efforts and growing awareness of governance technology. Growth accelerated markedly in 2024 and 2025, driven by broader cloud adoption, heightened compliance obligations, and a renewed focus on board effectiveness. The forecast period from 2026 through 2032 extends this trajectory, with the market projected to move from a 2026 estimate of roughly 2.21 billion USD toward a 2032 figure of approximately 4.42 billion USD. Across the forecast horizon, the compound annual growth rate is assessed at 12.15 percent, signaling sustained structural demand rather than a temporary compliance-driven surge.
The strategic relevance of these figures lies not only in their magnitude but in what they represent for enterprise planning. A double-digit growth rate in a specialized governance technology category indicates that company secretarial tools are no longer peripheral utilities. They are increasingly integrated into broader governance, risk, and compliance ecosystems. Boards and executive teams are seeking tools that reduce manual workload, improve the reliability of statutory filings, strengthen entity oversight across jurisdictions, and support secure collaboration around sensitive governance materials. In this environment, the market intelligence provided by our study becomes a practical input for budgeting, vendor evaluation, product roadmap decisions, and long-term organizational resilience.
From Historical Momentum to 2026 Decision Frameworks
Understanding where the market is heading requires more than reading a forecast curve. It demands attention to the operational forces reshaping demand. Over the 2020-to-2025 historical window, the sector benefited from a combination of regulatory modernization, cross-border entity complexity, and the ongoing migration of governance workloads away from manual or spreadsheet-based processes. The forecast period builds on that momentum by emphasizing tools that can adapt to changing filing requirements, varying jurisdictional obligations, and higher expectations for data protection and audit readiness.
For decision-makers, the 2026 landscape introduces several immediate considerations. First, technology selection is increasingly tied to compliance agility. As filing rules and cybersecurity expectations continue to evolve, organizations need platforms that can accommodate regulatory updates without costly re-engineering or fragmented workarounds. Second, the economics of compliance remain material. Recent estimates suggest that the average U.S. firm allocates a meaningful share of its total wage bill to regulatory compliance activities, underscoring the operational impact of secretarial and governance labor. Tools that automate routine filings, maintain registers, streamline confirmation statements, and coordinate board materials can help contain these costs while improving consistency. Third, the cost of failure is rising. Noncompliance-related data breaches have been associated with an average cost above 4.6 million USD in 2025, a figure that highlights the financial and reputational implications of weak governance controls. These dynamics reinforce why company secretary tools are now evaluated not only on convenience, but on their ability to reduce exposure across legal, regulatory, and cyber domains.
Our report captures these decision frameworks in a structured way, mapping market growth to the operational problems that buyers are trying to solve. This allows leaders to assess not just how large the market may become, but what kind of capability investment is warranted in different operating environments.
What the Report Covers: A Practical View of the Analysis
The study is organized to support both strategic overview and operational detail. It begins with a full market definition and scope architecture, ensuring that readers understand which product categories, workflows, and user contexts are included in the analysis. From there, the report examines historical performance and forecast trajectories, providing a clear account of how the market has expanded and how that expansion is expected to unfold across the forecast window.
A central feature of the research is its segmentation logic. The analysis breaks the market into solution types that reflect how organizations actually structure their governance and secretarial technology stacks. This includes entity management software, board portal software, and compliance and e-filing tools. Each category is explored in terms of its functional role, adoption drivers, and position within the broader governance workflow. The report also evaluates deployment models, distinguishing between cloud-based and on-premise approaches, because deployment preferences influence integration requirements, update cycles, security postures, and total cost of ownership.
Beyond segmentation, the report includes a detailed competitive landscape. This section does not merely list vendors; it contextualizes them by examining the types of solutions they bring to market, the regions and use cases they serve, and the strategic implications of their product positioning. The study also incorporates recent market developments and product movements that shape near-term buying behavior and vendor momentum. These include software updates aligned with new filing requirements, feature enhancements that refine access control and entity-level management, and partnerships that extend compliance capabilities through integrated service models.
The report further integrates industry context that affects demand for company secretary tools. This includes regulatory developments that influence governance, cybersecurity, and data handling expectations, as well as operational cost considerations that affect how firms evaluate automation and labor-intensive processes. By connecting these external forces to market behavior, the study provides a decision-oriented lens rather than an abstract market description.
Competitive Landscape and Vendor Positioning
The company secretary tool market is shaped by a diverse mix of established governance technology providers, specialized compliance software vendors, and emerging platforms that emphasize cloud-native entity management or board collaboration. The report analyzes this landscape by distinguishing between vendors that focus primarily on board management and those that extend more broadly into entity governance, compliance filing, and secretarial workflow automation.
Worldwide Company Secretary Tool Market
Among the major players, Diligent Corporation offers a well-known combination of board management and global entity management capabilities, supporting corporate secretaries with governance processes and regulatory filings. Nasdaq contributes through board portal and governance solutions that support meeting management and compliance-oriented collaboration. Wolters Kluwer is recognized for company secretarial software that supports filings, registers, and confirmation statements, reflecting a strong emphasis on statutory process automation. Athennian represents a cloud-based entity management approach that addresses legal entity governance, document automation, and multi-jurisdiction compliance workflows. BoardEffect focuses on secure board document collaboration and meeting preparation with an emphasis on company secretarial use cases. Azeus Systems provides board management and collaboration software with compliance-oriented features, and has expanded its market presence through partnerships aimed at integrated compliance solutions.
Additional vendors add further depth to the landscape. Loomion emphasizes collaboration and secure document handling for governance teams. Corporatek Inc. supports entity and compliance management workflows tied to regulatory requirements. Computershare brings board management and global entity management capabilities relevant to corporate secretarial tasks and regulatory filings. OnBoard offers a board intelligence and management platform designed to streamline meeting materials and governance processes. From the compliance automation side, Volody, CimplyFive, and Axar Digital target company secretarial workflows, statutory compliance, filings, and entity management, reflecting growing regional demand for specialized secretarial tools. In the United Kingdom context, BGL Corp and Relate Software provide company secretarial software focused on company returns, statutory registers, and compliance under relevant Companies Act obligations. BGL Corp notably updated its CAS 360 solution to align with significant Companies House filing changes, while Azeus Systems announced a partnership with KPMG Singapore to offer integrated compliance solutions, and Officio Cloud enhanced access controls that allow owner role users to limit access to specific entities.
This competitive breadth matters because it illustrates how different vendors are addressing the same underlying pressure points from different angles. Some organizations prioritize board-level collaboration and secure document flow. Others focus on entity registers, statutory filings, and jurisdiction-specific obligations. Still others emphasize automation, integration, or service-linked compliance models. The report helps leaders interpret these differences in a structured way so they can match vendor capabilities to organizational complexity, geographic footprint, and internal governance priorities.
Corporate Secretarial Services Market
Market Dynamics Shaping Demand Through 2032
The forecast period is not driven by technology trends alone. It is strongly influenced by regulatory and operational conditions that affect how governance tools are selected, deployed, and maintained. Several dynamics stand out.
Regulatory complexity continues to raise the bar for governance platforms. In the United States, the DOJ Bulk Data Rule effective from April 2025 introduced stringent cybersecurity controls and record-keeping expectations for certain transactions involving bulk sensitive personal data or government-related data. At the same time, multiple state comprehensive consumer data privacy laws have added new operational obligations for data processing, including measures effective in Minnesota and Maryland during 2025. These developments matter for company secretary tools because corporate records, board materials, and compliance data are increasingly part of broader data governance and privacy obligations. The New York Department of Financial Services cybersecurity requirements have also been applied more fully to financial services companies, with periodic risk assessments and compliance certifications that can extend to governance and compliance platforms.
These regulatory movements reinforce a wider trend: governance software is no longer evaluated solely on workflow convenience. It is increasingly considered part of the organization's control environment. That shift favors solutions with strong access management, auditability, versioning, and the ability to adapt to new filing or reporting rules without disrupting established processes. It also favors vendors that can demonstrate a credible approach to data protection and compliance readiness.
Beyond regulation, the cost structure of compliance work remains an important demand driver. When firms spend a noticeable portion of their wage bill on regulatory compliance activities, the potential efficiency gains from automation become strategically relevant. Company secretary tools that reduce manual register maintenance, simplify statutory filings, and streamline board meeting preparation can support both cost containment and consistency. In practice, this means the market is likely to continue favoring platforms that combine usability with process depth, especially where organizations manage multiple entities, multiple jurisdictions, or frequent changes in filing obligations.
The report examines these dynamics in a way that helps executives anticipate how vendor value propositions will be tested over time. Rather than treating regulation as a static backdrop, the analysis frames it as a moving variable that shapes purchasing criteria, implementation priorities, and vendor suitability.
How to Use This Research for 2026 Strategy
The value of this study lies in its ability to support concrete decisions. For governance, legal, and compliance leaders, the report provides a foundation for evaluating whether current tools are sufficiently aligned with future filing, security, and entity management requirements. For procurement and IT teams, it offers a market context that can inform vendor shortlisting, deployment choices, and integration planning. For investors and business development teams, it maps where growth is concentrated and how competitive coverage is evolving.
Importantly, the report does not stop at high-level trends. It connects those trends to the operational realities of company secretarial work: maintaining accurate registers, preparing filings on time, coordinating board materials securely, and managing compliance across organizational structures. By doing so, it helps readers distinguish between vendors that simply offer features and those that are better positioned to support sustained governance performance in a more demanding regulatory environment.
To access the full segmentation detail, competitive profiling, regional and solution-level breakdowns, deployment analysis, and forecast architecture underpinning these conclusions, please refer to the complete report through the source page. The complete study provides the depth required for procurement comparisons, market entry planning, product strategy, and board-level investment decisions.
In a market expanding at a double-digit rate and shaped by heightened compliance, cybersecurity, and entity complexity, the ability to choose the right governance technology has become a strategic capability. This research is designed to give decision-makers the clarity they need to act with confidence throughout 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Worldwide Company Secretary Tool Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Rheology Modifier Coating Additive Market to Hit $4.79 Billion by 2032 at 4.8% CAGR
By pmarketresearch, 2026-09-17
Strategic Intelligence in the Global Rheology Modifier Coating Additive Market: Key Insights for 2026 Decision-Makers
The global landscape for rheology modifier coating additives is undergoing a structural transformation driven by regulatory shifts, raw material volatility, and the accelerating transition to waterborne formulations. For executives navigating product portfolios, supply chain strategies, and capital allocation in 2026, surface-level market summaries are no longer sufficient. Comprehensive, granular intelligence is required to anticipate margin compression, identify high-growth application pockets, and benchmark competitive positioning against incumbents expanding capacity and launching next-generation chemistries. This newly released Worldwide Rheology Modifier Coating Additive Market study delivers precisely that depth. Designed as a decision-ready intelligence asset, the report synthesizes historical performance, forecast trajectories, and competitive dynamics into a cohesive framework that aligns with the strategic planning cycles of coatings manufacturers, additive suppliers, and downstream formulators.
Market Trajectory and the 2026 Inflection Point
The sector has demonstrated consistent expansion across the historical review window, advancing from approximately 2.75 billion USD in 2020 to an estimated 3.45 billion USD by 2025. This growth reflects sustained formulation modernization across architectural, industrial, and protective coating segments, alongside tightening environmental mandates that favor rheology additives capable of maintaining application performance while reducing volatile organic compound content. Looking ahead, the forecast period from 2026 through 2032 projects a compound annual growth rate of 4.8 percent, positioning the market to surpass 4.79 billion USD by the terminal forecast year.
These aggregated figures represent more than a simple top-line projection. They encapsulate a market recalibrating around formulation efficiency, regulatory compliance, and regional manufacturing footprints. The trajectory indicates that demand will not be distributed uniformly; rather, it will concentrate in applications where viscosity control, sag resistance, and levelness are non-negotiable performance parameters. Understanding how these macro trends intersect with segment-specific drivers, supply chain constraints, and pricing mechanisms is critical for 2026 planning. The full report dissects these intersections without oversimplifying, enabling stakeholders to map growth vectors against their own product roadmaps and procurement strategies.
Executives should note that the forecast horizon extends beyond short-term cyclical fluctuations. The modeled expansion incorporates structural shifts in formulation preferences, regulatory compliance costs, and capacity adjustments by key producers. By grounding strategy in these forward-looking parameters, organizations can better align inventory planning, R&D focus, and partnership development with the market's actual growth architecture. The report provides the analytical scaffolding required to translate these projections into actionable commercial and operational decisions.
Competitive Architecture and Strategic Positioning
The rheology modifier coating additive sector is characterized by a moderately concentrated competitive landscape, with the top three players collectively commanding 38.4 percent of market revenue and the top five accounting for 52.15 percent. This concentration reflects decades of formulation expertise, established technical service networks, and continuous innovation in associative thickeners, organoclays, cellulose derivatives, and polyurethane-based modifiers. Yet the remaining share distribution underscores meaningful fragmentation at the regional and application-specific level, creating both competitive threats and partnership opportunities for incumbents and challengers alike.
Worldwide Rheology Modifier Coating Additive Market
Leading global suppliers have built differentiated value propositions around viscosity control mechanisms, compatibility with low-VOC and solventborne systems, and rapid technical support for formulators. Major players headquartered across North America, Europe, and Asia maintain extensive portfolios spanning organoclays, hydrophobically modified ethoxylated urethanes, polyamide waxes, fumed silica-based additives, and cellulosic thickeners. Their product architectures are increasingly tailored to meet application-specific demands in architectural paints, industrial coatings, automotive finishes, wood and furniture coatings, and marine protective systems. The report profiles these core companies in detail, mapping their product ranges, geographic reach, formulation specialties, and recent strategic moves that signal where each competitor is placing its commercial bets.
Rheology Modifiers Market
Recent corporate activities illustrate the pace of competitive maneuvering. In late 2025, a global leader in organoclay and associative thickeners introduced a VOC-free organoclay rheology modifier engineered for enhanced sag resistance in waterborne coatings, directly addressing the formulation constraints of decorators and industrial painters. Earlier in the same year, a major North American chemical supplier launched a hydrophobically modified alkali-swellable emulsion grade designed to deliver high-shear viscosity in low-VOC paints, reflecting the industry's push for application robustness without compromising environmental performance. Alongside these product launches, certification milestones and production expansions have reshaped the competitive baseline. A prominent European supplier secured EU Ecolabel certification for a polyurethane-based rheovis modifier tailored to low-emission interior coatings, reinforcing its positioning in sustainability-driven architectural segments. Meanwhile, capacity expansions at European manufacturing sites have increased output of specific associative thickeners by roughly 20 percent, underscoring the strategic importance of securing supply for waterborne formulation growth.
These developments are not isolated product news; they are indicators of where value creation is shifting. The report analyzes how each competitive action influences pricing power, formulation substitution risks, and regional supply dynamics. By benchmarking your organization's capabilities against these moves, you can identify gaps in technical service, formulation support, or portfolio coverage that may affect win rates in key customer segments.
Regulatory Currents and Raw Material Dynamics Shaping Formulation Economics
The 2026 planning environment is heavily influenced by regulatory and input-cost variables that directly affect formulation economics and additive selection. Recent regulatory updates have introduced compliance considerations that formulators and suppliers must navigate carefully. Restrictions under EU chemical regulations now limit certain associative thickeners containing nonylphenol ethoxylates above threshold concentrations, prompting reformulation efforts and supplier qualification updates across European and export-oriented markets. In parallel, regional hazard communication requirements in the United States have mandated warning labels for specific thickener chemistries containing unreacted acrylamide, affecting labeling, documentation, and customer communication workflows for decorative and industrial coating producers.
Raw material pricing volatility adds another layer of complexity. Key solvent inputs used in solventborne rheology modifier formulations have experienced notable price fluctuations, with certain glycol ether acetate derivatives averaging elevated levels in late 2025. Simultaneously, isobutanol feedstock costs rose significantly year-over-year due to supply disruptions in the US Midwest, affecting the cost base for certain associative thickener and wax-based systems. These input dynamics do not impact all chemistries equally, which is why understanding the cost structure and substitution elasticity across organic and inorganic rheology modifiers is essential for margin protection.
Trade policy developments further complicate the procurement landscape. Adjustments to US tariff schedules on imported cellulose ethers have increased duty burdens on certain raw material streams, altering the relative cost competitiveness of regional supply chains. For formulators balancing performance, regulatory compliance, and total cost of ownership, these shifts create both risk and opportunity. The report evaluates how regulatory timelines, feedstock price trajectories, and trade measures intersect with segment demand, helping stakeholders anticipate formulation pivots, supplier transitions, and pricing negotiations in 2026 and beyond.
Application-Level Demand Drivers and Formulation Priorities
Demand for rheology modifiers is not uniform across end-use categories. Architectural coatings continue to represent a substantial share of consumption, driven by renovation cycles, housing activity, and the ongoing shift toward waterborne decorative formulations that require precise viscosity control, open time management, and sag resistance. Industrial coatings contribute a significant and technically demanding demand base, where shear-thinning behavior, anti-sag performance, and compatibility with high-solids systems are critical for achieving consistent film formation across metal, plastic, and composite substrates. Automotive coatings impose stringent aesthetic and performance requirements, with rheology additives playing a crucial role in gloss uniformity, levelness, and application robustness under varying shop conditions.
Wood and furniture coatings, as well as marine and protective coatings, represent additional demand pillars with distinct formulation challenges. These segments often require additives that can withstand harsh environmental exposure, maintain stability in solventborne and high-solids systems, and deliver consistent rheological performance across diverse pigment and filler loadings. The report examines how application-specific performance expectations shape additive selection, technical service requirements, and pricing dynamics, highlighting where formulation innovation is translating into commercial differentiation.
Importantly, the growth in waterborne and low-VOC systems is reshaping the relative attractiveness of organic versus inorganic rheology modifiers. Associative thickeners, hydrophobically modified polymers, and advanced cellulosic systems are gaining prominence in segments where environmental compliance and application performance must be balanced. Inorganic thickeners, including organoclays and fumed silica, continue to serve critical roles in solventborne and high-solids applications where thixotropic control and anti-sag properties are paramount. The full analysis delineates how these chemistry preferences evolve across regions and applications, providing a clear view of where substitution risk and portfolio expansion opportunities are most pronounced.
What the Report Delivers: Operational Intelligence for 2026 Planning
This market study is structured to move beyond high-level summaries and deliver operational intelligence that can be immediately integrated into strategy, procurement, and R&D processes. The report provides a comprehensive segmentation framework that maps market size, growth trajectories, and competitive intensity across region, type, and application dimensions. Stakeholders gain visibility into where demand is consolidating, where regional manufacturing footprints influence supply security, and which application categories are driving the most technically advanced rheology modifier requirements.
The competitive profiling section delivers detailed assessments of leading suppliers, including their headquarters, core product families, formulation specialties, and strategic positioning within architectural, industrial, automotive, wood, and marine coating markets. These profiles are complemented by a timeline of recent corporate developments, including product launches, grade introductions, capacity expansions, and certification achievements. By connecting these actions to broader market trends, the report helps readers interpret competitor intent and anticipate shifts in technical service emphasis, portfolio focus, and regional availability.
Beyond competitive and segmentation analysis, the study integrates market concentration metrics to clarify the balance between incumbent dominance and niche competition. This context is essential for assessing pricing dynamics, negotiating leverage, and the feasibility of entering or expanding within specific sub-segments. The report also examines how regulatory timelines, raw material cost movements, and trade policy adjustments are affecting formulation economics, providing a practical lens for evaluating supplier alternatives, inventory strategies, and cost pass-through mechanisms.
For organizations seeking to align product development with market demand, the report outlines the performance parameters that increasingly drive additive selection, including viscosity buildup characteristics, shear-thinning behavior, compatibility with waterborne and solventborne systems, and compliance with evolving environmental standards. These insights are designed to inform technical service roadmaps, customer messaging, and cross-functional planning across R&D, sales, and supply chain teams. By consolidating market sizing, competitive intelligence, regulatory context, and application-level demand drivers into a single authoritative source, the study reduces the time and uncertainty associated with piecing together fragmented data from multiple channels.
Translating Market Intelligence into 2026 Action
The strategic value of this report lies in its ability to convert complex market signals into clear decision frameworks. For coatings manufacturers, the analysis supports formulation portfolio optimization, raw material sourcing strategies, and regional expansion priorities. For additive suppliers, the study provides a detailed view of competitor positioning, customer formulation trends, and capacity allocation signals that inform technical service investments and product launch timing. For downstream stakeholders and investors, the report offers a structured perspective on market concentration, growth vectors, and the regulatory and cost variables that will shape profitability through the end of the decade.
In a market where performance expectations are rising, regulatory compliance is intensifying, and raw material costs are subject to regional disruptions, information advantage translates directly into commercial resilience. The report is designed to deliver that advantage by providing granular, decision-grade intelligence that goes well beyond aggregated headline figures. Stakeholders who integrate these insights into their 2026 planning cycles will be better positioned to navigate formulation transitions, manage supply chain volatility, and capture growth in the segments where rheology modifiers are becoming increasingly indispensable.
To access the complete segmentation analysis, full competitor profiles, detailed regional and application breakdowns, and the comprehensive regulatory and raw material assessments that underpin the forecast model, please visit the source page for the Worldwide Rheology Modifier Coating Additive Market research. The full report provides the depth and precision required to turn market intelligence into executable strategy across 2026 and the forecast horizon.
For detailed analysis of this topic, please visit the official page: Worldwide Rheology Modifier Coating Additive Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Portable Gantry Crane Market Hits $682.57M in 2025, Projected 4.71% CAGR Through 2032
By pmarketresearch, 2026-09-17
Powering Precision: Strategic Imperatives in the Global Portable Gantry Crane Market Through 2032
The worldwide portable gantry crane market stands at a critical inflection point where operational flexibility, material science, and automation converge to redefine how industries move heavy loads. As manufacturing footprints shift, warehouse networks expand, and construction programs demand faster mobilization, portable gantry cranes have transitioned from utilitarian support equipment to strategic assets that shape throughput, safety, and capital efficiency. For executives navigating a 2026 decision cycle, understanding where this market is headed—and why—is no longer optional. The latest market intelligence from PW Consulting maps a seven-year trajectory of steady expansion, structural segmentation, and intensifying competitive differentiation, offering a decision-grade lens for procurement, product strategy, and regional deployment.
This analysis is designed as a strategic preview of our full market study. It surfaces the macro architecture of demand, the forces reshaping supply, and the operational questions that will determine which organizations capture value as the market matures. The objective is to equip leadership teams with a clear framework for interpreting growth, evaluating vendor portfolios, and anticipating the material and regulatory variables that will influence total cost of ownership in the years ahead.
Worldwide Spider Crane Market
Market Architecture and the Growth Trajectory
Drawing on historical performance from 2020 through 2025 and a forward view extending to 2032, the market demonstrates resilient expansion anchored in broad-based industrial demand. The overall revenue base has progressed from approximately 545.12 million USD in 2020 to 682.57 million USD in 2025, reflecting cumulative growth across multiple end-use sectors and geographies. The forecast period maps a continued ascent, with 2026 projecting to 735.99 million USD, followed by measured climbs through the late 2020s and acceleration into the early 2030s, reaching an estimated 942.03 million USD by 2032. This path implies a compound annual growth rate of 4.71 percent over the forecast horizon, a pace that signals durable demand rather than cyclical spikes.
Such a growth profile is meaningful for capital planning. A mid-single-digit CAGR in a specialized lifting equipment category suggests that the market is being pulled by structural enablers—modular facility design, just-in-time material flow, and the need for rapidly deployable lifting solutions—rather than by a single short-term catalyst. The base year of 2025 and the historical window provide a validated reference point, while the forecast interval gives executive teams a usable planning runway for product roadmaps, capacity allocation, and service infrastructure. In practical terms, the numbers indicate that demand will keep expanding, but the distribution of that growth will vary by segment, region, and application profile, making segmentation intelligence essential for targeted investment.
Segmentation Signals That Shape Strategy
Portable gantry cranes are not a uniform category. Demand fractures along material construction, lifting capacity, end-user industry, and regional operating environment, and each fracture point carries distinct implications for pricing, specification, and service requirements.
- Material choice remains a defining commercial variable. Steel-based portable gantry cranes represent the larger revenue pool, favored where structural robustness, higher load retention, and long service life are paramount. Aluminum portable gantry cranes form a substantial secondary stream, appealing where portability, corrosion resistance, and rapid reconfiguration matter most. The balance between these material paths is sensitive to input cost dynamics, and in 2025 global steel prices stabilized in the low-to-mid $800s per short ton in the United States, with sideways to modestly firmer trends anticipated into 2026 as iron ore and scrap costs continue to influence producer economics. In parallel, the Chinese benchmark steel price reached approximately 3,154 CNY per ton as of April 2026, reflecting a moderate year-over-year uptick of about 2.57 percent.
- Capacity requirements divide the market into three practical bands: below 1 ton, 1 to 5 tons, and above 5 tons. Each band aligns with a different operational profile, from light industrial and workshop lifting to mid-range warehouse handling and heavier construction or infrastructure support. Understanding which capacity band is gaining share—and where—helps buyers and manufacturers align product portfolios with real-world load profiles rather than nominal specifications.
- End-user demand spans automotive and transportation, warehousing and logistics, construction and infrastructure, and general manufacturing. Each vertical imposes different cadence, duty cycle, and safety expectations. Warehousing and logistics often prioritize quick setup and repeatable lift precision; construction and infrastructure favor mobility and ruggedness; automotive and transportation applications demand consistency across line-side handling; and general manufacturing seeks adaptable solutions that can serve multiple work cells.
- Regional variation matters as much as application variation. Demand is distributed across North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa, with each region exhibiting its own mix of infrastructure spend, industrial modernization, and procurement norms. The regional split is not merely a geographic footnote; it reflects divergent adoption curves for automation, differing labor cost structures, and local content expectations that influence both specification and sourcing strategy.
These segmentation layers interact. A steel crane in the 1-to-5-ton band may be the right answer for a construction staging yard, while an aluminum unit in the same capacity range may fit a cross-dock logistics operation better. The strategic value of segmentation insight is that it converts a broad market number into actionable selection criteria for both buyers and vendors.
Competitive Landscape and Differentiation Levers
The market is characterized by a broad manufacturer base with a concentration profile that signals room for competitive maneuvering. The combined share of the top three participants stands at 18.45 percent, and the top five reach 29.12 percent, indicating a fragmented landscape where product specialization, regional reach, and service capability can outweigh scale alone. This structure rewards companies that can combine reliable mechanical design with application-specific configurations and responsive support.
Several established players illustrate the differentiation pathways shaping the market. Spanco, Inc. focuses on portable gantry cranes with adjustable height, span, and tread options across steel and aluminum lines, emphasizing flexible industrial material handling. Wallace Cranes designs portable gantry systems and broader industrial crane platforms for manufacturing, construction, and warehouse use, with a clear alignment to OSHA safety expectations. Shuttlelift targets heavy-duty lifting of long and oversized loads through rubber-tired mobile gantry cranes, including series engineered for concrete, steel, and modular components. Konecranes contributes mobile and portable gantry options with advanced automation, safety features, and precise control systems. Liebherr brings hydraulic sophistication and heavy-duty performance to gantry and mobile crane offerings, particularly in construction and industrial settings. Gorbel emphasizes easy-to-install portable gantry designs for job sites that require quick setup and adaptability in constrained spaces. Vestil Manufacturing Corp. supplies fixed-height portable gantry solutions for work-area lifting, with capacities geared toward lighter industrial and warehouse applications. XCMG provides mobile gantry cranes and heavy-duty lifting equipment with custom solutions for demanding industrial and construction requirements. Demag Cranes & Components offers precision-engineered modular gantry designs, including mobile variants for industrial material handling. Henan FineWork Cranes Co., Ltd. manufactures portable gantry cranes with custom solutions, including adjustable spans and heights for varied heavy-load environments.
Worldwide Portable Gantry Crane Market
What unites these competitors is not a single technology but a shared need to translate mechanical reliability into application outcomes. In a fragmented market, advantage increasingly comes from configurable product families, integration with site workflows, and the ability to support customers through installation, training, and maintenance. Companies that can demonstrate measurable reductions in setup time, safer load handling, and lower lifecycle friction are better positioned to defend pricing and win recurring service relationships.
Forces Reshaping Demand and Cost Structures
Beyond segmentation and competition, several external forces are rewriting the rulebook for portable gantry crane procurement and product planning. Automation and Industry 4.0 practices are accelerating the adoption of lifting equipment with enhanced precision, control, and safety features. As material handling operations seek repeatable throughput and reduced manual variability, demand is tilting toward cranes that can interface cleanly with broader site systems and support consistent lift performance. This is not an automation trend limited to large fixed installations; portable and mobile gantry cranes are increasingly expected to deliver smarter control, clearer load visibility, and safer operation in dynamic environments.
At the same time, input cost and trade policy dynamics are reshaping the economics of supply. The increase in US Section 232 steel tariffs from 25 percent to 50 percent effective June 2025 has altered raw material costs for domestic crane manufacturers, adding pressure to cost structures that rely on steel-intensive fabrication. For procurement leaders, this underscores the importance of sourcing scenarios, lead-time resilience, and specification flexibility. For manufacturers, it raises the stakes around material mix, regional production strategy, and value-based pricing. Steel price stability in the United States through 2025, alongside moderate upward movement in Chinese benchmark pricing in 2026, suggests that cost volatility will remain a monitoring priority even as the broader trend stays contained.
These forces combine to create a market where the winning strategy is rarely about price alone. It is about aligning crane specifications with operational realities, anticipating regulatory and input-cost shifts, and selecting partners who can support the full lifecycle of the equipment. In that context, short-term procurement decisions carry long-term consequences for uptime, safety, and total cost of ownership.
What the Full Study Delivers for 2026 Decision-Making
The complete PW Consulting study translates these macro signals into an operational intelligence package built for executive, product, and commercial teams. It provides a validated historical baseline and a forward forecast that can anchor budget planning, capacity decisions, and market-entry evaluations. It dissects the segmentation structure in a way that helps organizations identify which material, capacity, end-user, and regional profiles are most relevant to their position, without forcing a one-size-fits-all interpretation. It maps the competitive field with company-level profiling, recent activity, and development signals that reveal where capabilities are being reinforced and where differentiation is likely to intensify.
Equally important, the study integrates the environment in which these companies and customers operate. Raw material trends, trade policy developments, and automation-driven demand shifts are woven into the analysis so that readers can connect market numbers to actionable levers. The result is a framework for evaluating not just where the market is going, but how to respond in a way that protects margins, improves specification accuracy, and reduces exposure to cost or compliance surprises.
For organizations making 2026 decisions—whether selecting lifting equipment for a new facility, refining a product roadmap, assessing supplier portfolios, or prioritizing regional expansion—the study offers the granularity required to move from directional confidence to precise planning. It is structured to support scenario comparison, vendor evaluation, and demand forecasting with a level of detail that general market summaries cannot provide.
Why This Intelligence Matters Now
The portable gantry crane market is expanding at a steady, structural pace, but the value at stake is determined by how well organizations interpret segmentation, cost drivers, and competitive dynamics. A mid-single-digit growth trajectory can still produce markedly different outcomes depending on where a company plays and how it configures its offering or procurement strategy. In a fragmented landscape with evolving material costs and rising expectations for precision and safety, the organizations that outperform will be those that treat market intelligence as a decision tool rather than a benchmark.
This preview has outlined the scale of the opportunity, the segmentation forces that matter, the competitive logic now in play, and the external variables that will influence costs and demand. The full report goes further, delivering the detailed segmentation read, company-level context, and forward-looking scenario structure needed to convert insight into action. For leaders who need to align capital, product, and procurement decisions with where the market is actually heading, the complete study provides the intelligence foundation to do so with confidence.
For detailed analysis of this topic, please visit the official page: Worldwide Portable Gantry Crane Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Aviation Fuel Storage Tank Market to Hit $2,593.54M by 2032 at 5.19% CAGR
By pmarketresearch, 2026-09-17
Strategic Imperatives in the Worldwide Aviation Fuel Storage Tank Market: A 2026 Outlook
The global aviation industry stands at a critical juncture where infrastructure resilience meets the urgent demand for sustainable operations. As air travel recovers and evolves, the backbone of refueling operations—the storage tank infrastructure—requires unprecedented attention. For stakeholders navigating the complex landscape of fuel storage, understanding the macroeconomic trajectory and structural shifts within the market is no longer optional; it is a strategic necessity. Our latest comprehensive analysis of the Worldwide Aviation Fuel Storage Tank Market offers a detailed roadmap for navigating the period from 2026 through 2032, providing the intelligence needed to secure operational continuity and capitalize on emerging growth vectors.
This market research is designed to equip decision-makers with a granular understanding of value chains, competitive pressures, and regulatory headwinds. By synthesizing historical performance data with forward-looking projections, we illuminate the pathways that will define market leadership in the coming decade. The following insights summarize the strategic value embedded within this report, highlighting why immediate engagement with these findings is crucial for capital allocation and risk management.
Market Trajectory and Growth Dynamics
The economic fundamentals of the aviation fuel storage sector demonstrate robust resilience and steady expansion. Based on historical analysis spanning from 2020 to 2025, the market has exhibited consistent upward momentum, transitioning from a revenue valuation of approximately 1,415 million USD to over 1,820 million USD in the base year. This growth trajectory sets a strong foundation for the forecast period covering 2026 to 2032.
Historical Performance and Future Projections
The data indicates a mature yet accelerating market environment. Starting from 2020, the market has navigated through various global disruptions to establish a stable growth pattern. By 2025, the market size reached 1,820 million USD, reflecting a compounded increase over the preceding five years. Looking ahead, the forecast period projects a steady climb, with the market expected to breach the 2 billion USD threshold by 2027 and continue ascending toward 2,593.54 million USD by 2032.
The compound annual growth rate (CAGR) for the forecast period is estimated at 5.19 percent. This rate underscores a healthy demand environment driven by infrastructure upgrades, safety compliance mandates, and the expansion of airport capacities globally. For investors and industry participants, this growth rate signals a stable return profile, provided that entry strategies are aligned with the specific segments driving this expansion. The transition from 2026 to 2032 represents a period where capital expenditure on storage infrastructure will likely outpace general inflation, driven by the need for modernization and regulatory adherence.
Structural Segmentation and Value Distribution
Understanding where value resides within the market is essential for targeted investment. Our report dissects the market into critical operational dimensions, revealing how different segments contribute to the overall revenue pool. While specific percentage breakdowns are reserved for the full dataset, the absolute revenue contributions highlight the dominant areas of activity.
Worldwide Aviation Fuel Storage Tank Market
Regional Revenue Contributions
Geographically, the market is distributed across key industrial hubs. Asia Pacific represents a significant portion of the revenue landscape, contributing over 630 million USD, reflecting the region's aggressive airport expansion and increasing air traffic density. North America follows closely with contributions exceeding 511 million USD, driven by stringent safety regulations and ongoing mid-life infrastructure upgrades at legacy hubs. Europe accounts for over 424 million USD, while the Middle East & Africa and Latin America contribute 163.47 million USD and 90.37 million USD respectively. These figures illustrate the global nature of the demand, though concentration varies significantly based on aviation penetration and fuel logistics requirements.
Tank Type and Installation Preferences
The choice of storage technology remains a pivotal decision for airport planners. The market sees substantial activity in Fixed Roof Tanks, generating approximately 982.48 million USD, which indicates a strong preference for cost-effective storage solutions for stable fuel inventories. Floating Roof Tanks contribute around 837.52 million USD, often selected for specific environmental compliance needs or volatile inventory management.
Installation methodology further delineates the market structure. Above-Ground Storage Tanks (AST) dominate the landscape with a valuation near 1,344.06 million USD, favored for ease of inspection and compliance with modern safety standards. Underground Storage Tanks (UST) account for 475.94 million USD, typically utilized in specific spatial constraints or environmental protection scenarios. The balance between AST and UST often depends on local zoning laws and the specific risk profile of the storage location.
End-User Segmentation
Commercial Airports remain the primary revenue driver, engaging storage solutions valued at approximately 1,294.39 million USD. This dominance is expected given the volume requirements of commercial jet operations. Military Airbases follow with a contribution of 434.74 million USD, where strategic reserve capabilities and ruggedized storage solutions are prioritized. General Aviation, while smaller in scale at 90.87 million USD, represents a niche but high-growth segment, particularly with the rise of private aviation and regional connectivity initiatives.
Competitive Landscape and Strategic Positioning
The market structure is characterized by a moderate level of concentration, where scale and specialization allow key players to secure significant market share. The top three companies hold a combined market share of 28.5 percent, while the top five extend this to 42.3 percent. This indicates a competitive environment where the top tier commands substantial influence, yet a long tail of specialized manufacturers competes on customization, speed, and regional compliance.
Key Industry Participants
Several established players define the competitive baseline, each bringing distinct capabilities to the market:
- Ace Tank and Fueling Equipment: Based in the United States, this firm specializes in customized, fully-equipped aboveground storage tanks tailored specifically for airport fuel distribution networks, emphasizing turnkey integration.
- Tate Metalworks: Also US-based, Tate focuses on field-erected solutions using stainless steel, duplex steel, and carbon steel. Their engineering focus is increasingly directed toward sustainable aviation fuel (SAF) compatibility alongside conventional fuel requirements.
- AGI Westeel: Operating out of Canada, AGI Westeel provides shop-fabricated aboveground steel aviation tanks designed to meet rigorous Canadian Aviation Regulations, ensuring safe storage protocols are met from the outset.
- Center Enamel: A China-based specialist, Shijiazhuang Zhengzhong Technology Co., Ltd., focuses on corrosion-resistant stainless steel tanks with aluminum dome roofs. Their systems are optimized for Jet A-1 fuel purity and high-volume applications, recently emphasizing ultra-cleanliness and modular containment.
- Unity Fuel Solutions: This US manufacturer emphasizes quality and cleanliness, producing double-walled aboveground storage tanks for Jet A-1 and Avgas, catering to airports with strict fuel handling standards.
- Fuelchief: From New Zealand, Fuelchief supplies the SuperVault Aviation range, offering 4-hour fire-rated flammable storage tanks suitable for everything from helipads to full jet operations, addressing critical safety ratings.
- Avioneco: Based in Poland, this company produces double-walled steel tanks in both mobile and stationary configurations. Their solutions cover AVGAS, JET-A1, and MOGAS, providing flexibility for airfields with varying refueling needs.
- SEI Industries: A Canadian manufacturer known for the Bulk Aviation Transport Tank (BATT), a collapsible tank approved for air transport of aviation fuel (Class 3 UN 1863), addressing logistics flexibility.
- Western Global: Located in the United States, they manufacture transportable and static fuel storage tanks, including models certified for aviation fueling applications, bridging the gap between mobility and fixed infrastructure.
- Varec: Also US-based, Varec provides end-to-end fuel management solutions, including tank farm automation and level measurement for storage tanks at major airports, adding a technology layer to physical storage.
- eN-TANK Sp. z o.o. sp.k.: A Polish entity specializing in steel double-wall tanks for petroleum products including aviation fuels since 2002, leveraging long-term experience in double-wall integrity.
- CZ Ltd: A UK supplier with over 60 years of experience, providing aviation fuel storage tanks and systems for Jet A1 and Avgas, representing a legacy of design and manufacture expertise.
Recent Industry Developments and Project Intelligence
Real-time intelligence on project commissioning and planning provides early signals of demand shifts. Our research team tracks these milestones to validate market momentum.
Aircraft Fuel Tanks Market
- Jefferson County Airport (February 2026): The completion of a 12,000-gallon unleaded aviation fuel bulk storage tank installation was reported as part of the AIP-70 Unleaded Fuel Tank Project. This initiative supports wholesale deliveries of Swift Fuels UL94, signaling a tangible shift toward unleaded alternatives in general aviation infrastructure.
- Center Enamel (November 2025): The release of advanced stainless steel Jet A-1 fuel storage tank systems emphasized ultra-cleanliness and zero-tolerance quality control. This product certification highlights the industry's move toward modular containment optimized for global aviation logistics and stricter purity standards.
- Sonoma County Airport (October 2025): The Board approved an engineering and budget study for a new aircraft fuel storage facility. The objective is to more than double existing storage capacity, indicating significant public investment in regional airport infrastructure to accommodate future traffic growth.
Regulatory and Material Market Context
Strategic planning cannot occur in a vacuum; it must account for the raw material environment and the regulatory framework governing storage safety and sustainability.
Raw Material Cost Dynamics
The cost of steel, a primary input for tank manufacturing, influences project budgets and margins. As of mid-2025, U.S. Midwest hot-rolled coil steel prices stabilized in the low to mid $800s per short ton, with futures indicating range-bound trading into early 2026. This stability offers a predictable input cost environment for North American projects. Meanwhile, Chinese steel rebar benchmark prices stood at 3,103 CNY per tonne as of April 2026. These divergent regional price points influence the competitive positioning of manufacturers sourcing materials globally, affecting the landed cost of imported tank systems versus locally fabricated ones.
Regulatory Standards and Compliance
Safety and environmental performance are governed by evolving standards. The publication of API Standard 650, 13th Edition for Welded Tanks for Oil Storage, enhances safety and sustainability requirements applicable to aviation fuel applications. Compliance with this standard is becoming a baseline expectation for new installations and major retrofits.
In the United States, federal policy is also shaping the economic viability of fuel storage associated with emerging fuel types. The Section 45Z Clean Fuel Production Credit provides applicable amounts ranging from $0.20 to $1.00 per gallon for non-SAF transportation fuels produced after December 31, 2025, with specific rules for domestically sourced feedstocks from the US, Mexico, or Canada. While this credit targets production, it indirectly incentivizes the storage and distribution infrastructure required to handle these fuels, stimulating demand for compliant storage solutions that can handle varied fuel chemistries.
Furthermore, physical safety standards remain paramount. Storage tanks for aviation fuel must comply with UL 142 for steel aboveground tanks for flammable and combustible liquids or UL 2085 for protected tanks. These standards are referenced in FAA and DOI aviation fuel management guidelines, making certification a prerequisite for operational legality in many jurisdictions. Ignoring these compliance pathways exposes operators to significant liability and operational risk.
Strategic Recommendations for 2026 and Beyond
For executives and investors, the data suggests several actionable strategic postures. First, the growth trajectory supports continued investment in storage capacity, particularly in regions showing high absolute revenue contribution like Asia Pacific and North America. However, success depends on navigating the complexity of tank types and installation methods. The dominance of Above-Ground Storage Tanks suggests that procurement strategies should prioritize AST suppliers with strong safety certifications and modular capabilities.
Second, the competitive landscape indicates that partnerships with specialized manufacturers who offer end-to-end management, such as tank farm automation, may provide a competitive edge. As seen with providers like Varec, integrating technology with physical storage enhances operational efficiency and reduces leakage risks. Third, the regulatory environment regarding unleaded fuels and SAF compatibility requires forward-looking procurement. Projects like the Jefferson County Airport installation demonstrate that early adoption of infrastructure capable of handling unleaded blends positions operators ahead of regulatory curves and fuel supply shifts.
Finally, supply chain resilience is critical given the variations in global steel pricing. Locking in supply agreements or utilizing local fabrication partners in stable price regions can mitigate margin erosion. The market is not merely about buying tanks; it is about securing a compliant, safe, and efficient fuel supply chain that can withstand the operational demands of the next decade.
Conclusion
The Worldwide Aviation Fuel Storage Tank Market offers a landscape of steady growth and evolving technical requirements. With a projected market size approaching 2.6 billion USD by 2032 and a CAGR of 5.19 percent, the opportunity for strategic positioning is substantial. However, realizing this value requires deep insight into the segmentation dynamics, competitive capabilities, and regulatory constraints that define the sector.
This article provides a high-level overview of the market intelligence available. To access the full granularity of data—including exact segment percentages, detailed regional growth matrices, comprehensive company profiling, and risk analysis frameworks—we invite you to explore the complete Worldwide Aviation Fuel Storage Tank Market research report. Equip your organization with the definitive intelligence needed to navigate the complexities of aviation fuel infrastructure in 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Worldwide Aviation Fuel Storage Tank Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Medical Network Isolators Market to Hit $300.81M by 2032, 6.45% CAGR
By pmarketresearch, 2026-09-17
Strategic Intelligence for the Connected Healthcare Era: Inside the Worldwide Medical Network Isolators Market
The modern hospital is no longer a collection of standalone devices but a densely interconnected ecosystem where patient data, imaging streams, and life-support systems communicate across Ethernet backbones in real time. As this connectivity deepens, so does the imperative to guarantee galvanic separation, limit leakage currents, and protect vulnerable medical equipment from potential differences that travel along data cables. Our latest worldwide market study on medical network isolators maps this evolving landscape with the precision that procurement leaders, R&D directors, and regulatory affairs teams require to make confident investment decisions throughout 2026 and beyond.
The research anchors its perspective in a five-year historical window spanning 2020 through 2025, then projects forward across a seven-year forecast horizon from 2026 to 2032. This structure allows decision-makers to ground strategic plans in observed trajectory rather than speculative optimism. The overall market size has expanded from approximately 145.2 million USD in 2020 to 194.2 million USD in the 2025 base year, reflecting sustained demand driven by hospital modernization programs, tighter patient-safety expectations, and the proliferation of networked diagnostic and therapeutic equipment. The forecast period continues this upward path, reaching an estimated 214.24 million USD in 2026 and climbing toward 300.81 million USD by 2032. Over the full forecast window, the compound annual growth rate settles at 6.45 percent, a figure that signals steady, structurally supported expansion rather than a temporary cycle.
Worldwide Medical Network Isolators Market
For executives evaluating capital allocation, product roadmaps, or regional entry strategies, these macro indicators serve as a calibration point. Growth is not uniform across every segment, geography, or product architecture, and that unevenness is precisely where strategic advantage is created. The study deliberately avoids flattening the market into a single narrative. Instead, it dissects the demand structure so that leadership teams can identify which subsegments warrant deeper investment, which supply constraints demand contingency planning, and where regulatory momentum is reshaping procurement requirements.
Digital Isolators Market
Volume and Share Distribution Across Segments
Understanding where revenue concentrates is essential for prioritizing commercial efforts and engineering resources. The report breaks down the market across three dimensions that matter most to buyers and suppliers: geography, product type, and clinical application. In 2025, regional revenue distribution shows a clear hierarchy that mirrors the maturity of healthcare infrastructure and the pace of networked device adoption. North America accounts for 73.64 million USD of total revenue, reflecting dense hospital networks, robust capital equipment cycles, and early adoption of networked imaging and navigation systems. Europe follows with 53.53 million USD, supported by established medical device regulations and continued retrofitting of legacy facilities. Asia Pacific contributes 48.52 million USD, a segment shaped by rapidly expanding diagnostic capacity, growing private hospital chains, and increasing import and localization activity. Latin America records 9.99 million USD, while the Middle East and Africa account for 8.52 million USD, both regions representing high-potential but structurally different demand environments that require distinct go-to-market approaches.
The type segmentation reveals how engineering preferences differ across installation contexts. External network isolators represent the largest value pool at 131.8 million USD, reflecting their role as field-installable protection modules for existing Ethernet infrastructure in patient care vicinities. Wall-mounted network isolators contribute 41.04 million USD, capturing demand from fixed installation scenarios where space, compliance, and serviceability are paramount. Built-in OEM modules account for 21.36 million USD, a smaller but strategically significant pool tied to equipment manufacturers integrating isolation at the design stage rather than relying on post-market add-ons. These distinctions matter because each type carries different certification burdens, integration timelines, and procurement cycles.
Application segmentation further clarifies where demand originates on the clinical floor. Hospitals and clinics generate 111.23 million USD, the dominant environment for network isolation given the breadth of connected devices and the strictness of safety requirements in patient-adjacent areas. Diagnostic imaging centers contribute 51.56 million USD, reflecting the high data-throughput needs of imaging networks and the sensitivity of diagnostic equipment to electrical disturbances. Surgical suites account for 31.41 million USD, a specialized segment where isolation is often evaluated not only for safety but also for operational continuity during critical procedures. Together, these segments illustrate a market in which isolation is no longer an accessory but a design requirement tied to device certification, facility compliance, and risk management.
Competitive Dynamics and Supplier Positioning
The market is not fragmented in the traditional sense, but neither is it dominated by a single supplier architecture. The report places the competitive landscape in context by examining the players who shape product standards, certification practices, and purchasing expectations. Baaske Medical GmbH stands out for its TÜV-certified medical network isolators, including the MI 1005 series and the MI 2005 designed for 2.5 GBit/s throughput. Its product line is engineered to comply with IEC 60601-1 Edition 3.2, emphasizing galvanic isolation in patient care vicinities and protection against leakage currents, overvoltages, and electrostatic discharge for Ethernet connections in hospitals and medical devices. For procurement teams, this level of certification specificity matters because it reduces integration risk and shortens compliance verification cycles.
EMO Systems GmbH, operating under the EMOSAFE brand, provides network isolators such as the EN-1005+ and EN-70 series for medical applications. Its offerings are designed to conform to IEC 60601-1 with high dielectric strength, reaching up to 5 kV AC and 8.5 kV DC, alongside UL recognition and support for Gigabit-plus Ethernet. The emphasis on galvanic separation and patient safety in medical electrical devices positions EMOSAFE as a supplier aligned with environments where electrical robustness and regulatory recognition are equally important. Eaton, through its Tripp Lite series, contributes hospital-grade medical Ethernet network isolators such as the N234-MI-1005, a Cat6 RJ45 solution compliant with IEC 60601-1 and UL 60601-1. Its value proposition centers on isolating medical equipment from leakage currents on Ethernet networks in patient care vicinities, a concern that remains highly relevant as hospitals connect devices to non-medical infrastructure. Phoenix Contact rounds out the competitive field with passive network isolators such as the FL ISOLATOR 100-RJ/SC, providing up to 4 kV protection against potential differences. Its approach is particularly relevant for integration scenarios in medical and industrial settings where galvanic isolation must be achieved without adding external power dependencies.
The study also situates these supplier profiles within broader competitive metrics. Market concentration data shows a CR3 of 38.5 percent and a CR5 of 52.3 percent, indicating that while leading players hold meaningful share, the market still leaves substantial room for specialized suppliers, regional distributors, and OEM-embedded solutions. This structure has practical implications for sourcing strategy. Buyers can leverage multi-supplier validation to manage supply continuity, while suppliers must differentiate on certification breadth, throughput capability, installation form factor, and post-sales technical support rather than price alone.
Regulatory Pressure as a Market Accelerator
One of the most consequential themes in the research is the way regulatory requirements are converting network isolation from a desirable feature into a procurement mandate. Medical network isolators for Ethernet connections in patient care vicinities must comply with IEC 60601-1:2005/AMD1:2012/AMD2:2020, Edition 3.2, which defines reinforced insulation at the 2 MOPP level and requires galvanic separation to limit leakage currents. This is not a marginal specification; it shapes product architecture, validation documentation, and the way hospitals evaluate components during facility upgrades or equipment refreshes. Suppliers that align their offerings with these requirements gain a compliance shortcut, while buyers gain a clearer basis for specification writing and audit readiness.
The regulatory environment also interacts with certification ecosystems beyond the IEC baseline. EMOSAFE network isolators conform to IEC 60601-1 requirements for SIP and SOP interfaces on medical electrical equipment, with additional UL recognition as components for safe operation in medical environments. Eaton Tripp Lite medical Ethernet isolators such as the N234-MI-1005 comply with IEC 60601-1 and IEC 60601-1-2 EMC standards specifically for network connections between medical devices and non-medical Ethernet infrastructure in patient vicinities. These overlapping standards create a compliance matrix that procurement teams must navigate carefully, and the report maps that matrix so that readers can see where certification convergence reduces friction and where gaps still require custom validation.
Passive medical network isolators add another dimension to the regulatory discussion. By providing galvanic isolation without external power, they interrupt all conductive connections, including conductors and shielding, preventing the equalization of potential differences via data cables in healthcare settings. This passive approach appeals in scenarios where adding power-dependent components would complicate installation or introduce new failure modes. At the same time, it places greater importance on component quality, dielectric performance, and long-term reliability documentation, all of which are addressed in the study through supplier-level technical analysis.
Operational Reliability and the Cost of Downtime
Market growth is not only a function of regulation and device proliferation; it is also tied to the operational consequences of communication failure. Networked medical systems depend on stable Ethernet links for data integrity, device coordination, and clinical workflow continuity. When communication anomalies appear, isolation components can become part of troubleshooting workflows. A recent example from April 2025 illustrates this dynamic: during a malfunction analysis involving Medtronic Navigation, Inc., a network isolator component was replaced while troubleshooting a communication failure in a navigation system. Post-analysis showed no fault confirmed in the returned isolator. While the outcome did not attribute the failure to the isolator itself, the event highlights how isolation components are now embedded in the operational accountability chain for connected medical equipment.
For healthcare providers and device manufacturers, this has strategic implications. It reinforces the need to specify isolation components that are not only compliant but also traceable, serviceable, and supported by clear failure-mode documentation. It also underscores the value of supplier partnerships that extend beyond initial purchase, including technical support, replacement logistics, and compatibility assurance across network architectures. The report examines these operational realities in depth, showing how reliability expectations are reshaping both product design and procurement criteria.
What the Study Delivers Beyond the Top-Line Numbers
The headline market size and growth rate provide orientation, but the real strategic value of the study lies in its operational detail. The report moves beyond summary statistics to deliver content that can be used immediately in planning sessions, specification reviews, and investment committees. It covers the historical trajectory from 2020 through 2025, then projects the market across the 2026 to 2032 forecast period with a structured methodology that connects demand drivers to segment outcomes. It evaluates how type, application, and regional dynamics interact rather than treating them as isolated lenses, which is essential because real-world purchasing decisions rarely follow a single segmentation line.
The study also includes competitive profiling that goes past corporate descriptions. It examines how leading suppliers position themselves against regulatory requirements, throughput expectations, installation preferences, and certification ecosystems. This allows readers to compare not only what companies offer but why they matter in specific procurement contexts. In addition, the research integrates regulatory developments, technical conformity details, and operational case context so that decision-makers can see how compliance, performance, and reliability intersect in day-to-day purchasing and engineering choices.
For teams planning 2026 initiatives, this level of detail supports several practical outcomes. It helps identify where specification requirements are tightening and where procurement cycles may lengthen or shorten. It highlights which product architectures are gaining traction in specific installation environments, and where built-in OEM integration may shift demand away from field-installable add-ons. It also provides a framework for evaluating supplier resilience, including certification coverage, throughput range, and the ability to support both passive and powered isolation strategies where needed.
How to Use This Intelligence in 2026 Planning
The worldwide medical network isolators market is entering a phase in which growth is supported by structural factors rather than short-term cycles. Hospital connectivity continues to expand, regulatory expectations for patient-adjacent Ethernet infrastructure remain stringent, and device manufacturers are increasingly designing isolation into products rather than treating it as an afterthought. In that environment, the organizations that make the best decisions will be those that can connect top-line market direction to segment-level reality, supplier capability, and compliance requirements.
This study is built to support that decision-making. It gives leadership teams a defensible view of where the market has been, where it is headed, and which variables will matter most as 2026 plans are finalized. It also preserves the deeper numerical and supplier-level intelligence that procurement, engineering, and strategy teams need to act with precision. To access the full segmentation analysis, regional breakdowns, type and application detail, and complete competitive and regulatory mapping, readers are invited to explore the full research on the source page. The complete report transforms these high-level insights into actionable intelligence, allowing organizations to move from market awareness to informed execution.
For detailed analysis of this topic, please visit the official page: Worldwide Medical Network Isolators Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Remicade Market to Reach USD 4,950M in 2025, Shrinking at -4.52% CAGR Through 2032
By pmarketresearch, 2026-09-17
Navigating the Decline: Strategic Imperatives in the Global Remicade (Infliximab) Drug Market Through 2032
The global therapeutic landscape for monoclonal antibodies has long been defined by blockbuster agents that reshaped standard care across multiple autoimmune indications. Among these, Remicade (infliximab) stands as a foundational reference product, yet its commercial trajectory has entered a period of structural contraction. As biosimilar penetration deepens and originator revenue streams compress, pharmaceutical executives, market access leaders, and investment strategists require a granular, forward-looking analysis to navigate the coming years with confidence. Our newly released Worldwide Remicade (infliximab) Drug Market research delivers precisely that intelligence, synthesizing historical performance, competitive positioning, and multi-year forecasts into a decision-ready framework.
This executive overview outlines why this study is an essential strategic asset for 2026 planning cycles. It highlights the macroeconomic contours of the market, maps the evolving competitive architecture, details the operational contents of the full report, and demonstrates how procurement, pricing, and pipeline teams can translate these insights into measurable advantage. Crucially, the complete dataset—covering regional revenue trajectories, indication-level demand shifts, product-type dynamics, and company-specific market share estimates—resides within the full publication, accessible through our research portal.
The Macro Trajectory: A Contraction Shaped by Biosimilar Maturity and Payer Pressure
Understanding where the Remicade market is heading begins with acknowledging its historical arc. Over the 2020–2025 period, global revenue for infliximab products has followed a consistent downward slope, reflecting the irreversible shift from a single originator-dominated ecosystem to a fragmented, price-competitive biosimilar marketplace. Our model places the 2025 baseline at approximately $4,950 million, down from roughly $8,240 million at the start of the historical window. This compression is not a transient cycle but a structural realignment driven by patent expirations, tender-based procurement, and deliberate payer policies that reward lower-cost alternatives without compromising clinical outcomes.
Looking forward, the forecast period spanning 2026 through 2032 projects a continued contraction, with the compound annual growth rate indicating a decline of roughly 4.52 percent across the analysis horizon. By 2032, total market value is projected to settle near the $3.58 billion mark. Executives should interpret this trajectory not as market failure but as market maturation. The value pool is being redistributed: originators retain premium positioning in specific channels and patient segments, while biosimilar manufacturers capture volume through aggressive pricing, formulary placements, and emerging-market access programs.
Several structural forces reinforce this path. Cold-chain logistics and biologic manufacturing complexity continue to dominate cost-of-goods profiles, constraining the pace at which new entrants can scale without sacrificing quality or margin. Simultaneously, reimbursement architectures across major healthcare systems increasingly treat infliximab biosimilars as interchangeable options within treatment algorithms, accelerating utilization in rheumatoid arthritis, Crohn’s disease, ulcerative colitis, psoriatic arthritis and psoriasis, and ankylosing spondylitis. The strategic question for 2026 is no longer whether biosimilar share will grow, but how companies will defend or capture value as the remaining originator revenue erodes and biosimilar price competition intensifies.
Worldwide Remicade (infliximab) Drug Market
Competitive Architecture: Coexistence, Substitution, and Strategic Differentiation
The competitive landscape for infliximab is unusually dense, spanning the originator firm, a cohort of established biosimilar developers, and a second wave of emerging-market suppliers targeting price-sensitive channels. This fragmentation creates a multilayered battlefield where commercial strategy must be tailored to geography, formulation, distribution model, and payer relationship rather than applied uniformly.
Janssen Biotech, Inc. (Johnson & Johnson) remains the anchor of the reference-product ecosystem. As the originator of intravenous Remicade, the company continues active global commercialization, including promotion of an unbranded infliximab variant in select contexts. Its Q1 2026 worldwide sales reporting of $422 million illustrates both the resilience of the brand in remaining formulary positions and the steady headwind from biosimilar substitution and patient-mix shifts. For strategists, Janssen’s trajectory signals that originator value is increasingly tied to channel control, patient support programs, and relationship-driven procurement rather than volume dominance.
On the biosimilar side, Celltrion, Inc. has emerged as a formulation innovator. The company markets Remsima (CT-P13) IV biosimilar and Zymfentra (infliximab-dyyb) subcutaneous formulation, while also offering the world’s first liquid IV infliximab formulation. A recent European Commission marketing authorization for the Remsima IV liquid across all prior indications—including rheumatoid arthritis, Crohn’s disease, and ulcerative colitis—represents a meaningful operational advantage by reducing preparation complexity and potentially improving infusion-center efficiency. This kind of formulation-level differentiation is exactly the type of lever that can shift purchasing decisions in hospital and institutional settings.
Worldwide Belimumab Market
Pfizer Inc. continues to compete through Inflectra (infliximab-dyyb) and Ixifi (infliximab-qbtx) across multiple markets, leveraging broad commercial infrastructure. Samsung Bioepis Co., Ltd., in partnership with Organon & Co., commercializes Renflexis (infliximab-abda) in the United States and Flixabi (SB2) in Europe, demonstrating how co-commercialization and licensee relationships can extend reach without duplicating fixed costs. Amgen Inc. markets Avsola (infliximab-axxq), while Sandoz Group AG (a Novartis division) offers Zessly (infliximab) biosimilar in Europe and other regions. Viatris Inc. remains active through its legacy Mylan portfolio and select partnerships, and a broader tier of suppliers—including Biocon Biologics, Dr. Reddy’s Laboratories, Teva Pharmaceutical Industries, Fresenius Kabi AG, STADA Arzneimittel AG, Intas Pharmaceuticals, and Zydus Lifesciences—operates with a deliberate focus on emerging markets, tender-based supply, and cost-sensitive regions.
This architecture matters because pricing, access, and supply reliability are no longer determined by a single reference price. Instead, procurement teams evaluate a matrix of product specifications, cold-chain readiness, batch consistency, regulatory status by territory, and contractual flexibility. The full report dissects these dynamics company by company, enabling buyers and competitors to benchmark positioning with precision.
Structural Drivers: Regulation, Reimbursement, and Manufacturing Realities
Three interlocking dynamics define the operating environment for infliximab products and shape every strategic choice made in 2026.
First, regulatory milestones have already unlocked the biosimilar market. Remicade patents expired in the European Union in February 2015 and in the United States in September 2018, enabling multiple biosimilar entries. The FDA has since approved a sequence of infliximab biosimilars, including Inflectra (2016), Renflexis (2017), Ixifi (2017), and Avsola (2019), with continued utilization across autoimmune indications. These approvals are not historical footnotes; they are the foundation of today’s market structure and the reason why formulary decisions, interchangeability designations, and national procurement frameworks now operate under a biosimilar-friendly paradigm.
Second, reimbursement and pricing behavior are actively redistributing the value pool. Infliximab biosimilars have demonstrated average price discounts ranging from roughly 19 to 59 percent versus pre-biosimilar Remicade list prices, generating measurable cost savings for payers and healthcare systems. In the US, biosimilar market share reached approximately 48 percent by Q3 2024 and continued incremental gains into 2025, driven by payer preferences and lower average selling prices. Early 2025 data suggest biosimilars captured an estimated 48 to 53 percent share in the US, with gradual further uptake expected as tenders renew and formulary placements consolidate. For commercial teams, the implication is clear: list-price competition is being replaced by negotiated, volume-linked, and channel-specific pricing models, and success depends on contractual design as much as product quality.
Third, manufacturing and supply-chain economics remain a binding constraint. Biologic manufacturing complexity, including cold-chain logistics for monoclonal antibodies, continues to be a primary cost driver alongside active pharmaceutical ingredient production. This reality influences everything from tender competitiveness to risk of supply disruption and from geographic expansion sequencing to margin sustainability. Companies that can demonstrate reliable cold-chain capacity, consistent batch release, and defensible cost structures will command disproportionate leverage in institutional and government procurement contexts.
Inside the Report: Operational Content Designed for 2026 Decision-Making
Our Worldwide Remicade (infliximab) Drug Market study is structured to convert market complexity into actionable plans. Rather than offering high-level commentary, the report delivers operational content that procurement, pricing, market access, and business development teams can apply directly during planning cycles. The full publication includes:
- A comprehensive historical analysis covering the 2020–2025 window, establishing the baseline for trend interpretation and benchmarking current performance against prior-year dynamics.
- A forecast model extending through 2032 that quantifies the expected revenue trajectory at the total market level and isolates the drivers behind the projected decline, including biosimilar share gains, pricing compression, and indication-level demand evolution.
- Detailed segmentation analysis by region, product type, and indication, enabling readers to understand where value is concentrating, where substitution is accelerating, and which therapeutic areas retain the strongest pricing resilience.
- A competitive benchmarking module that evaluates the positioning, formulation strategies, geographic footprints, and commercial models of the key players shaping the infliximab ecosystem.
- Thematic analysis of regulatory timelines, reimbursement behavior, price discount ranges, and manufacturing and cold-chain constraints, integrated into a cohesive view of market dynamics rather than treated as isolated facts.
- Identification of recent developments and their strategic implications, including formulation-level approvals and quarterly sales signals that indicate how the competitive balance is shifting in real time.
Each section is designed to support a specific decision type. Procurement leaders can use the segmentation and pricing themes to structure tender evaluations and negotiate volume commitments. Pricing and market access teams can leverage the discount-range analysis and payer-behavior insights to model formulary positioning and contract architectures. Business development and competitive intelligence teams can use the company-level profiling and strategic context to assess partnership opportunities, geographic entry sequencing, and formulation-driven differentiation. The complete version of the report presents the underlying figures, regional and indication-level breakdowns, and company-specific estimates in full, ensuring that readers can validate assumptions and build internal models with confidence.
Strategic Implications for 2026 Planning Cycles
For executives entering 2026, the Remicade market demands a shift from volume-defensive thinking to value-positioning discipline. Several implications stand out.
Originator and reference-product teams must prioritize channel control, patient support, and relationship-based procurement to sustain relevance as biosimilar volume grows. The focus should be on protecting high-value segments, optimizing unbranded or supportive offerings, and aligning sales resources with the channels where clinical integration and service quality still differentiate the reference product.
Biosimilar developers should differentiate through formulation convenience, supply reliability, and contractual flexibility rather than price alone. The recent European authorization of a liquid IV infliximab formulation highlights how reduced preparation burden can resonate with infusion centers and hospital pharmacy operations. Where price competition is intense, margin defense depends on manufacturing efficiency, cold-chain capability, and the ability to secure recurring volume through tenders and institutional contracts.
Payers, procurement organizations, and healthcare systems should treat infliximab as a case study in managed substitution. With biosimilar discounts materially below pre-biosimilar list prices and utilization expanding across core autoimmune indications, the opportunity lies in structuring contracts that lock in savings while preserving supply continuity and clinical equivalence. Forecasting models that fail to account for incremental biosimilar uptake, indication-level demand patterns, and regional procurement cycles will overestimate remaining originator revenue and underestimate total cost savings.
Investors and market analysts should frame the market as a redistribution story rather than a collapse. Revenue is migrating from a single originator to a diverse set of biosimilar suppliers, with regional variation in pace and depth. Concentration among top players remains significant, underscoring the importance of understanding which firms control which channels and how partnership arrangements shape commercial reach. The full report quantifies these concentration dynamics and regional splits so that stakeholders can map risk and opportunity with precision.
Conclusion: Accessing the Full Intelligence
The Worldwide Remicade (infliximab) Drug Market is undergoing a measured but unmistakable contraction, shaped by mature biosimilar competition, aggressive payer cost management, and the enduring complexity of biologic manufacturing and distribution. For organizations operating in this space, the strategic imperative in 2026 is to replace assumptions with evidence: to know where value is eroding, where it is being captured, and which operational levers will determine outcomes over the 2026–2032 horizon.
This executive preview has outlined the macro trajectory, the competitive architecture, the structural drivers, and the operational content embedded in our research. The complete market size figures, regional and indication-level breakdowns, product-type dynamics, company-specific estimates, and concentration metrics are available in the full study. Readers seeking the granular intelligence required to build pricing models, structure procurement strategies, or assess competitive positioning can access the complete dataset and analysis through our research platform, where the full report provides the depth necessary to support confident, evidence-based decision-making.
For detailed analysis of this topic, please visit the official page: Worldwide Remicade (infliximab) Drug Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide FRP Cooling Tower Market to Hit $1,323.23M in 2025, Grow at 5.48% CAGR to 2032
By pmarketresearch, 2026-09-17
Navigating the Thermal Future: Strategic Intelligence for the Worldwide FRP Cooling Tower Market (2026-2032)
Executive Summary: The Imperative for Data-Driven Thermal Management
As industries globally pivot towards higher efficiency standards and stricter environmental compliance frameworks, the infrastructure supporting thermal regulation has become a critical focal point for capital expenditure planning. The Fiber Reinforced Plastic (FRP) cooling tower sector is not merely a component of industrial utility; it is a strategic lever for energy optimization, asset longevity, and operational resilience. Our latest comprehensive study, the Worldwide FRP Cooling Tower Market analysis, provides a granular look into the trajectory of this essential market through 2032. This article serves as a strategic preview, outlining the macroeconomic currents and competitive forces shaping the landscape, while highlighting the necessity of accessing detailed intelligence for precise decision-making.
For stakeholders operating in 2026, the margin between successful market positioning and operational lag often lies in the specificity of the data. General trends are insufficient for supply chain optimization, capacity expansion, or competitive benchmarking. This report bridges that gap, offering a robust framework for understanding how cooling infrastructure investment aligns with broader industrial goals in power generation, HVAC, and process industries.
Market Trajectory: Growth Dynamics and Core Drivers
The historical performance of the FRP cooling tower market indicates a steady upward trajectory, reflecting the increasing reliance on efficient heat exchange systems across heavy industry and commercial infrastructure. Between 2020 and 2025, the market demonstrated consistent revenue expansion, setting a strong foundation for the forecast period extending to 2032. The Compound Annual Growth Rate (CAGR) during the forecast horizon is projected at 5.48%, signaling sustained demand driven by industrialization in emerging economies and retrofitting activities in mature markets.
Revenue figures in USD Millions underscore the scale of the opportunity. Starting from a baseline in the early 2020s, the market revenue has climbed progressively, reaching new milestones by 2025. Looking forward, the valuation is expected to climb significantly, with projections indicating robust performance through the end of the decade. However, it is important to note that growth is not linear; it is subject to raw material volatility, regulatory shifts, and technological adoption rates. Our analysis dissects these variables to provide a nuanced view of potential revenue streams without relying on superficial aggregate numbers.
Segmentation Intelligence: Types, Applications, and Regional Nuances
Understanding the market requires a deep dive into how demand is distributed across different structural types and application verticals. The market is categorically divided by tower construction types, including Induced Draft, Forced Draft, and Natural Draft configurations. Each type offers distinct advantages regarding airflow management, energy consumption, and spatial requirements. Induced Draft units, for instance, dominate specific industrial scenarios where precise control over airflow is necessary, while Forced Draft systems are often favored for their compactness in constrained facilities. Natural Draft towers remain relevant for large-scale utility applications where longevity and low operational noise are prioritized. A detailed breakdown of the revenue contribution and growth potential of each type is essential for manufacturers determining their product mix strategy.
On the application front, the demand landscape is diverse. Power Generation remains a cornerstone consumer of cooling tower infrastructure, driven by the need for process cooling in thermal and nuclear facilities. HVAC applications represent a significant portion of the market, linking cooling tower demand to commercial construction rates and energy efficiency mandates in building management. Additionally, sectors such as Chemical and Petrochemical, Food and Beverage, and Oil and Gas contribute substantial volume to the market. Each vertical imposes unique operational stresses on cooling equipment, from corrosion resistance in chemical plants to hygiene standards in food processing. Our report details the specific requirements and spending patterns within each application segment, helping buyers align specifications with industry norms.
Geographically, the market exhibits varied intensity. Asia Pacific continues to be a hub of industrial activity and infrastructure development, reflecting in its significant share of market revenue. North America and Europe maintain steady demand driven by regulatory compliance and replacement cycles for aging infrastructure. Regions such as the Middle East and Africa, along with Latin America, present emerging opportunities tied to energy projects and industrial expansion. The regional analysis within our study goes beyond simple revenue splits to examine local supply chains, import/export dynamics, and region-specific regulatory hurdles that influence market entry and expansion strategies.
Competitive Landscape: Key Players and Strategic Positioning
The FRP cooling tower market is characterized by a mix of specialized manufacturers and broader industrial equipment providers. Market concentration levels indicate that while there is room for niche players, larger entities hold significant sway over pricing and technology standards. The competitive environment is fiercely focused on energy efficiency, durability, and certification compliance.
Several key companies define the current industry standards. Tower Tech, based in the United States, has positioned itself as a leader in modular FRP cooling towers utilizing pultruded FRP construction. Their focus on energy efficiency claims up to 40% less energy consumption, alongside water savings and critical certifications like FM Approvals for fire, storm, and seismic performance, sets a high bar for industrial and HVAC applications. Delta Cooling Towers, one of the oldest full-service fiberglass manufacturers in the US, emphasizes low maintenance and lightweight corrosion-resistant designs across multiple circular FRP models.
In the Asia Pacific region, particularly India, manufacturers like Gold Cooling Towers, World Cooling Towers, Perfect Cooling Towers, and Global Refrigeration & Equipments are strengthening the supply base. World Cooling Towers, for example, highlights ISO 9001:2015 certification and CTI standards compliance, offering energy-efficient belt-drive options. Perfect Cooling Towers expands the scope with dry cooling towers and various flow models, while Vincitore Edutechnologies caters to diverse sectors including power and petrochemical with induced and forced draft options. Chinese manufacturers such as Hebei Yiyang Environmental Protection Equipment also contribute to the global supply chain, focusing on FRP products for industrial applications.
Worldwide FRP Bridge Market
Competitive dynamics are further influenced by recent developments. For instance, Tower Tech highlighted industry-first fire certifications for factory-assembled FRP designs in early 2025. Meanwhile, semiconductor giant TSMC has continued rolling out high-efficiency cooling tower fans with FRP blades and epoxy coating, achieving significant electricity savings in fabs, illustrating cross-industry adoption of advanced cooling tech. These developments signal to stakeholders where technological differentiation is occurring.
Industry Dynamics: Materials, Efficiency, and Regulatory Pressures
The operational environment for FRP cooling towers is shaped by converging forces in raw materials, performance metrics, and regulatory compliance. Raw material costs fluctuate, impacting manufacturing economics. For example, glass fiber prices in the USA were observed around specific thresholds in early 2026, with comparable pricing in China. These costs are critical as fiberglass serves as a key reinforcement component in FRP construction. Furthermore, the global fiberglass market itself is projected to grow substantially over the next decade, driven by demand in composites for industrial applications. This macro trend suggests both supply availability and potential cost pressures that manufacturers must navigate.
Performance efficiency remains a primary driver for adoption. FRP cooling towers are noted to provide improvements in energy efficiency under high-humidity conditions compared to traditional materials. This aligns with broader industrial energy optimization goals, making FRP an attractive choice for facilities looking to reduce carbon footprints and operational costs.
Regulatory compliance is increasingly becoming a gatekeeper for market participation. FM Global approvals for fire, storm, and seismic performance are critical for FRP modular cooling towers in industrial settings to reduce loss exposure. Additionally, environmental permits for chemical facilities are increasingly explicit, referencing and regulating multiple FRP cooling tower cells for process brine cooling and emissions control. Such regulatory frameworks dictate not only what can be installed but also how it must be maintained and documented. Stakeholders must stay abreast of these evolving requirements to avoid compliance risks and ensure uninterrupted operations.
Strategic Value for 2026 Decision Makers
In the current economic climate, investing in market research is an investment in risk mitigation and strategic agility. The Worldwide FRP Cooling Tower Market report is designed to equip decision-makers with the intelligence needed to navigate these complexities. Whether you are a manufacturer considering capacity expansion, a procurement officer evaluating supplier reliability, or an investor assessing sector growth, the granular data contained in this study provides the necessary clarity.
Worldwide FRP Cooling Tower Market
The report offers actionable insights into supply chain vulnerabilities, emerging technological standards, and shifting demand centers. By understanding the interplay between raw material costs, regulatory updates, and regional growth rates, businesses can formulate strategies that are resilient to external shocks. The comprehensive segmentation analysis allows for precise targeting of high-growth niches, while the competitive profiling helps identify potential partners or threats in the value chain.
Conclusion: Accessing the Full Intelligence
The FRP cooling tower market is poised for continued evolution, driven by the dual engines of industrial growth and efficiency mandates. While this overview highlights the major trends and structural elements defining the sector, the full depth of the analysis contains the specific data points required to execute informed strategies. The nuances of revenue splits, detailed growth rates for specific segments, and in-depth company assessments are critical for moving from general awareness to specific action.
To leverage the complete potential of this intelligence for your organizational planning, we invite you to explore the full Worldwide FRP Cooling Tower Market research report. Access the detailed datasets, forecasts, and strategic recommendations that will define your competitive edge in the years leading up to 2032.
For detailed analysis of this topic, please visit the official page: Worldwide FRP Cooling Tower Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com