

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Military Smart Wearables Market Hits $3,715M in 2025, Forecast 13.8% CAGR to $9,182M by 2032

Strategic Horizons: Navigating the Worldwide Military Smart Wearable Devices Market Through 2032
Executive Overview
The contemporary battlefield is increasingly defined by data, connectivity, and the enhancement of individual soldier capabilities. As armed forces globally pivot toward modernization, the integration of smart wearable technologies has transitioned from experimental concepts to critical operational necessities. Our latest comprehensive study, Worldwide Military Smart Wearable Devices Market, offers a definitive analysis of this rapidly evolving landscape. Covering historical performance from 2020 through 2025 and projecting forward to 2032, this research provides the strategic intelligence required to navigate complex procurement cycles, technological disruptions, and shifting geopolitical demands.
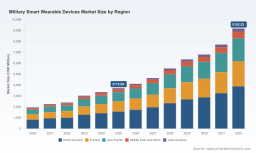
This market has demonstrated resilience and robust expansion over the past half-decade. In 2020, the global revenue stood at approximately 1950.4 million USD, reflecting the early stages of widespread adoption. By 2025, this figure had surged to 3715.06 million USD, underscoring the accelerating pace of deployment across multiple defense sectors. Looking ahead, the trajectory remains steep. The market is projected to reach 4109.98 million USD in 2026 and continue climbing to 9182.52 million USD by 2032. This growth represents a compound annual growth rate of 13.8 percent throughout the forecast period, signaling a sustained investment cycle that rewards early movers and strategic planners who understand the nuances of this domain.
Market Drivers and Technological Imperatives
The expansion of the military smart wearable sector is not merely a function of budgetary increases but is driven by fundamental changes in combat doctrine. Modern warfare requires heightened situational awareness, real-time health monitoring, and seamless communication networks. Soldiers are no longer just combatants; they are nodes within a broader Internet of Military Things (IoMT). Wearable devices facilitate this shift by enabling continuous monitoring of vital signs, environmental hazards, and tactical positioning.
Several key factors are propelling this demand. First, the need for extended dismounted operations pushes the requirement for reliable power management. Hardware bottlenecks often center on high-density, conformal batteries capable of supporting operations beyond 72 hours without resupply. Second, interoperability remains a critical priority. Defense agencies are increasingly mandating compliance with standards such as MIL-STD-810 for environmental durability, MIL-STD-461 for electromagnetic interference, and GOSSRA for Generic Open Soldier Systems Reference Architecture interoperability. These standards ensure that wearable sensors and networks integrate securely into tactical communications without compromising cybersecurity or data integrity.
Worldwide Military Wearable Market
Furthermore, regulatory frameworks are shaping market dynamics. Policies from the U.S. Department of Defense, for instance, restrict geolocation-capable wearables in certain operational areas and classified facilities, while allowing approved fitness and health monitoring devices under specific compliance criteria. Recently, updates such as the U.S. Air Force prohibition on wearing consumer smart glasses like Meta AI devices in uniform due to operational security risks highlight the delicate balance between innovation and security. Understanding these regulatory constraints is essential for any organization seeking to enter or expand within this market.
Segmentation Insights and Operational Focus
Our research dissect the market across multiple dimensions, providing granular visibility into where growth is concentrated and how technologies are categorized. The product landscape is diverse, encompassing head-mounted displays, body-worn cameras and sensors, smart watches and wrist-worn devices, exoskeletons, and power and data management devices. Each category serves distinct operational requirements, from augmented reality overlays for pilots and ground troops to haptic feedback systems for heavy lifting and endurance.
Application-wise, the market is driven by needs for situational awareness, health and vital monitoring, communication and navigation, and training and simulation. Situational awareness remains a primary focus, as forces seek to maintain a comprehensive understanding of the battlespace through real-time data feeds. Health and vital monitoring is equally critical, with programs like the U.S. Army's Wearable All-hazard Remote-monitoring Program advancing toward program of record status. This initiative utilizes patches for chemical, biological, and biometric monitoring, reflecting a broader trend toward precision health in military personnel. Training and simulation also leverage wearable tech, allowing for immersive experiences that prepare personnel for complex scenarios without the risks associated with live exercises.
Regional dynamics also play a significant role in market distribution. Investment levels vary across North America, Europe, Asia Pacific, the Middle East and Africa, and Latin America, influenced by local defense budgets, modernization programs, and geopolitical tensions. Our analysis provides a clear picture of these regional strengths without oversimplifying the unique procurement environments present in each geography.
Competitive Landscape and Strategic Positioning
The market features a mix of established defense giants and specialized technology firms, creating a competitive environment where innovation and compliance intersect. The top players hold significant market share, with the top three companies accounting for 42.5 percent of the market and the top five reaching 61.8 percent. This concentration indicates a mature market where scale and established relationships matter, yet there is still room for niche innovators who can solve specific technological hurdles.
Key contributors to the ecosystem include BAE Systems, which develops advanced soldier systems integrating health monitoring, communication, and tactical wearables for enhanced combat readiness. Elbit Systems Ltd. provides wearable systems tailored to military modernization programs, focusing on soldier health monitoring and electronic warfare solutions. Lockheed Martin Corporation invests in integrated wearable technologies including sensor systems and soldier modernization platforms for tactical operations. Honeywell International Inc. offers sensing, navigation, and wearable electronics focusing on durability and performance, while L3Harris Technologies Inc. supplies communication-focused wearables and tactical systems compliant with military standards.
European defense contractors are also highly active. Leonardo S.p.A. delivers defense electronics and wearable solutions for situational awareness, while Thales Group provides advanced sensors and communication systems for defense applications. Rheinmetall AG focuses on soldier systems and integrated wearable platforms for European and NATO forces, and Saab AB supplies tactical wearables emphasizing survivability and awareness. Aselsan A.S. develops electronic warfare and wearable sensor systems, adding regional depth to the competitive field.
Commercial technology firms are also making inroads. General Dynamics Corporation develops mission systems including communication and wearable technologies for ground forces. Garmin Ltd. provides rugged navigation and health monitoring wearables adapted for military use. Vuzix Corporation supplies AI-powered smart glasses and waveguide optics for military helmet-mounted AR/HUD systems, recently highlighting defense waveguide solutions and military helmet integration with Collins Aerospace. Microsoft Corporation develops augmented reality platforms, such as HoloLens adaptations, for military training and operational use. These collaborations between commercial innovators and defense primes illustrate the cross-pollination of technology that is defining the next generation of military wearables.
Worldwide Military Smart Wearable Devices Market
Recent Developments and Future Outlook
Recent activity underscores the momentum in this sector. In early 2026, Yank Technologies was selected for a U.S. Army Phase II SBIR contract valued at 2 million USD to advance wireless charging systems for conformal wearable batteries in military vehicles, addressing the critical power management bottleneck. Around the same time, Vuzix Corporation showcased defense waveguide solutions at major industry events, emphasizing rugged AR applications. The U.S. Army updated its Wearable All-hazard Remote-monitoring Program, noting initial fielding to special operations in late 2025 and progress toward program of record status in FY2027. Additionally, RTI International released details on the AlphaWear platform for the U.S. DoD, designed to monitor heat stress, infection risk, and mental health using wearable data for precision health.
Looking toward 2032, the market is poised for continued evolution. As cybersecurity, data interoperability, and MIL-SPEC environmental qualification become non-negotiable requirements, suppliers who can deliver secure, resilient, and interoperable solutions will capture the greatest value. The convergence of AI, advanced sensors, and ruggedized hardware will further blur the lines between consumer electronics and military-grade equipment, requiring strict adherence to operational security protocols.
How This Research Empowers Your Strategy
Our Worldwide Military Smart Wearable Devices Market report is designed to be a practical tool for decision-makers. It goes beyond high-level statistics to offer actionable intelligence on procurement trends, technology roadmaps, and competitive moves. Readers will find detailed profiles of key companies, analysis of recent contract awards and product launches, and a thorough examination of regulatory impacts. Whether you are evaluating entry opportunities, assessing competitor capabilities, or planning long-term R&D investments, this study provides the context needed to mitigate risk and identify growth vectors.
We invite you to explore the full scope of our findings. The complete report contains detailed segmentation data, regional breakdowns, and proprietary forecasts that are essential for crafting a winning strategy in this high-stakes environment. Access the full intelligence today to stay ahead of the curve in the global military smart wearable devices market.
For detailed analysis of this topic, please visit the official page: Worldwide Military Smart Wearable Devices Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com