

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Remicade Market to Reach USD 4,950M in 2025, Shrinking at -4.52% CAGR Through 2032

Navigating the Decline: Strategic Imperatives in the Global Remicade (Infliximab) Drug Market Through 2032
The global therapeutic landscape for monoclonal antibodies has long been defined by blockbuster agents that reshaped standard care across multiple autoimmune indications. Among these, Remicade (infliximab) stands as a foundational reference product, yet its commercial trajectory has entered a period of structural contraction. As biosimilar penetration deepens and originator revenue streams compress, pharmaceutical executives, market access leaders, and investment strategists require a granular, forward-looking analysis to navigate the coming years with confidence. Our newly released Worldwide Remicade (infliximab) Drug Market research delivers precisely that intelligence, synthesizing historical performance, competitive positioning, and multi-year forecasts into a decision-ready framework.
This executive overview outlines why this study is an essential strategic asset for 2026 planning cycles. It highlights the macroeconomic contours of the market, maps the evolving competitive architecture, details the operational contents of the full report, and demonstrates how procurement, pricing, and pipeline teams can translate these insights into measurable advantage. Crucially, the complete dataset—covering regional revenue trajectories, indication-level demand shifts, product-type dynamics, and company-specific market share estimates—resides within the full publication, accessible through our research portal.
The Macro Trajectory: A Contraction Shaped by Biosimilar Maturity and Payer Pressure
Understanding where the Remicade market is heading begins with acknowledging its historical arc. Over the 2020–2025 period, global revenue for infliximab products has followed a consistent downward slope, reflecting the irreversible shift from a single originator-dominated ecosystem to a fragmented, price-competitive biosimilar marketplace. Our model places the 2025 baseline at approximately $4,950 million, down from roughly $8,240 million at the start of the historical window. This compression is not a transient cycle but a structural realignment driven by patent expirations, tender-based procurement, and deliberate payer policies that reward lower-cost alternatives without compromising clinical outcomes.
Looking forward, the forecast period spanning 2026 through 2032 projects a continued contraction, with the compound annual growth rate indicating a decline of roughly 4.52 percent across the analysis horizon. By 2032, total market value is projected to settle near the $3.58 billion mark. Executives should interpret this trajectory not as market failure but as market maturation. The value pool is being redistributed: originators retain premium positioning in specific channels and patient segments, while biosimilar manufacturers capture volume through aggressive pricing, formulary placements, and emerging-market access programs.
Several structural forces reinforce this path. Cold-chain logistics and biologic manufacturing complexity continue to dominate cost-of-goods profiles, constraining the pace at which new entrants can scale without sacrificing quality or margin. Simultaneously, reimbursement architectures across major healthcare systems increasingly treat infliximab biosimilars as interchangeable options within treatment algorithms, accelerating utilization in rheumatoid arthritis, Crohn’s disease, ulcerative colitis, psoriatic arthritis and psoriasis, and ankylosing spondylitis. The strategic question for 2026 is no longer whether biosimilar share will grow, but how companies will defend or capture value as the remaining originator revenue erodes and biosimilar price competition intensifies.
Worldwide Remicade (infliximab) Drug Market
Competitive Architecture: Coexistence, Substitution, and Strategic Differentiation
The competitive landscape for infliximab is unusually dense, spanning the originator firm, a cohort of established biosimilar developers, and a second wave of emerging-market suppliers targeting price-sensitive channels. This fragmentation creates a multilayered battlefield where commercial strategy must be tailored to geography, formulation, distribution model, and payer relationship rather than applied uniformly.
Janssen Biotech, Inc. (Johnson & Johnson) remains the anchor of the reference-product ecosystem. As the originator of intravenous Remicade, the company continues active global commercialization, including promotion of an unbranded infliximab variant in select contexts. Its Q1 2026 worldwide sales reporting of $422 million illustrates both the resilience of the brand in remaining formulary positions and the steady headwind from biosimilar substitution and patient-mix shifts. For strategists, Janssen’s trajectory signals that originator value is increasingly tied to channel control, patient support programs, and relationship-driven procurement rather than volume dominance.
On the biosimilar side, Celltrion, Inc. has emerged as a formulation innovator. The company markets Remsima (CT-P13) IV biosimilar and Zymfentra (infliximab-dyyb) subcutaneous formulation, while also offering the world’s first liquid IV infliximab formulation. A recent European Commission marketing authorization for the Remsima IV liquid across all prior indications—including rheumatoid arthritis, Crohn’s disease, and ulcerative colitis—represents a meaningful operational advantage by reducing preparation complexity and potentially improving infusion-center efficiency. This kind of formulation-level differentiation is exactly the type of lever that can shift purchasing decisions in hospital and institutional settings.
Worldwide Belimumab Market
Pfizer Inc. continues to compete through Inflectra (infliximab-dyyb) and Ixifi (infliximab-qbtx) across multiple markets, leveraging broad commercial infrastructure. Samsung Bioepis Co., Ltd., in partnership with Organon & Co., commercializes Renflexis (infliximab-abda) in the United States and Flixabi (SB2) in Europe, demonstrating how co-commercialization and licensee relationships can extend reach without duplicating fixed costs. Amgen Inc. markets Avsola (infliximab-axxq), while Sandoz Group AG (a Novartis division) offers Zessly (infliximab) biosimilar in Europe and other regions. Viatris Inc. remains active through its legacy Mylan portfolio and select partnerships, and a broader tier of suppliers—including Biocon Biologics, Dr. Reddy’s Laboratories, Teva Pharmaceutical Industries, Fresenius Kabi AG, STADA Arzneimittel AG, Intas Pharmaceuticals, and Zydus Lifesciences—operates with a deliberate focus on emerging markets, tender-based supply, and cost-sensitive regions.
This architecture matters because pricing, access, and supply reliability are no longer determined by a single reference price. Instead, procurement teams evaluate a matrix of product specifications, cold-chain readiness, batch consistency, regulatory status by territory, and contractual flexibility. The full report dissects these dynamics company by company, enabling buyers and competitors to benchmark positioning with precision.
Structural Drivers: Regulation, Reimbursement, and Manufacturing Realities
Three interlocking dynamics define the operating environment for infliximab products and shape every strategic choice made in 2026.
First, regulatory milestones have already unlocked the biosimilar market. Remicade patents expired in the European Union in February 2015 and in the United States in September 2018, enabling multiple biosimilar entries. The FDA has since approved a sequence of infliximab biosimilars, including Inflectra (2016), Renflexis (2017), Ixifi (2017), and Avsola (2019), with continued utilization across autoimmune indications. These approvals are not historical footnotes; they are the foundation of today’s market structure and the reason why formulary decisions, interchangeability designations, and national procurement frameworks now operate under a biosimilar-friendly paradigm.
Second, reimbursement and pricing behavior are actively redistributing the value pool. Infliximab biosimilars have demonstrated average price discounts ranging from roughly 19 to 59 percent versus pre-biosimilar Remicade list prices, generating measurable cost savings for payers and healthcare systems. In the US, biosimilar market share reached approximately 48 percent by Q3 2024 and continued incremental gains into 2025, driven by payer preferences and lower average selling prices. Early 2025 data suggest biosimilars captured an estimated 48 to 53 percent share in the US, with gradual further uptake expected as tenders renew and formulary placements consolidate. For commercial teams, the implication is clear: list-price competition is being replaced by negotiated, volume-linked, and channel-specific pricing models, and success depends on contractual design as much as product quality.
Third, manufacturing and supply-chain economics remain a binding constraint. Biologic manufacturing complexity, including cold-chain logistics for monoclonal antibodies, continues to be a primary cost driver alongside active pharmaceutical ingredient production. This reality influences everything from tender competitiveness to risk of supply disruption and from geographic expansion sequencing to margin sustainability. Companies that can demonstrate reliable cold-chain capacity, consistent batch release, and defensible cost structures will command disproportionate leverage in institutional and government procurement contexts.
Inside the Report: Operational Content Designed for 2026 Decision-Making
Our Worldwide Remicade (infliximab) Drug Market study is structured to convert market complexity into actionable plans. Rather than offering high-level commentary, the report delivers operational content that procurement, pricing, market access, and business development teams can apply directly during planning cycles. The full publication includes:
- A comprehensive historical analysis covering the 2020–2025 window, establishing the baseline for trend interpretation and benchmarking current performance against prior-year dynamics.
- A forecast model extending through 2032 that quantifies the expected revenue trajectory at the total market level and isolates the drivers behind the projected decline, including biosimilar share gains, pricing compression, and indication-level demand evolution.
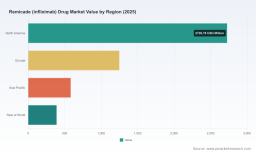
- Detailed segmentation analysis by region, product type, and indication, enabling readers to understand where value is concentrating, where substitution is accelerating, and which therapeutic areas retain the strongest pricing resilience.
- A competitive benchmarking module that evaluates the positioning, formulation strategies, geographic footprints, and commercial models of the key players shaping the infliximab ecosystem.
- Thematic analysis of regulatory timelines, reimbursement behavior, price discount ranges, and manufacturing and cold-chain constraints, integrated into a cohesive view of market dynamics rather than treated as isolated facts.
- Identification of recent developments and their strategic implications, including formulation-level approvals and quarterly sales signals that indicate how the competitive balance is shifting in real time.
Each section is designed to support a specific decision type. Procurement leaders can use the segmentation and pricing themes to structure tender evaluations and negotiate volume commitments. Pricing and market access teams can leverage the discount-range analysis and payer-behavior insights to model formulary positioning and contract architectures. Business development and competitive intelligence teams can use the company-level profiling and strategic context to assess partnership opportunities, geographic entry sequencing, and formulation-driven differentiation. The complete version of the report presents the underlying figures, regional and indication-level breakdowns, and company-specific estimates in full, ensuring that readers can validate assumptions and build internal models with confidence.
Strategic Implications for 2026 Planning Cycles
For executives entering 2026, the Remicade market demands a shift from volume-defensive thinking to value-positioning discipline. Several implications stand out.
Originator and reference-product teams must prioritize channel control, patient support, and relationship-based procurement to sustain relevance as biosimilar volume grows. The focus should be on protecting high-value segments, optimizing unbranded or supportive offerings, and aligning sales resources with the channels where clinical integration and service quality still differentiate the reference product.
Biosimilar developers should differentiate through formulation convenience, supply reliability, and contractual flexibility rather than price alone. The recent European authorization of a liquid IV infliximab formulation highlights how reduced preparation burden can resonate with infusion centers and hospital pharmacy operations. Where price competition is intense, margin defense depends on manufacturing efficiency, cold-chain capability, and the ability to secure recurring volume through tenders and institutional contracts.
Payers, procurement organizations, and healthcare systems should treat infliximab as a case study in managed substitution. With biosimilar discounts materially below pre-biosimilar list prices and utilization expanding across core autoimmune indications, the opportunity lies in structuring contracts that lock in savings while preserving supply continuity and clinical equivalence. Forecasting models that fail to account for incremental biosimilar uptake, indication-level demand patterns, and regional procurement cycles will overestimate remaining originator revenue and underestimate total cost savings.
Investors and market analysts should frame the market as a redistribution story rather than a collapse. Revenue is migrating from a single originator to a diverse set of biosimilar suppliers, with regional variation in pace and depth. Concentration among top players remains significant, underscoring the importance of understanding which firms control which channels and how partnership arrangements shape commercial reach. The full report quantifies these concentration dynamics and regional splits so that stakeholders can map risk and opportunity with precision.
Conclusion: Accessing the Full Intelligence
The Worldwide Remicade (infliximab) Drug Market is undergoing a measured but unmistakable contraction, shaped by mature biosimilar competition, aggressive payer cost management, and the enduring complexity of biologic manufacturing and distribution. For organizations operating in this space, the strategic imperative in 2026 is to replace assumptions with evidence: to know where value is eroding, where it is being captured, and which operational levers will determine outcomes over the 2026–2032 horizon.
This executive preview has outlined the macro trajectory, the competitive architecture, the structural drivers, and the operational content embedded in our research. The complete market size figures, regional and indication-level breakdowns, product-type dynamics, company-specific estimates, and concentration metrics are available in the full study. Readers seeking the granular intelligence required to build pricing models, structure procurement strategies, or assess competitive positioning can access the complete dataset and analysis through our research platform, where the full report provides the depth necessary to support confident, evidence-based decision-making.
For detailed analysis of this topic, please visit the official page: Worldwide Remicade (infliximab) Drug Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com