

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global Medical Network Isolators Market to Hit $300.81M by 2032, 6.45% CAGR

Strategic Intelligence for the Connected Healthcare Era: Inside the Worldwide Medical Network Isolators Market
The modern hospital is no longer a collection of standalone devices but a densely interconnected ecosystem where patient data, imaging streams, and life-support systems communicate across Ethernet backbones in real time. As this connectivity deepens, so does the imperative to guarantee galvanic separation, limit leakage currents, and protect vulnerable medical equipment from potential differences that travel along data cables. Our latest worldwide market study on medical network isolators maps this evolving landscape with the precision that procurement leaders, R&D directors, and regulatory affairs teams require to make confident investment decisions throughout 2026 and beyond.
The research anchors its perspective in a five-year historical window spanning 2020 through 2025, then projects forward across a seven-year forecast horizon from 2026 to 2032. This structure allows decision-makers to ground strategic plans in observed trajectory rather than speculative optimism. The overall market size has expanded from approximately 145.2 million USD in 2020 to 194.2 million USD in the 2025 base year, reflecting sustained demand driven by hospital modernization programs, tighter patient-safety expectations, and the proliferation of networked diagnostic and therapeutic equipment. The forecast period continues this upward path, reaching an estimated 214.24 million USD in 2026 and climbing toward 300.81 million USD by 2032. Over the full forecast window, the compound annual growth rate settles at 6.45 percent, a figure that signals steady, structurally supported expansion rather than a temporary cycle.
Worldwide Medical Network Isolators Market
For executives evaluating capital allocation, product roadmaps, or regional entry strategies, these macro indicators serve as a calibration point. Growth is not uniform across every segment, geography, or product architecture, and that unevenness is precisely where strategic advantage is created. The study deliberately avoids flattening the market into a single narrative. Instead, it dissects the demand structure so that leadership teams can identify which subsegments warrant deeper investment, which supply constraints demand contingency planning, and where regulatory momentum is reshaping procurement requirements.
Digital Isolators Market
Volume and Share Distribution Across Segments
Understanding where revenue concentrates is essential for prioritizing commercial efforts and engineering resources. The report breaks down the market across three dimensions that matter most to buyers and suppliers: geography, product type, and clinical application. In 2025, regional revenue distribution shows a clear hierarchy that mirrors the maturity of healthcare infrastructure and the pace of networked device adoption. North America accounts for 73.64 million USD of total revenue, reflecting dense hospital networks, robust capital equipment cycles, and early adoption of networked imaging and navigation systems. Europe follows with 53.53 million USD, supported by established medical device regulations and continued retrofitting of legacy facilities. Asia Pacific contributes 48.52 million USD, a segment shaped by rapidly expanding diagnostic capacity, growing private hospital chains, and increasing import and localization activity. Latin America records 9.99 million USD, while the Middle East and Africa account for 8.52 million USD, both regions representing high-potential but structurally different demand environments that require distinct go-to-market approaches.
The type segmentation reveals how engineering preferences differ across installation contexts. External network isolators represent the largest value pool at 131.8 million USD, reflecting their role as field-installable protection modules for existing Ethernet infrastructure in patient care vicinities. Wall-mounted network isolators contribute 41.04 million USD, capturing demand from fixed installation scenarios where space, compliance, and serviceability are paramount. Built-in OEM modules account for 21.36 million USD, a smaller but strategically significant pool tied to equipment manufacturers integrating isolation at the design stage rather than relying on post-market add-ons. These distinctions matter because each type carries different certification burdens, integration timelines, and procurement cycles.
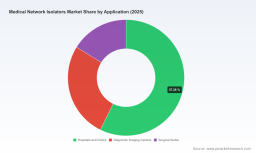
Application segmentation further clarifies where demand originates on the clinical floor. Hospitals and clinics generate 111.23 million USD, the dominant environment for network isolation given the breadth of connected devices and the strictness of safety requirements in patient-adjacent areas. Diagnostic imaging centers contribute 51.56 million USD, reflecting the high data-throughput needs of imaging networks and the sensitivity of diagnostic equipment to electrical disturbances. Surgical suites account for 31.41 million USD, a specialized segment where isolation is often evaluated not only for safety but also for operational continuity during critical procedures. Together, these segments illustrate a market in which isolation is no longer an accessory but a design requirement tied to device certification, facility compliance, and risk management.
Competitive Dynamics and Supplier Positioning
The market is not fragmented in the traditional sense, but neither is it dominated by a single supplier architecture. The report places the competitive landscape in context by examining the players who shape product standards, certification practices, and purchasing expectations. Baaske Medical GmbH stands out for its TÜV-certified medical network isolators, including the MI 1005 series and the MI 2005 designed for 2.5 GBit/s throughput. Its product line is engineered to comply with IEC 60601-1 Edition 3.2, emphasizing galvanic isolation in patient care vicinities and protection against leakage currents, overvoltages, and electrostatic discharge for Ethernet connections in hospitals and medical devices. For procurement teams, this level of certification specificity matters because it reduces integration risk and shortens compliance verification cycles.
EMO Systems GmbH, operating under the EMOSAFE brand, provides network isolators such as the EN-1005+ and EN-70 series for medical applications. Its offerings are designed to conform to IEC 60601-1 with high dielectric strength, reaching up to 5 kV AC and 8.5 kV DC, alongside UL recognition and support for Gigabit-plus Ethernet. The emphasis on galvanic separation and patient safety in medical electrical devices positions EMOSAFE as a supplier aligned with environments where electrical robustness and regulatory recognition are equally important. Eaton, through its Tripp Lite series, contributes hospital-grade medical Ethernet network isolators such as the N234-MI-1005, a Cat6 RJ45 solution compliant with IEC 60601-1 and UL 60601-1. Its value proposition centers on isolating medical equipment from leakage currents on Ethernet networks in patient care vicinities, a concern that remains highly relevant as hospitals connect devices to non-medical infrastructure. Phoenix Contact rounds out the competitive field with passive network isolators such as the FL ISOLATOR 100-RJ/SC, providing up to 4 kV protection against potential differences. Its approach is particularly relevant for integration scenarios in medical and industrial settings where galvanic isolation must be achieved without adding external power dependencies.
The study also situates these supplier profiles within broader competitive metrics. Market concentration data shows a CR3 of 38.5 percent and a CR5 of 52.3 percent, indicating that while leading players hold meaningful share, the market still leaves substantial room for specialized suppliers, regional distributors, and OEM-embedded solutions. This structure has practical implications for sourcing strategy. Buyers can leverage multi-supplier validation to manage supply continuity, while suppliers must differentiate on certification breadth, throughput capability, installation form factor, and post-sales technical support rather than price alone.
Regulatory Pressure as a Market Accelerator
One of the most consequential themes in the research is the way regulatory requirements are converting network isolation from a desirable feature into a procurement mandate. Medical network isolators for Ethernet connections in patient care vicinities must comply with IEC 60601-1:2005/AMD1:2012/AMD2:2020, Edition 3.2, which defines reinforced insulation at the 2 MOPP level and requires galvanic separation to limit leakage currents. This is not a marginal specification; it shapes product architecture, validation documentation, and the way hospitals evaluate components during facility upgrades or equipment refreshes. Suppliers that align their offerings with these requirements gain a compliance shortcut, while buyers gain a clearer basis for specification writing and audit readiness.
The regulatory environment also interacts with certification ecosystems beyond the IEC baseline. EMOSAFE network isolators conform to IEC 60601-1 requirements for SIP and SOP interfaces on medical electrical equipment, with additional UL recognition as components for safe operation in medical environments. Eaton Tripp Lite medical Ethernet isolators such as the N234-MI-1005 comply with IEC 60601-1 and IEC 60601-1-2 EMC standards specifically for network connections between medical devices and non-medical Ethernet infrastructure in patient vicinities. These overlapping standards create a compliance matrix that procurement teams must navigate carefully, and the report maps that matrix so that readers can see where certification convergence reduces friction and where gaps still require custom validation.
Passive medical network isolators add another dimension to the regulatory discussion. By providing galvanic isolation without external power, they interrupt all conductive connections, including conductors and shielding, preventing the equalization of potential differences via data cables in healthcare settings. This passive approach appeals in scenarios where adding power-dependent components would complicate installation or introduce new failure modes. At the same time, it places greater importance on component quality, dielectric performance, and long-term reliability documentation, all of which are addressed in the study through supplier-level technical analysis.
Operational Reliability and the Cost of Downtime
Market growth is not only a function of regulation and device proliferation; it is also tied to the operational consequences of communication failure. Networked medical systems depend on stable Ethernet links for data integrity, device coordination, and clinical workflow continuity. When communication anomalies appear, isolation components can become part of troubleshooting workflows. A recent example from April 2025 illustrates this dynamic: during a malfunction analysis involving Medtronic Navigation, Inc., a network isolator component was replaced while troubleshooting a communication failure in a navigation system. Post-analysis showed no fault confirmed in the returned isolator. While the outcome did not attribute the failure to the isolator itself, the event highlights how isolation components are now embedded in the operational accountability chain for connected medical equipment.
For healthcare providers and device manufacturers, this has strategic implications. It reinforces the need to specify isolation components that are not only compliant but also traceable, serviceable, and supported by clear failure-mode documentation. It also underscores the value of supplier partnerships that extend beyond initial purchase, including technical support, replacement logistics, and compatibility assurance across network architectures. The report examines these operational realities in depth, showing how reliability expectations are reshaping both product design and procurement criteria.
What the Study Delivers Beyond the Top-Line Numbers
The headline market size and growth rate provide orientation, but the real strategic value of the study lies in its operational detail. The report moves beyond summary statistics to deliver content that can be used immediately in planning sessions, specification reviews, and investment committees. It covers the historical trajectory from 2020 through 2025, then projects the market across the 2026 to 2032 forecast period with a structured methodology that connects demand drivers to segment outcomes. It evaluates how type, application, and regional dynamics interact rather than treating them as isolated lenses, which is essential because real-world purchasing decisions rarely follow a single segmentation line.
The study also includes competitive profiling that goes past corporate descriptions. It examines how leading suppliers position themselves against regulatory requirements, throughput expectations, installation preferences, and certification ecosystems. This allows readers to compare not only what companies offer but why they matter in specific procurement contexts. In addition, the research integrates regulatory developments, technical conformity details, and operational case context so that decision-makers can see how compliance, performance, and reliability intersect in day-to-day purchasing and engineering choices.
For teams planning 2026 initiatives, this level of detail supports several practical outcomes. It helps identify where specification requirements are tightening and where procurement cycles may lengthen or shorten. It highlights which product architectures are gaining traction in specific installation environments, and where built-in OEM integration may shift demand away from field-installable add-ons. It also provides a framework for evaluating supplier resilience, including certification coverage, throughput range, and the ability to support both passive and powered isolation strategies where needed.
How to Use This Intelligence in 2026 Planning
The worldwide medical network isolators market is entering a phase in which growth is supported by structural factors rather than short-term cycles. Hospital connectivity continues to expand, regulatory expectations for patient-adjacent Ethernet infrastructure remain stringent, and device manufacturers are increasingly designing isolation into products rather than treating it as an afterthought. In that environment, the organizations that make the best decisions will be those that can connect top-line market direction to segment-level reality, supplier capability, and compliance requirements.
This study is built to support that decision-making. It gives leadership teams a defensible view of where the market has been, where it is headed, and which variables will matter most as 2026 plans are finalized. It also preserves the deeper numerical and supplier-level intelligence that procurement, engineering, and strategy teams need to act with precision. To access the full segmentation analysis, regional breakdowns, type and application detail, and complete competitive and regulatory mapping, readers are invited to explore the full research on the source page. The complete report transforms these high-level insights into actionable intelligence, allowing organizations to move from market awareness to informed execution.
For detailed analysis of this topic, please visit the official page: Worldwide Medical Network Isolators Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com