

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide FRP Cooling Tower Market to Hit $1,323.23M in 2025, Grow at 5.48% CAGR to 2032

Navigating the Thermal Future: Strategic Intelligence for the Worldwide FRP Cooling Tower Market (2026-2032)
Executive Summary: The Imperative for Data-Driven Thermal Management
As industries globally pivot towards higher efficiency standards and stricter environmental compliance frameworks, the infrastructure supporting thermal regulation has become a critical focal point for capital expenditure planning. The Fiber Reinforced Plastic (FRP) cooling tower sector is not merely a component of industrial utility; it is a strategic lever for energy optimization, asset longevity, and operational resilience. Our latest comprehensive study, the Worldwide FRP Cooling Tower Market analysis, provides a granular look into the trajectory of this essential market through 2032. This article serves as a strategic preview, outlining the macroeconomic currents and competitive forces shaping the landscape, while highlighting the necessity of accessing detailed intelligence for precise decision-making.
For stakeholders operating in 2026, the margin between successful market positioning and operational lag often lies in the specificity of the data. General trends are insufficient for supply chain optimization, capacity expansion, or competitive benchmarking. This report bridges that gap, offering a robust framework for understanding how cooling infrastructure investment aligns with broader industrial goals in power generation, HVAC, and process industries.
Market Trajectory: Growth Dynamics and Core Drivers
The historical performance of the FRP cooling tower market indicates a steady upward trajectory, reflecting the increasing reliance on efficient heat exchange systems across heavy industry and commercial infrastructure. Between 2020 and 2025, the market demonstrated consistent revenue expansion, setting a strong foundation for the forecast period extending to 2032. The Compound Annual Growth Rate (CAGR) during the forecast horizon is projected at 5.48%, signaling sustained demand driven by industrialization in emerging economies and retrofitting activities in mature markets.
Revenue figures in USD Millions underscore the scale of the opportunity. Starting from a baseline in the early 2020s, the market revenue has climbed progressively, reaching new milestones by 2025. Looking forward, the valuation is expected to climb significantly, with projections indicating robust performance through the end of the decade. However, it is important to note that growth is not linear; it is subject to raw material volatility, regulatory shifts, and technological adoption rates. Our analysis dissects these variables to provide a nuanced view of potential revenue streams without relying on superficial aggregate numbers.
Segmentation Intelligence: Types, Applications, and Regional Nuances
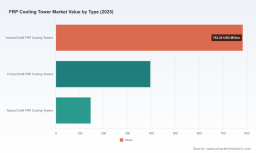
Understanding the market requires a deep dive into how demand is distributed across different structural types and application verticals. The market is categorically divided by tower construction types, including Induced Draft, Forced Draft, and Natural Draft configurations. Each type offers distinct advantages regarding airflow management, energy consumption, and spatial requirements. Induced Draft units, for instance, dominate specific industrial scenarios where precise control over airflow is necessary, while Forced Draft systems are often favored for their compactness in constrained facilities. Natural Draft towers remain relevant for large-scale utility applications where longevity and low operational noise are prioritized. A detailed breakdown of the revenue contribution and growth potential of each type is essential for manufacturers determining their product mix strategy.
On the application front, the demand landscape is diverse. Power Generation remains a cornerstone consumer of cooling tower infrastructure, driven by the need for process cooling in thermal and nuclear facilities. HVAC applications represent a significant portion of the market, linking cooling tower demand to commercial construction rates and energy efficiency mandates in building management. Additionally, sectors such as Chemical and Petrochemical, Food and Beverage, and Oil and Gas contribute substantial volume to the market. Each vertical imposes unique operational stresses on cooling equipment, from corrosion resistance in chemical plants to hygiene standards in food processing. Our report details the specific requirements and spending patterns within each application segment, helping buyers align specifications with industry norms.
Geographically, the market exhibits varied intensity. Asia Pacific continues to be a hub of industrial activity and infrastructure development, reflecting in its significant share of market revenue. North America and Europe maintain steady demand driven by regulatory compliance and replacement cycles for aging infrastructure. Regions such as the Middle East and Africa, along with Latin America, present emerging opportunities tied to energy projects and industrial expansion. The regional analysis within our study goes beyond simple revenue splits to examine local supply chains, import/export dynamics, and region-specific regulatory hurdles that influence market entry and expansion strategies.
Competitive Landscape: Key Players and Strategic Positioning
The FRP cooling tower market is characterized by a mix of specialized manufacturers and broader industrial equipment providers. Market concentration levels indicate that while there is room for niche players, larger entities hold significant sway over pricing and technology standards. The competitive environment is fiercely focused on energy efficiency, durability, and certification compliance.
Several key companies define the current industry standards. Tower Tech, based in the United States, has positioned itself as a leader in modular FRP cooling towers utilizing pultruded FRP construction. Their focus on energy efficiency claims up to 40% less energy consumption, alongside water savings and critical certifications like FM Approvals for fire, storm, and seismic performance, sets a high bar for industrial and HVAC applications. Delta Cooling Towers, one of the oldest full-service fiberglass manufacturers in the US, emphasizes low maintenance and lightweight corrosion-resistant designs across multiple circular FRP models.
In the Asia Pacific region, particularly India, manufacturers like Gold Cooling Towers, World Cooling Towers, Perfect Cooling Towers, and Global Refrigeration & Equipments are strengthening the supply base. World Cooling Towers, for example, highlights ISO 9001:2015 certification and CTI standards compliance, offering energy-efficient belt-drive options. Perfect Cooling Towers expands the scope with dry cooling towers and various flow models, while Vincitore Edutechnologies caters to diverse sectors including power and petrochemical with induced and forced draft options. Chinese manufacturers such as Hebei Yiyang Environmental Protection Equipment also contribute to the global supply chain, focusing on FRP products for industrial applications.
Worldwide FRP Bridge Market
Competitive dynamics are further influenced by recent developments. For instance, Tower Tech highlighted industry-first fire certifications for factory-assembled FRP designs in early 2025. Meanwhile, semiconductor giant TSMC has continued rolling out high-efficiency cooling tower fans with FRP blades and epoxy coating, achieving significant electricity savings in fabs, illustrating cross-industry adoption of advanced cooling tech. These developments signal to stakeholders where technological differentiation is occurring.
Industry Dynamics: Materials, Efficiency, and Regulatory Pressures
The operational environment for FRP cooling towers is shaped by converging forces in raw materials, performance metrics, and regulatory compliance. Raw material costs fluctuate, impacting manufacturing economics. For example, glass fiber prices in the USA were observed around specific thresholds in early 2026, with comparable pricing in China. These costs are critical as fiberglass serves as a key reinforcement component in FRP construction. Furthermore, the global fiberglass market itself is projected to grow substantially over the next decade, driven by demand in composites for industrial applications. This macro trend suggests both supply availability and potential cost pressures that manufacturers must navigate.
Performance efficiency remains a primary driver for adoption. FRP cooling towers are noted to provide improvements in energy efficiency under high-humidity conditions compared to traditional materials. This aligns with broader industrial energy optimization goals, making FRP an attractive choice for facilities looking to reduce carbon footprints and operational costs.
Regulatory compliance is increasingly becoming a gatekeeper for market participation. FM Global approvals for fire, storm, and seismic performance are critical for FRP modular cooling towers in industrial settings to reduce loss exposure. Additionally, environmental permits for chemical facilities are increasingly explicit, referencing and regulating multiple FRP cooling tower cells for process brine cooling and emissions control. Such regulatory frameworks dictate not only what can be installed but also how it must be maintained and documented. Stakeholders must stay abreast of these evolving requirements to avoid compliance risks and ensure uninterrupted operations.
Strategic Value for 2026 Decision Makers
In the current economic climate, investing in market research is an investment in risk mitigation and strategic agility. The Worldwide FRP Cooling Tower Market report is designed to equip decision-makers with the intelligence needed to navigate these complexities. Whether you are a manufacturer considering capacity expansion, a procurement officer evaluating supplier reliability, or an investor assessing sector growth, the granular data contained in this study provides the necessary clarity.
Worldwide FRP Cooling Tower Market
The report offers actionable insights into supply chain vulnerabilities, emerging technological standards, and shifting demand centers. By understanding the interplay between raw material costs, regulatory updates, and regional growth rates, businesses can formulate strategies that are resilient to external shocks. The comprehensive segmentation analysis allows for precise targeting of high-growth niches, while the competitive profiling helps identify potential partners or threats in the value chain.
Conclusion: Accessing the Full Intelligence
The FRP cooling tower market is poised for continued evolution, driven by the dual engines of industrial growth and efficiency mandates. While this overview highlights the major trends and structural elements defining the sector, the full depth of the analysis contains the specific data points required to execute informed strategies. The nuances of revenue splits, detailed growth rates for specific segments, and in-depth company assessments are critical for moving from general awareness to specific action.
To leverage the complete potential of this intelligence for your organizational planning, we invite you to explore the full Worldwide FRP Cooling Tower Market research report. Access the detailed datasets, forecasts, and strategic recommendations that will define your competitive edge in the years leading up to 2032.
For detailed analysis of this topic, please visit the official page: Worldwide FRP Cooling Tower Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com