

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Aviation Fuel Storage Tank Market to Hit $2,593.54M by 2032 at 5.19% CAGR

Strategic Imperatives in the Worldwide Aviation Fuel Storage Tank Market: A 2026 Outlook
The global aviation industry stands at a critical juncture where infrastructure resilience meets the urgent demand for sustainable operations. As air travel recovers and evolves, the backbone of refueling operations—the storage tank infrastructure—requires unprecedented attention. For stakeholders navigating the complex landscape of fuel storage, understanding the macroeconomic trajectory and structural shifts within the market is no longer optional; it is a strategic necessity. Our latest comprehensive analysis of the Worldwide Aviation Fuel Storage Tank Market offers a detailed roadmap for navigating the period from 2026 through 2032, providing the intelligence needed to secure operational continuity and capitalize on emerging growth vectors.
This market research is designed to equip decision-makers with a granular understanding of value chains, competitive pressures, and regulatory headwinds. By synthesizing historical performance data with forward-looking projections, we illuminate the pathways that will define market leadership in the coming decade. The following insights summarize the strategic value embedded within this report, highlighting why immediate engagement with these findings is crucial for capital allocation and risk management.
Market Trajectory and Growth Dynamics
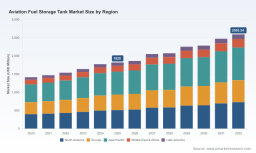
The economic fundamentals of the aviation fuel storage sector demonstrate robust resilience and steady expansion. Based on historical analysis spanning from 2020 to 2025, the market has exhibited consistent upward momentum, transitioning from a revenue valuation of approximately 1,415 million USD to over 1,820 million USD in the base year. This growth trajectory sets a strong foundation for the forecast period covering 2026 to 2032.
Historical Performance and Future Projections
The data indicates a mature yet accelerating market environment. Starting from 2020, the market has navigated through various global disruptions to establish a stable growth pattern. By 2025, the market size reached 1,820 million USD, reflecting a compounded increase over the preceding five years. Looking ahead, the forecast period projects a steady climb, with the market expected to breach the 2 billion USD threshold by 2027 and continue ascending toward 2,593.54 million USD by 2032.
The compound annual growth rate (CAGR) for the forecast period is estimated at 5.19 percent. This rate underscores a healthy demand environment driven by infrastructure upgrades, safety compliance mandates, and the expansion of airport capacities globally. For investors and industry participants, this growth rate signals a stable return profile, provided that entry strategies are aligned with the specific segments driving this expansion. The transition from 2026 to 2032 represents a period where capital expenditure on storage infrastructure will likely outpace general inflation, driven by the need for modernization and regulatory adherence.
Structural Segmentation and Value Distribution
Understanding where value resides within the market is essential for targeted investment. Our report dissects the market into critical operational dimensions, revealing how different segments contribute to the overall revenue pool. While specific percentage breakdowns are reserved for the full dataset, the absolute revenue contributions highlight the dominant areas of activity.
Worldwide Aviation Fuel Storage Tank Market
Regional Revenue Contributions
Geographically, the market is distributed across key industrial hubs. Asia Pacific represents a significant portion of the revenue landscape, contributing over 630 million USD, reflecting the region's aggressive airport expansion and increasing air traffic density. North America follows closely with contributions exceeding 511 million USD, driven by stringent safety regulations and ongoing mid-life infrastructure upgrades at legacy hubs. Europe accounts for over 424 million USD, while the Middle East & Africa and Latin America contribute 163.47 million USD and 90.37 million USD respectively. These figures illustrate the global nature of the demand, though concentration varies significantly based on aviation penetration and fuel logistics requirements.
Tank Type and Installation Preferences
The choice of storage technology remains a pivotal decision for airport planners. The market sees substantial activity in Fixed Roof Tanks, generating approximately 982.48 million USD, which indicates a strong preference for cost-effective storage solutions for stable fuel inventories. Floating Roof Tanks contribute around 837.52 million USD, often selected for specific environmental compliance needs or volatile inventory management.
Installation methodology further delineates the market structure. Above-Ground Storage Tanks (AST) dominate the landscape with a valuation near 1,344.06 million USD, favored for ease of inspection and compliance with modern safety standards. Underground Storage Tanks (UST) account for 475.94 million USD, typically utilized in specific spatial constraints or environmental protection scenarios. The balance between AST and UST often depends on local zoning laws and the specific risk profile of the storage location.
End-User Segmentation
Commercial Airports remain the primary revenue driver, engaging storage solutions valued at approximately 1,294.39 million USD. This dominance is expected given the volume requirements of commercial jet operations. Military Airbases follow with a contribution of 434.74 million USD, where strategic reserve capabilities and ruggedized storage solutions are prioritized. General Aviation, while smaller in scale at 90.87 million USD, represents a niche but high-growth segment, particularly with the rise of private aviation and regional connectivity initiatives.
Competitive Landscape and Strategic Positioning
The market structure is characterized by a moderate level of concentration, where scale and specialization allow key players to secure significant market share. The top three companies hold a combined market share of 28.5 percent, while the top five extend this to 42.3 percent. This indicates a competitive environment where the top tier commands substantial influence, yet a long tail of specialized manufacturers competes on customization, speed, and regional compliance.
Key Industry Participants
Several established players define the competitive baseline, each bringing distinct capabilities to the market:
- Ace Tank and Fueling Equipment: Based in the United States, this firm specializes in customized, fully-equipped aboveground storage tanks tailored specifically for airport fuel distribution networks, emphasizing turnkey integration.
- Tate Metalworks: Also US-based, Tate focuses on field-erected solutions using stainless steel, duplex steel, and carbon steel. Their engineering focus is increasingly directed toward sustainable aviation fuel (SAF) compatibility alongside conventional fuel requirements.
- AGI Westeel: Operating out of Canada, AGI Westeel provides shop-fabricated aboveground steel aviation tanks designed to meet rigorous Canadian Aviation Regulations, ensuring safe storage protocols are met from the outset.
- Center Enamel: A China-based specialist, Shijiazhuang Zhengzhong Technology Co., Ltd., focuses on corrosion-resistant stainless steel tanks with aluminum dome roofs. Their systems are optimized for Jet A-1 fuel purity and high-volume applications, recently emphasizing ultra-cleanliness and modular containment.
- Unity Fuel Solutions: This US manufacturer emphasizes quality and cleanliness, producing double-walled aboveground storage tanks for Jet A-1 and Avgas, catering to airports with strict fuel handling standards.
- Fuelchief: From New Zealand, Fuelchief supplies the SuperVault Aviation range, offering 4-hour fire-rated flammable storage tanks suitable for everything from helipads to full jet operations, addressing critical safety ratings.
- Avioneco: Based in Poland, this company produces double-walled steel tanks in both mobile and stationary configurations. Their solutions cover AVGAS, JET-A1, and MOGAS, providing flexibility for airfields with varying refueling needs.
- SEI Industries: A Canadian manufacturer known for the Bulk Aviation Transport Tank (BATT), a collapsible tank approved for air transport of aviation fuel (Class 3 UN 1863), addressing logistics flexibility.
- Western Global: Located in the United States, they manufacture transportable and static fuel storage tanks, including models certified for aviation fueling applications, bridging the gap between mobility and fixed infrastructure.
- Varec: Also US-based, Varec provides end-to-end fuel management solutions, including tank farm automation and level measurement for storage tanks at major airports, adding a technology layer to physical storage.
- eN-TANK Sp. z o.o. sp.k.: A Polish entity specializing in steel double-wall tanks for petroleum products including aviation fuels since 2002, leveraging long-term experience in double-wall integrity.
- CZ Ltd: A UK supplier with over 60 years of experience, providing aviation fuel storage tanks and systems for Jet A1 and Avgas, representing a legacy of design and manufacture expertise.
Recent Industry Developments and Project Intelligence
Real-time intelligence on project commissioning and planning provides early signals of demand shifts. Our research team tracks these milestones to validate market momentum.
Aircraft Fuel Tanks Market
- Jefferson County Airport (February 2026): The completion of a 12,000-gallon unleaded aviation fuel bulk storage tank installation was reported as part of the AIP-70 Unleaded Fuel Tank Project. This initiative supports wholesale deliveries of Swift Fuels UL94, signaling a tangible shift toward unleaded alternatives in general aviation infrastructure.
- Center Enamel (November 2025): The release of advanced stainless steel Jet A-1 fuel storage tank systems emphasized ultra-cleanliness and zero-tolerance quality control. This product certification highlights the industry's move toward modular containment optimized for global aviation logistics and stricter purity standards.
- Sonoma County Airport (October 2025): The Board approved an engineering and budget study for a new aircraft fuel storage facility. The objective is to more than double existing storage capacity, indicating significant public investment in regional airport infrastructure to accommodate future traffic growth.
Regulatory and Material Market Context
Strategic planning cannot occur in a vacuum; it must account for the raw material environment and the regulatory framework governing storage safety and sustainability.
Raw Material Cost Dynamics
The cost of steel, a primary input for tank manufacturing, influences project budgets and margins. As of mid-2025, U.S. Midwest hot-rolled coil steel prices stabilized in the low to mid $800s per short ton, with futures indicating range-bound trading into early 2026. This stability offers a predictable input cost environment for North American projects. Meanwhile, Chinese steel rebar benchmark prices stood at 3,103 CNY per tonne as of April 2026. These divergent regional price points influence the competitive positioning of manufacturers sourcing materials globally, affecting the landed cost of imported tank systems versus locally fabricated ones.
Regulatory Standards and Compliance
Safety and environmental performance are governed by evolving standards. The publication of API Standard 650, 13th Edition for Welded Tanks for Oil Storage, enhances safety and sustainability requirements applicable to aviation fuel applications. Compliance with this standard is becoming a baseline expectation for new installations and major retrofits.
In the United States, federal policy is also shaping the economic viability of fuel storage associated with emerging fuel types. The Section 45Z Clean Fuel Production Credit provides applicable amounts ranging from $0.20 to $1.00 per gallon for non-SAF transportation fuels produced after December 31, 2025, with specific rules for domestically sourced feedstocks from the US, Mexico, or Canada. While this credit targets production, it indirectly incentivizes the storage and distribution infrastructure required to handle these fuels, stimulating demand for compliant storage solutions that can handle varied fuel chemistries.
Furthermore, physical safety standards remain paramount. Storage tanks for aviation fuel must comply with UL 142 for steel aboveground tanks for flammable and combustible liquids or UL 2085 for protected tanks. These standards are referenced in FAA and DOI aviation fuel management guidelines, making certification a prerequisite for operational legality in many jurisdictions. Ignoring these compliance pathways exposes operators to significant liability and operational risk.
Strategic Recommendations for 2026 and Beyond
For executives and investors, the data suggests several actionable strategic postures. First, the growth trajectory supports continued investment in storage capacity, particularly in regions showing high absolute revenue contribution like Asia Pacific and North America. However, success depends on navigating the complexity of tank types and installation methods. The dominance of Above-Ground Storage Tanks suggests that procurement strategies should prioritize AST suppliers with strong safety certifications and modular capabilities.
Second, the competitive landscape indicates that partnerships with specialized manufacturers who offer end-to-end management, such as tank farm automation, may provide a competitive edge. As seen with providers like Varec, integrating technology with physical storage enhances operational efficiency and reduces leakage risks. Third, the regulatory environment regarding unleaded fuels and SAF compatibility requires forward-looking procurement. Projects like the Jefferson County Airport installation demonstrate that early adoption of infrastructure capable of handling unleaded blends positions operators ahead of regulatory curves and fuel supply shifts.
Finally, supply chain resilience is critical given the variations in global steel pricing. Locking in supply agreements or utilizing local fabrication partners in stable price regions can mitigate margin erosion. The market is not merely about buying tanks; it is about securing a compliant, safe, and efficient fuel supply chain that can withstand the operational demands of the next decade.
Conclusion
The Worldwide Aviation Fuel Storage Tank Market offers a landscape of steady growth and evolving technical requirements. With a projected market size approaching 2.6 billion USD by 2032 and a CAGR of 5.19 percent, the opportunity for strategic positioning is substantial. However, realizing this value requires deep insight into the segmentation dynamics, competitive capabilities, and regulatory constraints that define the sector.
This article provides a high-level overview of the market intelligence available. To access the full granularity of data—including exact segment percentages, detailed regional growth matrices, comprehensive company profiling, and risk analysis frameworks—we invite you to explore the complete Worldwide Aviation Fuel Storage Tank Market research report. Equip your organization with the definitive intelligence needed to navigate the complexities of aviation fuel infrastructure in 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Worldwide Aviation Fuel Storage Tank Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com