

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global Rheology Modifier Coating Additive Market to Hit $4.79 Billion by 2032 at 4.8% CAGR

Strategic Intelligence in the Global Rheology Modifier Coating Additive Market: Key Insights for 2026 Decision-Makers
The global landscape for rheology modifier coating additives is undergoing a structural transformation driven by regulatory shifts, raw material volatility, and the accelerating transition to waterborne formulations. For executives navigating product portfolios, supply chain strategies, and capital allocation in 2026, surface-level market summaries are no longer sufficient. Comprehensive, granular intelligence is required to anticipate margin compression, identify high-growth application pockets, and benchmark competitive positioning against incumbents expanding capacity and launching next-generation chemistries. This newly released Worldwide Rheology Modifier Coating Additive Market study delivers precisely that depth. Designed as a decision-ready intelligence asset, the report synthesizes historical performance, forecast trajectories, and competitive dynamics into a cohesive framework that aligns with the strategic planning cycles of coatings manufacturers, additive suppliers, and downstream formulators.
Market Trajectory and the 2026 Inflection Point
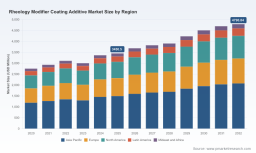
The sector has demonstrated consistent expansion across the historical review window, advancing from approximately 2.75 billion USD in 2020 to an estimated 3.45 billion USD by 2025. This growth reflects sustained formulation modernization across architectural, industrial, and protective coating segments, alongside tightening environmental mandates that favor rheology additives capable of maintaining application performance while reducing volatile organic compound content. Looking ahead, the forecast period from 2026 through 2032 projects a compound annual growth rate of 4.8 percent, positioning the market to surpass 4.79 billion USD by the terminal forecast year.
These aggregated figures represent more than a simple top-line projection. They encapsulate a market recalibrating around formulation efficiency, regulatory compliance, and regional manufacturing footprints. The trajectory indicates that demand will not be distributed uniformly; rather, it will concentrate in applications where viscosity control, sag resistance, and levelness are non-negotiable performance parameters. Understanding how these macro trends intersect with segment-specific drivers, supply chain constraints, and pricing mechanisms is critical for 2026 planning. The full report dissects these intersections without oversimplifying, enabling stakeholders to map growth vectors against their own product roadmaps and procurement strategies.
Executives should note that the forecast horizon extends beyond short-term cyclical fluctuations. The modeled expansion incorporates structural shifts in formulation preferences, regulatory compliance costs, and capacity adjustments by key producers. By grounding strategy in these forward-looking parameters, organizations can better align inventory planning, R&D focus, and partnership development with the market's actual growth architecture. The report provides the analytical scaffolding required to translate these projections into actionable commercial and operational decisions.
Competitive Architecture and Strategic Positioning
The rheology modifier coating additive sector is characterized by a moderately concentrated competitive landscape, with the top three players collectively commanding 38.4 percent of market revenue and the top five accounting for 52.15 percent. This concentration reflects decades of formulation expertise, established technical service networks, and continuous innovation in associative thickeners, organoclays, cellulose derivatives, and polyurethane-based modifiers. Yet the remaining share distribution underscores meaningful fragmentation at the regional and application-specific level, creating both competitive threats and partnership opportunities for incumbents and challengers alike.
Worldwide Rheology Modifier Coating Additive Market
Leading global suppliers have built differentiated value propositions around viscosity control mechanisms, compatibility with low-VOC and solventborne systems, and rapid technical support for formulators. Major players headquartered across North America, Europe, and Asia maintain extensive portfolios spanning organoclays, hydrophobically modified ethoxylated urethanes, polyamide waxes, fumed silica-based additives, and cellulosic thickeners. Their product architectures are increasingly tailored to meet application-specific demands in architectural paints, industrial coatings, automotive finishes, wood and furniture coatings, and marine protective systems. The report profiles these core companies in detail, mapping their product ranges, geographic reach, formulation specialties, and recent strategic moves that signal where each competitor is placing its commercial bets.
Rheology Modifiers Market
Recent corporate activities illustrate the pace of competitive maneuvering. In late 2025, a global leader in organoclay and associative thickeners introduced a VOC-free organoclay rheology modifier engineered for enhanced sag resistance in waterborne coatings, directly addressing the formulation constraints of decorators and industrial painters. Earlier in the same year, a major North American chemical supplier launched a hydrophobically modified alkali-swellable emulsion grade designed to deliver high-shear viscosity in low-VOC paints, reflecting the industry's push for application robustness without compromising environmental performance. Alongside these product launches, certification milestones and production expansions have reshaped the competitive baseline. A prominent European supplier secured EU Ecolabel certification for a polyurethane-based rheovis modifier tailored to low-emission interior coatings, reinforcing its positioning in sustainability-driven architectural segments. Meanwhile, capacity expansions at European manufacturing sites have increased output of specific associative thickeners by roughly 20 percent, underscoring the strategic importance of securing supply for waterborne formulation growth.
These developments are not isolated product news; they are indicators of where value creation is shifting. The report analyzes how each competitive action influences pricing power, formulation substitution risks, and regional supply dynamics. By benchmarking your organization's capabilities against these moves, you can identify gaps in technical service, formulation support, or portfolio coverage that may affect win rates in key customer segments.
Regulatory Currents and Raw Material Dynamics Shaping Formulation Economics
The 2026 planning environment is heavily influenced by regulatory and input-cost variables that directly affect formulation economics and additive selection. Recent regulatory updates have introduced compliance considerations that formulators and suppliers must navigate carefully. Restrictions under EU chemical regulations now limit certain associative thickeners containing nonylphenol ethoxylates above threshold concentrations, prompting reformulation efforts and supplier qualification updates across European and export-oriented markets. In parallel, regional hazard communication requirements in the United States have mandated warning labels for specific thickener chemistries containing unreacted acrylamide, affecting labeling, documentation, and customer communication workflows for decorative and industrial coating producers.
Raw material pricing volatility adds another layer of complexity. Key solvent inputs used in solventborne rheology modifier formulations have experienced notable price fluctuations, with certain glycol ether acetate derivatives averaging elevated levels in late 2025. Simultaneously, isobutanol feedstock costs rose significantly year-over-year due to supply disruptions in the US Midwest, affecting the cost base for certain associative thickener and wax-based systems. These input dynamics do not impact all chemistries equally, which is why understanding the cost structure and substitution elasticity across organic and inorganic rheology modifiers is essential for margin protection.
Trade policy developments further complicate the procurement landscape. Adjustments to US tariff schedules on imported cellulose ethers have increased duty burdens on certain raw material streams, altering the relative cost competitiveness of regional supply chains. For formulators balancing performance, regulatory compliance, and total cost of ownership, these shifts create both risk and opportunity. The report evaluates how regulatory timelines, feedstock price trajectories, and trade measures intersect with segment demand, helping stakeholders anticipate formulation pivots, supplier transitions, and pricing negotiations in 2026 and beyond.
Application-Level Demand Drivers and Formulation Priorities
Demand for rheology modifiers is not uniform across end-use categories. Architectural coatings continue to represent a substantial share of consumption, driven by renovation cycles, housing activity, and the ongoing shift toward waterborne decorative formulations that require precise viscosity control, open time management, and sag resistance. Industrial coatings contribute a significant and technically demanding demand base, where shear-thinning behavior, anti-sag performance, and compatibility with high-solids systems are critical for achieving consistent film formation across metal, plastic, and composite substrates. Automotive coatings impose stringent aesthetic and performance requirements, with rheology additives playing a crucial role in gloss uniformity, levelness, and application robustness under varying shop conditions.
Wood and furniture coatings, as well as marine and protective coatings, represent additional demand pillars with distinct formulation challenges. These segments often require additives that can withstand harsh environmental exposure, maintain stability in solventborne and high-solids systems, and deliver consistent rheological performance across diverse pigment and filler loadings. The report examines how application-specific performance expectations shape additive selection, technical service requirements, and pricing dynamics, highlighting where formulation innovation is translating into commercial differentiation.
Importantly, the growth in waterborne and low-VOC systems is reshaping the relative attractiveness of organic versus inorganic rheology modifiers. Associative thickeners, hydrophobically modified polymers, and advanced cellulosic systems are gaining prominence in segments where environmental compliance and application performance must be balanced. Inorganic thickeners, including organoclays and fumed silica, continue to serve critical roles in solventborne and high-solids applications where thixotropic control and anti-sag properties are paramount. The full analysis delineates how these chemistry preferences evolve across regions and applications, providing a clear view of where substitution risk and portfolio expansion opportunities are most pronounced.
What the Report Delivers: Operational Intelligence for 2026 Planning
This market study is structured to move beyond high-level summaries and deliver operational intelligence that can be immediately integrated into strategy, procurement, and R&D processes. The report provides a comprehensive segmentation framework that maps market size, growth trajectories, and competitive intensity across region, type, and application dimensions. Stakeholders gain visibility into where demand is consolidating, where regional manufacturing footprints influence supply security, and which application categories are driving the most technically advanced rheology modifier requirements.
The competitive profiling section delivers detailed assessments of leading suppliers, including their headquarters, core product families, formulation specialties, and strategic positioning within architectural, industrial, automotive, wood, and marine coating markets. These profiles are complemented by a timeline of recent corporate developments, including product launches, grade introductions, capacity expansions, and certification achievements. By connecting these actions to broader market trends, the report helps readers interpret competitor intent and anticipate shifts in technical service emphasis, portfolio focus, and regional availability.
Beyond competitive and segmentation analysis, the study integrates market concentration metrics to clarify the balance between incumbent dominance and niche competition. This context is essential for assessing pricing dynamics, negotiating leverage, and the feasibility of entering or expanding within specific sub-segments. The report also examines how regulatory timelines, raw material cost movements, and trade policy adjustments are affecting formulation economics, providing a practical lens for evaluating supplier alternatives, inventory strategies, and cost pass-through mechanisms.
For organizations seeking to align product development with market demand, the report outlines the performance parameters that increasingly drive additive selection, including viscosity buildup characteristics, shear-thinning behavior, compatibility with waterborne and solventborne systems, and compliance with evolving environmental standards. These insights are designed to inform technical service roadmaps, customer messaging, and cross-functional planning across R&D, sales, and supply chain teams. By consolidating market sizing, competitive intelligence, regulatory context, and application-level demand drivers into a single authoritative source, the study reduces the time and uncertainty associated with piecing together fragmented data from multiple channels.
Translating Market Intelligence into 2026 Action
The strategic value of this report lies in its ability to convert complex market signals into clear decision frameworks. For coatings manufacturers, the analysis supports formulation portfolio optimization, raw material sourcing strategies, and regional expansion priorities. For additive suppliers, the study provides a detailed view of competitor positioning, customer formulation trends, and capacity allocation signals that inform technical service investments and product launch timing. For downstream stakeholders and investors, the report offers a structured perspective on market concentration, growth vectors, and the regulatory and cost variables that will shape profitability through the end of the decade.
In a market where performance expectations are rising, regulatory compliance is intensifying, and raw material costs are subject to regional disruptions, information advantage translates directly into commercial resilience. The report is designed to deliver that advantage by providing granular, decision-grade intelligence that goes well beyond aggregated headline figures. Stakeholders who integrate these insights into their 2026 planning cycles will be better positioned to navigate formulation transitions, manage supply chain volatility, and capture growth in the segments where rheology modifiers are becoming increasingly indispensable.
To access the complete segmentation analysis, full competitor profiles, detailed regional and application breakdowns, and the comprehensive regulatory and raw material assessments that underpin the forecast model, please visit the source page for the Worldwide Rheology Modifier Coating Additive Market research. The full report provides the depth and precision required to turn market intelligence into executable strategy across 2026 and the forecast horizon.
For detailed analysis of this topic, please visit the official page: Worldwide Rheology Modifier Coating Additive Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com