

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Tendinitis Market Hits $218.65M in 2025, Forecast 4.71% CAGR Through 2032

Strategic Intelligence for the Next Wave: Inside the Worldwide Tendinitis Treatment Market
The global landscape for tendinitis treatment is undergoing a structural transformation. Driven by an aging athletic population, rising prevalence of overuse injuries, and rapid advancements in minimally invasive procedural technologies, the market has evolved from a commoditized pain management segment into a sophisticated ecosystem of biologics, robotics, and specialized rehabilitation protocols. For healthcare providers, medical device manufacturers, and investment stakeholders, understanding the trajectory of this market is no longer optional—it is a critical component of capital allocation and product development strategy.
PW Consulting's latest comprehensive study, the Worldwide Tendinitis Treatment Market report, delivers a granular analysis of this evolving sector. Spanning historical performance from 2020 through 2025 and offering a robust forecast horizon from 2026 to 2032, this research is designed to equip decision-makers with the foresight required to navigate upcoming regulatory shifts, reimbursement changes, and competitive displacements. This article serves as a strategic preview of the report's core findings, illustrating why this intelligence is essential for 2026 enterprise planning.
Macro Trends and Growth Trajectory
The tendinitis treatment sector has demonstrated remarkable resilience and consistent expansion over the past half-decade. Historical data indicates that the global market generated revenue of approximately 172,450 million USD in 2020, climbing steadily to reach 207,737 million USD by 2024. This upward momentum continued into the base year of 2025, with the market valuation establishing itself at 218,650 million USD.
Looking forward, the growth trajectory remains positive, albeit maturing. The market is projected to breach the 219,000 million USD threshold in 2026, signaling a stabilization phase before the next acceleration cycle. By the end of the forecast period in 2032, the worldwide tendinitis treatment market is expected to surpass 301,764 million USD. This expansion is underpinned by a Compound Annual Growth Rate (CAGR) of 4.71 percent throughout the 2026 to 2032 forecast window.
For strategic planners, this CAGR suggests a market that is growing faster than general healthcare inflation but requires precise segmentation to capture value. The jump from roughly 241,717 million USD in 2027 to over 296,372 million USD by 2031 highlights a significant inflection point likely driven by the adoption of advanced biologic implants and robotic-assisted surgical suites. Organizations that position their portfolios ahead of this 2027 to 2031 acceleration window will be best placed to secure market share.
Competitive Landscape and Key Players
The market structure is characterized by moderate concentration, with the top three players holding a combined share of 18.45 percent and the top five accounting for 26.82 percent. This fragmentation indicates ample room for niche innovators and specialized boutique manufacturers to thrive alongside industry giants. However, the competitive dynamics are shifting as large conglomerates acquire specialized technologies to bolster their orthopedic portfolios.
Leading the charge is Smith & Nephew, headquartered in London, UK. Their strategy focuses heavily on biologic augmentation and minimally invasive tenotomy. Notably, in October 2024, Smith & Nephew received 510(k) clearance for the next-generation REGENETEN Bioinductive Implant, featuring an enhanced resorption profile designed to accelerate tendon healing. This regulatory milestone underscores their commitment to dominating the rotator cuff and general tendinopathy segments.
In the United States, Arthrex, based in Naples, Florida, continues to strengthen its foothold in arthroscopic interventions. Their September 2024 product launch of the FiberRing XS suture specifically targets small tendon repairs in upper extremity procedures, addressing a high-volume clinical need in tennis elbow and rotator cuff pathologies. Similarly, Stryker, headquartered in Kalamazoo, Michigan, is leveraging robotics to precision-engineer tendon repairs. Their March 2024 expansion of Mako robotic-arm assisted systems through partnerships with ambulatory surgery centers represents a strategic move to capture outpatient procedure volume, which is growing faster than inpatient settings.
Elbow Stiffness Treatment Market
The competitive field also includes major contributions from DePuy Synthes (Johnson & Johnson) and Zimmer Biomet, both of which are integrating knotless anchor systems and surgical mesh solutions like Regeneten into their standard offerings. CONMED, based in Largo, Florida, maintains a strong position in suture management with their Y-Knot RC all-suture anchors. Furthermore, the acquisition and integration of Tenex Health by Stryker highlights a pivotal industry trend: the convergence of ultrasonic tenotomy technologies with broader orthopedic distribution networks. Tenex Health's June 2024 clinical study results, showing 89 percent pain reduction in chronic tendinitis patients, provide the clinical evidence necessary to justify premium pricing and insurance coverage expansions.
Treatment Modalities and Clinical Segmentation
The market is diversified across several treatment types, each facing distinct adoption curves and reimbursement hurdles. Medication remains a foundational pillar of the market, capturing the largest share of revenue due to the high volume of initial presentations for pain management. However, the growth rate in this segment is stabilizing as clinicians and patients increasingly seek curative rather than palliative solutions.
Physical therapy constitutes a significant portion of the market value, driven by the essential role of rehabilitation in preventing recurrence. Yet, the most dynamic growth is observed in procedural interventions. Shockwave therapy has gained traction as a non-invasive middle ground, while surgical interventions remain critical for severe cases. Within the surgical segment, the shift is unequivocally toward minimally invasive techniques. Knotless anchors, bioabsorbable sutures, and robotic assistance are redefining the standard of care.
Condition-specific analysis reveals that Rotator Cuff Tendinitis and Achilles Tendinitis represent substantial portions of the clinical volume. Patellar Tendinitis and Tennis Elbow also contribute significantly, particularly in sports medicine and occupational health contexts. Each condition presents unique biomechanical challenges that require tailored implant solutions, from foot and ankle specific systems provided by Wright Medical to upper extremity sutures from Arthrex. Understanding the interplay between these condition-specific demands and the available technological solutions is vital for product managers and clinical procurement officers.
Regulatory and Economic Dynamics
Navigating the tendinitis treatment market requires a deep understanding of the regulatory and economic environment. In the United States, the FDA classifies tendon repair scaffolds as Class II devices. This classification requires 510(k) premarket notification under product code MWO, a process that shapes the timeline for new product introductions. Companies must maintain rigorous documentation to demonstrate substantial equivalence to existing predicates.
Across the Atlantic, the European Union's Medical Device Regulation (EU MDR) imposes stricter requirements. Notified Body certification is mandatory for tendon implants under Rule 8, with clinical evaluations needing to adhere to MEDDEV 2.7/1 Rev 4 guidelines. These regulatory frameworks increase the barrier to entry for new competitors but provide a moat for established players who have already secured compliance.
Worldwide Tendinitis Treatment Market
On the economic front, reimbursement policies play a pivotal role in procedure adoption. Under the 2025 Medicare Physician Fee Schedule, CPT code 28285 for tendon repair procedures reimburses an average of 1,200 USD. This reimbursement level influences the viability of outpatient surgeries versus inpatient stays. Additionally, material costs remain a key variable for hospital procurement teams. Medical-grade PLLA bioabsorbable suture anchors typically cost between 150 and 250 USD per unit in bulk procurement for tendinitis kits. Margins are tightly linked to supply chain efficiency and volume contracting.
It is also important to note specific usage limitations. For instance, the TENEX tenotomy system is cleared for research use only in investigational protocols outside its labeled indications. Stakeholders must ensure compliance with Instructions for Use (IFU) to avoid liability risks during off-label adoption campaigns.
Strategic Value for 2026 Decision Making
Why does this detailed intelligence matter for 2026 planning? The answer lies in the convergence of clinical evidence, regulatory approval, and market access. The 4.71 percent CAGR is not uniform across all segments. Growth will be disproportionately captured by companies that can demonstrate superior clinical outcomes, such as the 89 percent pain reduction data published by Tenex Health, and those that can navigate the reimbursement landscape effectively.
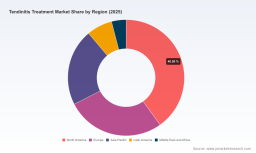
For device manufacturers, the report provides actionable insights into where to direct R&D spend. The data suggests that bioinductive implants and robotic-assisted precision tools are the high-growth vectors, while traditional suture anchors may face margin pressure due to commoditization and bulk pricing dynamics. For healthcare providers, understanding the regional demand shifts and the availability of ambulatory surgery center partnerships is crucial for infrastructure investment.
Furthermore, the moderate market concentration indicates that consolidation is possible. Strategic acquirors looking to enter or expand in this space should monitor the pipeline of startups focusing on ultrasonic tenotomy and biologic scaffolds. Investors need to assess which companies have cleared the regulatory hurdles of 510(k) or EU MDR certification, as these milestones are primary drivers of valuation multiples in this sector.
Conclusion and Accessing Full Intelligence
The Worldwide Tendinitis Treatment Market is at a pivotal juncture. The historical stability from 2020 to 2025 has laid a strong foundation, but the forecast period from 2026 to 2032 promises dynamic changes driven by technology and regulation. With revenues projected to exceed 300 billion USD by the end of the decade, the opportunity is vast, but so is the complexity.
This article has outlined the macro trends, competitive maneuvers, and regulatory constraints shaping the industry. However, successful execution requires granular data that goes beyond high-level summaries. Detailed segmentation breakdowns, specific regional revenue forecasts, granular competitor profiling, and proprietary supply chain analysis are essential for crafting a winning strategy.
To access the full depth of this analysis, including the complete segmentation splits, detailed company profiles, and the comprehensive forecast model, we invite you to explore the full Worldwide Tendinitis Treatment Market research report. Equip your organization with the precise data needed to lead in 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Worldwide Tendinitis Treatment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com