

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Category: market research
PW Consulting: Omega‑3 Products market to expand at 6.98% CAGR through 2032
By pmarketresearch, 2026-07-30
Omega‑3 Products Market: Strategic Briefing for 2026 Decision‑Makers
Executive summary
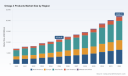
As global health narratives and sustainability imperatives converge, the omega‑3 products market is entering a structurally transformative phase. Our latest PW Consulting market study — with a base year of 2025 and a forecast window spanning 2026–2032 — shows continued expansion at a compound annual growth rate (CAGR) of 6.98%. The market measured USD 11,314.42 Million in 2025 and, under our baseline scenario, is forecast to more than double by the end of the modelling period. For executives preparing investment, portfolio, or go‑to‑market choices in 2026, this study is designed to convert epidemiological, consumer and regulatory trends into executable commercial actions.
Omega 3 Products Market
Why this research matters for 2026 strategy
-
From opportunity timing to risk mitigation: 2026 is a turning point. Growth is no longer linear; it is being re‑cast by ingredient innovation (notably microalgal and other non‑marine sources), regulatory tightening, and accelerating e‑commerce adoption. Firms that align upstream sourcing, formulation and digital distribution now will secure scale advantages as the market matures.
Omega 3 Products Market -
Clarity for allocation decisions: with overall market momentum established, the pressing question for boards and strategic planning teams is not whether to play, but where and how much to invest. Our modelling translates high‑level growth into probabilistic outcome bands that support capital budgeting, plant investment, and M&A prioritization under multiple macro scenarios.
Omega 3 Products Market -
Actionable compliance readying: regulatory attention on dietary supplements has intensified. Anticipated rule‑making and process modernization initiatives in 2026 raise execution risks for product launches and cross‑border supply chains. The study provides regulatory readiness frameworks that map probable timelines and required controls to practical program milestones.
What the report delivers — practical, operational intelligence
-
Market sizing and trajectory: a transparent reconciliation of historical performance (2020–2025) against forward projections (2026–2032), with scenario lenses (conservative, baseline, upside) and sensitivity to raw‑material price shocks.
-
Commercial playbooks: channel‑specific GTM templates (DTC/e‑commerce, brick‑and‑mortar, pet food, infant nutrition and pharma pathways) tailored to ingredient form (triglyceride vs. ethyl ester vs. algal concentrates) and consumer purchase behaviors.
-
Supplier and manufacturing scorecards: independent assessments of ingredient producers, contract manufacturers and third‑party certifiers, including operational capacity, sustainability credentials, traceability practices and unit economics.
-
Regulatory risk heatmaps and GRAS readiness checklists: step‑by‑step compliance actions keyed to the FDA’s 2026 priorities for recall process modernization and planned guidance around new‑substance notices.
-
Financial and M&A analytics: target screening for bolt‑on acquisitions, accretion/dilution modelling, and integration playbooks aligned to consolidation scenarios consistent with observed market concentration metrics.
Competitive landscape — what leading players are doing in 2026
The market remains moderately fragmented: our competitive concentration analysis indicates that the three largest players account for roughly a quarter of market value, and the top five capture only marginally more — a structural signal of opportunity for consolidation and scale plays.
-
Aker BioMarine (Lysaker, Norway) — continues to leverage its brand and R&D orientation in krill and algae solutions. Recent participation at Vitafoods India 2026 to introduce a high‑concentration algae DHA demonstrates a dual strategy: expand into higher‑margin sustainable ingredients while reinforcing global distribution relationships.
-
GC Rieber VivoMega (Kristiansund, Norway) — has focused on high‑potency triglyceride concentrates for nutraceuticals. Its early‑2026 launch of a high‑potency algal TG product signals a deliberate push to capture demand from vegan and label‑conscious consumer segments.
-
dsm‑firmenich (Kaiseraugst, Switzerland) — is pursuing scale in North America, evidenced by a multi‑million dollar upgrade of regional premix capacity and product introductions targeted at adjacent categories (e.g., pet nutrition). Their activity underlines a platform strategy: combine ingredient IP with customer‑facing formulation services.
-
Corbion (Gorinchem, Netherlands) — remains focused on algal DHA for infant and plant‑based markets, maintaining a differentiated stance on sustainability and system integration with infant formula makers.
-
Pharma Marine (Søvik, Norway) and Neptune Wellness Solutions (Toronto) — represent suppliers that blend marine sourcing with certification playbooks, positioning for customers looking for traceability and sustainability assurances.
-
Omega Protein Corporation (Houston) — continues to be a strategic supplier for high‑volume fish oil requirements, relevant for companies that prioritize cost and scale.
Recent industry movements worth tracking
-
Product innovation: several suppliers introduced concentrated algal and marine omega‑3 ingredients in early 2026, sharpening the competitive boundary between traditional marine oils and next‑generation non‑marine sources.
-
Capacity and capability investments: modernization projects in premix and formulation centers reflect supplier bets on faster time‑to‑market in the Americas and pet nutrition expansion.
-
Certification and sustainability signaling: suppliers are increasingly using third‑party sustainability credentials to underpin premium pricing and secure partnerships with consumer brands that require verified chain‑of‑custody.
Market dynamics, headwinds and strategic implications
-
Raw‑material volatility: fluctuations in marine by‑product and shellfish markets materially affect manufacturing margins. Scenario analysis in the report quantifies margin impacts across sourcing choices and shows where hedging, multi‑supplier contracts and backward integration alter outcomes.
-
Regulatory tightening: the FDA’s 2026 agenda — including recall modernization and proposed requirements for broader GRAS submissions — elevates the cost of non‑compliance. Firms should accelerate product documentation, expand lot‑level traceability, and budget for faster response capabilities.
-
Consumer purchase shifts: online grocery and direct e‑commerce channels now represent a significant share of sales in 2026, driving demand for smaller‑format, single‑serve and subscription‑friendly omega‑3 SKUs. Brands that adapt packaging, fulfillment and digital engagement see larger conversion and retention gains.
-
Fragmentation and consolidation dynamics: with the market concentration metrics indicating room for scale economies, well‑capitalized players and PE sponsors will find attractive arbitrage between manufacturing optimization and brand roll‑ups.
Actionable plays for 2026 — 90‑day and 12‑month roadmaps
-
90‑day priorities: complete an audit of supplier traceability; run a GRAS/compliance gap assessment for all SKUs; pilot a high‑potency algal SKU with a small e‑commerce partner; stress‑test contracts for raw‑material price pass‑through clauses.
-
12‑month priorities: establish a multi‑source ingredient strategy; pursue targeted capacity upgrades or tolling arrangements; execute one focused acquisition to capture distribution or ingredient IP; implement lot‑level serialization and a rapid recall playbook aligned to regulatory timelines.
Why PW Consulting’s Omega‑3 Report is the right decision tool
Our study is built to be operational: not an archive of descriptive statistics, but a toolkit for deployment. It combines detailed market modelling (historical 2020–2025, base year 2025, forecast 2026–2032), supplier due diligence templates, regulatory readiness matrices and commercial playbooks that link to P&L and cash‑flow implications. We preserve confidentiality of sensitive sub‑segment datasets in this overview so executives can assess strategic direction quickly; the full dataset, including granular regional and application breakouts, pricing curves, and supplier scorecards, is available via the report portal.
Next steps
-
If you are setting 2026 capex or M&A mandates, use our scenario modules to quantify downside exposure to raw‑material shocks and regulatory cost ramps.
-
If you are a commercial or R&D leader, review the GTM templates and pilot planning checklist to reduce time‑to‑launch for algal and alternative omega‑3 SKUs.
-
For investor teams, our competitive concentration analysis and deal‑scoping tools identify the most accretive target profiles within current consolidation dynamics.
To access the complete intelligence set — including the granular segmentation that underpins the figures summarized here and executable annexes for procurement, regulatory and commercial teams — please consult the full PW Consulting Omega‑3 Products Market report on our website.
For detailed analysis of this topic, please visit the official page: Omega 3 Products Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: CMTS/QAM Market to Reach USD 7,494M by 2032 at 8.8% CAGR
By pmarketresearch, 2026-07-30
CMTS & QAM Market 2026: Strategic Intelligence for Executive Decision-Makers
By PW Consulting — Senior Strategic Advisor & Chief Industry Analyst
CMTS/QAM Market
Executive teaser
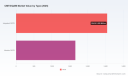
The global CMTS (Cable Modem Termination System) and QAM (Quadrature Amplitude Modulation) market has moved from a niche operator concern into a decisive infrastructure topic for broadband strategy. Our CMTS/QAM Market research, anchored on 2025 as base year and a multi-year historical series (2020–2025), projects sustained momentum through 2032. The market expands from a multi‑billion dollar base in 2025 to an even larger addressable opportunity by 2032, driven by DOCSIS evolution, virtualization, and video distribution models. Over the 2026–2032 forecast window we model an 8.8% CAGR — a rate that demands active strategic choices in procurement, architecture, and ecosystem partnerships during 2026.
CMTS/QAM Market
Why this matters for 2026 strategy
Service providers and vendors face a convergence of three strategic pressures: accelerating customer demand for multi‑gigabit services, the economics of headend consolidation, and an industry trajectory toward cloud‑native, software‑defined access. These forces create a binary set of choices for network executives in 2026: move decisively to virtualized, distributed architectures with vendor interop and managed transition paths — or manage rising OpEx and capacity constraints by extending legacy architectures with incremental upgrades.
CMTS/QAM Market
- Timing matters: the projected 8.8% CAGR amplifies the cost of delay. Every quarter of deferred modernization compounds capacity and support costs, and reduces negotiating leverage with suppliers.
- Architecture choices are strategic bets: hardware‑centric CCAP/CMTS platforms remain relevant, but virtual CMTS (vCMTS) and cloud‑native implementations materially alter TCO profiles and upgrade cadence.
- Regulatory and security contours are changing: industry‑wide interoperability events and security‑focused interop sessions in 2026 underline that vendor compatibility and secure software lifecycles will be procurement differentiators.
What the research delivers (practical toolkit)
This report is built as an operational playbook for decision‑makers, not an academic exercise. Highlights include:
- Market sizing and trend analytics: a validated historical series (2020–2025) and scenario‑based forecasts to 2032 that quantify the macro opportunity and downside sensitivities.
- Adoption curves and migration roadmaps: tested deployment templates for phased DOCSIS 3.1→4.0 and vCMTS adoption, with milestone‑based gating criteria to align CapEx cycles with customer demand.
- TCO and CapEx/OpEx models: comparative analyses showing the inflection points where virtualization becomes financially attractive, including power, rack‑space, and personnel assumptions.
- Interoperability matrix and vendor readiness scoring: vendor capabilities assessed against criteria such as DOCSIS feature parity, QAM integration, cloud‑native maturity, and security posture.
- Procurement playbook: negotiation levers, SLA templates, and upgrade path clauses designed to protect operators during multi‑year migrations.
- Risk register and mitigation playbooks: scenarios spanning component cost volatility, supplier consolidation, and interoperability lags, with practical mitigation steps.
Competitive landscape — what to watch in 2026
The market structure features a mixture of global incumbents, specialist vendors, and emerging cloud‑native challengers. Aggregate concentration indicates meaningful scale among the top players, yet the vendor field remains sufficiently fragmented to allow strategic sourcing options.
- Cisco Systems — a traditional incumbent with integrated CMTS/Edge QAM platforms that continue to serve large operators requiring tightly integrated hardware solutions. Strengths: global field support, breadth of platform functionality, and legacy operator relationships. Watch: migration path toward greater software modularity and cloud interop.
- Arris Group — positioned with high‑density CCAP and Edge QAM offerings suitable for operators wanting a path from video‑dense headends to combined data/video services. Strengths: density and service provider familiarity. Watch: roadmap alignment to DOCSIS 4.0 and virtualization.
- Casa Systems — a leading voice for virtual CCAP/vCMTS and distributed access. Strengths: DAA‑oriented solutions and strong software stacks for operators planning cloud migration. Watch: commercial scalability and integration with third‑party virtualization platforms.
- Harmonic Inc. — notable for cloud‑native vCMTS and Edge QAM products and recent contract wins supporting DOCSIS 4.0 pilots. Strengths: cloud‑first approach and strong presence in video streaming stacks. Watch: execution on large‑scale Unified DOCSIS projects.
- Vecima Networks — a specialist whose Entra vCMTS and video QAM management solutions are increasingly selected by operators pursuing cloud‑native modernization. Strengths: interoperability focus and tailored modernization offers. Watch: ability to scale to multi‑operator contracts.
- Huawei, WISI, Sumavision, Teleste and regional OEMs — provide alternative technology and price points, especially in markets where regional supply diversity or localization matters. Strengths: cost competitiveness and regional support models. Watch: compliance, interoperability, and long‑term software support commitments.
- Smaller entrants (e.g., C9 Networks, Chongqing Jinghong) — bring niche innovation and targeted platform features; suitable for pilots and regional rollouts but require caution on roadmaps and support SLAs.
Recent industry signals that change tactical choices
Market signals over the past 18 months accelerate the need for decisive choices in 2026:
- Contract awards to cloud‑native vCMTS suppliers demonstrate operator willingness to shift away from pure hardware dependency. Selected deployments validate scale and commercial models for virtualization.
- Interoperability events organized by CableLabs in early 2026 expanded DOCSIS 4.0 testing, explicitly adding security and multi‑vendor interop scenarios — a positive for operators requiring vendor agnosticism but also a warning that multi‑vendor integration carries execution risk if not planned.
- Partnerships in Distributed Access Architecture (DAA) deployments signal a move toward disaggregated headend functionality; procurement teams must therefore evaluate components for fit in both centralized and distributed topologies.
Cost and technology dynamics to factor into 2026 decisions
Two structural cost dynamics will shape vendor selection and architecture choices:
- Hardware complexity: DOCSIS 3.1/4.0 implementations demand advanced LDPC error correction and OFDM/OFDMA modulation support, which drives higher component and unit costs versus legacy 256‑QAM platforms. These costs must be weighed against lifecycle benefits and per‑subscriber capacity gains.
- Virtualization economics: relocating CMTS functions to commercial off‑the‑shelf servers can materially reduce headend footprint and power consumption; however, the financial case depends on virtualization maturity, orchestration overhead, and integration with existing OSS/BSS systems.
Actionable recommendations for 2026 — a concise checklist
- Run a staged migration pilot: prioritize vCMTS pilots with clearly defined KPIs (latency, throughput, operational overhead) before committing to network‑wide rollouts.
- Embed interoperability clauses: require multi‑vendor interop certification milestones and security audit results as part of procurement contracts.
- Quantify TCO with sensitivity testing: model scenarios where virtualization yields breakeven at different energy, personnel, and capacity assumptions to inform CapEx timing.
- Protect upgrade optionality: include modular upgrade and rollback clauses to preserve options as DOCSIS standards and vendor roadmaps evolve.
- Align procurement with architecture: build vendor shortlists around target architecture — centralized CCAP, hybrid DAA, or fully distributed vCMTS — rather than selecting vendors first and forcing design later.
- Monitor supply and regulatory tides: track interoperability events and regulatory guidance that may change timelines for secure DOCSIS 4.0 rollouts.
What we intentionally withhold here — and why
To preserve the strategic "trailer" value of this briefing, detailed segmentation tables — including regional and application breakouts, and granular vendor share by subsegment — are only available in the full CMTS/QAM Market report. The high‑level market trajectory, CAGR, and practical implications for 2026 strategy are disclosed here to inform executive decisions; the granular splits, procurement‑grade vendor scorecards, and downloadable TCO models are provided in the paid report to ensure decision teams have a single canonical source for negotiations and planning.
Next steps
Executives preparing procurement or network transformation roadmaps in 2026 should request the full PW Consulting CMTS/QAM Market report to obtain:
- Operational playbooks and vendor scorecards for procurement teams.
- Downloadable TCO models and scenario planners tailored to operator scale.
- Access to proprietary interoperability matrices and secure‑by‑design checklists that are updated against the latest CableLabs testing outcomes.
PW Consulting will be publishing an executive briefing series and supporting workshops in Q3 2026 to help operators convert these findings into 12–36 month execution plans. For operators and vendors seeking to participate in workshop engagements or to obtain the full dataset and annexes, visit our report page or contact our advisory desk.
For detailed analysis of this topic, please visit the official page: CMTS/QAM Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Slitter Market Set to Expand at 6.2% CAGR Through 2032
By pmarketresearch, 2026-07-30
Slitter Market 2026 Strategic Outlook — A PW Consulting Preview
As companies finalize capital allocation and product roadmaps for 2026, understanding the slitter market’s structural dynamics has moved from useful to essential. This preview synthesizes the strategic implications drawn from PW Consulting’s new Slitter Market research (base year 2025, historical 2020–2025, forecast 2026–2032). It signals where opportunities, supply risks, and competitive inflection points will occur — and how executives should reframe decisions to capture durable advantage. Note: this piece is intentionally high-level. Core segment-level detail and granular tables are reserved for the full report to preserve its tactical value.
Slitter Market
Market Trajectory: What the Numbers Tell Us
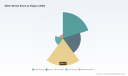
The slitter market has demonstrated steady expansion through the first half of the decade, growing from an estimated market size in 2020 to a substantially larger base in 2025. Our forecast models, calibrated across demand-side drivers and supply-side constraints, project a compound annual growth rate (CAGR) of 6.2% through the 2026–2032 horizon, with the overall market continuing to expand meaningfully by 2032. These aggregate trends signal a mid-single-digit growth regime that is large enough to justify targeted investment yet selective enough to reward disciplined segmentation and execution.
Slitter Market
Two observations follow immediately from the headline trajectory. First, above-market growth pockets will be tied to semiconductor packaging, advanced films, and precision electronics applications — areas where tolerance and automation premiums justify higher unit ASPs and aftersales revenue. Second, cyclical pressures and episodic raw-material shocks will create idiosyncratic timing opportunities to acquire capacity or enter adjacencies at favorable valuations.
Slitter Market
Demand Drivers and Technology Inflection Points
- Electronics miniaturization and panel-level packaging (PLP): The transition toward larger glass panels and PLP-compatible workflows is reshaping machine specifications. Equipment that supports panel-level processing and high-throughput film handling commands strategic importance.
- Higher-precision requirements: Micron-level tolerances for thin metal and copper strips are raising the bar on machine rigidity, blade technology, and inline metrology integration.
- Aftermarket and service revenue: As capital intensity rises, so does the lifetime value of installed bases. Service contracts, retrofit kits, and consumables will be decisive contributors to margin expansion.
- Automation and integration: Buyers increasingly prefer slitter systems that integrate seamlessly into MES/Industry 4.0 stacks, reducing manual intervention and improving uptime.
Supply Chain, Materials, and Regulatory Stressors
Macro and micro supply constraints materially affect deployment timing and cost curves. Key dynamics to account for in 2026 decisions:
- Component lead times: Precision optics and specialty gas shortages have extended lead times beyond six months in many cases, forcing firms to build inventory buffers or secure prioritized allocations.
- Raw-material price volatility: Critical inputs such as copper have experienced sharp price spikes, crossing materially elevated thresholds in 2026. This raises the cost of slitting solutions for copper foil and thin strip applications and compresses gross margins unless recovered through pricing or design efficiencies.
- Regulatory compliance: Market access requirements remain in flux. In the European context, continued compliance with key machinery safety directives is required for market entry through January 2027, and high-precision slitters used for thin copper strips face specific tariff/HTS classifications with commercial implications.
- Labor and sourcing: Rising labor costs and geopolitical uncertainty make multi-sourcing mandatory for many OEMs; single-source strategies expose manufacturers to interruption risks and potential contractual penalties.
Competitive Landscape — Where the Power Sits
The market remains fragmented by design: incumbent equipment specialists, semiconductor-capable OEMs, and niche slitter manufacturers each play distinct roles. Market concentration metrics indicate that the top three and top five suppliers capture a modest share of industry revenues, leaving ample room for differentiated entrants and consolidation plays. For executives, the recommendation is clear — prioritize positioning rather than attempting to outscale incumbents on their terms.
- Applied Materials, Inc. (Santa Clara, CA): A major player in precision wafer dicing and cutting equipment. Their strengths are deep process knowledge and integration into semiconductor fabs — a lever for upselling slitting-capable tools into established customer lifecycles.
- Tokyo Electron Limited (Tokyo, Japan): Known for dicing and precision materials-handling equipment, TEL’s footprint in semiconductor production equipment makes it an important competitor for panel- and wafer-level slitting solutions.
- KLA Corporation (San Jose, CA): While principally a metrology and inspection vendor, KLA’s ability to embed inspection into slitting workflows changes the value proposition for high-accuracy applications and can shift procurement toward bundled solutions.
- Toray Engineering (Tokyo, Japan): A focused innovator in film slitting and panel-level packaging equipment. Recent product launches targeting PLP and large glass panels underscore the strategic pivot toward advanced semiconductor packaging markets.
- ACRETECH Co., Ltd. (Tokyo, Japan): Specialized in semiconductor dicing — a company whose precision tooling and market access in electronics make it a natural partner or competitor depending on route-to-market.
Notable near-term developments include a cluster of product introductions by firms addressing PLP and larger-panel compatibility — a clear signal that the supply side is racing to meet packaging-led demand. These vendor moves alter incumbent cost structures and create timing windows for strategic partnerships or targeted capex.
What the PW Consulting Report Contains (Practical, Transaction-Ready Intelligence)
Our full Slitter Market study is built to inform commercial execution and investment decisions rather than to be merely descriptive. It includes:
- Transparent market-sizing and a reproducible methodology spanning 2020–2032, with scenario-based forecasts calibrated to material, regulatory, and demand shocks.
- Actionable segmentation frameworks identifying where premium pricing and higher service attach rates are sustainable (note: detailed segment tables are withheld in this preview).
- Supplier and vendor heat maps, including supplier capability matrices, lifecycle cost models, and retrofit opportunities for installed machines.
- Buy-side decision playbooks: procurement timing, TCO calculators, and prioritized sourcing checklists to reduce lead-time exposure and protect margins.
- Regulatory and tariff mapping with tactical guidance on customs classifications and compliance timelines affecting market entry and aftersales.
- M&A and partnership thesis pages that identify consolidation targets, typical valuation multiples observed, and integration risk checklists.
- Technology roadmaps and R&D priority matrices to align product development with near-term application demand.
Strategic Actions for 2026 — Where to Place Bets
For executives preparing budgets and strategic plans for 2026, PW Consulting recommends a set of coordinated actions that balance growth capture with downside protection.
- Prioritize high-precision, integrated offerings: Invest in slitter systems that come with embedded metrology or inspection, or partner with inspection vendors to offer bundled solutions. These systems demand premium pricing and deliver recurring service revenues.
- Lock in critical components and diversify sources: Given extended lead-times for precision optics and specialty gases, secure multi-year supply agreements and create dual-sourcing strategies to avoid bottlenecks.
- Hedge material inflation: Implement index-linked pricing clauses or design-to-cost initiatives for copper-intensive products; consider pass-through mechanisms for volatile commodities.
- Time capital deployment: Use forecasted mid-single-digit market growth to stage capacity additions. Avoid blanket greenfield expansions; instead, target incremental capacity or modular platforms that can be scaled as demand crystallizes.
- Monetize installed bases: Accelerate aftermarket programs — remote diagnostics, retrofit kits for automation, and service subscriptions — to convert equipment sales into annuity-style revenue.
- Regulatory readiness: Update compliance roadmaps for EU machinery directives and HTS classifications, and price new products to account for compliance-related cost increases.
- Prepare M&A playbooks: With low-to-moderate concentration, acquisition targets will often be technology-rich but capital-constrained. Prioritize targets that provide route-to-market synergies or gap-filling IP.
Using This Intelligence — Practical Next Steps
This preview is designed to align leadership around the material trends, constraints, and competitive moves shaping the slitter market as 2026 planning commences. The full PW Consulting Slitter Market report contains the granular, transaction-level analysis (including segment tables, regional maps, and supplier scorecards) needed to underwrite deals, set product-roadmap priorities, and design procurement programs.
For teams deciding on capital allocation, procurement timing, or M&A targets, the right next step is a focused diagnostic: a 4–6 week engagement to stress-test your demand assumptions against our scenarios, calibrate supplier scorecards to your product mix, and produce a bespoke execution plan with prioritized initiatives for 2026.
Final Word
The slitter market sits at the intersection of precision engineering and high-growth electronics applications. Aggregate growth supports investment, but execution will be won by firms that integrate metrology, secure supply chains, and convert equipment into recurring revenue streams. PW Consulting’s full market study operationalizes those insights into the playbooks and models companies need in 2026. For the detailed segment breakdowns, vendor-by-vendor benchmarking, and transaction-ready appendices that underlie these conclusions, access to the complete report is required.
For detailed analysis of this topic, please visit the official page: Slitter Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Patient Infotainment Terminal Market Outlook — 8.5% CAGR (2026–2032)
By pmarketresearch, 2026-07-30
Patient Infotainment Terminal Market — Strategic Preview for 2026 Decision-Makers
Executive teaser
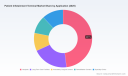
As healthcare providers shift from one-size-fits-all bedside experiences to integrated clinical-communication platforms, patient infotainment terminals are transitioning from a service differentiation to a clinical-enablement component. PW Consulting’s forthcoming Patient Infotainment Terminal Market research frames that transition with a data-driven lens: the market has expanded materially through 2020–2025 and, under conservative modeling, is set to continue growing at a compound annual growth rate of 8.5% through the 2026–2032 forecast window. This preview outlines the strategic implications executives must address in 2026 without disclosing the granular segmentation that makes the full report indispensable for tactical planning.
Patient Infotainment Terminal Market
Why this matters for 2026
-
Capital allocation: Buyers and investors must reconcile near-term modernization budgets with multi-year integration costs—hardware replacement cycles, software licensing, and EHR integration all compound total cost of ownership.
Patient Infotainment Terminal Market -
Clinical outcomes and satisfaction: Infotainment terminals are increasingly part of clinical workflows—patient education, medication reconciliation, telemedicine access and recovery pathway adherence—making vendor selection a clinical as well as an IT decision.
Patient Infotainment Terminal Market -
Regulatory and procurement posture: Medical-grade certification, privacy compliance, and procurement-ready technical specifications are gating factors for large systems procurements and public-sector tenders.
Market trajectory — the macro picture
PW Consulting’s base-year alignment is 2025, and the dataset shows the market growing from its early-decade base to a materially larger installed footprint by the mid-2020s. Our forecast horizon (2026–2032) is modeled with conservative to moderate adoption scenarios and returns a compounded growth rate of 8.5% across the period. That trajectory reflects several reinforcing dynamics: accelerating digital patient engagement initiatives at health systems, continued replacement of legacy TV-only systems with integrated clinical interfaces, and pressure to standardize medical-grade endpoints under strict safety and privacy regimes.
Dynamics shaping demand
-
Regulatory inflection: Compliance with medical electrical safety and manufacturing standards (UL/IEC/ANSI families) and increasing scrutiny of data privacy elevate validation timelines and cost for suppliers and system integrators.
-
Reimbursement friction: Because payers are slow to create pathways for non-clinical or partially clinical digital tools, procurement decisions increasingly rely on measurable operational and quality-of-care KPIs rather than direct reimbursement offsets.
-
Input-cost pressure: Hardware component pricing, anti-microbial enclosures, and secure network infrastructure contribute to higher upfront and lifecycle expenses, prompting buyers to emphasize upgradeability and modularity.
-
Clinical interoperability: EHR integration, bedside clinical workflows, and telehealth links are now baseline asks; vendors who can demonstrate certified connectors and predictable integration effort stand a far greater chance in large tenders.
Where the value pools are opening (high-level)
Value is forming at the intersection of clinical utility, IT manageability, and operational cost. Specifically:
-
Integrated platforms that combine entertainment, secure messaging, patient education, and basic clinical data capture are being valued higher than single-function displays.
-
Endpoints designed for easy device management and standardized security patching reduce hospital IT support costs and therefore change procurement evaluation criteria.
-
Modularity—swap-in media modules, upgradeable SoCs, or standardized peripheral interfaces—reduces replacement capex and increases appeal to large multi-site health systems.
Competitive landscape — who to watch
The market shows a mix of deep-specialist medical-electronics firms, IT-focused integrators, and regional OEMs. Competition is neither purely commoditized nor fully consolidated: the top-tier firms account for meaningful share, but compelling capabilities exist across mid-market and regional players. Below is a high-level strategic read on key participants and their positioning.
-
BEWATEC (Germany) — Strengths: integrated bedside series and a platform approach (ConnectedCare) that connects scheduling, treatment plans and medication information. Strategic implication: deep clinical workflows integration makes BEWATEC a natural partner for health systems seeking an out-of-the-box clinical-to-patient experience; challengers must match both software breadth and deployment references.
-
Onyx Healthcare Inc. (Taiwan) — Strengths: emphasis on medical-grade certification and manufacturing compliance. Strategic implication: Onyx is well-positioned where procurement mandates strict safety certifications. For partners and buyers, certification roadmaps are as important as price.
-
PDi Communication Systems (USA) — Strengths: strong integrations with leading EHR patient engagement modules. Strategic implication: for hospital systems where EHR-embedded patient experiences are prioritized, vendors with proven EHR connectors reduce integration risk and shorten time-to-value.
-
ClinicAll (Canada) — Strengths: platforms that blend entertainment with communication and operational workflows. Strategic implication: vendors offering configurable UX and a portfolio of clinical engagement features will win pilots and scale across wards.
-
Teguar (USA) — Strengths: rugged, MIL-STD-oriented hardware and capacitive touch. Strategic implication: in high-acuity or transportable-use cases (e.g., emergency, mobile carts), ruggedization and durability are differentiators.
-
Advantech (Taiwan) — Strengths: recognized medical-grade bedside tablets and recent Android Enterprise Recommended certification that streamlines device management in hospital IT environments (certified late 2025). Strategic implication: standardization of update and management protocols materially reduces TCO and is a procurement-winning attribute.
-
Barco NV (Belgium) — Strengths: advanced visualization and differentiated experiences (e.g., glasses-free 3D). Strategic implication: specialty deployments (surgical suites, high-end patient education) can justify premium UX spend when tied to clinical outcomes.
-
Lincor Solutions (Canada) — Strengths: EHR connectivity and patient engagement services. Strategic implication: providers seeking a single-vendor software/hardware procurement path may favor integrated service providers who can deliver both content and endpoint management.
-
Saintwaytech & Hitekon (China) — Strengths: competitive pricing, rapid product variants, antimicrobial touch surfaces, and Android/Linux options. Strategic implication: regional deployments and price-sensitive procurements will look to these suppliers; however, buyers must balance unit-price advantages against validation and long-term support risk.
Recent vendor and market signals
-
Advantech’s Android Enterprise Recommended certification for a medical-grade tablet (Nov 2025) signals greater IT-friendliness and a lower lifecycle management burden for large hospital networks.
-
BEWATEC’s expanded rollouts of its VITOS bedside terminals following organizational consolidation events are indicative of M&A-driven scale and platform integration strategies gaining traction among incumbents.
-
Regulatory reminders from multiple vendors underscore that UL/IEC/ANSI medical safety certifications and registered manufacturing remain mandatory design constraints—organizations must budget for conformance validation early in the product roadmap.
Practical 2026 playbook — what executives should do now
-
Prioritize integration pilots over feature pilots. Run end-to-end trials that include EHR integration, device management, cybersecurity verification and clinician workflow tests. Short pilots that only test streaming content will not reveal integration costs.
-
Require a lifecycle TCO model from vendors. Ask for 5–7 year scenarios that include security patching, warranty, spare-part logistics and upgrade paths; compare them on normalized net-present-value terms rather than unit price alone.
-
Lock in regulatory proof points. For public tenders and larger systems, demand evidence of relevant safety certifications and manufacturing registrations up front; vendor prequalification should include certification artifacts and a vulnerability response SLA.
-
Design modular procurement. Specify modular hardware and standardized APIs so that entertainment, telehealth and clinical modules can evolve independently of the display hardware.
-
Consider hybrid sourcing. Combine global suppliers for core clinical-grade endpoints with regional OEMs for non-critical deployments to balance cost, speed and risk.
-
Embed outcome measurement. Negotiate pilots and rollouts tied to measurable KPIs—patient satisfaction, readmission rates for specific cohorts, nursing time saved—and use those KPIs to unlock subsequent deployment tranches.
What the full PW Consulting report delivers (practical contents)
-
Robust forecasting model (2026–2032) with scenario sensitivity, and explicit assumptions so procurement teams can rerun models under their own pricing, replacement cycles and site counts.
-
Vendor scorecards and capability matrices covering certifications, integration footprints, device-management support, upgrade paths and commercial models.
-
Procurement-ready RFx language, a compliance checklist (certification and privacy), and a 90-day pilot protocol template with suggested KPIs, data collection plans and go/no-go gates.
-
Investment and M&A lenses that surface likely consolidation targets, strategic fit assessments and upside synergies for acquirers.
-
Deployment economics templates—TCO calculators that incorporate hardware, software, staging, integration and ongoing support.
Final perspective — the strategic insight in one line
Infotainment terminals are no longer a bedside luxury; they are an operational and clinical integration point whose selection determines cost, cybersecurity posture, and patient experience for the next hardware cycle. The market momentum (with an 8.5% CAGR through our forecast window) rewards vendors who can prove both clinical interoperability and IT manageability, while buyers who demand lifecycle transparency and certified endpoints will avoid hidden costs.
Next step
This preview highlights the strategic questions and directional data executives must confront in 2026. For the full segmentation, vendor scoring, and actionable RFx materials that operational teams need to execute, access the complete PW Consulting Patient Infotainment Terminal Market report and the accompanying toolkit available on our website. The detailed breakdowns—including site-level adoption scenarios, vendor share analysis, and procurement templates—are intentionally reserved for the full publication to support your team’s tactical deployment and capital planning.
For detailed analysis of this topic, please visit the official page: Patient Infotainment Terminal Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Non‑Woven Abrasive Locking Discs Market — USD 92.4M in 2025, Poised for 5.2% CAGR
By pmarketresearch, 2026-07-30
Non-Woven Abrasive Locking Discs Market — Strategic Outlook for 2026 Decision-Makers
As industrial demand patterns normalize post‑pandemic and OEMs accelerate surface‑finishing standardization, non‑woven abrasive locking discs are transitioning from a niche consumable to a strategic component of productivity improvement programs. PW Consulting’s preview synthesizes empirical market sizing, competitive mapping and prescriptive actions that are directly actionable in 2026 planning cycles — while intentionally withholding granular subsegment datapoints to preserve the full strategic value of the underlying study and to invite decision‑makers to review the complete deliverable.
Non-Woven Abrasive Locking Discs Market
At a glance: why this research matters for 2026
- Provides a defensible baseline for budgeting and portfolio prioritization: the market exhibits steady, compound growth (CAGR 5.2%) with clear demand momentum into the forecast window.
- Maps competitive intensity and consolidation dynamics: the top-three suppliers account for a dominant share of supply (CR3 ~68.5%), and the top-five concentration (CR5 ~82.1%) highlights concentrated supplier power and potential M&A opportunity.
- Delivers modular tools for procurement, R&D, commercial and M&A teams — enabling cross‑functional alignment on sourcing, product development and inorganic growth strategies for 2026.
Macro trajectory — validated market sizing and the near‑term inflection
Using 2025 as the base year, our bottom‑up model traces market evolution from 2020 through 2025 and projects through 2032. The market expanded steadily through the historical window, and PW Consulting’s forecast anticipates continued expansion across the 2026–2032 period under a 5.2% compound annual growth rate. This trajectory reflects a mix of replacement demand, increased adoption in manufacturing sub‑segments pursuing higher surface quality, and incremental use in new applications driven by finishing automation and sustainability considerations.
Non-Woven Abrasive Locking Discs Market
For 2026 planning, the implication is twofold: first, suppliers and buyers should assume a growing total addressable market that supports selective capacity investment and product line extension; second, the concentration metrics signal that market access and channel relationships will be pivotal for challengers and incumbents alike.
Non-Woven Abrasive Locking Discs Market
What the full PW Consulting report delivers — operational, commercial and M&A utility
The full study is built for executives who must convert market intelligence into executable plans. Key deliverables include:
- Market sizing and forecast model (2020–2032) with scenario toggles for demand, price and substitution risk — provided in editable spreadsheet form for boardroom and planning use.
- Proprietary demand driver analysis: segmentation by application class, end‑use purchasing behavior, and adoption curves for quick‑change locking vs. legacy arbor systems (note: the preview intentionally omits granular regional and application splits; the full dataset contains the disaggregated views needed for micro‑targeting).
- Supply chain and cost‑to‑serve maps that flag raw material sensitivities, labour cost pockets and logistics choke points relevant to 2026 CAPEX and near‑term sourcing decisions.
- Competitive landscape with concise profiles, capability matrices and strategic benchmarking for the major manufacturers: Dynabrade Inc., MCK Nonwoven Abrasives Co., Standard Abrasives, Klingspor Abrasives and Norton Abrasives. The analysis highlights product portfolios, channel approaches and performance positioning.
- Go‑to‑market playbooks tailored to OEM channels, MRO distributors and contract finishers — including pricing levers, sample programs, and specification substitution tactics to accelerate adoption.
- M&A and JV target screening framework based on strategic fit, manufacturing footprint, and integration complexity — plus valuation sensitives keyed to the market’s growth profile and concentration dynamics.
- Risk heat maps and mitigation strategies covering regulatory shifts, raw material volatility and substitution threats (including competitive influence from coated abrasives and alternative finishing methods).
- Commercial KPIs, R&D roadmaps and procurement checklists to operationalize the strategy within 90‑day and 12‑month horizons.
Competitive snapshot — strengths and strategic considerations
PW Consulting’s competitive review focuses on capability and channel advantages rather than on protected share details. Highlights for the named players:
- Dynabrade Inc. (Clarence, NY): A recognized player in non‑woven nylon locking quick‑change discs with strong OEM and industrial channel presence. Strengths include product breadth for metalworking surface conditioning and an established reputation in finishing tools.
- MCK Nonwoven Abrasives Co. (Central Taiwan): Longstanding specialty manufacturer with quick‑change product lines and a logistics foothold serving North American customers. Advantageous for partners seeking supply flexibility and cost engineering expertise.
- Standard Abrasives (United States): Established brand in surface conditioning quick‑change locking discs with a balanced focus on distribution networks used by contract finishers and maintenance operations.
- Klingspor Abrasives (Hickory, NC / Haiger, Germany): Global reach with hand‑tool and abrasive system expertise. Notable for cross‑market channel capabilities and product adaptations for different regulatory environments.
- Norton Abrasives (United States): Positions products for rapid prep and finishing, with recognized series tailored to surface conditioning. Strong R&D pipeline in resin and abrasive media blends that improve lifetime and consistency.
For 2026, competitive dynamics to monitor include product differentiation through bonding technology and fibre blends, channel consolidation among distributors, and service propositions (e.g., vendor-managed inventory for high‑usage MRO buyers). The concentration measures suggest that while a small set of incumbents dominate, strategic niches remain attractive for focused challengers.
Strategic implications by function — 2026 action playbook
- R&D/Product: Prioritize formulations that extend abrasive life while reducing dust and operator exposure. Short‑cycle pilot programs with key OEMs will accelerate spec adoption.
- Commercial & Sales: Redirect account plans to emphasize total cost of ownership (TCO) and finish consistency rather than unit price. Implement targeted trials within high‑value production lines and tiered sampling to build case studies for specification changes.
- Supply Chain & Procurement: Hedge raw‑material exposure through dual sourcing and negotiate conditional volume commitments tied to agreed NPI roadmaps. Evaluate regional logistics hubs to shorten lead times for quick‑change consumables in critical plants.
- M&A/Corporate Development: Use concentration and growth signals to prioritize tuck‑ins that add channel access or finish‑specific R&D. Valuation models should reflect the steady CAGR and the strategic premium commanded by suppliers with proven OEM approvals.
- Manufacturing & Operations: Invest selectively in automation for high‑volume disc assembly and bonding tasks to reduce labour variability and improve throughput. Run scenario analyses on utilization and break‑even of incremental lines within the provided forecast model.
Practical 2026 roadmaps — immediate next steps and 12‑month initiatives
- 90‑day actions: (1) Run an SKU profitability triage using the report’s unit‑economics template; (2) launch two closed‑loop trials with strategic customers using alternative non‑woven blends; (3) validate alternate suppliers for critical resin inputs.
- 12‑month initiatives: (1) Implement a channel development program focused on distributor certification and inventory management; (2) execute one tuck‑in acquisition (or JV) to secure manufacturing scale in a preferred geography; (3) roll out a product‑line re‑pricing linked to demonstrated TCO outcomes.
Using the preview in your planning: what you can and cannot do without the full dataset
This article provides enough macro context and tactical framing to inform early 2026 decisions — for example, to set budget ranges, prioritize functional initiatives, and calibrate executive KPIs. However, to make precise allocation decisions (e.g., site‑level inventory sizing, regional go‑to‑market sequencing, or targeted M&A bid modeling), teams will need access to the full, disaggregated data tables and sensitivity models that the PW Consulting report includes. We intentionally withhold granular regional and application splits in this preview to protect the practical value of those analytics for subscribers and licensees.
Final note — how PW Consulting supports execution
Beyond the report, PW Consulting offers a hands‑on advisory package for 2026 that couples the market model with implementation workshops: scenario stress tests, procurement negotiation playbooks, hands‑on R&D commercialization sprints, and M&A diligence support. The combination of validated market sizing, concentration insights and a supplier capability map makes the study a practical input to board decisions and 2026 operating plans.
To obtain the full dataset, editable models and the vendor‑level playbooks referenced in this preview, contact PW Consulting for access to the complete Non‑Woven Abrasive Locking Discs Market Report and our advisory engagement options.
For detailed analysis of this topic, please visit the official page: Non-Woven Abrasive Locking Discs Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: LNG Bunkering Market to Surge at 27.8% CAGR, Reach USD 9.7M by 2032
By pmarketresearch, 2026-07-30
LNG Bunkering Market 2026: Strategic Imperatives for Decision-Makers
Executive snapshot
As LNG bunkering moves from niche pilot projects to a commercial-scale fuel solution, 2026 will be a year of structural choices for shipping companies, ports, fuel suppliers and investors. PW Consulting’s latest market study—anchored on a 2025 base year, a five‑year historical review (2020–2025) and a forward forecast to 2032—shows a market accelerating rapidly: the addressable LNG bunkering market expanded from a modest base in 2020 to a substantially larger footprint in 2025, and is forecast to grow at a compounded annual growth rate (CAGR) of 27.8% over 2026–2032, reaching a multi‑million USD market by 2032.
LNG Bunkering Market
Why this matters for 2026 corporate strategy
- Timing and optionality: Decisions taken in 2026—charter agreements, JV formations, port investments, fleet retrofits—will lock in capex and commercial exposure through the late 2020s when market volumes and route availability swing from constrained to more liquid.
- Competitive positioning: The market’s current concentration dynamics indicate room for both established energy majors and agile regional specialists to shape supply corridors. The top tier of providers controls a meaningful share, but gaps remain at port and corridor levels that favour targeted entrants and partnerships.
- Regulatory and operational gating factors: Emerging best practices and national policy changes are reshaping the operational baseline for safety, permitting and cross‑border fuel flows—creating first‑mover advantages for operators who align compliance with commercial strategies early.
Market trajectory: data that frames decisions
PW Consulting’s historical analysis shows a clear inflection: the LNG bunkering market more than tripled in measured commercial activity between 2020 and 2025. Our forecast traces that momentum into an aggressive expansion phase through 2032. The implied demand curve and investment requirements during 2026–2030 are particularly steep—underscoring the need to determine stance (lead, follow, niche) this year. While headline CAGR captures the scale of expansion, the practical implication for executives is the compression of the window to secure supply, vessels and port access before competition and vessel lead‑times push prices and contract terms unfavorably.
LNG Bunkering Market
Key demand and supply dynamics
- Fuel switching economics: Fleet owners balancing retrofits, newbuilds and alternative fuels must model multi‑fuel price scenarios. LNG’s role will differ by route density and operational profile—making offtake structures and fuel flexibility clauses essential in 2026 contracting.
- Infrastructure bottlenecks: Port readiness, small‑scale liquefaction capacity, and Jones Act/regulatory considerations in critical corridors will create asymmetric supply reliability risks. Investors should prioritize corridor‑level analysis rather than treating LNG bunkering as a monolithic market.
- Operational standardisation: The publication of harmonised best practices is lowering operational uncertainty but raising baseline compliance investment. Early alignment with these standards reduces permitting friction and insurance premium volatility.
- Corporate partnerships and long‑term supply: Long‑tenor supply agreements and JV structures are becoming the dominant mechanism to de‑risk both project finance and fuel security for major shipping lines and ports.
Regulatory and industry catalysts (what changed recently)
- Policy tightening on export and bunkering operations in some jurisdictions has altered cross‑border supply flows and contractual structures—requiring legal and trade‑compliance reviews of supply chains initiated in 2026.
- IRClass and other classification bodies have published harmonised best practices for LNG bunkering, which will be increasingly referenced by port authorities, underwriters and safety regulators. These publications create a new compliance bar for operations.
- Selective infrastructure project advancement in 2025–2026—especially targeted small‑scale bunkering facilities and Jones Act‑eligible vessel charters in North America—changes the commercial landscape for U.S. coastwise trade and adjacent corridors.
Competitive landscape — who matters and why
The competitive field today is a mix of integrated energy majors, regional gas companies, specialist bunkering operators and vertically integrated shipping owners. Market concentration metrics indicate a meaningful share held by the industry’s leading players, but not an immovable oligopoly—leaving strategic room for partnerships, regional champions and innovative service models.
LNG Bunkering Market
- Shell plc (London): Leveraging global fuel retail expertise and vessel assets, Shell is focused on securing large container and liner customers through integrated supply and logistics solutions. Shell’s strength is its global footprint and commercial relationships with major shipping lines.
- TotalEnergies SE (Paris): An operator with dedicated large‑capacity bunker tonnage and strategic long‑term supply agreements, TotalEnergies is pursuing scale through JV and fleet investment—illustrated by recent high‑profile partnerships that deepen port access in key hubs.
- Gasum Oy (Helsinki): A regional specialist with purpose‑built assets in the Baltic and North Sea, Gasum demonstrates how concentrated regional operations, local port ties and tailored service portfolios can create defensible positions against larger entrants.
- ENGIE SA (Paris): Bringing integrated infrastructure and renewable sourcing capabilities, ENGIE’s playbook is to connect LNG bunkering to broader energy transition services—positioning for biomethane/bioLNG interchangeability as regulations evolve.
- North American specialists (e.g., Eagle LNG Partners, Seaspan Energy, Harvey Gulf) : These firms are mobilising dedicated tonnage and corridor‑specific capabilities. Their advantage lies in regulatory familiarity, local relationships and the ability to execute Jones Act‑compliant solutions.
- Titan Clean Fuels (Amsterdam): A notable example of a supplier combining LNG and bioLNG offerings and demand aggregation—important where decarbonisation credentials become a procurement differentiator.
Recent market moves that change the 2026 playbook
- Large JV commitments between energy majors and shipping lines to build dedicated large‑capacity bunker vessels and secure multi‑year offtake volumes have emerged as a preferred instrument to de‑risk supply while aggregating demand.
- New entrants and regional operators are beginning ship‑to‑ship services in previously under‑served corridors, accelerating competition and improving access—particularly where new small‑scale liquefaction or port projects reach FID.
- Regulatory orders and updated best practice publications are actively changing contract terms, insurance approaches and port licensing timelines—requiring expedited compliance and stakeholder engagement strategies.
What PW Consulting’s report delivers (practical contents)
Our study is built for executives who must act in 2026. It combines rigorously modelled market forecasts with operational tools and decision frameworks:
- Demand modelling: route‑level demand scenarios and stress tests across fuel price, carbon pricing and fleet composition sensitivities (including downside and upside cases).
- Supply‑side analysis: vessel lead‑time templates, capex/opex benchmarking for different bunkering assets, and a prioritised list of chokepoint ports where investment unlocks corridor growth.
- Commercial playbooks: contracting templates for long‑term supply, tender strategies for ports, JV term sheets, and negotiating levers for indexation and flexibility.
- Regulatory and compliance matrix: jurisdictional permit timelines, safety standard adoption pathways, and insurance implications mapped to operational models.
- Competitive intelligence: concise company profiles, asset inventories, announced JV and offtake deals, and a set of tactical scenarios illustrating likely competitive reactions to three different market entry plays.
- Investment decision support: IRR sensitivity tables, staged capex pathways, and exit contingencies for owners and port authorities contemplating greenfield bunkering projects.
Strategic recommendations for 2026 (actionable priorities)
- Decide your market stance within 12 months: lead with capex, partner for shared risk, or adopt a niche/corridor play—each choice requires different contracting timelines and partner profiles.
- Secure vessel and port access early: vessel lead times and port slot competition will compress windows. Consider time‑charters or JV charter structures to accelerate availability.
- Negotiate flexible offtakes: include fuel flexibility, volume bands, and price indexation that reflect a range of fuel scenarios (LNG, bioLNG, future e‑fuels).
- Align compliance with commercial strategy: adopt published best practices proactively to shorten permitting and reduce insurance friction; allocate modest capex for compliance retrofits now rather than incurring delays later.
- De‑risk through partnerships: long‑term supply agreements with majors or regional aggregators can protect fuel access and enable predictable pricing for ship operators and ports.
- Embed exit and pivot clauses: as alternative fuels mature, build contractual mechanisms to re‑purpose assets (e.g., LNG to bioLNG) or shift service models without stranded capex.
How to use the full PW report
The report is structured to move users from strategy to execution: concise executive dashboards for board briefings, operational checklists for port authorities and detailed financial models for investors. Because competitive advantage will arise from proprietary submarket insight, we intentionally withhold granular regional and application splits in this preview—our full subscription provides the complete segmentation tables, port‑by‑port readiness scores, and downloadable models used in our forecasts.
Final note — the strategic window is narrow
2026 is the pivot year. The market’s steep forecasted growth and the recent flurry of JV, port and regulatory moves mean that commercial footprints will be materially different by 2028. Stakeholders who take coordinated, data‑driven action this year—aligning capital, partners and compliance—will secure advantaged positions as volumes grow. PW Consulting’s full LNG Bunkering Market report is designed to equip executives with the granular intelligence and transaction templates necessary to make those choices with confidence.
To access the detailed segmentation, port‑level analysis and downloadable scenario models referenced above, please visit our report page or contact PW Consulting’s research desk for a tailored briefing.
For detailed analysis of this topic, please visit the official page: LNG Bunkering Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Nylon Copolymer Market to Reach $340.41M by 2032; 2026-2032 CAGR 1.44% - PW Consulting
By pmarketresearch, 2026-07-30
Nylon Copolymer Market — Strategic Outlook for 2026 Decision‑Making
PW Consulting’s latest Nylon Copolymer Market introduction is written for executives and strategy teams who must make high‑stakes decisions in 2026: capital allocation, supply‑chain commitments, portfolio rationalization, and M&A screening. This concise briefing samples the report’s evidence-driven, executable insights while deliberately withholding the full granular sub‑segment tables and regional splits — the exact data and interactive models are available in the complete report.
Nylon Copolymer Market
Why this report matters right now
-
A mature market with modest growth. Using 2025 as the base year, the nylon copolymer market is positioned as a steady, low‑single‑digit expansion opportunity rather than a high‑velocity breakout. Our market model shows modest growth from the 2025 baseline (USD 308.87 Million) into a forecast horizon that reaches roughly USD 340.41 Million by 2032, implying a compound annual growth rate (CAGR) of approximately 1.44% across the forecast period (2026–2032).
Nylon Copolymer Market -
Strategic choices have asymmetric outcomes. With limited headline growth, share gains, margin recovery, and product premiumization drive disproportionate value. The report converts market trajectories into boardroom levers — the moves that materially affect returns in the current cycle.
Nylon Copolymer Market -
Supply‑side shocks are already reshaping commercial terms. Upstream feedstock and strategic capacity actions in early 2026 have fundamentally altered short‑term price pass‑through dynamics and will affect procurement and pricing strategies for at least the next 12–24 months.
Key market dynamics — what to watch
-
Feedstock volatility and pass‑through pressure. Adipic acid and other upstream intermediates experienced notable price escalation in early 2026, driven by feedstock inflation and restocking. Producers have started to translate these cost increases into implemented price actions. For commercial teams, this has two immediate effects: margin squeeze for firms unable to pass costs through and negotiation leverage for sellers with differentiated products.
-
Balancing capacity expansion with feedstock integration. New upstream projects coming online (notably large adiponitrile capacity in Asia and modular expansions by specialty producers) are creating both localized oversupply risk and opportunities for firms with secured offtake or vertical integration strategies. Timing matters: capacity that ramps too quickly into a softening demand mix creates inventory risk; capacity that trails demand supports pricing resilience.
-
Regulatory shifts alter upstream incentives. Recent regulatory steps in major jurisdictions aim to secure upstream production of key intermediates, changing the investment calculus for local and regional supply chains. Companies should translate regulatory signals into actionable sourcing and contingency plans.
-
Product and material differentiation is a margin lever. Technical grades — high‑temperature nylons, flame‑retardant copolymers, and long‑chain specialty nylons — continue to command premium positions where design‑in friction is high. The competitive battleground is product performance, reliability of supply, and engineering support rather than commodity price alone.
Competitive landscape — concentrated but specialized
The nylon copolymer market shows a moderate level of concentration at the top: the top three players control a meaningful share of global supply and the top five extend that control further. That concentration shapes competitive behaviors: price leadership by a few, niche premium producers, and a stable set of incumbents with deep customer relationships.
-
Celanese Corporation (Dallas, Texas, USA) — Recognized for engineered Zytel® HTN flame‑retardant grades targeted at high‑temperature engineering plastics applications. Recent commercial actions include price adjustments that reflect supply chain and raw material pressure, signaling an intent to protect margins while managing volume.
-
DuPont de Nemours, Inc. (Wilmington, Delaware, USA) — Offers a broad portfolio including Zytel® and Selar PA® series; strong design‑in presence across automotive and electronics. DuPont remains a strategic supplier for customers that value legacy product breadth and engineering services.
-
BASF SE (Ludwigshafen, Germany) — Supplies Ultramid® C PA6/66 grades, with deep reach into injection molding and extrusion applications. BASF’s strengths are technical depth and global manufacturing scale.
-
EMS‑GRIVORY (Domat/Ems, Switzerland) — Focuses on premium polyamide alloys and metal‑replacement applications. Their positioning is centered on high‑value engineering substitutions where materials performance reduces system costs.
-
Nylon Corporation of America, Inc. (Manchester, New Hampshire, USA) — Specialist in long‑chain and amorphous nylons for high‑performance niches; recent capacity investments demonstrate a strategic bet on specialty demand recovery.
Strategically, incumbents pursue one of three playbooks: (1) defend with broad product portfolios and global reach, (2) specialize in higher‑margin technical niches, or (3) vertically integrate into feedstock to control cost and availability. Each has materially different capital and commercial implications in 2026.
Report contents — what you get (practical, board‑ready materials)
-
Proprietary market model (2020–2032) with scenario variants for low, base, and high recovery — updated to reflect early‑2026 feedstock and capacity events.
-
Pricing sensitivity and pass‑through calculators that convert raw‑material moves into margin outcomes by strategic product family.
-
Supplier & feedstock risk matrix: probabilistic supply disruption scenarios, time‑to‑recovery estimates, and mitigation playbooks (e.g., dual sourcing, hedging, tolling, or vertical integration).
-
Actionable competitor profiles and capability maps — technology, geography, customer verticals, and recent strategic moves.
-
Step‑by‑step go‑to‑market playbooks for priority segments (engineering plastics, high‑temp nylons, long‑chain specialties), including pricing strategies and engagement roadmaps for OEM design‑ins.
-
Investment decision framework: capex triggers, hurdle rates, and sensitivity thresholds tied to our market scenarios and feedstock outlook.
-
Regulatory and sustainability impact assessment, including lifecycle and recyclability implications for different nylon chemistries.
Strategic implications for 2026 decisions
-
Prioritize margin protection over volume growth. Given the market’s modest headline CAGR, superior returns will come from extracting premium pricing where performance differentiates and from cost control linked to feedstock strategies.
-
Lock strategically valuable supply. Early 2026 feedstock volatility means procurement should shift from short‑term spot reliance to medium‑term secured offtake, hedging, or tolling arrangements where commercially feasible.
-
Accelerate product premiumization and design‑in support. Investment in application engineering and co‑development with OEMs creates a moat that is resilient to commodity cycles.
-
Calibrate capacity expansion to demand signals and contractual coverage. Announcements and ramp‑ups in the upstream chain can quickly change the competitive balance; commit to incremental, staged investments tied to validated demand.
-
Consider selective vertical integration or partnerships near critical feedstocks. Projects adding upstream capacity are shifting bargaining power; evaluate partnerships that secure cost advantages or ensure continuity.
-
Embed regulatory foresight in procurement and plant siting. New regulatory frameworks are altering incentives for local upstream production; use the regulatory assessment in the full report to stress‑test location decisions.
Near‑term watchlist (next 6–18 months)
-
Raw material price trajectories and announced supplier price actions — these will determine margin shocks and contract renegotiation windows.
-
Capacity ramps and commissioning timelines of new upstream projects and specialty reactor expansions — assess whether new feedstock availability is overshooting demand or stabilizing supply.
-
OEM design cycles and specification changes driven by electrification, miniaturization, and sustainability targets — technical grades could see pull‑through if design wins are achieved.
-
M&A and alliance activity among mid‑tier producers — consolidation can quickly reconfigure regional supply dynamics and bargaining power.
How to use the full report in your 2026 boardroom
-
Plug our market scenarios into your capital planning templates to compute cash‑on‑cash returns under stressed feedstock pricing and delayed demand scenarios.
-
Use the pass‑through calculator and supplier risk matrix as the basis for procurement policy updates: contract lengths, indexation clauses, and penalty structures.
-
Adopt the competitor capability maps to prioritize strategic partnerships or M&A targets that fill technology or geographic gaps.
-
Suspend irreversible capacity commitments until scenario triggers in our decision framework are met; prefer staged greenfield or brownfield strategies with clear go/no‑go gates.
PW Consulting’s Nylon Copolymer Market report provides the data, analytical tools, and playbooks that executive teams need to turn a modestly growing market into a differentiated value pool. For the complete regional and application breakdowns, interactive dashboards, and the full suite of models and templates referenced here, access the full report on the PW Consulting publications page — the granular sub‑segment and customer‑level intelligence are provided there to support transaction execution and operational plans.
For detailed analysis of this topic, please visit the official page: Nylon Copolymer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Multi-crystalline Ingot Furnace Market to Reach USD 344.8M by 2032 (5.9% CAGR)
By pmarketresearch, 2026-07-30
Multi-crystalline Ingot Furnace Market: Strategic Outlook for 2026 Decision-Makers
As PW Consulting’s lead industry analyst, I present a focused preview of our latest Multi-crystalline Ingot Furnace Market study — a working document designed to inform capital allocation, supply‑chain strategy, and product roadmap decisions in 2026. The market for multi‑crystalline ingot furnaces is neither nascent nor saturated: after steady recovery through the early 2020s, the global market (measured in USD Million) expanded from the early‑decade base and reached an estimated USD 215.0 million in the 2025 base year. Under our central scenario the market advances to roughly USD 344.8 million by 2032, reflecting a compound annual growth rate (CAGR) of 5.9% across the 2026–2032 forecast horizon. This preview outlines the practical strategic implications we see for suppliers, equipment OEMs, module manufacturers, and investors preparing for 2026 — while reserving the full, granular intelligence for report subscribers.
Multi-crystalline Ingot Furnace Market
Why this study matters for 2026 decisions
-
Timing of capital deployment: The moderate 5.9% CAGR masks heterogeneity in replacement cycles, retrofit windows, and new capacity ramps across regions. For executives planning large CapEx in 2026, the key decision is not whether to invest in furnace capacity, but how to align the timing, technology choice, and financing structure to capture margin expansion as furnaces become more energy‑efficient and automated.
Multi-crystalline Ingot Furnace Market -
Risk-adjusted supplier selection: Our analysis shows material and component constraints (notably graphite hot‑zones and crucibles) are a persistent near‑term risk. These items represent a meaningful share of system costs and continue to exhibit single‑digit to mid‑teens annual inflation and lead‑time volatility — factors that should be built into procurement contracts and dual‑sourcing strategies in 2026.
Multi-crystalline Ingot Furnace Market -
Regulatory and ESG-driven retrofits: Energy‑efficiency mandates are tightening. Advanced furnace designs must deliver energy reductions in line with new regulatory baselines (our sector review points to required efficiency gains on the order of tens of percentage points relative to legacy systems). That dynamic will favour OEMs that can demonstrate verifiable energy and emissions performance and service offerings that monetize energy savings.
What the market numbers tell us (and what they don’t)
-
Market trajectory. The market’s progression through 2020–2025 shows recovery and selective reinvestment; the 2025 baseline and our 2026–2032 forecast quantify a multi‑year growth runway for both replacement and incremental solar wafer capacity. The CAGR of 5.9% implies steady demand for furnace upgrades and new-build lines, but not runaway expansion — meaning competitive execution and cost discipline will determine winners.
-
Structure and concentration. The sector remains fragmented: concentration metrics indicate that leadership groups do not yet command dominant global market share, leaving room for regional champions, technology specialists, and consolidation plays. This fragmentation creates attractive niches for focused product differentiation and services monetization.
-
Data withholding. To respect the “trailer” nature of this preview, granular regional, type‑level, and application splits are not disclosed here. The full report contains detailed segmentation tables, time‑series datasets, and downloadable models that convert market sizes into actionable targets for sales coverage, M&A screening, and manufacturing footprint planning.
Key structural dynamics shaping supplier economics
-
Raw material and input inflation. Graphite hot‑zones and crucibles are single points of stress: they represent a substantial cost item within furnace BOMs, face extended lead times, and have moved into inflationary territory. For procurement and product teams, the response is threefold — supplier qualification and hedging, redesign for material efficiency, and maintenance business models that capture recurring revenue from consumables.
-
Energy and regulatory pressure. New energy‑efficiency mandates require advanced furnace designs to attain large percentage reductions in energy consumption versus legacy models. Buyers evaluating 2026 procurement should prioritize validated energy performance and lifecycle cost analyses (including grid‑level and on‑site energy costs), since energy savings often drive the largest portion of total cost of ownership (TCO) improvements.
-
Automation and process intelligence. The next generation of furnaces integrates advanced automation that reduces labor dependence and supports predictive maintenance; our sector review suggests automation can materially lower staffing needs while enabling yield optimization through predictive control. For manufacturers, embedding software and analytics into equipment offerings creates differentiation and recurring revenue via service contracts.
Competitive landscape — who to watch and why
The competitive map combines established western OEMs, Japanese and European technology suppliers, and growing Chinese manufacturers. Below I summarize strategic positioning and the practical implications for partners and buyers.
-
GT Advanced Technologies (Merrimack, NH, USA) — GT’s directional solidification (DSS) furnaces are purpose‑built for casting multi‑crystalline silicon ingots. Their strength lies in incumbent relationships with wafer producers and in engineering know‑how around thermal control. Strategic implication: partners seeking modular upgrades and validated process performance may find lower integration risk with DSS platforms from established vendors.
-
ALD Vacuum Technologies (Hanau, Germany) — ALD’s Silicon Crystallization Unit (SCU) series supports both multi‑ and mono‑crystalline production. Its value proposition is process flexibility and European engineering pedigree. Strategic implication: buyers prioritizing multi‑product lines or planning transitions between wafer types should model conversion costs and vendor support capabilities carefully.
-
Ferrotec Corporation (Tokyo, Japan) — With thermal systems expertise and materials know‑how, Ferrotec competes through integrated casting systems and consumable supply. Strategic implication: companies sensitive to supply‑chain shocks will evaluate partnerships with vendors that can bundle consumables and service commitments.
-
Zhejiang Jingsheng Mechanical & Electrical Co., Ltd. (Hangzhou, China) — A domestic player focused on efficient semi‑melting models and cost‑competitive platforms. Strategic implication: players expanding in high‑volume, price‑sensitive markets will monitor Jingsheng for competitive pressure and potential scale partners.
-
Tanlong Photoelectric and Zhejiang Jinggong Technology (China) — Both firms represent the broad cohort of Chinese OEMs growing capabilities in multi‑crystalline furnace production. Strategic implication: their presence increases options for buyers but also compresses margins for vendors that do not differentiate on service, performance, or energy efficiency.
Practical playbook for 2026
-
Segment investments by risk and return: Create a three‑bucket allocation for furnace spending — immediate retrofit for energy mandates, medium‑term automation upgrades for yield and OPEX reduction, and long‑term greenfield capacity. Each bucket should have different procurement terms and financing structures.
-
Contract for materials volatility: Negotiate longer supplier lead times with built‑in indexation and consignment options for critical graphite components. Consider strategic stockpiles for key consumables sized to cover the longest supplier lead time plus a safety buffer.
-
Make software a competitive lever: If you are an OEM, bundle analytics, predictive maintenance, and energy benchmarking as subscription services. If you are a buyer, require data access clauses and prove‑it trials that demonstrate energy and yield gains before full roll‑out.
-
M&A and partnerships: For private equity and corporate development teams, the fragmented market and modest CR metrics indicate attractive roll‑up economics for scale players that can consolidate regional service networks and standardize automation platforms.
Report scope — what we provide in the full study
-
Comprehensive market sizing and outlook (historical 2020–2025 base, forecast 2026–2032) with downloadable time‑series tables and sensitivity scenarios.
-
Filtered segmentation analysis by region, furnace type, and application with anonymized benchmarking to support go‑to‑market targeting (note: detailed splits are withheld in this preview to preserve subscriber value).
-
Supply‑chain risk maps for critical inputs (graphite, power electronics, crucibles) and mitigations, including procurement playbooks and contract templates.
-
Technology and regulatory impact assessment, including validated energy efficiency models and lifecycle cost calculators to compare retrofit versus replacement decisions.
-
Competitive profiles and a tactical M&A playbook, including an acquisition scorecard and integration checklist tailored to furnace and ancillary services businesses.
-
Excel‑based scenario models for CapEx planning, TCO, and ROI timelines that tie directly to the market forecast and sensitivity levers.
How senior executives should use this preview
Consider this preview a strategic roadmap: it identifies the high‑impact levers — energy performance, automation/software, consumables strategy, and timing of capacity spend — that will determine commercial outcomes through 2026 and beyond. Tactical next steps for leaders include stress‑testing 2026 budgets against the efficiency and supply‑chain scenarios described above, initiating supplier de‑risking for critical graphite consumables, and piloting analytics‑enabled furnace upgrades that demonstrate yield improvements before scaling.
To obtain the full dataset, granular segmentation, vendor scorecards, and executable playbooks referenced here, access the complete PW Consulting Multi‑crystalline Ingot Furnace Market report and the accompanying Excel models. The full report translates the high‑level trends and the USD Million market sizing into precise operational targets and commercial initiatives you can deploy in 2026.
For detailed analysis of this topic, please visit the official page: Multi-crystalline Ingot Furnace Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Electric Dental Handpieces Market to Hit USD 524.74M by 2032 at 6.5% CAGR
By pmarketresearch, 2026-07-30
Electric Dental Handpieces Market — Strategic Outlook for 2026 Decision-Makers
PW Consulting’s latest Electric Dental Handpieces Market study is built to inform high-stakes decisions in 2026. Anchored on a 2025 base year and a detailed historical series (2020–2025), our forecast horizon runs through 2032. The global market has accelerated from a clear recovery phase in the early 2020s to a structurally higher-growth corridor; the study’s base calibration places the market at USD 340 Million in 2025 and projects a steady compound annual growth rate (CAGR) of 6.5% across the 2026–2032 forecast window. This introduction highlights the report’s strategic value, key dynamics affecting 2026 planning, and the competitive moves executives must weigh — deliberately omitting the granular segmentation tables and proprietary model outputs that are available in full on our research portal.
Electric Dental Handpieces Market
Why this study matters for 2026
Electric handpieces are no longer a single-product conversation about speed and torque. The category is evolving into an interoperability and service-led market where ergonomics, sterilization compliance, digital integration and lifecycle economics determine winner-take-share outcomes. For C-suite and BU leaders planning capital expenditure, R&D roadmaps, M&A and channel investments in 2026, our study provides three practical advantages:
Electric Dental Handpieces Market
- Evidence-based prioritization — quantifying the addressable opportunity and growth momentum so leaders can sequence investments across product, service and go-to-market initiatives.
- Risk reduction — mapping regulatory and reprocessing vectors that materially affect product acceptance, warranty exposure and aftermarket servicing costs.
- Competitive clarity — benchmarking incumbent technology bets (brushless motors, LED integration, sensor torque management, proprietary coatings) and translating them into defendable product and commercial plays.
Macro and regulatory forces shaping the 2026 agenda
The category’s trajectory is shaped by a tight interplay of clinical protocol, regulation and reimbursement dynamics that matter to manufacturers, distributors and large purchaser groups.
Electric Dental Handpieces Market
- Regulatory and reprocessing requirements. Industry guidance—principally CDC recommendations and FDA device classification—continue to drive product design and documentation requirements. Reprocessing instructions (validated cleaning, lubrication and heat sterilization at recommended cycles and temperatures) are a gating factor for clinical adoption and procurement agreements. Cordless and integrated systems attract extra scrutiny and must carry manufacturer-validated reprocessing protocols to mitigate cross-contamination risk.
- Standards compliance. ISO performance criteria and FDA guidance define minimum acceptable thresholds for clinical performance and labeling — non-compliance creates commercial and liability headwinds.
- Reimbursement pressure. Public payor structures and lower Medicaid dental reimbursement relative to private pay (noted in our sector analysis) constrain demand growth in certain market segments and influence product pricing, financing and service model viability for low-margin clinics.
- Clinical preference evolution. Dentists and clinic procurement teams increasingly evaluate total cost of ownership (TCO): upfront price, service intervals, sterilization throughput, battery and motor longevity, and integration with digital dental units for workflow efficiency.
Competitive landscape — what incumbents and challengers are signaling
The competitive field blends century-old dental equipment houses with specialist engineering firms. Market concentration indicates meaningful dominance by leading players, but not an impenetrable oligopoly: the top three vendors account for a significant share of revenue while the top five widen that dominance further, leaving mid-tier players and technology specialists room to carve niche positions.
Key players profiled in our analysis include (representative examples):
- KaVo Dental GmbH — emphasizes sensor-driven torque management and integrated LED illumination in its MASTERtorque LUX and INTRA LUX series, underscoring a clinical ergonomics-led positioning.
- Dentsply Sirona Inc. — continues to push digital-enablement and thermal control via Midwest Energo T1 and comfort T2 series, with recent product updates claiming operational and environmental benefits.
- NSK Ltd. — leverages multifunction platforms (e.g., an electric platform that integrates scaling and powder therapy) and clinical sensor feedback to sell systems rather than standalone handpieces.
- W&H Dentalwerk — differentiates with surface engineering (proprietary coatings) and high-torque power variants tailored for restorative workflows featuring hard-material removal.
- Bien-Air, J. Morita, A-dec, DentalEZ, SciCan and Brasseler — collectively represent complementary strategies from integration partnerships to micromotor specialization and sterilization equipment adjacencies.
Recent market actions that matter for 2026 decisions:
- Early 2026: New product introduction signaling ergonomic and mode-driven designs (e.g., a lightweight system with preset clinical modes) — relevant to purchasing teams focused on productivity gains.
- Early 2026: Strategic partnerships integrating electric handpiece systems into delivery units — a channel strategy that favors vendors with delivery-equipment alliances.
- Late 2025: Platform expansions that emphasize energy efficiency, thermal control and emissions reduction — messaging that matters to large group buyers and sustainability-conscious purchasers.
- Mid 2025: Platforms unveiled at major industry shows that combine ultrasonic, powder therapy and electric handpiece functions, increasing cross-sell opportunities for platform vendors.
Practical contents of the full PW Consulting study (what you’ll get)
The full report is organized to convert insight into immediate action. Highlights include:
- Comprehensive market model (2020–2032) with scenario sensitivities and a clear statement of assumptions — enabling in-house finance teams to adapt our baseline to alternate pricing, adoption and regulatory scenarios.
- Vendor benchmarking dashboard — technology scorecards, go-to-market mapping, manufacturing footprint risk, warranty and service economics, and partner ecosystems.
- Regulatory and sterilization matrix — a practical checklist tying product claims to validated reprocessing instructions, ISO testing requirements and FDA labeling obligations.
- Channel and procurement playbooks for OEMs and distributors — tender strategies, leasing vs. capital sale analyses, and clinic upgrade conversion frameworks.
- M&A and partnership scouting — target archetypes, valuation multiples observed in the sector, and integration risk profiles tailored to 2026 priorities.
- Commercial levers and pricing elasticity analysis — TCO calculators and pack/service-bundle designs that reflect pressure from public-pay markets.
Note: detailed segment-by-segment financial tables and the underlying micro-data model are reserved for subscribers; the materials above are offered as structured deliverables in the full research package.
Strategic implications and recommended moves for 2026
Our analysis yields a compact set of recommended initiatives for manufacturers, large distributor networks and strategic buyers planning 2026 actions:
- Invest selectively in modular platforms. Prioritize R&D that enables interchangeable heads, upgradeable electronics and software-enabled feature sets to extend product lifecycles and capture aftermarket service revenue.
- Lock down validated reprocessing protocols as a commercial differentiator. Clear, tested instructions for cleaning, lubrication and sterilization reduce purchasing friction with large clinical buyers and compliance-focused hospital procurement teams.
- Pursue delivery-unit and integrator partnerships. Vendors that partner with chair/delivery manufacturers gain preferential access to large accounts and can embed premium pricing through ergonomically integrated solutions.
- Design service-first commercial models for price-sensitive markets. Where reimbursement compresses procedure economics, offer leasing, subscription-for-service, and guaranteed uptime contracts to preserve margins.
- Use recent product and partnership moves as signals for M&A and alliance screening. Targeted acquisitions can rapidly add coatings expertise, sensor capabilities or channel reach without the time and cost of organic development.
- Defend via aftermarket and consumable ecosystems. Sterilization consumables, maintenance kits and software updates are high-margin retention levers that also mitigate competitive pricing pressure on hardware.
How to apply these insights in boardroom conversations
For 2026 planning cycles, executives should translate the study’s outputs into three board-level artifacts: (1) a prioritized investment roadmap aligning R&D and go-to-market spend to where adoption and margin expansion coincide; (2) a regulatory-compliance roadmap tying product labeling and sterilization validation to commercial launch timing; and (3) an M&A heat map identifying targets that accelerate time-to-market for high-value features (sensor feedback, high-torque variants, integrated delivery partnerships).
These artifacts turn market growth visibility (anchored in our 6.5% CAGR baseline) into executable choices that preserve optionality while accelerating access to expanding clinical segments.
Next steps
This introduction is designed to demonstrate the analytical depth and practical orientation of PW Consulting’s Electric Dental Handpieces Market study while intentionally withholding the proprietary segment tables and model outputs that underpin our forecasts. For access to the complete dataset, vendor scorecards, reprocessing checklist and the interactive model you can use to stress-test strategic scenarios, visit our research portal or contact your PW Consulting account representative. If you are planning procurement cycles, R&D prioritization, strategic partnerships or M&A activity in 2026, the full report will save months of primary research and materially de-risk execution.
For detailed analysis of this topic, please visit the official page: Electric Dental Handpieces Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Halal Cosmetics Market to Reach USD 54,590M by 2032 at 11.8% CAGR
By pmarketresearch, 2026-07-30
Halal Cosmetics Market: Strategic Outlook and Decision Playbook for 2026
As PW Consulting’s lead industry analyst, I present a forward-looking brief that condenses the strategic implications of our comprehensive Halal Cosmetics Market study (base year 2025) for executive decision-making in 2026. This introduction is designed as a “trailer” — to surface the analytical backbone, priority actions and directional forecasts that matter to senior leaders, while preserving the granular segment tables and proprietary models for clients who access the full report.
Halal Cosmetics Market
Why Halal Cosmetics Matters to Corporate Strategy in 2026
The halal cosmetics sector has moved decisively from niche to mainstream. Our market-level view shows the industry expanding on a robust growth trajectory (projected compound annual growth rate of 11.8% across the 2026–2032 forecast window). After a steady recovery from pandemic-era distortions, the market base in 2025 provides a solid launching point for aggressive expansion. By 2032 the market is set to more than double relative to the early-2020s baseline — a signal that demand dynamics, regulatory momentum and product innovation are aligning to create sustained opportunity.
Halal Cosmetics Market
For 2026 strategists, that macro profile translates into three immutable imperatives:
Halal Cosmetics Market
- Operationalize halal compliance as a commercial advantage rather than a regulatory checkbox.
- Re-engineer product and channel portfolios to capture premiumisation and cross-cultural appeal (halal-certified, natural, sustainable).
- Prioritise supply-chain resilience and control of key botanical inputs that underpin margin and claims credibility.
Market Structure and Competitive Texture (Directional)
The competitive environment remains fragmented: a meaningful proportion of market share is held by regional champions and agile manufacturers rather than by a handful of global conglomerates. Our concentration metrics confirm a low-to-moderate consolidation level, indicating room for scale-driven M&A and selective vertical integration to deliver rapid market share gains.
What this means practically: multinational beauty houses can expect to face well-entrenched regional incumbents with culturally-tailored brands and superior local route-to-market capabilities. Conversely, specialized players — OEMs and ingredient specialists — can scale through partnerships with global players that lack halal-certified manufacturing footprints.
Profiles of Strategic Players: Who to Watch and Why
- Wardah Cosmetics (Jakarta, Indonesia) — A pioneer halal-certified consumer brand that leverages a Halal Green Beauty philosophy across skincare, color cosmetics and body care. Wardah’s strong domestic positioning and brand recognition make it a natural acquirer/partner for players seeking immediate access to mass-market distribution and regulatory know-how in Indonesia.
- Paragon Technology and Innovation (Tangerang, Indonesia) — Parent to Wardah and other halal lines, Paragon operates as a full-stack group combining R&D, manufacturing and brand development. Its emphasis on natural purity and halal-certified processes is a strategic template for scalable halal operations.
- Ivy Beauty Corporation (Seri Kembangan, Malaysia) — A dual-role player (OEM + proprietary brands) with export capabilities across Asia. Ivy’s model is instructive for firms seeking a low-risk route to expand product portfolios through white-label and co-manufacturing agreements.
- Clara International Beauty Group (Bayan Lepas, Malaysia) — Specialist in herbal, halal-compliant formulations that benefit from provenance-based storytelling. Clara demonstrates the commercial lift available to brands that couple ingredient narratives with halal assurance.
- Martha Tilaar Group (Jakarta, Indonesia) — Builds competitive moat around Indonesian botanicals and heritage formulations. Their positioning underscores the higher-margin potential of wellness-anchored, halal-certified personal care lines.
- Inika Organic (Australia) — An example of premium halal-certified, organic and mineral products designed for cross-market appeal (vegan/cruelty-free plus halal credentials). Inika’s recent luxury line expansion signals demand at the intersection of halal and green luxury.
The strategic takeaway for 2026: enter partnerships with regionally dominant manufacturers or secure capabilities through minority stakes in OEMs to accelerate time-to-market for halal SKUs.
Regulatory and Market Dynamics: Immediate 2026 Actions
Regulation is now a primary growth lever rather than merely a compliance cost. Two regulatory events crystallise the 2026 horizon:
- Indonesia’s enforcement timeline for mandatory halal certification for cosmetics is tightening — a material factor for any company with distribution plans in the country. This imposes immediate resource allocation for certification readiness, factory audits and labeling updates.
- GCC harmonisation through the GSO 2931:2025 standard simplifies multi-country certification across a high-value regional market, lowering marginal certification costs and accelerating entry for compliant brands.
Actions for 2026:
- Complete a halal-certification gap analysis for every SKU intended for Indonesia and GCC distribution; prioritize resources for SKUs with the fastest payback.
- Implement an audit-ready compliance program linking procurement, QC and regulatory reporting to avoid last-minute distribution disruptions.
Product and Consumer Strategy: High-Impact Plays
Demand drivers are converging on three product themes: natural/botanical formulations, premiumisation (serums and active-infused makeup), and hybrid wellness-beauty propositions. In particular, local sourcing of botanicals in Indonesia and Malaysia is improving gross margins for manufacturers that vertically integrate or secure exclusive supplier relationships.
For 2026 commercialization plans we recommend:
- Design two product tiers: a mass-accessible halal line optimized for price and supply-chain simplicity; and a premium “halal premium” line marrying clinical acts with provenance storytelling.
- Invest in formulations that reduce dependency on contentious excipients; this both eases certification and shields brands from regulatory and consumer scrutiny.
- Leverage clean-label and cruelty-free claims as parallel value drivers that enhance crossover appeal beyond Muslim-majority markets.
Channels, Distribution and Go-to-Market
Digital-first distribution remains the fastest growth vector, but brick-and-mortar and travel retail retain strategic importance for premium discovery and impulse categories. The launch of trade platforms focused on halal supply chains (e.g., co-located trade events and verified supplier marketplaces) is lowering friction for international sourcing and distribution partnerships.
2026 channel playbook:
- Segment SKUs by channel economics — digital-native SKUs with faster refresh cycles; premium and experiential SKUs reserved for travel retail and specialty stores.
- Negotiate shared-margin pilot bundles with leading e-commerce platforms in target markets to accelerate conversion and capture first-party consumer data.
- Use trade-platform participation to qualify halal-certified suppliers and accelerate supply-chain diversification.
M&A, Partnerships and Manufacturing Strategy
Given the fragmented landscape and the operational demands of certification, targeted acquisitions and strategic alliances are often faster and less risky than greenfield expansion. Priorities for acquirers in 2026:
- Acquire or partner with certified OEMs that have regulatory experience and audited facilities in Indonesia and Malaysia.
- Secure long-term contracts for high-value botanical inputs and invest selectively in local agronomy programs to protect margin and ensure provenance.
- Consider bolt-on acquisitions of brands with strong retail distribution but weak digital capabilities — then migrate those brands to a centralized e‑commerce engine.
Risk, Resilience and Scenario Planning
Major downside risks in 2026 include certification delays, supply-chain disruptions for key botanicals, and rapid shifts in consumer sentiment around greenwashing. Our stress-testing suggests that firms that delay certification or fail to secure verified suppliers face immediate distribution risk in Indonesia and reputational risk in export markets.
Mitigations include multi-sourcing strategies, investment in inventory buffers for critical inputs, and transparent third-party verification for ingredient claims.
What the Full Report Contains (Practical Deliverables)
Our full Halal Cosmetics Market report (base year 2025, historical 2020–2025, forecast 2026–2032) provides the operational intelligence executives and business-unit leaders need to convert strategy into results. Key deliverables include:
- Comprehensive forecasts and scenario models (top-line and by strategic segmentation) with sensitivity analyses.
- Granular market-size tables and growth drivers by region, product type and application (note: this preview intentionally omits the segment-level figures; they are included in the full report).
- Regulatory tracker for Indonesia, GCC and selected APAC markets, including certification timelines and audit requirements.
- 50+ company profiles and capability maps highlighting manufacturing capacity, certification status and partnership readiness.
- Actionable playbooks for certification execution, channel roll-outs, pricing strategies and M&A screening templates.
- Primary-source interview extracts and supplier maps to accelerate vendor qualification and RFP readiness.
Final Strategic Counsel for 2026
Halal cosmetics is no longer a compliance-driven sideline — it is a strategic growth domain that rewards early operational commitment and culturally intelligent branding. For executives planning 2026 investments, prioritize three cross-cutting moves:
- Make halal certification an early-stage gating criterion for product launches in target markets, not an afterthought.
- Lock supply for high-margin botanical inputs and invest in provenance to defend pricing power.
- Use partnerships with regional manufacturers and platforms to accelerate distribution while keeping the option to consolidate via M&A.
This briefing is a strategic preview. The full PW Consulting Halal Cosmetics Market report contains the complete datasets, segmented forecasts, company financials and tactical playbooks necessary to operationalize the strategies outlined above. Contact our research access team to obtain the full report and interactive dashboards, which include the segment-level tables intentionally withheld from this preview.
For detailed analysis of this topic, please visit the official page: Halal Cosmetics Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com