

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Nylon Copolymer Market to Reach $340.41M by 2032; 2026-2032 CAGR 1.44% - PW Consulting

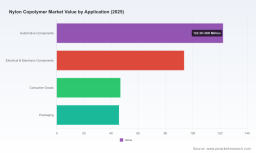
Nylon Copolymer Market — Strategic Outlook for 2026 Decision‑Making
PW Consulting’s latest Nylon Copolymer Market introduction is written for executives and strategy teams who must make high‑stakes decisions in 2026: capital allocation, supply‑chain commitments, portfolio rationalization, and M&A screening. This concise briefing samples the report’s evidence-driven, executable insights while deliberately withholding the full granular sub‑segment tables and regional splits — the exact data and interactive models are available in the complete report.
Nylon Copolymer Market
Why this report matters right now
-
A mature market with modest growth. Using 2025 as the base year, the nylon copolymer market is positioned as a steady, low‑single‑digit expansion opportunity rather than a high‑velocity breakout. Our market model shows modest growth from the 2025 baseline (USD 308.87 Million) into a forecast horizon that reaches roughly USD 340.41 Million by 2032, implying a compound annual growth rate (CAGR) of approximately 1.44% across the forecast period (2026–2032).
Nylon Copolymer Market -
Strategic choices have asymmetric outcomes. With limited headline growth, share gains, margin recovery, and product premiumization drive disproportionate value. The report converts market trajectories into boardroom levers — the moves that materially affect returns in the current cycle.
Nylon Copolymer Market -
Supply‑side shocks are already reshaping commercial terms. Upstream feedstock and strategic capacity actions in early 2026 have fundamentally altered short‑term price pass‑through dynamics and will affect procurement and pricing strategies for at least the next 12–24 months.
Key market dynamics — what to watch
-
Feedstock volatility and pass‑through pressure. Adipic acid and other upstream intermediates experienced notable price escalation in early 2026, driven by feedstock inflation and restocking. Producers have started to translate these cost increases into implemented price actions. For commercial teams, this has two immediate effects: margin squeeze for firms unable to pass costs through and negotiation leverage for sellers with differentiated products.
-
Balancing capacity expansion with feedstock integration. New upstream projects coming online (notably large adiponitrile capacity in Asia and modular expansions by specialty producers) are creating both localized oversupply risk and opportunities for firms with secured offtake or vertical integration strategies. Timing matters: capacity that ramps too quickly into a softening demand mix creates inventory risk; capacity that trails demand supports pricing resilience.
-
Regulatory shifts alter upstream incentives. Recent regulatory steps in major jurisdictions aim to secure upstream production of key intermediates, changing the investment calculus for local and regional supply chains. Companies should translate regulatory signals into actionable sourcing and contingency plans.
-
Product and material differentiation is a margin lever. Technical grades — high‑temperature nylons, flame‑retardant copolymers, and long‑chain specialty nylons — continue to command premium positions where design‑in friction is high. The competitive battleground is product performance, reliability of supply, and engineering support rather than commodity price alone.
Competitive landscape — concentrated but specialized
The nylon copolymer market shows a moderate level of concentration at the top: the top three players control a meaningful share of global supply and the top five extend that control further. That concentration shapes competitive behaviors: price leadership by a few, niche premium producers, and a stable set of incumbents with deep customer relationships.
-
Celanese Corporation (Dallas, Texas, USA) — Recognized for engineered Zytel® HTN flame‑retardant grades targeted at high‑temperature engineering plastics applications. Recent commercial actions include price adjustments that reflect supply chain and raw material pressure, signaling an intent to protect margins while managing volume.
-
DuPont de Nemours, Inc. (Wilmington, Delaware, USA) — Offers a broad portfolio including Zytel® and Selar PA® series; strong design‑in presence across automotive and electronics. DuPont remains a strategic supplier for customers that value legacy product breadth and engineering services.
-
BASF SE (Ludwigshafen, Germany) — Supplies Ultramid® C PA6/66 grades, with deep reach into injection molding and extrusion applications. BASF’s strengths are technical depth and global manufacturing scale.
-
EMS‑GRIVORY (Domat/Ems, Switzerland) — Focuses on premium polyamide alloys and metal‑replacement applications. Their positioning is centered on high‑value engineering substitutions where materials performance reduces system costs.
-
Nylon Corporation of America, Inc. (Manchester, New Hampshire, USA) — Specialist in long‑chain and amorphous nylons for high‑performance niches; recent capacity investments demonstrate a strategic bet on specialty demand recovery.
Strategically, incumbents pursue one of three playbooks: (1) defend with broad product portfolios and global reach, (2) specialize in higher‑margin technical niches, or (3) vertically integrate into feedstock to control cost and availability. Each has materially different capital and commercial implications in 2026.
Report contents — what you get (practical, board‑ready materials)
-
Proprietary market model (2020–2032) with scenario variants for low, base, and high recovery — updated to reflect early‑2026 feedstock and capacity events.
-
Pricing sensitivity and pass‑through calculators that convert raw‑material moves into margin outcomes by strategic product family.
-
Supplier & feedstock risk matrix: probabilistic supply disruption scenarios, time‑to‑recovery estimates, and mitigation playbooks (e.g., dual sourcing, hedging, tolling, or vertical integration).
-
Actionable competitor profiles and capability maps — technology, geography, customer verticals, and recent strategic moves.
-
Step‑by‑step go‑to‑market playbooks for priority segments (engineering plastics, high‑temp nylons, long‑chain specialties), including pricing strategies and engagement roadmaps for OEM design‑ins.
-
Investment decision framework: capex triggers, hurdle rates, and sensitivity thresholds tied to our market scenarios and feedstock outlook.
-
Regulatory and sustainability impact assessment, including lifecycle and recyclability implications for different nylon chemistries.
Strategic implications for 2026 decisions
-
Prioritize margin protection over volume growth. Given the market’s modest headline CAGR, superior returns will come from extracting premium pricing where performance differentiates and from cost control linked to feedstock strategies.
-
Lock strategically valuable supply. Early 2026 feedstock volatility means procurement should shift from short‑term spot reliance to medium‑term secured offtake, hedging, or tolling arrangements where commercially feasible.
-
Accelerate product premiumization and design‑in support. Investment in application engineering and co‑development with OEMs creates a moat that is resilient to commodity cycles.
-
Calibrate capacity expansion to demand signals and contractual coverage. Announcements and ramp‑ups in the upstream chain can quickly change the competitive balance; commit to incremental, staged investments tied to validated demand.
-
Consider selective vertical integration or partnerships near critical feedstocks. Projects adding upstream capacity are shifting bargaining power; evaluate partnerships that secure cost advantages or ensure continuity.
-
Embed regulatory foresight in procurement and plant siting. New regulatory frameworks are altering incentives for local upstream production; use the regulatory assessment in the full report to stress‑test location decisions.
Near‑term watchlist (next 6–18 months)
-
Raw material price trajectories and announced supplier price actions — these will determine margin shocks and contract renegotiation windows.
-
Capacity ramps and commissioning timelines of new upstream projects and specialty reactor expansions — assess whether new feedstock availability is overshooting demand or stabilizing supply.
-
OEM design cycles and specification changes driven by electrification, miniaturization, and sustainability targets — technical grades could see pull‑through if design wins are achieved.
-
M&A and alliance activity among mid‑tier producers — consolidation can quickly reconfigure regional supply dynamics and bargaining power.
How to use the full report in your 2026 boardroom
-
Plug our market scenarios into your capital planning templates to compute cash‑on‑cash returns under stressed feedstock pricing and delayed demand scenarios.
-
Use the pass‑through calculator and supplier risk matrix as the basis for procurement policy updates: contract lengths, indexation clauses, and penalty structures.
-
Adopt the competitor capability maps to prioritize strategic partnerships or M&A targets that fill technology or geographic gaps.
-
Suspend irreversible capacity commitments until scenario triggers in our decision framework are met; prefer staged greenfield or brownfield strategies with clear go/no‑go gates.
PW Consulting’s Nylon Copolymer Market report provides the data, analytical tools, and playbooks that executive teams need to turn a modestly growing market into a differentiated value pool. For the complete regional and application breakdowns, interactive dashboards, and the full suite of models and templates referenced here, access the full report on the PW Consulting publications page — the granular sub‑segment and customer‑level intelligence are provided there to support transaction execution and operational plans.
For detailed analysis of this topic, please visit the official page: Nylon Copolymer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com