

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Patient Infotainment Terminal Market Outlook — 8.5% CAGR (2026–2032)

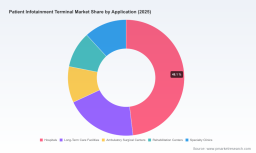
Patient Infotainment Terminal Market — Strategic Preview for 2026 Decision-Makers
Executive teaser
As healthcare providers shift from one-size-fits-all bedside experiences to integrated clinical-communication platforms, patient infotainment terminals are transitioning from a service differentiation to a clinical-enablement component. PW Consulting’s forthcoming Patient Infotainment Terminal Market research frames that transition with a data-driven lens: the market has expanded materially through 2020–2025 and, under conservative modeling, is set to continue growing at a compound annual growth rate of 8.5% through the 2026–2032 forecast window. This preview outlines the strategic implications executives must address in 2026 without disclosing the granular segmentation that makes the full report indispensable for tactical planning.
Patient Infotainment Terminal Market
Why this matters for 2026
-
Capital allocation: Buyers and investors must reconcile near-term modernization budgets with multi-year integration costs—hardware replacement cycles, software licensing, and EHR integration all compound total cost of ownership.
Patient Infotainment Terminal Market -
Clinical outcomes and satisfaction: Infotainment terminals are increasingly part of clinical workflows—patient education, medication reconciliation, telemedicine access and recovery pathway adherence—making vendor selection a clinical as well as an IT decision.
Patient Infotainment Terminal Market -
Regulatory and procurement posture: Medical-grade certification, privacy compliance, and procurement-ready technical specifications are gating factors for large systems procurements and public-sector tenders.
Market trajectory — the macro picture
PW Consulting’s base-year alignment is 2025, and the dataset shows the market growing from its early-decade base to a materially larger installed footprint by the mid-2020s. Our forecast horizon (2026–2032) is modeled with conservative to moderate adoption scenarios and returns a compounded growth rate of 8.5% across the period. That trajectory reflects several reinforcing dynamics: accelerating digital patient engagement initiatives at health systems, continued replacement of legacy TV-only systems with integrated clinical interfaces, and pressure to standardize medical-grade endpoints under strict safety and privacy regimes.
Dynamics shaping demand
-
Regulatory inflection: Compliance with medical electrical safety and manufacturing standards (UL/IEC/ANSI families) and increasing scrutiny of data privacy elevate validation timelines and cost for suppliers and system integrators.
-
Reimbursement friction: Because payers are slow to create pathways for non-clinical or partially clinical digital tools, procurement decisions increasingly rely on measurable operational and quality-of-care KPIs rather than direct reimbursement offsets.
-
Input-cost pressure: Hardware component pricing, anti-microbial enclosures, and secure network infrastructure contribute to higher upfront and lifecycle expenses, prompting buyers to emphasize upgradeability and modularity.
-
Clinical interoperability: EHR integration, bedside clinical workflows, and telehealth links are now baseline asks; vendors who can demonstrate certified connectors and predictable integration effort stand a far greater chance in large tenders.
Where the value pools are opening (high-level)
Value is forming at the intersection of clinical utility, IT manageability, and operational cost. Specifically:
-
Integrated platforms that combine entertainment, secure messaging, patient education, and basic clinical data capture are being valued higher than single-function displays.
-
Endpoints designed for easy device management and standardized security patching reduce hospital IT support costs and therefore change procurement evaluation criteria.
-
Modularity—swap-in media modules, upgradeable SoCs, or standardized peripheral interfaces—reduces replacement capex and increases appeal to large multi-site health systems.
Competitive landscape — who to watch
The market shows a mix of deep-specialist medical-electronics firms, IT-focused integrators, and regional OEMs. Competition is neither purely commoditized nor fully consolidated: the top-tier firms account for meaningful share, but compelling capabilities exist across mid-market and regional players. Below is a high-level strategic read on key participants and their positioning.
-
BEWATEC (Germany) — Strengths: integrated bedside series and a platform approach (ConnectedCare) that connects scheduling, treatment plans and medication information. Strategic implication: deep clinical workflows integration makes BEWATEC a natural partner for health systems seeking an out-of-the-box clinical-to-patient experience; challengers must match both software breadth and deployment references.
-
Onyx Healthcare Inc. (Taiwan) — Strengths: emphasis on medical-grade certification and manufacturing compliance. Strategic implication: Onyx is well-positioned where procurement mandates strict safety certifications. For partners and buyers, certification roadmaps are as important as price.
-
PDi Communication Systems (USA) — Strengths: strong integrations with leading EHR patient engagement modules. Strategic implication: for hospital systems where EHR-embedded patient experiences are prioritized, vendors with proven EHR connectors reduce integration risk and shorten time-to-value.
-
ClinicAll (Canada) — Strengths: platforms that blend entertainment with communication and operational workflows. Strategic implication: vendors offering configurable UX and a portfolio of clinical engagement features will win pilots and scale across wards.
-
Teguar (USA) — Strengths: rugged, MIL-STD-oriented hardware and capacitive touch. Strategic implication: in high-acuity or transportable-use cases (e.g., emergency, mobile carts), ruggedization and durability are differentiators.
-
Advantech (Taiwan) — Strengths: recognized medical-grade bedside tablets and recent Android Enterprise Recommended certification that streamlines device management in hospital IT environments (certified late 2025). Strategic implication: standardization of update and management protocols materially reduces TCO and is a procurement-winning attribute.
-
Barco NV (Belgium) — Strengths: advanced visualization and differentiated experiences (e.g., glasses-free 3D). Strategic implication: specialty deployments (surgical suites, high-end patient education) can justify premium UX spend when tied to clinical outcomes.
-
Lincor Solutions (Canada) — Strengths: EHR connectivity and patient engagement services. Strategic implication: providers seeking a single-vendor software/hardware procurement path may favor integrated service providers who can deliver both content and endpoint management.
-
Saintwaytech & Hitekon (China) — Strengths: competitive pricing, rapid product variants, antimicrobial touch surfaces, and Android/Linux options. Strategic implication: regional deployments and price-sensitive procurements will look to these suppliers; however, buyers must balance unit-price advantages against validation and long-term support risk.
Recent vendor and market signals
-
Advantech’s Android Enterprise Recommended certification for a medical-grade tablet (Nov 2025) signals greater IT-friendliness and a lower lifecycle management burden for large hospital networks.
-
BEWATEC’s expanded rollouts of its VITOS bedside terminals following organizational consolidation events are indicative of M&A-driven scale and platform integration strategies gaining traction among incumbents.
-
Regulatory reminders from multiple vendors underscore that UL/IEC/ANSI medical safety certifications and registered manufacturing remain mandatory design constraints—organizations must budget for conformance validation early in the product roadmap.
Practical 2026 playbook — what executives should do now
-
Prioritize integration pilots over feature pilots. Run end-to-end trials that include EHR integration, device management, cybersecurity verification and clinician workflow tests. Short pilots that only test streaming content will not reveal integration costs.
-
Require a lifecycle TCO model from vendors. Ask for 5–7 year scenarios that include security patching, warranty, spare-part logistics and upgrade paths; compare them on normalized net-present-value terms rather than unit price alone.
-
Lock in regulatory proof points. For public tenders and larger systems, demand evidence of relevant safety certifications and manufacturing registrations up front; vendor prequalification should include certification artifacts and a vulnerability response SLA.
-
Design modular procurement. Specify modular hardware and standardized APIs so that entertainment, telehealth and clinical modules can evolve independently of the display hardware.
-
Consider hybrid sourcing. Combine global suppliers for core clinical-grade endpoints with regional OEMs for non-critical deployments to balance cost, speed and risk.
-
Embed outcome measurement. Negotiate pilots and rollouts tied to measurable KPIs—patient satisfaction, readmission rates for specific cohorts, nursing time saved—and use those KPIs to unlock subsequent deployment tranches.
What the full PW Consulting report delivers (practical contents)
-
Robust forecasting model (2026–2032) with scenario sensitivity, and explicit assumptions so procurement teams can rerun models under their own pricing, replacement cycles and site counts.
-
Vendor scorecards and capability matrices covering certifications, integration footprints, device-management support, upgrade paths and commercial models.
-
Procurement-ready RFx language, a compliance checklist (certification and privacy), and a 90-day pilot protocol template with suggested KPIs, data collection plans and go/no-go gates.
-
Investment and M&A lenses that surface likely consolidation targets, strategic fit assessments and upside synergies for acquirers.
-
Deployment economics templates—TCO calculators that incorporate hardware, software, staging, integration and ongoing support.
Final perspective — the strategic insight in one line
Infotainment terminals are no longer a bedside luxury; they are an operational and clinical integration point whose selection determines cost, cybersecurity posture, and patient experience for the next hardware cycle. The market momentum (with an 8.5% CAGR through our forecast window) rewards vendors who can prove both clinical interoperability and IT manageability, while buyers who demand lifecycle transparency and certified endpoints will avoid hidden costs.
Next step
This preview highlights the strategic questions and directional data executives must confront in 2026. For the full segmentation, vendor scoring, and actionable RFx materials that operational teams need to execute, access the complete PW Consulting Patient Infotainment Terminal Market report and the accompanying toolkit available on our website. The detailed breakdowns—including site-level adoption scenarios, vendor share analysis, and procurement templates—are intentionally reserved for the full publication to support your team’s tactical deployment and capital planning.
For detailed analysis of this topic, please visit the official page: Patient Infotainment Terminal Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com