

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Multi-crystalline Ingot Furnace Market to Reach USD 344.8M by 2032 (5.9% CAGR)

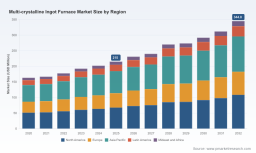
Multi-crystalline Ingot Furnace Market: Strategic Outlook for 2026 Decision-Makers
As PW Consulting’s lead industry analyst, I present a focused preview of our latest Multi-crystalline Ingot Furnace Market study — a working document designed to inform capital allocation, supply‑chain strategy, and product roadmap decisions in 2026. The market for multi‑crystalline ingot furnaces is neither nascent nor saturated: after steady recovery through the early 2020s, the global market (measured in USD Million) expanded from the early‑decade base and reached an estimated USD 215.0 million in the 2025 base year. Under our central scenario the market advances to roughly USD 344.8 million by 2032, reflecting a compound annual growth rate (CAGR) of 5.9% across the 2026–2032 forecast horizon. This preview outlines the practical strategic implications we see for suppliers, equipment OEMs, module manufacturers, and investors preparing for 2026 — while reserving the full, granular intelligence for report subscribers.
Multi-crystalline Ingot Furnace Market
Why this study matters for 2026 decisions
-
Timing of capital deployment: The moderate 5.9% CAGR masks heterogeneity in replacement cycles, retrofit windows, and new capacity ramps across regions. For executives planning large CapEx in 2026, the key decision is not whether to invest in furnace capacity, but how to align the timing, technology choice, and financing structure to capture margin expansion as furnaces become more energy‑efficient and automated.
Multi-crystalline Ingot Furnace Market -
Risk-adjusted supplier selection: Our analysis shows material and component constraints (notably graphite hot‑zones and crucibles) are a persistent near‑term risk. These items represent a meaningful share of system costs and continue to exhibit single‑digit to mid‑teens annual inflation and lead‑time volatility — factors that should be built into procurement contracts and dual‑sourcing strategies in 2026.
Multi-crystalline Ingot Furnace Market -
Regulatory and ESG-driven retrofits: Energy‑efficiency mandates are tightening. Advanced furnace designs must deliver energy reductions in line with new regulatory baselines (our sector review points to required efficiency gains on the order of tens of percentage points relative to legacy systems). That dynamic will favour OEMs that can demonstrate verifiable energy and emissions performance and service offerings that monetize energy savings.
What the market numbers tell us (and what they don’t)
-
Market trajectory. The market’s progression through 2020–2025 shows recovery and selective reinvestment; the 2025 baseline and our 2026–2032 forecast quantify a multi‑year growth runway for both replacement and incremental solar wafer capacity. The CAGR of 5.9% implies steady demand for furnace upgrades and new-build lines, but not runaway expansion — meaning competitive execution and cost discipline will determine winners.
-
Structure and concentration. The sector remains fragmented: concentration metrics indicate that leadership groups do not yet command dominant global market share, leaving room for regional champions, technology specialists, and consolidation plays. This fragmentation creates attractive niches for focused product differentiation and services monetization.
-
Data withholding. To respect the “trailer” nature of this preview, granular regional, type‑level, and application splits are not disclosed here. The full report contains detailed segmentation tables, time‑series datasets, and downloadable models that convert market sizes into actionable targets for sales coverage, M&A screening, and manufacturing footprint planning.
Key structural dynamics shaping supplier economics
-
Raw material and input inflation. Graphite hot‑zones and crucibles are single points of stress: they represent a substantial cost item within furnace BOMs, face extended lead times, and have moved into inflationary territory. For procurement and product teams, the response is threefold — supplier qualification and hedging, redesign for material efficiency, and maintenance business models that capture recurring revenue from consumables.
-
Energy and regulatory pressure. New energy‑efficiency mandates require advanced furnace designs to attain large percentage reductions in energy consumption versus legacy models. Buyers evaluating 2026 procurement should prioritize validated energy performance and lifecycle cost analyses (including grid‑level and on‑site energy costs), since energy savings often drive the largest portion of total cost of ownership (TCO) improvements.
-
Automation and process intelligence. The next generation of furnaces integrates advanced automation that reduces labor dependence and supports predictive maintenance; our sector review suggests automation can materially lower staffing needs while enabling yield optimization through predictive control. For manufacturers, embedding software and analytics into equipment offerings creates differentiation and recurring revenue via service contracts.
Competitive landscape — who to watch and why
The competitive map combines established western OEMs, Japanese and European technology suppliers, and growing Chinese manufacturers. Below I summarize strategic positioning and the practical implications for partners and buyers.
-
GT Advanced Technologies (Merrimack, NH, USA) — GT’s directional solidification (DSS) furnaces are purpose‑built for casting multi‑crystalline silicon ingots. Their strength lies in incumbent relationships with wafer producers and in engineering know‑how around thermal control. Strategic implication: partners seeking modular upgrades and validated process performance may find lower integration risk with DSS platforms from established vendors.
-
ALD Vacuum Technologies (Hanau, Germany) — ALD’s Silicon Crystallization Unit (SCU) series supports both multi‑ and mono‑crystalline production. Its value proposition is process flexibility and European engineering pedigree. Strategic implication: buyers prioritizing multi‑product lines or planning transitions between wafer types should model conversion costs and vendor support capabilities carefully.
-
Ferrotec Corporation (Tokyo, Japan) — With thermal systems expertise and materials know‑how, Ferrotec competes through integrated casting systems and consumable supply. Strategic implication: companies sensitive to supply‑chain shocks will evaluate partnerships with vendors that can bundle consumables and service commitments.
-
Zhejiang Jingsheng Mechanical & Electrical Co., Ltd. (Hangzhou, China) — A domestic player focused on efficient semi‑melting models and cost‑competitive platforms. Strategic implication: players expanding in high‑volume, price‑sensitive markets will monitor Jingsheng for competitive pressure and potential scale partners.
-
Tanlong Photoelectric and Zhejiang Jinggong Technology (China) — Both firms represent the broad cohort of Chinese OEMs growing capabilities in multi‑crystalline furnace production. Strategic implication: their presence increases options for buyers but also compresses margins for vendors that do not differentiate on service, performance, or energy efficiency.
Practical playbook for 2026
-
Segment investments by risk and return: Create a three‑bucket allocation for furnace spending — immediate retrofit for energy mandates, medium‑term automation upgrades for yield and OPEX reduction, and long‑term greenfield capacity. Each bucket should have different procurement terms and financing structures.
-
Contract for materials volatility: Negotiate longer supplier lead times with built‑in indexation and consignment options for critical graphite components. Consider strategic stockpiles for key consumables sized to cover the longest supplier lead time plus a safety buffer.
-
Make software a competitive lever: If you are an OEM, bundle analytics, predictive maintenance, and energy benchmarking as subscription services. If you are a buyer, require data access clauses and prove‑it trials that demonstrate energy and yield gains before full roll‑out.
-
M&A and partnerships: For private equity and corporate development teams, the fragmented market and modest CR metrics indicate attractive roll‑up economics for scale players that can consolidate regional service networks and standardize automation platforms.
Report scope — what we provide in the full study
-
Comprehensive market sizing and outlook (historical 2020–2025 base, forecast 2026–2032) with downloadable time‑series tables and sensitivity scenarios.
-
Filtered segmentation analysis by region, furnace type, and application with anonymized benchmarking to support go‑to‑market targeting (note: detailed splits are withheld in this preview to preserve subscriber value).
-
Supply‑chain risk maps for critical inputs (graphite, power electronics, crucibles) and mitigations, including procurement playbooks and contract templates.
-
Technology and regulatory impact assessment, including validated energy efficiency models and lifecycle cost calculators to compare retrofit versus replacement decisions.
-
Competitive profiles and a tactical M&A playbook, including an acquisition scorecard and integration checklist tailored to furnace and ancillary services businesses.
-
Excel‑based scenario models for CapEx planning, TCO, and ROI timelines that tie directly to the market forecast and sensitivity levers.
How senior executives should use this preview
Consider this preview a strategic roadmap: it identifies the high‑impact levers — energy performance, automation/software, consumables strategy, and timing of capacity spend — that will determine commercial outcomes through 2026 and beyond. Tactical next steps for leaders include stress‑testing 2026 budgets against the efficiency and supply‑chain scenarios described above, initiating supplier de‑risking for critical graphite consumables, and piloting analytics‑enabled furnace upgrades that demonstrate yield improvements before scaling.
To obtain the full dataset, granular segmentation, vendor scorecards, and executable playbooks referenced here, access the complete PW Consulting Multi‑crystalline Ingot Furnace Market report and the accompanying Excel models. The full report translates the high‑level trends and the USD Million market sizing into precise operational targets and commercial initiatives you can deploy in 2026.
For detailed analysis of this topic, please visit the official page: Multi-crystalline Ingot Furnace Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com