

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: LNG Bunkering Market to Surge at 27.8% CAGR, Reach USD 9.7M by 2032

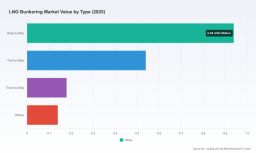
LNG Bunkering Market 2026: Strategic Imperatives for Decision-Makers
Executive snapshot
As LNG bunkering moves from niche pilot projects to a commercial-scale fuel solution, 2026 will be a year of structural choices for shipping companies, ports, fuel suppliers and investors. PW Consulting’s latest market study—anchored on a 2025 base year, a five‑year historical review (2020–2025) and a forward forecast to 2032—shows a market accelerating rapidly: the addressable LNG bunkering market expanded from a modest base in 2020 to a substantially larger footprint in 2025, and is forecast to grow at a compounded annual growth rate (CAGR) of 27.8% over 2026–2032, reaching a multi‑million USD market by 2032.
LNG Bunkering Market
Why this matters for 2026 corporate strategy
- Timing and optionality: Decisions taken in 2026—charter agreements, JV formations, port investments, fleet retrofits—will lock in capex and commercial exposure through the late 2020s when market volumes and route availability swing from constrained to more liquid.
- Competitive positioning: The market’s current concentration dynamics indicate room for both established energy majors and agile regional specialists to shape supply corridors. The top tier of providers controls a meaningful share, but gaps remain at port and corridor levels that favour targeted entrants and partnerships.
- Regulatory and operational gating factors: Emerging best practices and national policy changes are reshaping the operational baseline for safety, permitting and cross‑border fuel flows—creating first‑mover advantages for operators who align compliance with commercial strategies early.
Market trajectory: data that frames decisions
PW Consulting’s historical analysis shows a clear inflection: the LNG bunkering market more than tripled in measured commercial activity between 2020 and 2025. Our forecast traces that momentum into an aggressive expansion phase through 2032. The implied demand curve and investment requirements during 2026–2030 are particularly steep—underscoring the need to determine stance (lead, follow, niche) this year. While headline CAGR captures the scale of expansion, the practical implication for executives is the compression of the window to secure supply, vessels and port access before competition and vessel lead‑times push prices and contract terms unfavorably.
LNG Bunkering Market
Key demand and supply dynamics
- Fuel switching economics: Fleet owners balancing retrofits, newbuilds and alternative fuels must model multi‑fuel price scenarios. LNG’s role will differ by route density and operational profile—making offtake structures and fuel flexibility clauses essential in 2026 contracting.
- Infrastructure bottlenecks: Port readiness, small‑scale liquefaction capacity, and Jones Act/regulatory considerations in critical corridors will create asymmetric supply reliability risks. Investors should prioritize corridor‑level analysis rather than treating LNG bunkering as a monolithic market.
- Operational standardisation: The publication of harmonised best practices is lowering operational uncertainty but raising baseline compliance investment. Early alignment with these standards reduces permitting friction and insurance premium volatility.
- Corporate partnerships and long‑term supply: Long‑tenor supply agreements and JV structures are becoming the dominant mechanism to de‑risk both project finance and fuel security for major shipping lines and ports.
Regulatory and industry catalysts (what changed recently)
- Policy tightening on export and bunkering operations in some jurisdictions has altered cross‑border supply flows and contractual structures—requiring legal and trade‑compliance reviews of supply chains initiated in 2026.
- IRClass and other classification bodies have published harmonised best practices for LNG bunkering, which will be increasingly referenced by port authorities, underwriters and safety regulators. These publications create a new compliance bar for operations.
- Selective infrastructure project advancement in 2025–2026—especially targeted small‑scale bunkering facilities and Jones Act‑eligible vessel charters in North America—changes the commercial landscape for U.S. coastwise trade and adjacent corridors.
Competitive landscape — who matters and why
The competitive field today is a mix of integrated energy majors, regional gas companies, specialist bunkering operators and vertically integrated shipping owners. Market concentration metrics indicate a meaningful share held by the industry’s leading players, but not an immovable oligopoly—leaving strategic room for partnerships, regional champions and innovative service models.
LNG Bunkering Market
- Shell plc (London): Leveraging global fuel retail expertise and vessel assets, Shell is focused on securing large container and liner customers through integrated supply and logistics solutions. Shell’s strength is its global footprint and commercial relationships with major shipping lines.
- TotalEnergies SE (Paris): An operator with dedicated large‑capacity bunker tonnage and strategic long‑term supply agreements, TotalEnergies is pursuing scale through JV and fleet investment—illustrated by recent high‑profile partnerships that deepen port access in key hubs.
- Gasum Oy (Helsinki): A regional specialist with purpose‑built assets in the Baltic and North Sea, Gasum demonstrates how concentrated regional operations, local port ties and tailored service portfolios can create defensible positions against larger entrants.
- ENGIE SA (Paris): Bringing integrated infrastructure and renewable sourcing capabilities, ENGIE’s playbook is to connect LNG bunkering to broader energy transition services—positioning for biomethane/bioLNG interchangeability as regulations evolve.
- North American specialists (e.g., Eagle LNG Partners, Seaspan Energy, Harvey Gulf) : These firms are mobilising dedicated tonnage and corridor‑specific capabilities. Their advantage lies in regulatory familiarity, local relationships and the ability to execute Jones Act‑compliant solutions.
- Titan Clean Fuels (Amsterdam): A notable example of a supplier combining LNG and bioLNG offerings and demand aggregation—important where decarbonisation credentials become a procurement differentiator.
Recent market moves that change the 2026 playbook
- Large JV commitments between energy majors and shipping lines to build dedicated large‑capacity bunker vessels and secure multi‑year offtake volumes have emerged as a preferred instrument to de‑risk supply while aggregating demand.
- New entrants and regional operators are beginning ship‑to‑ship services in previously under‑served corridors, accelerating competition and improving access—particularly where new small‑scale liquefaction or port projects reach FID.
- Regulatory orders and updated best practice publications are actively changing contract terms, insurance approaches and port licensing timelines—requiring expedited compliance and stakeholder engagement strategies.
What PW Consulting’s report delivers (practical contents)
Our study is built for executives who must act in 2026. It combines rigorously modelled market forecasts with operational tools and decision frameworks:
- Demand modelling: route‑level demand scenarios and stress tests across fuel price, carbon pricing and fleet composition sensitivities (including downside and upside cases).
- Supply‑side analysis: vessel lead‑time templates, capex/opex benchmarking for different bunkering assets, and a prioritised list of chokepoint ports where investment unlocks corridor growth.
- Commercial playbooks: contracting templates for long‑term supply, tender strategies for ports, JV term sheets, and negotiating levers for indexation and flexibility.
- Regulatory and compliance matrix: jurisdictional permit timelines, safety standard adoption pathways, and insurance implications mapped to operational models.
- Competitive intelligence: concise company profiles, asset inventories, announced JV and offtake deals, and a set of tactical scenarios illustrating likely competitive reactions to three different market entry plays.
- Investment decision support: IRR sensitivity tables, staged capex pathways, and exit contingencies for owners and port authorities contemplating greenfield bunkering projects.
Strategic recommendations for 2026 (actionable priorities)
- Decide your market stance within 12 months: lead with capex, partner for shared risk, or adopt a niche/corridor play—each choice requires different contracting timelines and partner profiles.
- Secure vessel and port access early: vessel lead times and port slot competition will compress windows. Consider time‑charters or JV charter structures to accelerate availability.
- Negotiate flexible offtakes: include fuel flexibility, volume bands, and price indexation that reflect a range of fuel scenarios (LNG, bioLNG, future e‑fuels).
- Align compliance with commercial strategy: adopt published best practices proactively to shorten permitting and reduce insurance friction; allocate modest capex for compliance retrofits now rather than incurring delays later.
- De‑risk through partnerships: long‑term supply agreements with majors or regional aggregators can protect fuel access and enable predictable pricing for ship operators and ports.
- Embed exit and pivot clauses: as alternative fuels mature, build contractual mechanisms to re‑purpose assets (e.g., LNG to bioLNG) or shift service models without stranded capex.
How to use the full PW report
The report is structured to move users from strategy to execution: concise executive dashboards for board briefings, operational checklists for port authorities and detailed financial models for investors. Because competitive advantage will arise from proprietary submarket insight, we intentionally withhold granular regional and application splits in this preview—our full subscription provides the complete segmentation tables, port‑by‑port readiness scores, and downloadable models used in our forecasts.
Final note — the strategic window is narrow
2026 is the pivot year. The market’s steep forecasted growth and the recent flurry of JV, port and regulatory moves mean that commercial footprints will be materially different by 2028. Stakeholders who take coordinated, data‑driven action this year—aligning capital, partners and compliance—will secure advantaged positions as volumes grow. PW Consulting’s full LNG Bunkering Market report is designed to equip executives with the granular intelligence and transaction templates necessary to make those choices with confidence.
To access the detailed segmentation, port‑level analysis and downloadable scenario models referenced above, please visit our report page or contact PW Consulting’s research desk for a tailored briefing.
For detailed analysis of this topic, please visit the official page: LNG Bunkering Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com