

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Halal Cosmetics Market to Reach USD 54,590M by 2032 at 11.8% CAGR

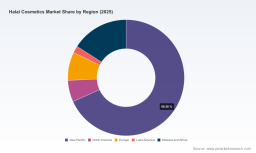
Halal Cosmetics Market: Strategic Outlook and Decision Playbook for 2026
As PW Consulting’s lead industry analyst, I present a forward-looking brief that condenses the strategic implications of our comprehensive Halal Cosmetics Market study (base year 2025) for executive decision-making in 2026. This introduction is designed as a “trailer” — to surface the analytical backbone, priority actions and directional forecasts that matter to senior leaders, while preserving the granular segment tables and proprietary models for clients who access the full report.
Halal Cosmetics Market
Why Halal Cosmetics Matters to Corporate Strategy in 2026
The halal cosmetics sector has moved decisively from niche to mainstream. Our market-level view shows the industry expanding on a robust growth trajectory (projected compound annual growth rate of 11.8% across the 2026–2032 forecast window). After a steady recovery from pandemic-era distortions, the market base in 2025 provides a solid launching point for aggressive expansion. By 2032 the market is set to more than double relative to the early-2020s baseline — a signal that demand dynamics, regulatory momentum and product innovation are aligning to create sustained opportunity.
Halal Cosmetics Market
For 2026 strategists, that macro profile translates into three immutable imperatives:
Halal Cosmetics Market
- Operationalize halal compliance as a commercial advantage rather than a regulatory checkbox.
- Re-engineer product and channel portfolios to capture premiumisation and cross-cultural appeal (halal-certified, natural, sustainable).
- Prioritise supply-chain resilience and control of key botanical inputs that underpin margin and claims credibility.
Market Structure and Competitive Texture (Directional)
The competitive environment remains fragmented: a meaningful proportion of market share is held by regional champions and agile manufacturers rather than by a handful of global conglomerates. Our concentration metrics confirm a low-to-moderate consolidation level, indicating room for scale-driven M&A and selective vertical integration to deliver rapid market share gains.
What this means practically: multinational beauty houses can expect to face well-entrenched regional incumbents with culturally-tailored brands and superior local route-to-market capabilities. Conversely, specialized players — OEMs and ingredient specialists — can scale through partnerships with global players that lack halal-certified manufacturing footprints.
Profiles of Strategic Players: Who to Watch and Why
- Wardah Cosmetics (Jakarta, Indonesia) — A pioneer halal-certified consumer brand that leverages a Halal Green Beauty philosophy across skincare, color cosmetics and body care. Wardah’s strong domestic positioning and brand recognition make it a natural acquirer/partner for players seeking immediate access to mass-market distribution and regulatory know-how in Indonesia.
- Paragon Technology and Innovation (Tangerang, Indonesia) — Parent to Wardah and other halal lines, Paragon operates as a full-stack group combining R&D, manufacturing and brand development. Its emphasis on natural purity and halal-certified processes is a strategic template for scalable halal operations.
- Ivy Beauty Corporation (Seri Kembangan, Malaysia) — A dual-role player (OEM + proprietary brands) with export capabilities across Asia. Ivy’s model is instructive for firms seeking a low-risk route to expand product portfolios through white-label and co-manufacturing agreements.
- Clara International Beauty Group (Bayan Lepas, Malaysia) — Specialist in herbal, halal-compliant formulations that benefit from provenance-based storytelling. Clara demonstrates the commercial lift available to brands that couple ingredient narratives with halal assurance.
- Martha Tilaar Group (Jakarta, Indonesia) — Builds competitive moat around Indonesian botanicals and heritage formulations. Their positioning underscores the higher-margin potential of wellness-anchored, halal-certified personal care lines.
- Inika Organic (Australia) — An example of premium halal-certified, organic and mineral products designed for cross-market appeal (vegan/cruelty-free plus halal credentials). Inika’s recent luxury line expansion signals demand at the intersection of halal and green luxury.
The strategic takeaway for 2026: enter partnerships with regionally dominant manufacturers or secure capabilities through minority stakes in OEMs to accelerate time-to-market for halal SKUs.
Regulatory and Market Dynamics: Immediate 2026 Actions
Regulation is now a primary growth lever rather than merely a compliance cost. Two regulatory events crystallise the 2026 horizon:
- Indonesia’s enforcement timeline for mandatory halal certification for cosmetics is tightening — a material factor for any company with distribution plans in the country. This imposes immediate resource allocation for certification readiness, factory audits and labeling updates.
- GCC harmonisation through the GSO 2931:2025 standard simplifies multi-country certification across a high-value regional market, lowering marginal certification costs and accelerating entry for compliant brands.
Actions for 2026:
- Complete a halal-certification gap analysis for every SKU intended for Indonesia and GCC distribution; prioritize resources for SKUs with the fastest payback.
- Implement an audit-ready compliance program linking procurement, QC and regulatory reporting to avoid last-minute distribution disruptions.
Product and Consumer Strategy: High-Impact Plays
Demand drivers are converging on three product themes: natural/botanical formulations, premiumisation (serums and active-infused makeup), and hybrid wellness-beauty propositions. In particular, local sourcing of botanicals in Indonesia and Malaysia is improving gross margins for manufacturers that vertically integrate or secure exclusive supplier relationships.
For 2026 commercialization plans we recommend:
- Design two product tiers: a mass-accessible halal line optimized for price and supply-chain simplicity; and a premium “halal premium” line marrying clinical acts with provenance storytelling.
- Invest in formulations that reduce dependency on contentious excipients; this both eases certification and shields brands from regulatory and consumer scrutiny.
- Leverage clean-label and cruelty-free claims as parallel value drivers that enhance crossover appeal beyond Muslim-majority markets.
Channels, Distribution and Go-to-Market
Digital-first distribution remains the fastest growth vector, but brick-and-mortar and travel retail retain strategic importance for premium discovery and impulse categories. The launch of trade platforms focused on halal supply chains (e.g., co-located trade events and verified supplier marketplaces) is lowering friction for international sourcing and distribution partnerships.
2026 channel playbook:
- Segment SKUs by channel economics — digital-native SKUs with faster refresh cycles; premium and experiential SKUs reserved for travel retail and specialty stores.
- Negotiate shared-margin pilot bundles with leading e-commerce platforms in target markets to accelerate conversion and capture first-party consumer data.
- Use trade-platform participation to qualify halal-certified suppliers and accelerate supply-chain diversification.
M&A, Partnerships and Manufacturing Strategy
Given the fragmented landscape and the operational demands of certification, targeted acquisitions and strategic alliances are often faster and less risky than greenfield expansion. Priorities for acquirers in 2026:
- Acquire or partner with certified OEMs that have regulatory experience and audited facilities in Indonesia and Malaysia.
- Secure long-term contracts for high-value botanical inputs and invest selectively in local agronomy programs to protect margin and ensure provenance.
- Consider bolt-on acquisitions of brands with strong retail distribution but weak digital capabilities — then migrate those brands to a centralized e‑commerce engine.
Risk, Resilience and Scenario Planning
Major downside risks in 2026 include certification delays, supply-chain disruptions for key botanicals, and rapid shifts in consumer sentiment around greenwashing. Our stress-testing suggests that firms that delay certification or fail to secure verified suppliers face immediate distribution risk in Indonesia and reputational risk in export markets.
Mitigations include multi-sourcing strategies, investment in inventory buffers for critical inputs, and transparent third-party verification for ingredient claims.
What the Full Report Contains (Practical Deliverables)
Our full Halal Cosmetics Market report (base year 2025, historical 2020–2025, forecast 2026–2032) provides the operational intelligence executives and business-unit leaders need to convert strategy into results. Key deliverables include:
- Comprehensive forecasts and scenario models (top-line and by strategic segmentation) with sensitivity analyses.
- Granular market-size tables and growth drivers by region, product type and application (note: this preview intentionally omits the segment-level figures; they are included in the full report).
- Regulatory tracker for Indonesia, GCC and selected APAC markets, including certification timelines and audit requirements.
- 50+ company profiles and capability maps highlighting manufacturing capacity, certification status and partnership readiness.
- Actionable playbooks for certification execution, channel roll-outs, pricing strategies and M&A screening templates.
- Primary-source interview extracts and supplier maps to accelerate vendor qualification and RFP readiness.
Final Strategic Counsel for 2026
Halal cosmetics is no longer a compliance-driven sideline — it is a strategic growth domain that rewards early operational commitment and culturally intelligent branding. For executives planning 2026 investments, prioritize three cross-cutting moves:
- Make halal certification an early-stage gating criterion for product launches in target markets, not an afterthought.
- Lock supply for high-margin botanical inputs and invest in provenance to defend pricing power.
- Use partnerships with regional manufacturers and platforms to accelerate distribution while keeping the option to consolidate via M&A.
This briefing is a strategic preview. The full PW Consulting Halal Cosmetics Market report contains the complete datasets, segmented forecasts, company financials and tactical playbooks necessary to operationalize the strategies outlined above. Contact our research access team to obtain the full report and interactive dashboards, which include the segment-level tables intentionally withheld from this preview.
For detailed analysis of this topic, please visit the official page: Halal Cosmetics Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com