

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: CMTS/QAM Market to Reach USD 7,494M by 2032 at 8.8% CAGR

CMTS & QAM Market 2026: Strategic Intelligence for Executive Decision-Makers
By PW Consulting — Senior Strategic Advisor & Chief Industry Analyst
CMTS/QAM Market
Executive teaser
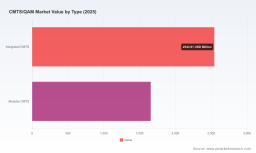
The global CMTS (Cable Modem Termination System) and QAM (Quadrature Amplitude Modulation) market has moved from a niche operator concern into a decisive infrastructure topic for broadband strategy. Our CMTS/QAM Market research, anchored on 2025 as base year and a multi-year historical series (2020–2025), projects sustained momentum through 2032. The market expands from a multi‑billion dollar base in 2025 to an even larger addressable opportunity by 2032, driven by DOCSIS evolution, virtualization, and video distribution models. Over the 2026–2032 forecast window we model an 8.8% CAGR — a rate that demands active strategic choices in procurement, architecture, and ecosystem partnerships during 2026.
CMTS/QAM Market
Why this matters for 2026 strategy
Service providers and vendors face a convergence of three strategic pressures: accelerating customer demand for multi‑gigabit services, the economics of headend consolidation, and an industry trajectory toward cloud‑native, software‑defined access. These forces create a binary set of choices for network executives in 2026: move decisively to virtualized, distributed architectures with vendor interop and managed transition paths — or manage rising OpEx and capacity constraints by extending legacy architectures with incremental upgrades.
CMTS/QAM Market
- Timing matters: the projected 8.8% CAGR amplifies the cost of delay. Every quarter of deferred modernization compounds capacity and support costs, and reduces negotiating leverage with suppliers.
- Architecture choices are strategic bets: hardware‑centric CCAP/CMTS platforms remain relevant, but virtual CMTS (vCMTS) and cloud‑native implementations materially alter TCO profiles and upgrade cadence.
- Regulatory and security contours are changing: industry‑wide interoperability events and security‑focused interop sessions in 2026 underline that vendor compatibility and secure software lifecycles will be procurement differentiators.
What the research delivers (practical toolkit)
This report is built as an operational playbook for decision‑makers, not an academic exercise. Highlights include:
- Market sizing and trend analytics: a validated historical series (2020–2025) and scenario‑based forecasts to 2032 that quantify the macro opportunity and downside sensitivities.
- Adoption curves and migration roadmaps: tested deployment templates for phased DOCSIS 3.1→4.0 and vCMTS adoption, with milestone‑based gating criteria to align CapEx cycles with customer demand.
- TCO and CapEx/OpEx models: comparative analyses showing the inflection points where virtualization becomes financially attractive, including power, rack‑space, and personnel assumptions.
- Interoperability matrix and vendor readiness scoring: vendor capabilities assessed against criteria such as DOCSIS feature parity, QAM integration, cloud‑native maturity, and security posture.
- Procurement playbook: negotiation levers, SLA templates, and upgrade path clauses designed to protect operators during multi‑year migrations.
- Risk register and mitigation playbooks: scenarios spanning component cost volatility, supplier consolidation, and interoperability lags, with practical mitigation steps.
Competitive landscape — what to watch in 2026
The market structure features a mixture of global incumbents, specialist vendors, and emerging cloud‑native challengers. Aggregate concentration indicates meaningful scale among the top players, yet the vendor field remains sufficiently fragmented to allow strategic sourcing options.
- Cisco Systems — a traditional incumbent with integrated CMTS/Edge QAM platforms that continue to serve large operators requiring tightly integrated hardware solutions. Strengths: global field support, breadth of platform functionality, and legacy operator relationships. Watch: migration path toward greater software modularity and cloud interop.
- Arris Group — positioned with high‑density CCAP and Edge QAM offerings suitable for operators wanting a path from video‑dense headends to combined data/video services. Strengths: density and service provider familiarity. Watch: roadmap alignment to DOCSIS 4.0 and virtualization.
- Casa Systems — a leading voice for virtual CCAP/vCMTS and distributed access. Strengths: DAA‑oriented solutions and strong software stacks for operators planning cloud migration. Watch: commercial scalability and integration with third‑party virtualization platforms.
- Harmonic Inc. — notable for cloud‑native vCMTS and Edge QAM products and recent contract wins supporting DOCSIS 4.0 pilots. Strengths: cloud‑first approach and strong presence in video streaming stacks. Watch: execution on large‑scale Unified DOCSIS projects.
- Vecima Networks — a specialist whose Entra vCMTS and video QAM management solutions are increasingly selected by operators pursuing cloud‑native modernization. Strengths: interoperability focus and tailored modernization offers. Watch: ability to scale to multi‑operator contracts.
- Huawei, WISI, Sumavision, Teleste and regional OEMs — provide alternative technology and price points, especially in markets where regional supply diversity or localization matters. Strengths: cost competitiveness and regional support models. Watch: compliance, interoperability, and long‑term software support commitments.
- Smaller entrants (e.g., C9 Networks, Chongqing Jinghong) — bring niche innovation and targeted platform features; suitable for pilots and regional rollouts but require caution on roadmaps and support SLAs.
Recent industry signals that change tactical choices
Market signals over the past 18 months accelerate the need for decisive choices in 2026:
- Contract awards to cloud‑native vCMTS suppliers demonstrate operator willingness to shift away from pure hardware dependency. Selected deployments validate scale and commercial models for virtualization.
- Interoperability events organized by CableLabs in early 2026 expanded DOCSIS 4.0 testing, explicitly adding security and multi‑vendor interop scenarios — a positive for operators requiring vendor agnosticism but also a warning that multi‑vendor integration carries execution risk if not planned.
- Partnerships in Distributed Access Architecture (DAA) deployments signal a move toward disaggregated headend functionality; procurement teams must therefore evaluate components for fit in both centralized and distributed topologies.
Cost and technology dynamics to factor into 2026 decisions
Two structural cost dynamics will shape vendor selection and architecture choices:
- Hardware complexity: DOCSIS 3.1/4.0 implementations demand advanced LDPC error correction and OFDM/OFDMA modulation support, which drives higher component and unit costs versus legacy 256‑QAM platforms. These costs must be weighed against lifecycle benefits and per‑subscriber capacity gains.
- Virtualization economics: relocating CMTS functions to commercial off‑the‑shelf servers can materially reduce headend footprint and power consumption; however, the financial case depends on virtualization maturity, orchestration overhead, and integration with existing OSS/BSS systems.
Actionable recommendations for 2026 — a concise checklist
- Run a staged migration pilot: prioritize vCMTS pilots with clearly defined KPIs (latency, throughput, operational overhead) before committing to network‑wide rollouts.
- Embed interoperability clauses: require multi‑vendor interop certification milestones and security audit results as part of procurement contracts.
- Quantify TCO with sensitivity testing: model scenarios where virtualization yields breakeven at different energy, personnel, and capacity assumptions to inform CapEx timing.
- Protect upgrade optionality: include modular upgrade and rollback clauses to preserve options as DOCSIS standards and vendor roadmaps evolve.
- Align procurement with architecture: build vendor shortlists around target architecture — centralized CCAP, hybrid DAA, or fully distributed vCMTS — rather than selecting vendors first and forcing design later.
- Monitor supply and regulatory tides: track interoperability events and regulatory guidance that may change timelines for secure DOCSIS 4.0 rollouts.
What we intentionally withhold here — and why
To preserve the strategic "trailer" value of this briefing, detailed segmentation tables — including regional and application breakouts, and granular vendor share by subsegment — are only available in the full CMTS/QAM Market report. The high‑level market trajectory, CAGR, and practical implications for 2026 strategy are disclosed here to inform executive decisions; the granular splits, procurement‑grade vendor scorecards, and downloadable TCO models are provided in the paid report to ensure decision teams have a single canonical source for negotiations and planning.
Next steps
Executives preparing procurement or network transformation roadmaps in 2026 should request the full PW Consulting CMTS/QAM Market report to obtain:
- Operational playbooks and vendor scorecards for procurement teams.
- Downloadable TCO models and scenario planners tailored to operator scale.
- Access to proprietary interoperability matrices and secure‑by‑design checklists that are updated against the latest CableLabs testing outcomes.
PW Consulting will be publishing an executive briefing series and supporting workshops in Q3 2026 to help operators convert these findings into 12–36 month execution plans. For operators and vendors seeking to participate in workshop engagements or to obtain the full dataset and annexes, visit our report page or contact our advisory desk.
For detailed analysis of this topic, please visit the official page: CMTS/QAM Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com