

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Category: market research
PW Consulting: Micro Turbine Market to Reach USD 344.8M by 2032 with 9.44% CAGR
By pmarketresearch, 2026-07-30
Micro Turbine Market — Strategic Outlook for 2026 Decision‑Makers
PW Consulting’s latest Micro Turbine Market study is designed as a strategic playbook for executives making capital, product and policy decisions in 2026. Grounded in a five‑year historical review (2020–2025) and a detailed forecast through 2032, the research converts complex technical, regulatory and commercial dynamics into actionable options — while deliberately reserving the granular sub‑segment tables and vendor scorecards for clients who access the full report.
Micro Turbine Market
Market at a glance: macro trajectory and what it means
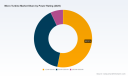
Micro turbine markets have moved beyond niche backup installations toward versatile building blocks for distributed energy, combined heat and power (CHP), and waste‑heat recovery. On a top‑line basis, the global micro turbine market expanded from approximately USD 163.2 Million in 2020 to about USD 215.0 Million in 2025 (base year). Under our central projection, the market is expected to rise to roughly USD 233.5 Million in 2026 and reach about USD 344.8 Million by 2032. That trajectory reflects a compound annual growth rate (CAGR) of 9.44% over the 2026–2032 forecast window — a pace that signals sustained commercial opportunity for manufacturers, integrators and project financiers.
Micro Turbine Market
Two high‑level implications follow: first, the market scale is now material enough to justify dedicated R&D and commercial investment while remaining fragmented enough to reward focused specialization. Second, policy drivers and fuel‑stack evolution (from natural gas and biogas to higher hydrogen blends and hybridized systems) will determine which value pools emerge fastest.
Micro Turbine Market
Why this research matters to a 2026 strategic plan
- Capital allocation: Our models translate headline growth into project‑level IRR sensitivities for CHP, standby and waste‑heat recovery applications so CFOs can prioritize capex and leasing options against other distributed energy investments.
- Product and technology roadmaps: Engineering leaders receive a comparative view of fuel flexibility, electrical/thermal efficiencies and balance‑of‑plant tradeoffs that influence lifecycle O&M and retrofit potential.
- Go‑to‑market and commercial structuring: Sales and business development teams will find playbooks for bundling micro turbines with energy storage, controls and service agreements to capture recurring revenue.
- Policy and incentive optimization: Project teams get a synthesis of near‑term incentives and compliance risks (see regulatory highlights below) to accelerate project payback and maximize tax credit capture.
- M&A and partnership screening: Corporate development teams can identify acquisition targets and JV partners with niche IP or channel access before valuations re‑rate the sector.
Regulatory and incentive context that will shape 2026 decisions
Policy remains a key lever. The report collates current incentive mechanics that materially change project economics: for example, the Fuel Cells (Residential and Microturbine System) Tax Credit provides a specific per‑capacity credit structure, and provisions within the Inflation Reduction Act (IRA) offer an Investment Tax Credit and Production Tax Credit pathway — notably a 30% ITC for qualifying systems under 1 MW AC or thermal when prevailing wage and apprenticeship conditions are met. Project teams must also reconcile recent administrative and statutory developments that alter eligibility timelines and emissions requirements. Installation capital expenditures continue to vary with capacity and configuration; recent benchmarking places microturbine CHP installed costs in the range reported by major energy programs, which should be used as a baseline for project underwriting.
Two practical takeaways: lock in incentive eligibility early in the design phase, and build prevailing‑wage compliance into contractor selection to avoid losing value at financial close.
What PW Consulting’s report delivers — operationally useful content
- Market sizing and forecast model (2020–2032) with downloadable scenario variants (central, upside, downside) and sensitivity tools you can run with your own price and fuel assumptions.
- TAM/SAM/SOM framework and practical guidance on how to partition opportunity by application, power rating and procurement model (CAPEX vs. EPC vs. energy service contract).
- Vendor landscape and competitive scorecards that evaluate technology readiness, fuel flexibility, service network, and commercial terms (note: detailed vendor revenue shares and segment allocations are reserved for subscribers).
- Unit economics calculator and payback templates that incorporate capital costs, incentive capture, fuel price trajectories and O&M profiles.
- Technical Appendix with benchmarked efficiency curves, emissions factor comparisons and recommended test protocols for field acceptance.
- Risk heatmaps and mitigation playbooks covering supply‑chain concentration, rare‑earth exposure, and counterparty credit risk for off‑take agreements.
- Case studies and commissioning checklists from recent projects that clarify lessons learned on permitting, interconnection and performance verification.
Competitive landscape — who matters and why
The micro turbine market remains moderately fragmented: the three largest players account for under a quarter of global share (CR3 ≈ 24.6%) and the top five approximately 26.2%. That structure favors specialist entrants and focused scale strategies over broad incumbent dominance. Below is an executive read on core vendors and their strategic posture.
- Ansaldo Energia S.p.A. (Genoa, Italy) — Ansaldo is positioning microturbines as part of integrated CHP/CCHP systems, promoting multi‑fuel capability (natural gas, biogas and hydrogen blends up to high percentages) and high electrical/thermal efficiency performance metrics. Their strength lies in system engineering for industrial and utility customers and in leveraging turbomachinery expertise across product lines.
- Capstone Green Energy Corporation (Van Nuys, CA, USA) — Capstone operates with a broad product footprint and a distribution model that emphasizes repeatable CHP deployments. Recent major orders and repeat business with food manufacturers underscore strength in packaged solutions and aftermarket services. Capstone’s air‑bearing microturbine architecture supports flexible fuels (natural gas, RNG, landfill gas, and hydrogen blends) and is a commercial leader in volume deployments.
- Bladon Micro Turbine (Warwick, UK) — Bladon is focused on small gensets for off‑grid and telecom backup applications and differentiates through single‑engine simplicity and ruggedness. Their positioning makes them a preferred option in harsh environments and for customers prioritizing fuel flexibility including liquid fuels.
- FlexEnergy Solutions (Centennial, CO, USA) — FlexEnergy targets larger microturbine gensets and hybrid off‑grid/grid‑parallel systems. The company’s emphasis on modular, scalable plants positions it well for distributed utility and industrial projects where site‑specific customization is needed.
- Turtle Turbines (India) — Turtle Turbines operates in the steam and compact cogeneration niche, offering mini‑cogen and waste‑heat recovery systems tailored to process industries. Their market edge is local manufacturing and fast time‑to‑deployment for captive power use‑cases.
- Advanced Microturbines Srl (Genoa, Italy) — With offerings spanning microturbines to turboexpanders, Advanced Microturbines targets energy‑recovery applications (gas decompression, pressure let‑down recovery) and small off‑grid systems. Their value proposition centers on energy recovery economics and compact system footprints.
- pyropower GmbH (Germany) — pyropower focuses on externally fired micro gas turbines for pyrolysis CHP systems, enabling electricity generation from thermal feedstocks in decentralized industrial settings. This technology is attractive where waste feedstock heat is available but fuel cleanliness varies.
Recent commercial signals reinforce these dynamics: a series of Capstone orders and follow‑on projects in 2025 highlights robust industrial demand for packaged CHP systems, and commissioning of small hydro‑powered microturbine projects demonstrates how the same core technology can be deployed in non‑combustion energy recovery roles. These events emphasize the market’s dual path: traditional combustion‑based CHP and a growing set of energy recovery and hybrid applications.
Strategic recommendations for 2026
- Prioritize modular CHP pilots in industrial hubs with high thermal loads — use the payback templates in our report to size projects that meet corporate decarbonization targets while accessing IRA/ITC benefits.
- Design product roadmaps for multi‑fuel capability, with explicit support for higher hydrogen blends and biogas/RNG compatibility; retrofit pathways will be a competitive differentiator.
- Bundle service and performance guarantees to convert one‑time equipment sales into annuity streams; rigorous remote monitoring and predictive maintenance materially increase life‑cycle margins.
- Evaluate M&A targets in niche categories (steam microturbines, turboexpanders, pyrolysis CHP) to secure specialty IP and accelerate entry into adjacent value pools.
- Embed regulatory compliance planning (prevailing wage, incentive phase‑outs) into the earliest development gates to avoid value leakage at financial close.
- Establish strategic supply‑chain partnerships for critical rotating components and control electronics to reduce lead times and protect gross margins as demand scales.
PW Consulting’s Micro Turbine Market study provides the models, templates and industry intelligence executives need to convert this growth trajectory into defensible action in 2026. For readers seeking the complete sub‑segment breakouts, vendor financials, downloadable forecast models and our full competitive scorecards, the detailed report and supporting data sets are available through PW Consulting’s research portal.
For detailed analysis of this topic, please visit the official page: Micro Turbine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Solar Ingot Wafer Market to 2032 — 9.39% CAGR, USD 107.3 Million
By pmarketresearch, 2026-07-30
Solar Ingot & Wafer Market: Strategic Preview for 2026 Decisions
As governments accelerate decarbonization and module manufacturers push toward higher-efficiency cells, the upstream ingot-and-wafer tier is reasserting its role as a strategic bottleneck and opportunity. PW Consulting’s latest Solar Ingot Wafer Market study, with a 2025 base year and a seven‑year forecast window (2026–2032), synthesizes proprietary supply‑chain mapping, cost modeling, and competitive scenario analysis to give executive teams the evidence base they need to make high‑stakes decisions in 2026.
Solar Ingot Wafer Market
Why this study matters now
-
Macro momentum: The market has more than doubled over the second half of the decade, growing from an approximate USD 32.5 million in 2020 to about USD 57.2 million in 2025, and our baseline projects continued expansion to roughly USD 107.3 million by 2032. That trajectory represents a compound annual growth rate of 9.39% across the forecast horizon, underscoring durable demand for wafers as module efficiency upgrades and deployment incentives accelerate.
Solar Ingot Wafer Market -
Timing for strategic capital allocation: 2026 is a pivotal inflection point where supply‑side capacity additions (new greenfield plants; retrofits to reduce kerf loss) and policy windows (manufacturing tax credits, capital subsidies) converge. Decisions on greenfield siting, technology mix, and vertical integration made this year will largely determine unit economics and market positioning for the next decade.
Solar Ingot Wafer Market -
Supply‑chain reconfiguration: Trade policy, tariff regimes, and the emergence of alternative manufacturing hubs are altering cost and risk calculations for import reliance. Concurrently, material and process innovations—particularly around kerf reduction and n‑type wafer adoption—are compressing cost curves but creating near‑term volatility in price signaling.
What the report delivers (practical, deal‑ready content)
-
Actionable market sizing and scenarios: We provide a base case aligned to current demand drivers and two additional scenarios (policy‑led upside; technology shock downside) that stress‑test capacity planning and price outcomes across 2026–2032.
-
Unit‑level cost models: Bottom‑up manufacturing models that reflect real input cost levers—polysilicon sourcing, kerf loss mitigation paths, labor productivity, energy consumption—allow you to simulate the ROI of alternate process upgrades or automation investments.
-
Supply‑chain heatmaps and vendor scorecards: A pragmatic view of sourcing options by technology node (mono/ poly / n‑type), supplier reliability, and logistics exposure—built to serve procurement negotiations and dual‑sourcing strategies.
-
Regulatory and incentive playbook: Quantified impact matrices for major policy levers—domestic manufacturing tax credits and capital subsidies—so financiers and corporate strategy teams can assess after‑incentive payback periods and internal hurdle rates.
-
M&A and partnership diagnostic: A layered framework to evaluate targets (asset, technology, or capability buys) with integration checklists, valuation multipliers tailored to wafer markets, and a short list of pragmatic entry/exit triggers for corporate development teams.
-
Risk register and mitigation pathways: From tariff shocks to polysilicon supply squeezes, the report ranks risks by impact and probability and prescribes hedging and operational responses—covering contractual, geographic, and technology levers.
Market dynamics you must model into 2026 planning
-
Cost structure distortions from process waste: Traditional wire‑saw processes continue to impose high silicon kerf loss—measured in tens of percent of silicon input—materially inflating raw material and labor costs. Incremental investment in kerf‑reducing technologies or adoption of alternative slicing methods materially alters unit economics and payback horizons.
-
Technology mix evolution: The wafer market is transitioning toward higher‑efficiency formats and n‑type substrates. Early 2026 saw double‑digit price moves in certain n‑type wafer grades, highlighting a phase of constrained supply relative to accelerating demand. Manufacturers must weigh the capital intensity of conversion versus the margin premium of advanced wafers.
-
Policy and incentive inflection points: Recent manufacturing incentives and capital subsidy schemes significantly improve the calculus for domestic capacity builds. For example, certain advanced manufacturing tax credits and national capital subsidy programs materially lower effective capex and shorten payback—making local production economically attractive under many scenarios.
-
Trade and tariff friction: Heightened tariff profiles on specific origin countries have accelerated diversification strategies, with buyers evaluating reshoring, nearshoring, and multi‑country sourcing to mitigate trade risk and maintain uptime for module assembly lines.
-
Concentration and supplier leverage: The upstream wafer segment remains top‑heavy; the top three players account for a substantial majority of supply, and the top five for an even larger share. This concentration amplifies the commercial influence of leading suppliers on pricing, lead times, and technology roadmaps.
Competitive landscape — what incumbents and new entrants are doing
-
Established wafer and ingot specialists from Japan, Korea, Europe, and China continue to compete on purity, customer qualification cycles, and node migration support. Companies with deep experience in high‑purity monocrystalline ingots and wafer manufacturing maintain an advantage in premium segments where yield and consistency directly affect downstream cell performance.
-
Integrated players are expanding vertically to capture more value across polysilicon → ingot → wafer → cell chains. These incumbents are able to manage input volatility more effectively and accelerate qualification of new wafer types for their captive cell lines.
-
Regional newcomers and diversified conglomerates are deploying greenfield projects in markets offering strong investment incentives and lower labor costs, aiming to undercut incumbents on delivered cost while leveraging favorable trade arrangements.
-
Notable firm-level moves included a recent overseas facility build‑out by a leading Chinese manufacturer, a U.S. incumbent bringing full domestic ingot‑wafer production online in 2025, and a major Indian energy company gaining board approval in 2026 to develop multi‑GW domestic capacity. These developments collectively shift geographic supply balances and create both pricing pressure and opportunity for offtake partners.
-
Supplier profiles included in the report: leading monocrystalline ingot producers, major wafer suppliers across Asia, Europe and North America, n‑type specialists, and integrated polysilicon players—each profiled with capability matrices, historic product roadmaps, and readiness to support large OEM qualification cycles.
What this means for corporate decision‑makers in 2026
-
For manufacturers: Prioritize investments that reduce silicon waste and operational costs (process upgrades, automation). Combine those with selective vertical integration or long‑term offtake agreements to stabilize input costs and secure premium wafer supply for higher‑efficiency modules.
-
For investors and industrial planners: Use the scenario outputs to stress‑test capital allocation across alternative siting options. Incentive‑enabled greenfield projects can present attractive IRRs—but require disciplined assessment of tariff exposure, technology risk, and supplier lock‑in.
-
For procurement leaders: Implement a layered sourcing strategy—diversify by geography and technology node, qualify secondary suppliers early, and structure contracts with flexibility to manage short‑term price spikes in advanced wafer types.
-
For policy engagement teams: Advocate for technology‑neutral manufacturing incentives that accelerate adoption of kerf‑reducing and higher‑efficiency wafer types, thereby creating domestic jobs while lowering module LCOE in the medium term.
How PW Consulting’s study turns insight into action
-
We combine empirical market sizing (historical 2020–2025 and an explicit forecast through 2032) with a decision‑grade toolkit: financial models, capex schedules, supplier due diligence templates, and a transactional playbook for M&A or JV structures. The report transforms market narratives into executable plans for boardrooms, corporate development teams, and project finance groups.
-
Importantly, while this preview highlights strategic themes, the full study contains the granular models, supplier scorecards, and scenario outputs you need to finalize 2026 commitments. Sensitive segmentation and unit‑level metrics are intentionally gated to ensure clients receive verified, actionable datasets in the full report.
For executive teams contemplating capacity expansions, procurement overhauls, or M&A in 2026, PW Consulting’s Solar Ingot Wafer Market study is designed to be your decisioning backbone: rigorous, scenario‑aware, and transaction‑ready. Access the complete analysis to download the models, stress‑test your assumptions, and derive the exact segmentation and pricing intelligence required to execute with confidence.
For detailed analysis of this topic, please visit the official page: Solar Ingot Wafer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: HD Microcellular PU Foam Market to Reach USD 2,115M by 2032 at 6.5% CAGR
By pmarketresearch, 2026-07-30
High Density Microcellular Polyurethane Foam: Strategic Preview for 2026 Decision‑Makers
Introduction — why this preview matters
As organizations enter 2026 with capital allocation, product roadmaps, and supply‑chain redesigns on their agendas, the High Density Microcellular Polyurethane (HD‑MCPU) foam market presents a distinct mix of opportunity and risk. PW Consulting’s latest study (base year 2025, historical window 2020–2025, forecast 2026–2032) frames that environment with quantitative backbone and actionable implications. The market is sizable and expanding — driven by demand in technical applications — and our analysis highlights where executive teams should concentrate attention this year to convert growth into durable competitive advantage.
High Density Microcellular Polyurethane Foam Market
Market at a glance — macro trajectory without revealing the playbook
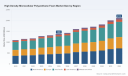
Key macro signals every senior leader must internalize: the HD‑MCPU foam market has demonstrated steady expansion through the first half of the decade and continues to compound. The report’s base year (2025) anchors a market value measured in the hundreds of millions (USD, Million) with a mid‑single‑digit compound annual growth rate (CAGR) projected across 2026–2032. By the end of the forecast window the market is materially larger than the 2025 base, reflecting both organic demand from established industrial verticals and emergent uses in electrification and precision manufacturing.
High Density Microcellular Polyurethane Foam Market
Two implications follow immediately. First, growth is sufficient to justify selective capacity investments and targeted R&D for firms seeking technical differentiation. Second, growth is not uniform — it is concentrated in technically demanding applications and geographies where regulatory and logistics dynamics can materially change cost economics within quarters. Our study provides the granularity to prioritize where to put money at risk; this preview is designed to orient strategy and highlight the questions that must be answered before capital is committed.
High Density Microcellular Polyurethane Foam Market
What 2026 decisions this market influences
- Procurement & commodity hedging: With polyurethane feedstock prices remaining volatile, procurement teams must move beyond yearly contracts. Dynamic hedging, supplier segmentation, and options for backward integration are now strategic imperatives.
- CapEx and footprint strategy: Mid‑term capacity additions make sense only when matched to technical capabilities and local input cost economics. Consider modular micro‑scale lines for regional flexibility rather than single, large greenfield plants.
- Product & application strategy: The highest returns accrue to formulations and machining capabilities that reduce tolerance, thermal conductivity, or outgassing for EV, aerospace, and medical instrument use cases. Prioritize product roadmaps that raise switching costs for key buyers.
- M&A and partnerships: The market is moderately concentrated among a handful of specialists. M&A can rapidly scale capabilities and customer access, but must be evaluated against integration complexity and raw material exposure.
- Risk management & regulatory compliance: Environmental constraints on feedstocks and emissions are tightening; compliance strategies must be budgeted into product lifecycle costs and go‑to‑market timelines.
Dynamics shaping the 2026 landscape
Three categories of dynamics dominate the near‑term outlook: raw‑material economics, logistics & trade, and regulation. Each directly influences margin, time‑to‑market, and strategic optionality.
- Raw‑material economics: Polyurethane input costs have shown renewed upward momentum in early 2026. Analysts reported polyurethane prices in Europe at approximately 3.48 USD/kg in March 2026, with upward movement driven by elevated MDI and polyol feedstock costs. South America experienced a similar cost lift, with prices near 3.43 USD/kg and a significant rise through the winter months due to constrained cargo availability and feedstock pressure. These inputs drive variable cost and can quickly compress margins on commoditized products.
- Logistics & freight: Freight disruptions and rerouting raised landed costs for imports in key manufacturing hubs during early 2026, increasing the value of local capacity or nearshoring strategies. Transport surcharges are no longer a short‑term cost blip; they are a structural element for regional sourcing models.
- Regulatory pressure: Environmental scrutiny on raw materials and the carbon footprint of intermediate chemicals has intensified. Regulators are enforcing lifecycle considerations that affect formulations, permissible emissions, and waste management. Compliance timelines should be embedded in product development and customer contracts today.
Competitive landscape — who matters and what they bring
The HD‑MCPU foam market is populated by specialized incumbents and a small but growing set of technical suppliers. Market concentration metrics indicate meaningful market share held by the leading firms (CR3 and CR5 at moderate levels), creating both an entry barrier and a landscape of potential partnership targets.
- Rubberlite Inc. (Huntington, WV) — https://www.rubberlite.com/ Rubberlite’s HyPUR‑cel® family is a clear example of a focused product architecture for technical applications such as gasketing, sealing, and industrial components. Their strength lies in differentiated product specifications and longstanding relationships in industrial segments that value consistency and post‑sale support.
- XYFoams (Hubei Xiangyuan New Material Technology Inc.) (Xiaogan, Hubei Province, China) — https://www.xyfoams.com/ XYFoams is notable for breadth in density range and for addressing emerging high‑growth needs like EV battery insulation and precision electronics. They combine scale with cost competitiveness, making them a natural partner or competitor depending on regional strategy.
- General Plastics Manufacturing Co. (Tacoma, WA) — https://www.generalplastics.com/ General Plastics’ LAST‑A‑FOAM® portfolio targets aerospace and precision engineering applications where tolerances, material stability, and certification pathways are central. Their go‑to‑market strength is technical validation and regulatory familiarity.
- Urethane Technologies International (Monroe, WA) — https://www.utech-polyurethane.com/ Urethane Technologies focuses on high‑quality urethane foam production with an emphasis on microcellular high density variants for industrial and technical uses. Their value proposition is process control and customization for customer‑specific performance.
For decision‑makers, the takeaway is straightforward: business models that combine technical depth with supply‑chain resilience command premium positioning. Whether through vertical integration, long‑term offtake agreements, or collaborative development contracts, securing upstream inputs and certification pathways accelerates de‑risking.
Practical, operational levers for 2026
- Short term (0–12 months): Lock in flexible supply agreements that include escalators and volume bands; establish a cross‑functional materials war room to monitor feedstock indices daily; prioritize customer contracts that pass a portion of feedstock risk through indexation clauses.
- Medium term (12–36 months): Invest in modular capacity and regional finishing operations rather than single large plants; develop co‑innovation labs with key OEMs to fast‑track qualified materials into EV and aerospace supply chains.
- Long term (36+ months): Evaluate upstream investments or minority stakes in polyol/MDI producers where regulatory shifts and feedstock security materially affect product economics; pursue bolt‑on acquisitions that bring process IP, certification history, or market access to priority verticals.
What PW Consulting’s full report delivers (and what this preview intentionally withholds)
Our full market study provides the operational detail required to execute the 2026 plays outlined above. Deliverables include:
- Detailed market volumes and value by segment, region, and application across the historical and forecast windows (2020–2032).
- Scenario models that stress test margins under different feedstock price, freight, and regulatory outcomes — plus sensitivity matrices for capital projects.
- Benchmarked supplier performance and supplier‑level scorecards that evaluate cost, technical capability, lead time reliability, and compliance risk.
- Deal‑ready strategic options: a prioritization framework for M&A targets, partnership templates, and phased integration roadmaps.
- Operational playbooks for procurement, quality assurance, and product qualification tailored to high‑density microcellular formulations used in high‑value applications.
In this preview we have deliberately avoided publishing granular regional or application split figures and certain product‑level economics. That core segmentation data is the most valuable intelligence for commercial negotiations and capital allocation — and it is included in the complete report and associated data‑dashboards.
Final strategic advice for 2026
Executives should treat HD‑MCPU foam not as a commodity but as a strategic intermediate where formulation, process control, and supply certainty determine competitive advantage. The combination of mid‑single‑digit CAGR and concentrated supplier capabilities favors focused investment in technical differentiation, flexible sourcing, and regulatory readiness. If you are preparing capital plans, supplier selection criteria, or R&D roadmaps for 2026, act now: secure your feedstock exposure, validate materials with high‑priority customers, and consider targeted partnerships to accelerate qualification cycles.
To convert these directional recommendations into executable decisions — supported by the data and scenario analysis that senior teams require — access the full PW Consulting High Density Microcellular Polyurethane Foam Market study. The complete report contains the proprietary segmentation, supplier scorecards, and financial models that underpin the strategic plays outlined here.
Contact PW Consulting or visit our source webpage to request the report, the interactive data‑dashboards, and a tailored briefing for your executive team.
For detailed analysis of this topic, please visit the official page: High Density Microcellular Polyurethane Foam Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Mango Butter Market Poised for 6.98% CAGR Through 2032
By pmarketresearch, 2026-07-30
Mango Butter Market — Strategic Briefing for 2026 Decision Makers
Executive summary
By the end of our historical baseline (2025, base year), the global mango butter market has moved from a niche ingredient to a commercially material ingredient in cosmetics, food, and select pharmaceutical formulations. PW Consulting’s market model shows growth from roughly USD 100 million in 2020 to USD 145 million in 2025, with our forecast extending through 2032 at a compound annual growth rate (CAGR) of 6.98% — crossing the USD 230 million threshold by 2032. For executives preparing budgets, supply strategies, or M&A activity in 2026, this trajectory signals both predictable expansion and a window where strategic moves will disproportionately shape market share and margin profiles.
Mango Butter Market
Why this matters for 2026 strategy
-
Timing: 2026 is the inflection point when steady annual growth transitions into accelerated scale for premium formulations and specialty industrial applications. Firms that lock in supply, certification, and formulation advantages in 2026 capture compounding benefits through the forecast window (2026–2032).
Mango Butter Market -
Margin leverage: As demand for refined, low-melt and certified variants rises, price realization diverges between commodity-grade butter and differentiated SKUs. Companies that proactively invest in downstream formulation capabilities and certification (organic, halal, fair-trade) will see higher margin expansion than pure bulk suppliers.
Mango Butter Market -
Risk consolidation: Market concentration metrics indicate meaningful advantage for a small set of incumbents. The top-tier players control a material share of the market, creating both barriers and acquisition opportunities for challengers in 2026.
Market trajectory and what the numbers tell us
The market’s growth path is not speculative — it is measured. From around USD 100 million in 2020 to USD 145 million in 2025, demand has been driven by expanding use in cosmetics and food applications and by ongoing innovation in formulation science (including low-melt and refined variants). At a projected CAGR of 6.98% across 2026–2032, market expansion is steady rather than explosive, which means the competitive advantage lies less in capturing a one-time spike and more in sustained strategic positioning: securing preferred suppliers, developing branded ingredient lines, and integrating traceability and sustainability claims across the value chain.
Supply-side dynamics: seasonality, sourcing, and cost pressure
-
Raw material concentration: Mango butter production is inherently linked to mango kernel availability, which is seasonally and geographically concentrated. This introduces recurrent supply volatility and creates premium pricing windows. New entrants must account for these cyclical constraints when modeling working capital and storage strategies.
-
Labor and collection model: In key sourcing geographies, production remains largely manual and organized through cooperatives. This model supports authenticity and social-impact positioning (e.g., fair-trade claims) but also exposes buyers to labor-cost inflation and collection bottlenecks. Buyers that invest in cooperative partnerships or contract farming mechanisms can secure preferred access and reduce volatility.
-
Regulatory backdrop: Policy measures affecting mango exports and domestic markets matter. For example, measures introduced to protect local growers can alter export economics for kernel feedstock. Firms must maintain an active regulatory watch to anticipate shifts in export pricing and raw-material availability.
-
Buyer economics: Minimum order quantities at the smaller end of the market (low-pound orders for butters and oils) enable boutique formulators but limit scale advantages for larger buyers unless they negotiate consolidated supply agreements. Structuring purchase terms to aggregate demand across product lines is a straightforward lever to improve sourcing economics.
Competitive landscape and strategic plays
The current supplier base includes diversified ingredient houses, regional processors, and cooperative-sourced specialty producers. The market exhibits moderate concentration: a few incumbents command significant share, but there remains room for specialized entrants that offer product differentiation or supply assurances.
-
Shay and Company Inc. — Millwaukie, Oregon: Competitive strength lies in certified organic and Halal, non‑GMO bulk offerings targeted to cosmetics and soap manufacturers. Their positioning highlights the transactional wholesale channel combined with certification-driven product premiumization. For buyers targeting the clean-beauty segment, Shay is a preferred partner for scale-certified sourcing.
-
Jedwards International, Inc. — Braintree, Massachusetts: A bulk supplier with both conventional and organic lines, Jedwards’ recent product innovation (April 2025 launch of a Low Melt / Olein variant) demonstrates how formulation-driven SKUs can unlock new formulation use-cases, particularly in personal-care products where tactile properties matter. This is an example of upstream product evolution directly enabling downstream product innovation.
-
Pure Check India Pvt. Ltd. — Pune, India: Focused on refined mango butter in bulk drums, their capability is critical for manufacturers that prefer consistency and neutral sensory profiles. Refining capability is a differentiation axis — it reduces batch variability and broadens applicability in high-volume cosmetic lines.
-
Manorama Industries Limited — Raipur, India: With a portfolio rooted in wild, cooperative-sourced, fair-trade mango butter and recent industry recognitions, Manorama exemplifies the sustainability + provenance play. Their awards and certifications provide a credible narrative for brands seeking traceable social impact stories.
Strategic implication: competing firms should choose one or two of the following plays in 2026 — (a) upstream integration through cooperative partnerships and kernel processing; (b) product differentiation via low-melt/refined variants and certification ladders; or (c) commercial consolidation through strategic partnerships and targeted M&A to capture scale and reduce supply risk.
Practical content in the full report (what you will get)
PW Consulting’s full Mango Butter Market report is designed as an operational decision toolkit for 2026. Key deliverables include:
-
Top-line market model with historicals (2020–2025) and scenario-based forecasts (2026–2032), including sensitivity analyses tied to raw-material price swings and adoption curves for differentiated SKUs.
-
Supplier and sourcing dashboard: verified supplier profiles, capability maps, and a risk heatmap for seasonality, political/regulatory exposure, and labor-cost inflation.
-
Commercial playbooks and go-to-market templates for ingredient brands, private-label manufacturers, and co-manufacturers — covering pricing strategies, certification roadmaps, and minimum viable SKUs.
-
Transaction support: M&A target screening criteria, valuation ranges, and integration checklists for those pursuing inorganic growth or backward integration into kernel processing.
-
Sustainability and traceability framework: how to structure cooperative partnerships, CRM-based traceability, and consumer-facing claims that withstand due diligence.
Risk vectors and mitigation tactics
-
Supply shocks: build dual-sourcing arrangements across origin regions and secure forward contracts with cooperative alliances to flatten seasonality-driven variability.
-
Price exposure: use structured purchasing (options, capped forwards) and consider inventory pre-positioning in bonded facilities to mitigate short‑term spikes.
-
Regulatory shifts: maintain a regulatory-readiness playbook. Export restrictions and minimum import price measures can alter landed costs rapidly — a cross-functional team linking commercial, legal, and procurement is non-negotiable.
-
Quality and certification risk: invest in third-party testing, batch traceability, and supplier-audit programs. Brands pay premiums for certifiable claims; failing on claims risks brand equity and retail partnerships.
Actionable recommendations for 2026
-
Prioritize supply security in Q1–Q2 2026: negotiate multi-year offtake with cooperative networks or processors and build safety stock for critical SKUs.
-
Segment your commercial approach: allocate resources between commodity bulk programs and a differentiated SKUs roadmap (refined, low-melt, certified). Each requires different supplier relationships and margin expectations.
-
Invest selectively in product innovation: small-format trials of low-melt or olein variants can identify high-value formulation applications before committing to broader rollouts.
-
Scan M&A and JV opportunities: incumbents with scale advantage are likely consolidators. For challengers, targeted partnerships or bolt-on acquisitions of refining/processing assets accelerate capability build-out with lower execution risk.
-
Embed sustainability credentials into procurement and marketing: traceability and fair-trade narratives materially influence buyer preference in cosmetics and premium food channels.
Concluding perspective
For 2026, mango butter is a market where executional rigor matters more than speculative timing. The ROI on investments in supply security, formulation capability, and certification will compound over the forecast window. PW Consulting’s in-depth study provides the decision-grade inputs you need — from scenario-validated financial models to supplier scorecards and M&A playbooks. This briefing highlights the strategic lines of attack; the full report contains the granular splits, pricing matrices, and unit economics necessary to operationalize these recommendations.
Next steps
If your 2026 plan requires prioritized supplier shortlists, transaction-ready due diligence materials, or a tailored sourcing playbook, PW Consulting can prepare a bespoke module aligned to your risk appetite and commercial objectives. Access to the full segmented datasets, granular region/application breakdowns, and supplier-by-supplier financials is available in the full market report and will be essential for execution-ready decisions.
For detailed analysis of this topic, please visit the official page: Mango Butter Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Surge Arresters Market to Hit USD 2,717M by 2032 at 5.5% CAGR
By pmarketresearch, 2026-07-30
Surge Arresters Market: Strategic Imperatives for 2026 Decision‑Makers
As utilities, industrial operators and power equipment OEMs prepare capital plans and sourcing strategies for 2026, the surge arresters market presents a concrete — and manageable — growth opportunity. PW Consulting’s latest market study, anchored on a 2025 base year and covering the historical period 2020–2025 with a forecast to 2032, maps a steady recovery and structural expansion at a compound annual growth rate (CAGR) of 5.5%. Measured in USD millions, the global market has materially expanded since 2020 and is projected to approach a broader market scale by 2032, highlighting sustained demand tied to grid modernization, electrification and resilience investments.
Surge Arresters Market
Why this study matters for 2026 choices
-
Actionable timing: With a forecast window beginning in 2026, the report converts macro momentum into year‑by‑year decision points — acquisition targets, product launches, qualification cycles and inventory posture — that align to board and procurement calendars.
Surge Arresters Market -
Risk‑aware growth: A 5.5% CAGR does not imply uniform growth across technologies, voltages or geographies. Our study reconciles growth trajectories with policy and standards timing to prioritize where to deploy limited capital in 2026 without exposing confidential segment tables in this overview.
Surge Arresters Market -
Competitive posture: The market’s concentration metrics (CR3 ~29.5%, CR5 ~42.8%) indicate meaningful leader advantages but also room for challengers. That combination creates opportunities for targeted M&A, differentiation via product integration and local manufacturing strategies.
-
Procurement and specification: Procurement teams will face evolving qualification regimes and seismic/insulation performance expectations that materially affect lead times and qualification costs. The study translates these implications into procurement playbooks for 2026 cycles.
What the report delivers (practical, ready‑to‑use outputs)
-
Time‑series market model: Full historical (2020–2025) and forward (2026–2032) market-sizing by primary dimensions, with sensitivity scenarios to reflect policy and tariff shocks.
-
Demand drivers and use‑case profiles: Clear articulation of utility, industrial and transmission triggers that determine replacement vs. new‑build procurement.
-
Supply‑side cost and margin analysis: Benchmarking of manufacturing economics, MOV element sourcing considerations and housing material tradeoffs that influence product roadmaps.
-
Vendor scorecards and strategic options: Comparative assessment of incumbent and challenger firms across technology, global footprint, product breadth and aftermarket service capability.
-
Regulatory and standards heatmap: Timing and procurement impact of key standards, seismic performance amendments and emerging qualification regimes.
-
Strategic playbooks: M&A screen, partnership templates, and procurement strategies tailored for 2026 RFQs and multi‑year contracts.
Competitive landscape — what we see and why it matters
The market structure pairs large, integrated electrical equipment groups with specialized protection vendors and regional manufacturers. A few observations drawn from our analysis:
-
Technology and system integration leaders. Global engineering groups that offer surge arresters as part of broader transformer and grid portfolios (for example, firms with deep MV/HV lines and integrated product systems) are leveraging system‑level bundling to protect margins and shorten customer procurement cycles.
-
Specialist protectors. Companies focused on surge protection elements and device performance bring rapid innovation in zinc‑oxide MOV formulations, polymer housing design and compact solutions for distribution networks. Such specialists are attractive partners for OEMs seeking faster time to market for niche applications.
-
Distribution and field service strength. Firms with in‑house production of MOV discs, polymer housings and strong field service networks capture aftermarket and retrofit opportunities — a critical growth area as utilities prioritize lifecycle management over one‑off purchases.
-
Regional manufacturers and new entrants. Manufacturers rooted in growth markets offer competitive pricing and local qualification knowledge. Their presence increases procurement options but also requires careful supplier risk assessment to manage quality and standards compliance.
Notable recent moves that inform 2026 strategy include product integrations that improve system reliability, targeted acquisitions that broaden grounding and lightning protection capabilities, and new product introductions extending protection to military and high‑reliability applications. These developments underscore two trends: consolidation of technical capability via acquisition, and continuing product innovation at both ends of the market.
Regulatory and standards dynamics shaping 2026 procurement
-
Standards remain a gating factor. IEC 60099‑4 continues as the baseline qualification reference for metal‑oxide surge arresters; compliance will remain a minimum procurement requirement in most jurisdictions.
-
Seismic and performance updates. The recent IEEE amendment addressing seismic performance of high‑voltage substation arresters raises qualification costs and extends lead times for certain installations; buyers must plan for these certification windows.
-
New technical standards under development — including workstreams for controllable metal‑oxide arresters in ultra‑high voltage systems — signal future product differentiation and qualification needs that should be tracked by R&D and procurement teams now.
-
Trade and local content. Geopolitical measures and tariff reviews continue to influence sourcing risk. Even where tariffs remain under review, localization strategies and dual‑source supplier models mitigate procurement exposure.
Strategic actions for 2026 (a concise playbook)
-
Convert forecast visibility into procurement cadence: Use the report’s year‑by‑year forecasts to align RFQs, qualification tests and inventory buffers so that 2026 projects are not delayed by testing cycles or lead‑time volatility.
-
Prioritize standards and seismic qualifications in project budgets: Anticipate incremental qualification costs and longer qualification windows for high‑risk sites; build these into contract terms and acceptance criteria.
-
Use CR metrics to inform M&A and partnership targets: The market’s moderate concentration suggests opportunities for bolt‑on acquisitions or technology partnerships to expand installed bases or margin profiles.
-
Hedge supply risk tactically: Adopt dual‑sourcing or regional buffer strategies for critical MOV components and polymer housings, and assess the trade‑offs between price and reliability in supplier scorecards.
-
Invest in aftermarket and digital monitoring: Condition‑based maintenance and digital surge logging increase value capture and create service revenue streams that compound unit growth.
Why PW Consulting’s study is the right reference for your 2026 planning
Our research team couples a bottom‑up component model with payer/owner interviews across utilities, industrial end‑users and OEM procurement teams. The deliverables are intentionally practical: downloadable model files, vendor scorecards, procurement templates and a scenario toolkit that stress‑tests plans against standards changes, tariff outcomes and accelerated electrification scenarios. Importantly, this introduction purposefully omits the granular segment tables and proprietary vendor valuations included in the full report — those detailed intelligence assets are preserved for the full report and consulting engagements to protect client value and encourage direct dialogue.
In a market expanding at a mid‑single‑digit CAGR from a well‑established 2025 base and projected to reach a materially larger scale by 2032, the difference between competing successfully and under‑performing will be the precision of your 2026 execution plan: the suppliers you qualify, the standards you pre‑approve, and the partnerships you form. PW Consulting’s Surge Arresters Market study translates market momentum into a disciplined set of actions that deliver measurable outcomes for procurement, product and corporate development teams.
For the full set of segment‑level forecasts, supplier scorecards and our scenario model, access the complete report or contact PW Consulting’s advisory team to schedule a briefing tailored to your 2026 planning cycle.
For detailed analysis of this topic, please visit the official page: Surge Arresters Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Annatto Market: Strategic Imperatives for 2026 — PW Consulting Preview
As companies finalize 2026 strategies, the trajectory of natural colorants — and annatto in particular — will determine product roadmaps, supply-chain choices, and M&A targets across food & beverage, cosmetics, and specialty ingredients. This preview introduces PW Consulting’s full Annatto Market research and explains why our findings will be a practical, decision-grade input for executive teams this year. We show the analytical thrust and proprietary framing we used to reach conclusions, while reserving the granular segment-level tables and forecasts for the full report to preserve the “trailer” dynamic: enough depth to inform, not enough to substitute for the primary analysis.
Annatto Market
Why annatto matters to corporate strategy in 2026
Annatto sits at the intersection of several converging strategic vectors: shifting clean-label preferences, reformulation pressures driven by regulatory and retailer demands, inflationary input-cost dynamics, and an expanding set of high-margin applications beyond traditional dairy coloring. For companies with exposure to colorants — ingredient manufacturers, co-packers, CPG brands, and private-label players — decisions made in 2026 about sourcing, formulation, and capacity will shape cost curves and differentiation for the rest of the decade.
Annatto Market
-
Reformulation momentum is accelerating: product teams face both retailer-driven clean-label requests and regulatory changes that change permissible processing routes and solvent profiles.
Annatto Market -
Commercial differentiation increasingly relies on certified stability and functionality (heat, pH, solvent compatibility) as much as on “natural” claims.
-
Fragmented supply and innovation topology creates exploitable niches for focused players — from encapsulation specialists to solvent-free extraction innovators.
Market trajectory at a glance (what our modeling shows)
PW Consulting’s base-year analysis uses 2025 as the reference point with historical calibration from 2020–2025 and a forecast window covering 2026–2032. The annatto market experienced a contraction during the early 2020s, declining from a peak in 2020 and stabilizing into 2025. Our macro model indicates a recovery beginning in 2026 and a steady upward trend through 2032, with a compound annual growth rate (CAGR) of 5.62% over the forecast period. By 2032 the market is projected to exceed its earlier peak and deliver material expansion versus 2025, driven by reformulation programs, new application wins, and greater commercialization of solvent-free and value-added grades.
Key high-level datapoints we reference in the full report (and calibrate all downstream modules to) include the historical series 2020–2025, the 2025 base, and the 2026–2032 forecast envelope. These headline numbers underpin scenario planning and sensitivity analytics presented in the complete study.
Regulatory dynamics — immediate implications for 2026 planning
The regulatory environment has shifted materially in early 2026. An FDA action in April 2026 altered permissible processing language around certain solvents used with annatto-derived extracts, which has two practical consequences:
-
Short-term reformulation & procurement shocks: formulators will need validated alternatives for legacy grades where solvent profiles changed, creating immediate demand for solvent-free and encapsulated products.
-
Medium-term differentiation: players that had invested earlier in solvent-free extraction, robust cleaning protocols, or alternative solvent platforms are positioned to capture incremental share as CPG customers accelerate reformulation timelines.
PW Consulting’s full report includes a regulatory appendix that maps these changes into operational checklists for R&D, regulatory affairs, and procurement teams — including timing windows for reformulation, label implications across major markets, and an assessment of compliance risk by product format.
Competitive landscape — who matters and why
The market remains fragmented with relatively low concentration among the top players (our CR3 and CR5 indicators show a market that is not tightly consolidated). That fragmentation creates opportunities for differentiated technology providers and contract manufacturers to scale quickly if they can secure distribution and specification wins with large food or cosmetic customers.
-
Large, integrated players (example profiles): Established flavor and ingredient conglomerates have leveraged their extraction platforms and global regulatory footprints to offer standardized annatto grades with global registration and stability claims. These suppliers win on scale, technical support, and route-to-market for multinational customers.
-
Specialists and solvent-free innovators: A cohort of nimble extract specialists emphasize solvent-free processes, odor-removal, or targeted pigment concentration. Their value proposition is clean-label compliance and tailored formulations for premium or plant-based applications.
-
Regional manufacturers: Several regional ingredient firms supply standardized, shelf-stable grades to local dairy, bakery, and beverage producers. Their strengths are cost and proximity; their challenge is meeting cross-border regulatory and certification requirements for global customers.
In the complete report, we publish company-level SWOTs, product positioning maps, and strategic scenarios that evaluate which type of player is most likely to benefit from each macro trend (e.g., volatility in raw-seed supply, rising demand for high-purity water-soluble grades, and encapsulation to improve light and pH stability). For confidentiality and competitive reasons we reserve detailed revenue and share tables for subscribers.
What’s inside the full PW Consulting Annatto Market report (practical deliverables)
The full research goes well beyond high-level commentary. It is designed to be directly actionable for commercial and product teams planning 2026 programs. Key modules include:
-
Market sizing and baseline model (2020–2025 historical, 2026–2032 forecast) with scenario toggles for supply shocks, accelerated reformulation, and premiumization demand curves.
-
Price and margin sensitivity analysis for key product formats, including break-even timelines for capital investments in alternative extraction or encapsulation equipment.
-
Go-to-market playbooks for ingredient suppliers and co-packers: format selection, sample-pack strategy, spec sheets, and commercial terms that win specification trials.
-
M&A and partnership screening: a prioritization matrix identifying the most accretive targets by capability (extraction tech, formulation IP, channel access).
-
Supply-chain risk maps and mitigation options: seed sourcing, inventory buffers, contract structures, and near-shoring scenarios.
-
Regulatory and claims roadmap with timelines and compliance checklists for food, cosmetic, and pharmaceutical uses in major jurisdictions.
-
Case studies and recipe-level reformulation notes from selective pilot programs with manufacturers, demonstrating how annatto grades perform across oil-based, water-based, and emulsified matrices.
Each module contains executive-ready slides, a data workbook with configurable inputs, and a one-page “action plan” tailored to one of three client archetypes: global ingredient supplier, regional manufacturer, or CPG brand.
Strategic recommendations for 2026 (what to do immediately)
-
Prioritize technical validation of solvent-free and encapsulated grades. Regulatory shifts mean that customers will favor suppliers who can demonstrate compliant, stable performance quickly.
-
Run value-based pricing pilots in premium applications. Where annatto can deliver clean-label differentiation (plant-based, organic, or allergen-free propositions), pricing power exists.
-
Lock in multi-year supply and quality agreements for seed and semi-finished intermediates. Volatility in upstream inputs can erode margins rapidly; structured contracts reduce exposure.
-
Evaluate bolt-on acquisitions that add specific technological capabilities (e.g., solvent-free extraction, microencapsulation) rather than volume alone — these deliver asymmetric returns in an innovation-driven window.
-
Embed regulatory surveillance into the product development lifecycle. Changes in additive approvals or solvent permissibility can create both compliance hazards and first-mover commercial advantage.
How PW Consulting’s report helps you act
Our work turns headline trends into executable choices. The headline macro forecast (base-year 2025; forecast 2026–2032; CAGR 5.62%) is more than a number: it is the input we use to stress-test pricing, manufacturing scale, and commercial commitments. The low market concentration we observe creates multiple playbooks — partner for scale, specialize for margin, or consolidate for efficiency — and our deliverables map each back to quantified outcomes and timelines.
Because this preview intentionally omits the detailed segmentation tables and company share matrices, decision-makers who need the full toolkit — market models, granular scenario outputs, step-by-step reformulation checklists, and supplier scorecards — should review the complete report. That package contains the downloadable data workbook and the actionable one-page plans that R&D, procurement, and M&A teams can use to execute in 2026.
Next steps
If your 2026 agenda includes ingredient sourcing, reformulation, or inorganic growth in natural coloration, PW Consulting’s Annatto Market report provides the analytical foundation and operational playbooks to move from strategy to execution. Reach out to our client services team to schedule a briefing, request the full data workbook, or commission a tailored workshop that maps these insights to your portfolio and margins.
For detailed analysis of this topic, please visit the official page: Annatto Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Carbon Fiber Bike Market to hit USD 344.8M by 2032 at 6.98% CAGR
By pmarketresearch, 2026-07-30
Carbon Fiber Bike Market — 2026 Strategic Preview
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present a focused strategic primer drawn from our full Carbon Fiber Bike Market study. This preview is written for executives, product leaders, investors, and supply‑chain managers who must make decisive moves in 2026. It highlights the commercial logic, competitive contours, and near‑term inflection points shaping the market — while intentionally reserving the detailed segment matrices and proprietary scenario outputs for the full report.
Carbon Fiber Bike Market
Market trajectory at a glance
The carbon fiber bike market has shown resilient expansion through the first half of the decade, rising from roughly 163 million USD in 2020 to about 215 million USD by 2025. Our forecast models, incorporating demand diffusion, cost inflation, and technology adoption curves, project continued growth to roughly 345 million USD by 2032, reflecting a compound annual growth rate of 6.98% across the 2026–2032 forecast window. That trajectory reflects a market that is maturing, but still amenable to structural shifts driven by material advances, distribution innovations, and competitive repositioning.
Carbon Fiber Bike Market
Why PW Consulting’s 2026 perspective matters
- Timing: 2026 will be a make‑or‑break year for players seeking to upgrade manufacturing capabilities or to shift to direct‑to‑consumer models — the window for cost recovery on recent tooling investments narrows rapidly.
- Material sensitivity: With standard modulus carbon fiber priced in the low‑two‑digit USD/kg range in 2026, small shifts in resin and fiber input costs materially affect profitability on entry and mid‑segment frames unless offset by layup efficiency or scale.
- Regulatory and safety premium: ISO 4210 remains the baseline safety standard; however, higher test thresholds (e.g., independent protocols exceeding ISO by meaningful multipliers) are becoming de facto differentiators for aspirational and premium brands.
- Competitive structure: Market concentration metrics indicate a moderately fragmented industry — sufficient room for consolidation but also for specialist entrants to carve defensible niches.
What’s inside the full report (practical, action‑oriented deliverables)
- Comprehensive market sizing and trailing 2020–2025 historical analysis, with transparent methodology and sensitivity tables.
- Seven‑year forecasts with scenario hulls (base, upside, downside) and the underlying assumptions for demand, price, and input cost trajectories.
- Demand archetypes and product playbooks — mapping frame architectures, layup approaches, and price bands to buyer personas.
- Supply‑chain maps and cost‑build models that quantify the levers (material, labor, process, rejection rates) that move gross margins.
- Regulatory landscape and testing matrix, including a practical checklist to upgrade QA programs beyond ISO 4210 toward more stringent industry protocols.
- Competitive benchmarking and capability heatmaps for 20+ manufacturers and OEM suppliers, highlighting R&D, manufacturing footprint, channel strategy, and brand positioning.
- Go‑to‑market playbooks (retail vs DTC vs hybrid), including short‑term promotional strategies and longer‑term brand architecture decisions.
- M&A and partnership screening framework — granular criteria to identify targets that accelerate access to technology, capacity, or distribution.
Key market dynamics and strategic implications
1) Premiumization with cost pressure. Demand continues to bifurcate: consumers seeking performance and weight gains remain willing to pay premium prices, while an expanding entry cohort looks for carbon fiber’s aspirational cache at accessible price bands. This dynamic forces incumbents to manage a classic two‑front battle — protect margin in high end while optimizing cost structures and manufacturing yields for lower price tiers.
Carbon Fiber Bike Market
2) Raw material volatility is a leverage point. With standard modulus carbon priced in the approximate USD 12–20/kg band in 2026, material cost swings materially reshape product economics. Companies that invest in optimized layups, automation or long‑term fiber supply agreements will see rapid margin improvements relative to peers that remain exposed to spot pricing.
3) Safety and durability as brand trust vectors. Compliance with ISO 4210 is table stakes; brands and OEMs that adopt testing regimes exceeding ISO will develop stronger claims for durability and safety, shortening the adoption cycle among discerning road and racing customers and premium fleet buyers.
4) Manufacturing and distribution bifurcation. We are observing parallel trends: European and North American brands double down on R&D, high‑precision machining and premium brand storytelling, while Asian OEMs scale sophisticated layup processes and DTC channels to deliver competitive price‑performance. The result is differential margin pools and the opportunity for win‑win partnerships that combine design, brand and scale.
Competitive landscape — what to watch from leading players
- Giant Manufacturing Co., Ltd. — Leveraging scale and OEM capability, Giant continues to push broad portfolio depth and value engineering, making it a default partner for brands seeking reliable capacity and consistent quality at scale.
- Trek Bicycle Corporation — Trek’s emphasis on integrated systems, rider analytics and carbon R&D keeps it competitive in premium road and endurance segments; expect further investments in material science and connected components.
- Specialized — Known for proprietary carbon technologies and rider‑centric design, Specialized prioritizes innovation and differentiation through material layups and ergonomics rather than competing on cost.
- Cannondale — Engineering intensity and legacy design IP position Cannondale to compete on performance and component integration, with opportunities in selective vertical manufacturing moves.
- Merida — Merida’s volume disciplines and product breadth give it leverage in mid‑market growth corridors, where cost control and rapid product refresh cycles matter.
- Scott, Colnago, Pinarello, Bianchi, Cervélo — These performance and boutique brands anchor the high end; their value is built on craftsmanship, race heritage and premium channel relationships.
- Canyon, Cube — Direct‑to‑consumer models from European challengers continue to compress distribution margins and redefine purchasing expectations for performance at price.
- Chinese manufacturers and brands (e.g., Winspace, Yoeleo, LightCarbon, Tiny Rock, ICAN) — Rapid product development cycles, improved layup technologies and aggressive cost structures have elevated these players from OEM role to brand competitor. Recent trade show launches and ultra‑light frame claims highlight rising technical competence and speed to market.
Market concentration indicators underline the room available for both established and insurgent players: while the largest groups command a meaningful share, a fragmented mid‑tier and nimble regional suppliers sustain competitive dynamism and opportunity for consolidation.
Recent signals from the field (select highlights)
- Exhibition and product demos at key trade shows in 2025–2026 highlight accelerating product cycles and a push toward aero integration and lightweight framesets.
- New product launches from smaller innovators have included ultra‑light frames and compact full‑suspension small‑wheel MTB models — indicators of both material capability and market experimentation.
- Manufacturers increasingly showcase advanced layup and integrated cockpit systems, signaling cross‑functional R&D investments that shorten the performance gap with legacy premium brands.
Practical next steps for 2026 decision makers
- Implement a material cost hedging and supplier diversification strategy to protect margin against fiber/resin price moves.
- Adopt a two‑lane product strategy: defend premium price points with differentiated R&D, and pursue efficiency and scale for accessible carbon offerings via targeted partnerships or in‑house process automation.
- Upgrade testing and QA frameworks beyond ISO 4210 where brand trust and fleet contracts are strategic priorities.
- Pursue selective M&A or JV opportunities to gain capacity, proprietary layup IP, or DTC channel expertise — but validate with bottom‑up integration models rather than headline multiples.
- Invest in real‑time analytics for demand sensing and price elasticity testing; short product cycles reward those who can shift production and marketing faster than competitors.
How PW Consulting helps — the missing mile
Our full Carbon Fiber Bike Market report delivers the detailed segmentation matrices, regional and application breakouts, supplier scorecards and scenario models that operational teams need to convert strategy into measurable programs. For 2026, we pair that product with advisory services: custom scenario modeling, sourcing due diligence, supplier audit playbooks, and M&A target screening calibrated to margin accretion and integration risk.
We designed this preview to surface the strategic choices that matter: material exposure, manufacturing footprint, channel design, and innovation cadence. The full dataset — including the granular splits and proprietary assumptions that underpin our forecasts — is available through the PW Consulting portal for those responsible for resource allocation in 2026.
Contact our team to arrange a briefing and obtain the complete report, including the actionable workstreams your organization will need to capture share and protect margin as the carbon fiber bike market enters its next chapter.
For detailed analysis of this topic, please visit the official page: Carbon Fiber Bike Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Baby Stroller & Pram Market to Reach USD 4,117.7M by 2032 (CAGR 4.58%)
By pmarketresearch, 2026-07-30
Baby Stroller and Pram Market 2026 Strategic Brief: Actionable Insights for Corporate Decision‑Making
Executive summary
As the global baby stroller and pram market enters the mid‑2020s inflection, corporate leaders face a narrow window to translate steady market expansion into durable competitive advantage. Our baseline analysis shows the sector expanding from roughly USD 2.3 billion in 2020 to USD 3.0 billion by 2025, and the PW Consulting forecast through 2032 anticipates continued growth at a compound annual growth rate of approximately 4.58% over the 2026–2032 horizon, bringing the market to just over USD 4.1 billion by 2032 under the base case. That trajectory masks important dynamics—accelerating premiumization in developed markets, margin pressure in value tiers, and a heightened regulatory and safety scrutiny that can rapidly reprice reputational capital.
Baby Stroller and Pram Market
Why this research matters for 2026 corporate decisions
-
Investment timing and capital allocation: With a predictable mid‑single‑digit CAGR, companies can plan multi‑year capex and product investments with greater confidence—but only if they account for volatility introduced by safety recalls, supply chain disruptions, and rapid product obsolescence in design‑led segments.
Baby Stroller and Pram Market -
Portfolio prioritization: Our historical series (2020–2025) reveals a period of moderate growth followed by a renewed acceleration into 2024–2025. This pattern implies that companies who shift resources into higher‑growth sub‑segments and modular product lines in 2026 will capture outsized share in the years that follow.
Baby Stroller and Pram Market -
M&A and partnership timing: Market consolidation is incremental rather than sweeping. The competitive landscape leaves opportunity for bolt‑on acquisitions and strategic alliances that can close capability gaps (e.g., safety‑tech, digital services, regional distribution) without requiring transformational buyouts.
-
Regulatory and quality risk management: Recent industry events underscore how product safety incidents quickly become strategic inflection points. Robust pre‑market testing, traceability, and crisis playbooks are no longer optional.
Scope and practical contents of the PW Consulting report
The report is designed as a pragmatic playbook for commercial, product, and corporate development teams. It combines rigorous market modeling with executable tools and includes:
-
Market sizing and methodology: a transparent approach reconciling demand‑side indicators with supplier shipment data and retail sell‑throughs for 2020–2025, and scenario‑based projections for 2026–2032.
-
Segmentation framework and demand drivers: a detailed segmentation architecture (by product type, application and channel) and the callouts that matter for go‑to‑market planning—note that granular segment tables are available in the full report.
-
Competitive benchmarking: capability heatmaps, product portfolios, price ladders, and go‑to‑market positioning for the leading firms operating across premium, mid, and value tiers.
-
Distribution and channel economics: margins, cost‑to‑serve, and trade promotion effectiveness across wholesale, retail, and direct‑to‑consumer models, including playbooks to improve conversion and LTV.
-
Supply chain and sourcing risk matrix: supplier concentration, country‑level sourcing scenarios, and recommendations for near‑sourcing vs. offshore optimization.
-
Regulatory & safety tracker: active recall log, regional certification requirements, and an incident response framework to protect brand equity under stress.
-
Innovation and product roadmaps: modular design templates, materials roadmaps (incl. sustainability levers), and a prioritized R&D investment map tied to ROI thresholds.
-
M&A and partnership playbook: target screening criteria, valuation heuristics, and integration checklists to accelerate value capture.
-
Interactive Excel model & dashboards: scenario toggles, sensitivity analysis for price and mix, and presentations ready for board review.
Competitive landscape: positioning and implications
The market is populated by a spectrum of players—from design‑led premium houses to mass‑market cost players. Our competitive analysis of the core incumbents yields clear strategic implications for 2026:
-
UPPAbaby (United States) : A premium player focused on full‑size and mid‑size strollers with advanced suspension and modular systems. UPPAbaby’s product engineering strength supports a premium pricing strategy and franchise expansion—but sustaining growth requires expanding service ecosystems and international distribution partnerships. A recent May 2026 launch of a mid‑size Kona model underscores their cadence of product refreshes and the importance of modular platforms that scale across use cases.
-
Bugaboo International (Netherlands) : Known for lightweight, design‑first strollers and a strong social‑brand presence. Their strength is brand desirability and design IP; the strategic task is converting high awareness into repeat cross‑sell and resilient margin streams through accessories and certified service programs.
-
Chicco (Italy) : A mid‑range player with a reputation for safety certifications and broad retail presence. Chicco’s strategy should emphasize channel rationalization—optimizing between bricks‑and‑mortar distribution and D2C—while protecting margins via product rationalization.
-
Britax (UK) : A safety‑centric brand whose integrated car seat travel systems differentiate on child protection. Their competitive edge is technical safety credentials; they must now monetize that credibility through premium services (installation support, extended warranties) and data‑capture at point‑of‑sale.
-
Dorel Industries / Maxi‑Cosi & Safety 1st (Canada) : Platform scale and localized manufacturing provide a cost advantage in important markets. Dorel’s playbook benefits from SKU optimization and leveraging scale to negotiate channel economics.
-
Graco (United States) : Resilient in the value and travel‑system segments due to integrated car‑seat compatibility. However, recent safety incidents (a recall affecting specific infant car seats in early 2026) demonstrate how product quality issues can cascade into elevated regulatory scrutiny and short‑term demand disruption. Companies must model recall scenarios into working capital and brand remediation plans.
-
Evenflo (United States) : Budget‑focused with a steady stream of launches. Their aggressive new‑product cadence pressures industry margins and accelerates the need for cost productivity improvements among competitors.
-
Goodbaby International (Hong Kong) : A platform manufacturer with broad OEM/brand capabilities. Their scale in Asia and breadth of platforms make them a logical partner for coalition manufacturing, but partner selection must consider IP protection and quality governance.
-
Stokke (Norway) : Ultra‑premium with distinctive design leadership. Stokke’s challenge is scaling without diluting exclusivity—subscription and white‑glove services can enhance ARPU while preserving brand equity.
-
Mamas & Papas (UK) : Accessible, everyday prams and strollers with strong retail resonance. Their focus should be on optimizing assortments and elevating in‑store experience to defend share versus private label entrants.
Strategic imperatives for 2026
-
Design modularity and platform rationalization: prioritize platforms that serve multiple applications to reduce time‑to‑market and SKU complexity.
-
Invest in safety as a commercial differentiator: certification, telematics for incident logging, and transparent quality metrics boost trust and support premium pricing.
-
Channel rebalancing towards D2C and omnichannel analytics: optimize margins by reallocating spend from unprofitable retail channels into owned commerce and service subscriptions.
-
Supply chain reshoring where it matters: near‑sourcing critical components to mitigate recall and lead‑time risks while preserving cost efficiency for commoditized parts.
-
Service and recurring revenue: introduce care plans, accessory bundles, and trade‑up programs to increase customer LTV.
-
Sustainability as product strategy: deploy materials roadmaps that lower total lifecycle cost and satisfy fast‑moving retail sustainability requirements.
-
Scenario planning and capital buffers: stress‑test plans against recall events, tariffs, and shifts in consumer spend—preserve liquidity to act on opportunistic M&A.
How to use this research in boardroom and execution
For CEOs and boards, the report is a decision‑quality input to the 2026 strategic planning cycle. Use it to:
-
Validate or reallocate R&D and capex plans based on product life‑cycle returns;
-
Shape M&A screens and prioritize targets with clear synergistic economics;
-
Set KPIs for product family margin, time‑to‑market, and recall risk exposure; and
-
Frame commercial pilots—pricing experiments, subscription bundles, and D2C cohorts—using the provided Excel scenarios for rapid A/B testing.
Next steps and where to get the full intelligence
This brief demonstrates the strategic opportunity and risk map for the baby stroller and pram market heading into 2026. PW Consulting’s full report contains the datasets, detailed segmentation tables, regional and application splits, pricing ladders, and the downloadable modeling toolkit that allow teams to execute the tactical moves outlined above. For executives preparing a 90‑day turnaround plan, we recommend downloading the full dataset and scheduling a dedicated strategy workshop to convert the analysis into a prioritized roadmap.
PW Consulting’s approach is centered on turning market foresight into implementable initiatives—benched against historical performance, tested through scenario analysis, and packaged with executable templates. The summary here is intentionally selective; the complete intelligence suite is available on our report page for teams ready to act decisively in 2026.
For detailed analysis of this topic, please visit the official page: Baby Stroller and Pram Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Automotive Front End Module Market to Reach USD 222.5M by 2032 (6.1% CAGR)
By pmarketresearch, 2026-07-30
Automotive Front End Module Market: Strategic Imperatives for 2026 Decision‑Makers
As OEMs accelerate electrification, advanced safety systems and life‑cycle transparency, the front end module (FEM) has evolved from a parts bundle into a strategic vehicle subsystem. PW Consulting’s latest market model (base year 2025) places the global FEM market at USD 147.1 Million, rising from USD 108.5 Million in 2020. Under our central scenario the market grows at a 6.1% CAGR across the 2026–2032 forecast window, reaching roughly USD 222.5 Million by 2032. For executives planning 2026 decisions, that trajectory changes how product architecture, supply‑chain strategy and capital allocation should be prioritized.
Automotive Front End Module Market
Why this research matters in 2026
-
Time‑sensitive integration. FEMs are now convergence zones for thermal management, ADAS sensors, and aerodynamic systems in EVs. Decisions taken in 2026 about platform architectures and supplier partnerships will lock in performance and cost outcomes for a multi‑year horizon.
Automotive Front End Module Market -
Regulatory and reputational risk. New life‑cycle reporting requirements and tightened safety testing protocols increase the technical and compliance burden on FEM designs; early alignment reduces rework and certification delays.
Automotive Front End Module Market -
Value capture changes. The FEM’s role in vehicle differentiation—lighting, active aero, sensor mounting, and thermal pathways—creates new opportunities for OEM differentiation or supplier monetization via platform licensing and co‑engineering.
High‑level market dynamics shaping 2026 choices
-
Electrification and thermal integration: EV architectures require FEMs that integrate battery and power‑electronics cooling pathways. Expect prioritized spend on thermal‑capable FEM variants and consolidated thermal/electrical architectures.
-
ADAS and sensor convergence: Safety protocols now mandate higher levels of integration for cameras, radars and lidars. FEMs that deliver robust, serviceable sensor platforms without aerodynamic penalty will command a premium.
-
Lightweight materials and LCA pressure: Material innovation—long‑fiber thermoplastics, laser‑welded assemblies, fiber‑placed composites and recycled metal/bio‑resins—are being adopted to meet mass reduction and life‑cycle constraints.
-
Modularization vs. unique differentiation: OEMs face a trade‑off between cost‑efficient standardized FEM platforms and bespoke modules that enable distinct vehicle identity (lighting signatures, active grilles, integrated sensors).
-
Supply resilience and concentration: While several global Tier‑1s dominate platform supply, niche specialists are capturing value in new material and sensor integration capabilities—creating a mixed landscape of consolidation and specialization.
Technology and materials trajectory — what 2026 buyers should prioritize
-
Thermal/structural co‑design: Recent supplier advances (early‑2026 product moves) demonstrate integrated thermal paths in FEMs that cool batteries and power electronics while preserving crash performance. Buyers should require thermal validation data earlier in design cycles.
-
Sensor‑first FEM architectures: With Euro NCAP and related protocols pushing AEB and lane support mandates, FEMs must be designed as primary sensor hosts. Sensor calibration, maintainability and electromagnetic compatibility (EMC) must be specified up front.
-
Material plurality: Laser‑welded steel subframes remain cost‑effective for some platforms, but LFT‑based and fiber‑placed composite solutions are proving lighter and more assembly‑friendly for C‑segment and SUV applications. Procurement teams must build dual‑material sourcing roadmaps to respond to regional material availability and LCA targets.
-
Active aero and integrated lighting: The combination of aerodynamic shutters, lighting modules and grille surfaces is converging into unified façade systems—creating opportunities for integrated suppliers but raising complexity for service networks.
Competitive landscape: profiles and implications
The FEM market is populated by a mix of diversified Tier‑1 systems integrators and specialist product houses. Strategic implications for OEMs and suppliers are summarized below; the full competitive scorecards and supplier capability maps are detailed in the full report.
-
Magna International — positioned as a systems integrator with EV‑platform laser‑welded solutions. Expect Magna to compete on modular, highly manufacturable FEMs that support platform commonality. For OEMs, Magna offers scale and integration capability.
-
Valeo — strong in lighting‑integrated and ADAS‑ready modules. Valeo’s advantage is combining optics and sensor mounts into cohesive façade systems; ideal partners for OEMs prioritizing signature lighting and sensor performance.
-
HBPO — specialist in complex plastic composite modules and active shutters. HBPO is a go‑to for manufacturers seeking sophisticated polymer front ends with integrated aero features.
-
Hyundai Mobis — offers EV‑specific modules with thermal and structural integration. Their capabilities suit OEMs focused on tightly integrated EV subsystems and regional platform strategies in Asia.
-
Denso — leader in thermal management with full‑module assemblies for passenger vehicles. Denso’s depth in heat‑path engineering is a differentiator where thermal performance is mission‑critical.
-
Plastic Omnium — expert in large‑format injection carriers and fascia systems; best suited for OEMs seeking cost‑efficient polymer structural carriers at high volumes.
-
SL Corporation and Marelli (formerly Calsonic Kansei) — competing on lighting/structure and thermal/electronics integration respectively; both provide specialist niches that can be combined with larger Tier‑1s for complex builds.
Market structure is characterized by a handful of global integrators commanding substantial share, complemented by specialists that win adjacency niches (materials, active aero, sensor platforms). That mix yields strategic choices: consolidate with a primary global partner, or maintain multi‑sourcing to secure capability and mitigate supplier concentration risk.
How to use this report operationally (what’s inside)
-
Executive dashboard: base‑year metrics (2025), historical growth (2020–2025) and 2026–2032 scenario outputs under three demand pathways.
-
Technology roadmaps: maturity matrices for thermal integration, sensor mounting, materials and production technologies (laser welding, LFT, fiber placement).
-
Supplier playbooks: capability heatmaps, supplier scorecards, negotiation levers and co‑development templates tailored to OEM vs. Tier‑1 strategies.
-
Cost and margin model: component‑level cost curves, sensitivity to material substitutions and assembly automation choices.
-
Regulatory and LCA toolkit: checklist for ISO 14040 compliance, recommended recycled content pathways and certification timelines aligned to Euro NCAP 2026 protocols.
-
M&A and J/V screening: prioritized target list and valuation heuristics for capability buys (thermal, sensor platforms, high‑volume polymer pressing).
-
Implementation checklists: seven‑step action plans for engineering, procurement, manufacturing and aftersales readiness.
Five succinct recommendations for 2026 planning cycles
-
Set thermal integration as a gating criterion for FEM supplier selection on EV programs. Thermal shortcomings are costly to remediate late in development.
-
Mandate sensor mount standards and serviceability targets in early FEM specifications—design for field calibration and repair to reduce warranty exposure.
-
Adopt a materials transition plan that sequences LFT/composite adoption, while maintaining steel or hybrid backbones where crash budgets require it; build dual‑sourcing for key materials.
-
Negotiate IP‑sharing/co‑development clauses with Tier‑1s to protect future monetization rights (lighting signatures, aero solutions, sensor housings).
-
Run scenario planning anchored to the PW central forecast (6.1% CAGR) but stress‑test +/- 300–500 bps to evaluate capex phasing, supplier capacity and inventory policies.
Next steps — using PW Consulting as an operational partner
For teams preparing supplier RFPs, platform business cases, or M&A due diligence in 2026, PW Consulting’s full Automotive Front End Module Market report contains the granular segmentation, regional models, and supplier scorecards required to execute rapidly. This introduction lays out the strategic frame—download the full report to access the detailed tables, regional breakdowns, and the supplier capability matrix that we deliberately reserve for subscribers and clients.
In an industry where the front end is now a systems battleground for safety, efficiency and brand expression, the choices you make this year will determine vehicle performance and margin capture across the next product generation. PW Consulting’s analysis gives you the roadmap to make those calls with confidence.
For detailed analysis of this topic, please visit the official page: Automotive Front End Module Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Pet Food Packaging Market to Reach USD 18.0 Billion by 2032 (5.7% CAGR)
By pmarketresearch, 2026-07-30
Pet Food Packaging Market 2026: Strategic Preview for Executive Decision-Making
Between 2020 and 2025 the pet food packaging market expanded materially, moving from a mid‑single‑digit billion-dollar base to a significantly larger industry by the 2025 base year. Our analysis forecasts continued expansion through the 2026–2032 horizon, with the market tracking a steady compounded annual growth rate (CAGR) of 5.7% and approaching the high‑teens billion‑dollar mark by 2032. For leadership teams planning capital allocation, product redesigns, or market entry in 2026, these headline dynamics create both opportunity and urgency.
Pet Food Packaging Market
Why this report matters for 2026 strategy cycles
- Timing of regulatory inflection points: New packaging regulations and expanding producer responsibility schemes in key markets mean compliance-driven redesigns and EPR cost exposures will crystallize in 2026–2027. Decisions made this year on material choices, recyclability pathways, and supplier contracts will lock in fee and waste-management outcomes for the next decade.
- Capitalizing on predictable growth: With a multi‑year growth trajectory and clear category tailwinds (premiumisation, convenience formats, and e‑commerce demand), firms that prioritize scalable, recyclable formats will capture disproportionate share without depending solely on price competition.
- Margin preservation under input volatility: Raw material price drivers—resins, paper, metal—continue to create margin variability. The right combination of design‑to‑cost, supplier hedging, and recycled-content sourcing is now a strategic must, not just an operational improvement.
- Competitive positioning vs. concentration: The market displays moderate concentration (CR3 ~37%; CR5 ~47%), indicating significant room for differentiated plays by regional specialists, sustainable innovators, and format disruptors.
What the full PW Consulting report provides (practical, decision‑ready content)
- Robust market model: Annual market sizing from 2020 through 2025, plus a granular forecast for 2026–2032 under base, upside, and downside scenarios—built to be plugged into your financial models.
- Actionable segmentation framework: Demand breakdowns by material families, packaging formats, and pet food types—framed to guide SKU rationalisation and capex planning (note: this preview omits detailed split figures; the full dataset is included in the report).
- Value‑chain cost maps: Line‑by‑line input cost drivers, transport and conversion margins, and sensitivity tables to quantify margin impact from raw material swings and recyclate price movement.
- Regulatory impact assessment: Scenario analyses of EU and US EPR timelines, expected eco‑modulation effects on producer fees, and compliance roadmaps for global and regional product portfolios.
- Supplier and capability matrix: A pragmatic vendor scorecard—technical, sustainability credentials, geographic coverage, and scale—that supports rapid shortlist creation for RFPs and strategic partnerships.
- Commercial playbooks: Go‑to‑market strategies for brand owners, private label operators, and converters focused on premiumisation, convenience (reclosability, spouts), and e‑commerce protection requirements.
- M&A and partnership diagnostics: Target archetypes, valuation multiples observed in adjacent packaging segments, and regulatory due diligence checklists that reflect the evolving circularity landscape.
- Implementation templates: Roadmaps for packaging trials, conversion timelines, cost‑benefit templates for mono‑material conversions, and a 12–24 month action plan to operationalise recyclable formats.
Competitive landscape — who matters and why
The pet food packaging ecosystem is served by a mix of global converters, regional specialists, and metal can manufacturers. The competitive set includes leaders that combine scale with innovation in recyclable, mono‑material and high‑barrier solutions. Key players profiled in the report include:
Pet Food Packaging Market
- Amcor plc (Zurich): A global supplier focusing on recycle‑ready flexible portfolios designed for wet and dry pet food. Amcor’s investments in heat‑seal and barrier technologies mean brand owners can target recyclability without sacrificing shelf life—important for premium wet formats.
- Huhtamaki Oyj (Espoo): Known for mono‑material and alu‑free solutions, Huhtamaki’s blueloop concept and retort pouch capabilities make it a strategic partner for customers wanting to reduce composite materials while preserving convenience attributes.
- UFlex Limited (New Delhi): A fast‑moving manufacturer offering a broad array of recyclable flexible formats. Recent trade show activity demonstrates a drive to capture demand from emerging markets and private label operators seeking cost‑effective, recyclable alternatives.
- Mondi plc (Vienna): Strong in sustainable mono‑material solutions for dry pet food. Recent product launches with brand partners signal that paper‑based and mono‑plastic replacements are commercially viable at scale where barrier performance is managed through design.
- Silgan Holdings Inc. (Norwalk): A leading metal container producer, Silgan is positioned to serve wet food and specialty segments where shelf stability, dosing, and perceived premiumity justify rigid formats and dispensing closures.
Recent company moves underscore strategic themes: product launches and trade show demonstrations illustrate an industry pivot toward recyclable mono‑materials and format diversity. These developments are not isolated PR— they reflect investment decisions that will shape supplier roadmaps and cost structures through 2028 and beyond.
Pet Food Packaging Market
Regulatory and raw‑material drivers shaping 2026 decisions
- European PPWR: With the Packaging and Packaging Waste Regulation entering into force and recyclability targets becoming binding by 2030, European market participants must accelerate redesigns and prepare for eco‑modulated EPR fees. This creates a near‑term window (2026–2028) for phased portfolio migration and supplier requalification.
- US packaging EPR expansion: Multiple US states have passed comprehensive EPR laws and others are considering bills. Producer responsibilities in these states are already changing packaging economics and will drive demand for recycled content and mono‑material approaches.
- Input commodity volatility: Paper, metal and various plastic resins remain principal cost determinants. The report’s sensitivity scenarios quantify how price shocks translate to pack‑level margin erosion and when to hedge versus redesign.
Strategic imperatives for leadership in 2026
- Prioritise portfolio triage: Identify SKUs where recyclability upgrades deliver the greatest EPR and brand value lift, and where rigid formats versus flexible alternatives change total system cost.
- Design for recyclability, not merely substitution: Focus on mono‑material engineering, compatible inks and adhesives, and barrier innovations that reduce EPR exposure without compromising shelf life or food safety.
- Lock in supply chain partnerships now: Early agreements with converters and resin suppliers for recycled content and collection credits will be a competitive barrier as demand for certified recyclate intensifies.
- Test at scale, then industrialise: Move beyond lab prototypes—use controlled rollouts and retailer pilots to validate consumer acceptance, machinability on existing fill lines, and reverse‑logistics implications.
- Embed regulatory scenario planning in pricing: Use the report’s fee‑modelling templates to stress‑test price realignment and promotional strategies under different EPR outcomes.
- Assess M&A and JV opportunities: Target converters with mono‑material IP or regional collection ecosystems that accelerate time‑to‑market for recyclable formats.
How to use this intelligence in your 2026 planning cadence
For C‑suite and category leaders, the report functions as both a market compass and an execution playbook. Use it to:
- Calibrate three‑year capex plans for packaging equipment and conversion tooling.
- Develop supplier scorecards and RFP templates that quantify recyclability and EPR impact.
- Build pricing and promotional scenarios that reflect both material cost trajectories and evolving regulatory fees.
- Prioritise SKU rationalisation to reduce SKUs that are high‑cost to convert to compliant formats.
Next steps — converting insight into advantage
2026 will be a turning point where regulatory, commercial and material forces converge. The PW Consulting Pet Food Packaging Market report is structured to move your team from awareness to action: it supplies the market model, supplier intelligence, regulatory scenarios, and playbooks required to make defensible investment and sourcing decisions in 2026.
Executives preparing budget proposals, capex cases, or M&A memos will find the detailed datasets, supplier scorecards and implementation templates indispensable. This preview intentionally omits detailed segmentation tables and certain proprietary split figures; those are included in the full report and critical for pinpointing SKU‑level decisions.
For leadership teams that must balance sustainability commitments with margin preservation, our core recommendation is straightforward: treat packaging transformation as a portfolio of initiatives—regulatory compliance, consumer value, and cost optimisation—each requiring dedicated metrics, vendor commitments, and staged implementation. The right decisions this year will not only reduce regulatory risk but will create durable differentiation in a market growing steadily toward the late‑decade opportunity set.
For detailed analysis of this topic, please visit the official page: Pet Food Packaging Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com