

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Automotive Front End Module Market to Reach USD 222.5M by 2032 (6.1% CAGR)

Automotive Front End Module Market: Strategic Imperatives for 2026 Decision‑Makers
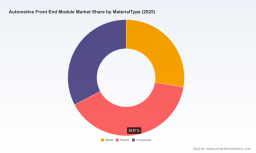
As OEMs accelerate electrification, advanced safety systems and life‑cycle transparency, the front end module (FEM) has evolved from a parts bundle into a strategic vehicle subsystem. PW Consulting’s latest market model (base year 2025) places the global FEM market at USD 147.1 Million, rising from USD 108.5 Million in 2020. Under our central scenario the market grows at a 6.1% CAGR across the 2026–2032 forecast window, reaching roughly USD 222.5 Million by 2032. For executives planning 2026 decisions, that trajectory changes how product architecture, supply‑chain strategy and capital allocation should be prioritized.
Automotive Front End Module Market
Why this research matters in 2026
-
Time‑sensitive integration. FEMs are now convergence zones for thermal management, ADAS sensors, and aerodynamic systems in EVs. Decisions taken in 2026 about platform architectures and supplier partnerships will lock in performance and cost outcomes for a multi‑year horizon.
Automotive Front End Module Market -
Regulatory and reputational risk. New life‑cycle reporting requirements and tightened safety testing protocols increase the technical and compliance burden on FEM designs; early alignment reduces rework and certification delays.
Automotive Front End Module Market -
Value capture changes. The FEM’s role in vehicle differentiation—lighting, active aero, sensor mounting, and thermal pathways—creates new opportunities for OEM differentiation or supplier monetization via platform licensing and co‑engineering.
High‑level market dynamics shaping 2026 choices
-
Electrification and thermal integration: EV architectures require FEMs that integrate battery and power‑electronics cooling pathways. Expect prioritized spend on thermal‑capable FEM variants and consolidated thermal/electrical architectures.
-
ADAS and sensor convergence: Safety protocols now mandate higher levels of integration for cameras, radars and lidars. FEMs that deliver robust, serviceable sensor platforms without aerodynamic penalty will command a premium.
-
Lightweight materials and LCA pressure: Material innovation—long‑fiber thermoplastics, laser‑welded assemblies, fiber‑placed composites and recycled metal/bio‑resins—are being adopted to meet mass reduction and life‑cycle constraints.
-
Modularization vs. unique differentiation: OEMs face a trade‑off between cost‑efficient standardized FEM platforms and bespoke modules that enable distinct vehicle identity (lighting signatures, active grilles, integrated sensors).
-
Supply resilience and concentration: While several global Tier‑1s dominate platform supply, niche specialists are capturing value in new material and sensor integration capabilities—creating a mixed landscape of consolidation and specialization.
Technology and materials trajectory — what 2026 buyers should prioritize
-
Thermal/structural co‑design: Recent supplier advances (early‑2026 product moves) demonstrate integrated thermal paths in FEMs that cool batteries and power electronics while preserving crash performance. Buyers should require thermal validation data earlier in design cycles.
-
Sensor‑first FEM architectures: With Euro NCAP and related protocols pushing AEB and lane support mandates, FEMs must be designed as primary sensor hosts. Sensor calibration, maintainability and electromagnetic compatibility (EMC) must be specified up front.
-
Material plurality: Laser‑welded steel subframes remain cost‑effective for some platforms, but LFT‑based and fiber‑placed composite solutions are proving lighter and more assembly‑friendly for C‑segment and SUV applications. Procurement teams must build dual‑material sourcing roadmaps to respond to regional material availability and LCA targets.
-
Active aero and integrated lighting: The combination of aerodynamic shutters, lighting modules and grille surfaces is converging into unified façade systems—creating opportunities for integrated suppliers but raising complexity for service networks.
Competitive landscape: profiles and implications
The FEM market is populated by a mix of diversified Tier‑1 systems integrators and specialist product houses. Strategic implications for OEMs and suppliers are summarized below; the full competitive scorecards and supplier capability maps are detailed in the full report.
-
Magna International — positioned as a systems integrator with EV‑platform laser‑welded solutions. Expect Magna to compete on modular, highly manufacturable FEMs that support platform commonality. For OEMs, Magna offers scale and integration capability.
-
Valeo — strong in lighting‑integrated and ADAS‑ready modules. Valeo’s advantage is combining optics and sensor mounts into cohesive façade systems; ideal partners for OEMs prioritizing signature lighting and sensor performance.
-
HBPO — specialist in complex plastic composite modules and active shutters. HBPO is a go‑to for manufacturers seeking sophisticated polymer front ends with integrated aero features.
-
Hyundai Mobis — offers EV‑specific modules with thermal and structural integration. Their capabilities suit OEMs focused on tightly integrated EV subsystems and regional platform strategies in Asia.
-
Denso — leader in thermal management with full‑module assemblies for passenger vehicles. Denso’s depth in heat‑path engineering is a differentiator where thermal performance is mission‑critical.
-
Plastic Omnium — expert in large‑format injection carriers and fascia systems; best suited for OEMs seeking cost‑efficient polymer structural carriers at high volumes.
-
SL Corporation and Marelli (formerly Calsonic Kansei) — competing on lighting/structure and thermal/electronics integration respectively; both provide specialist niches that can be combined with larger Tier‑1s for complex builds.
Market structure is characterized by a handful of global integrators commanding substantial share, complemented by specialists that win adjacency niches (materials, active aero, sensor platforms). That mix yields strategic choices: consolidate with a primary global partner, or maintain multi‑sourcing to secure capability and mitigate supplier concentration risk.
How to use this report operationally (what’s inside)
-
Executive dashboard: base‑year metrics (2025), historical growth (2020–2025) and 2026–2032 scenario outputs under three demand pathways.
-
Technology roadmaps: maturity matrices for thermal integration, sensor mounting, materials and production technologies (laser welding, LFT, fiber placement).
-
Supplier playbooks: capability heatmaps, supplier scorecards, negotiation levers and co‑development templates tailored to OEM vs. Tier‑1 strategies.
-
Cost and margin model: component‑level cost curves, sensitivity to material substitutions and assembly automation choices.
-
Regulatory and LCA toolkit: checklist for ISO 14040 compliance, recommended recycled content pathways and certification timelines aligned to Euro NCAP 2026 protocols.
-
M&A and J/V screening: prioritized target list and valuation heuristics for capability buys (thermal, sensor platforms, high‑volume polymer pressing).
-
Implementation checklists: seven‑step action plans for engineering, procurement, manufacturing and aftersales readiness.
Five succinct recommendations for 2026 planning cycles
-
Set thermal integration as a gating criterion for FEM supplier selection on EV programs. Thermal shortcomings are costly to remediate late in development.
-
Mandate sensor mount standards and serviceability targets in early FEM specifications—design for field calibration and repair to reduce warranty exposure.
-
Adopt a materials transition plan that sequences LFT/composite adoption, while maintaining steel or hybrid backbones where crash budgets require it; build dual‑sourcing for key materials.
-
Negotiate IP‑sharing/co‑development clauses with Tier‑1s to protect future monetization rights (lighting signatures, aero solutions, sensor housings).
-
Run scenario planning anchored to the PW central forecast (6.1% CAGR) but stress‑test +/- 300–500 bps to evaluate capex phasing, supplier capacity and inventory policies.
Next steps — using PW Consulting as an operational partner
For teams preparing supplier RFPs, platform business cases, or M&A due diligence in 2026, PW Consulting’s full Automotive Front End Module Market report contains the granular segmentation, regional models, and supplier scorecards required to execute rapidly. This introduction lays out the strategic frame—download the full report to access the detailed tables, regional breakdowns, and the supplier capability matrix that we deliberately reserve for subscribers and clients.
In an industry where the front end is now a systems battleground for safety, efficiency and brand expression, the choices you make this year will determine vehicle performance and margin capture across the next product generation. PW Consulting’s analysis gives you the roadmap to make those calls with confidence.
For detailed analysis of this topic, please visit the official page: Automotive Front End Module Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com